
 Cosmetic Surgery and Procedure Market | 2026-2036
Cosmetic Surgery and Procedure Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Surgery and Procedure Market Intelligence
The Cosmetic Surgery and Procedure Market is recalibrating around a widening split between premium concierge practices and commoditized chain clinics. AbbVie Inc. leverages its Allergan Aesthetics portfolio to dominate the injectable neurotoxin segment through captive supply of botulinum toxin formulations. Johnson & Johnson sustains competitive positioning in breast implants and facial reconstruction through its Mentor subsidiary's manufacturing scale and surgeon training networks. Galderma differentiates via integrated dermatology-aesthetics platforms spanning prescription skincare and hyaluronic acid fillers.
Cosmetic surgery and procedure encompasses surgical alteration and non-invasive enhancement of physical appearance using implantable devices, energy-based systems, and injectable biologics, with specifications including laser wavelengths tunable between 532 nm and 10,600 nm for tissue ablation and radiofrequency depths reaching 4.5 mm for dermal remodeling. Its primary commercial purpose centers on elective aesthetic improvement and reconstructive correction performed in licensed medical facilities. Injectable fillers and non-surgical treatments represent the fastest-expanding margin pools as patients prioritize downtime reduction over permanent surgical outcomes. Breast augmentation and liposuction remain mature revenue anchors within surgical procedures, while ultrasound-based technologies capture growing share in body contouring applications.
FDA clearance pathways for Class II and III aesthetic devices, CE marking under the EU MDR, and ISO 13485 quality management standards collectively govern product commercialization and clinical trial requirements across major markets. These frameworks shape demand by restricting market access to compliant manufacturers and mandating post-market surveillance for adverse event reporting. Stakeholders must monitor evolving reimbursement policies for reconstructive indications and shifting liability standards for off-label aesthetic applications.
Market Dynamics
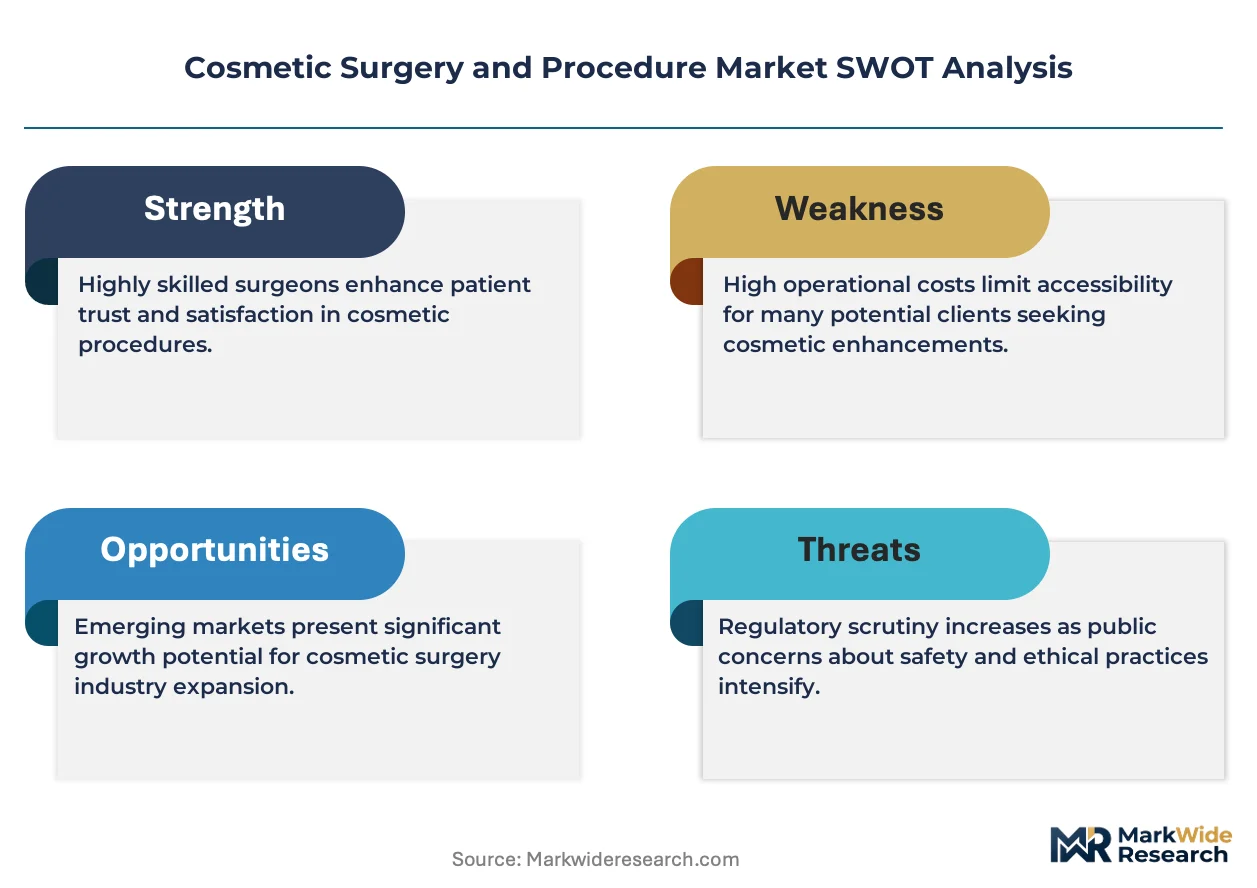
Energy-based devices and biologics are forcing a bifurcation between premium concierge practices and high-volume chain clinics, with FDA and CE marking compliance costs concentrating manufacturing among scaled players.
Growth Catalysts
- MFDS fast-track pathways:South Korea's medical device regulator accelerates approvals for laser and ultrasound systems, channeling patient flows toward Seoul's specialized aesthetic centers.
- Hyaluronic acid filler platforms:Integrated dermatology-aesthetics systems spanning prescription skincare and injectables capture margin pools as patients prioritize downtime reduction.
- Ambulatory surgical center migration:Licensed outpatient facilities in Brazil and Thailand expand capacity for minimally invasive facial rejuvenation protocols.
Market Restraints
- Biologics supply concentration:Botulinum toxin manufacturing clusters in Ireland and Switzerland create single-source vulnerability for neurotoxin-dependent practices.
- EU MDR transition friction:CE marking recertification under the 2017 Medical Device Regulation extends timelines for energy-based device commercialization.
- Radiofrequency depth limitations:Current 4.5 mm maximum penetration restricts dermal remodeling efficacy for patients with advanced skin laxity.
Strategic Opportunities
- India's underserved tier-2 cities:Mumbai, Bangalore, and Hyderabad exhibit rising disposable income without proportional aesthetic clinic penetration.
- AI-guided treatment planning:Machine learning algorithms converging with 3D imaging systems enable personalized injection mapping and outcome prediction.
- Telemedicine pre-consultation channels:Virtual assessment platforms reduce patient acquisition costs and expand geographic reach beyond metropolitan catchments.
Industry Challenges
- Surgeon training pipeline gaps:Fellowship programs in aesthetic medicine fail to match demand for practitioners credentialed in ultrasound-based body contouring.
- ISO 13485 certification timelines:Quality management system audits for new device manufacturers extend 14-18 months, delaying market entry.
- Cross-border liability complexity:Medical tourism patients pursuing revision procedures in home jurisdictions create malpractice coverage disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Surgery and Procedure Market |
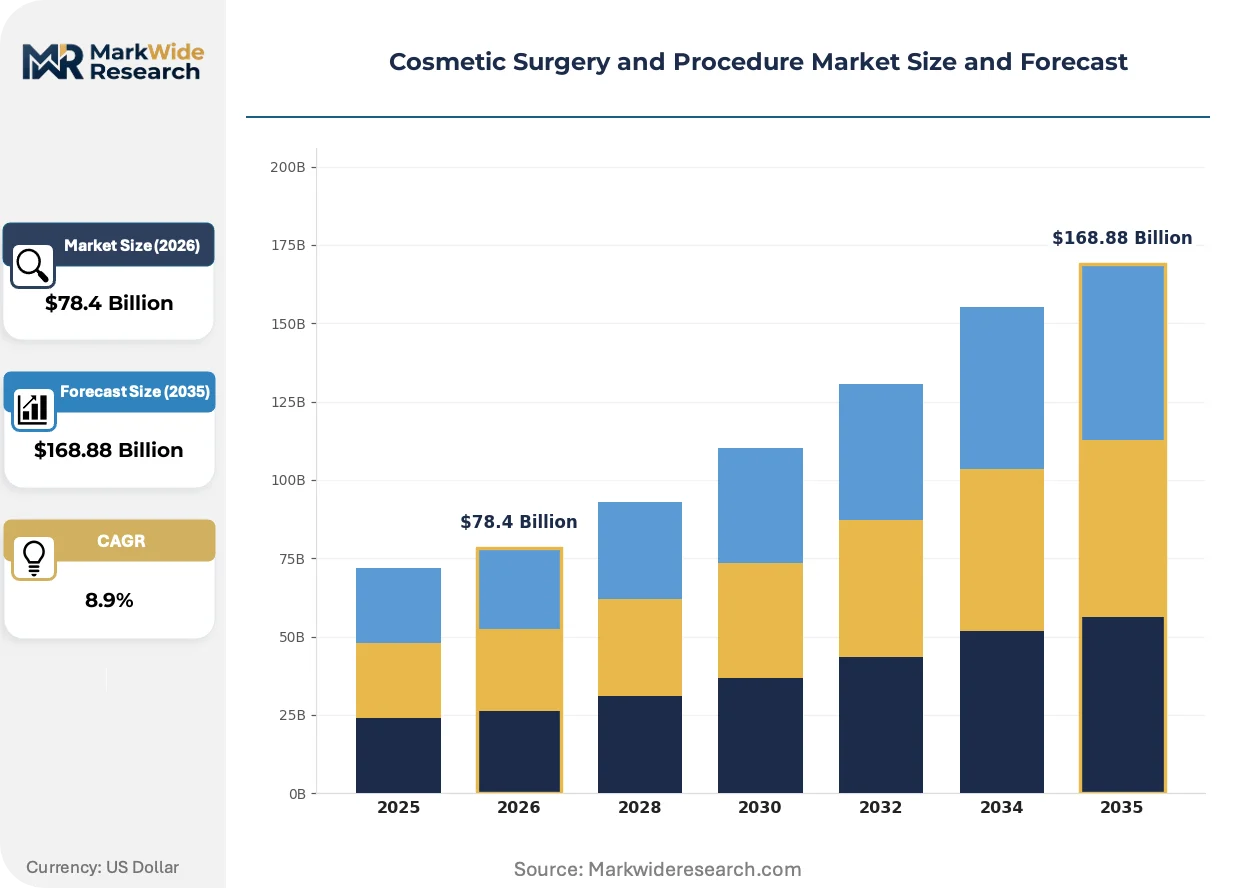
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $168.88 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Rhinoplasty, Liposuction, Facelift Technology: Laser Surgery, Injectable Fillers, Radiofrequency, Ultrasound End User: Clinics, Hospitals, Private Practices, Ambulatory Surgical Centers Service Type: Consultation, Surgical Procedures, Non-Surgical Treatments, Aftercare |
| Companies Covered | AbbVie Inc., Bausch Health Companies Inc., Johnson & Johnson, Galderma, Cynosure, Merz Pharma, Lumenis, Solta Medical, Evolus Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Surgery and Procedure Market Strategic Shifts & Innovations
Injectable platforms and energy-based systems are compressing the recovery window for aesthetic procedures, reshaping competitive positioning around convenience and repeat-visit frequency rather than surgical permanence.
High-intensity focused ultrasound systems operate at depths up to 4.5 mm for non-surgical skin lifting and fat reduction. Ambulatory surgical centers in Seoul and São Paulo adopt these platforms at accelerating pace to differentiate from traditional liposuction offerings. This modality is expanding into body contouring applications previously dominated by surgical intervention, compressing margins for invasive fat removal procedures.
The EU Medical Device Regulation's 2021 implementation elevates clinical evidence requirements for Class IIa and IIb aesthetic devices. Manufacturers face expanded post-market surveillance obligations and notified body capacity constraints. Breast implant and laser device categories experience the most pronounced compliance cost inflation, with smaller European players exiting or consolidating.
Subscription-based maintenance programs for neurotoxin and filler regimens displace episodic treatment purchasing in affluent urban markets. Direct-to-patient membership models in Los Angeles, London, and Dubai lock in recurring revenue and reduce patient churn. South Korea's clinic chains pioneer this shift, with bundled annual protocols now capturing preference among patients under 40.
Cosmetic Surgery and Procedure Market Segmentation
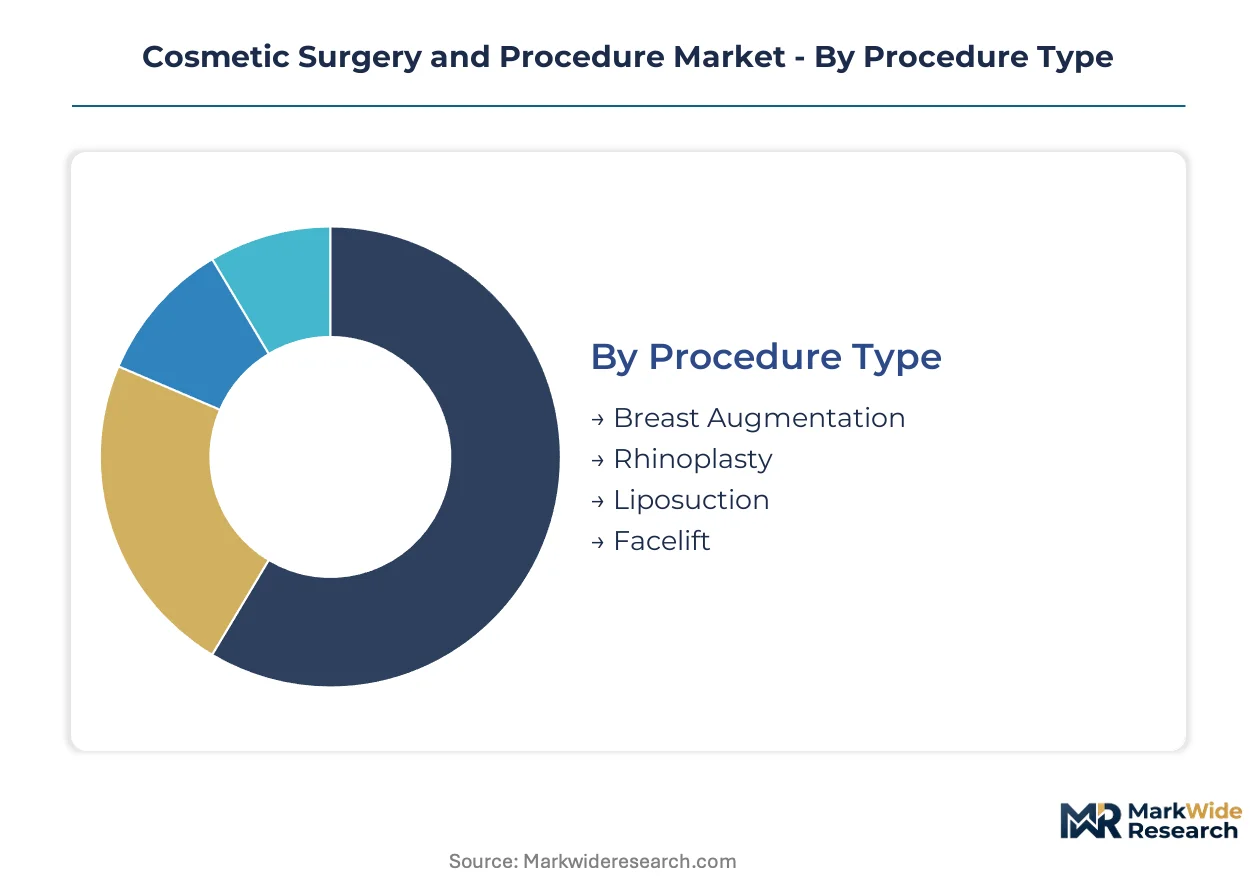
Segmentation in cosmetic surgery reveals how patient priorities split between permanent surgical outcomes and convenience-driven non-invasive protocols. Technology choice and facility type increasingly determine margin capture and repeat-visit economics for providers.
Procedure Type:
Patient risk tolerance and recovery capacity differentiate buyers across surgical categories.
- Breast Augmentation:Silicone and saline implants with textured or smooth shell surfaces address volume restoration and aesthetic proportioning. Demand concentrates in licensed surgical centers across Brazil and South Korea where surgeon training density supports complex revision work.
- Rhinoplasty:Open and closed surgical techniques reshape nasal bone and cartilage structures for functional and cosmetic correction. High-volume practices in Tehran and Istanbul attract medical tourism flows seeking ethnic preservation techniques combined with airway improvement.
- Liposuction:Suction-assisted and ultrasound-assisted fat removal targets localized adipose deposits.
- Facelift:SMAS plication and deep plane techniques address midface descent and jowl formation.
Volume sits with Breast Augmentation; growth tilts toward Rhinoplasty.
Technology:
Capital intensity and consumable economics separate technology choices for facility operators.
- Injectable Fillers:Hyaluronic acid and calcium hydroxylapatite formulations restore facial volume and smooth rhytides through minimally invasive injection. Private practices in Los Angeles and London capture repeat-visit revenue through subscription-based maintenance protocols.
- Laser Surgery:Ablative and non-ablative wavelengths from 532 nm to 10,600 nm target pigmentation, vascular lesions, and tissue resurfacing. Seoul's aesthetic chains deploy fractional CO2 systems to differentiate from commoditized IPL offerings.
- Radiofrequency:Monopolar and bipolar energy delivery systems heat dermal collagen to 65°C for tissue tightening.
- Ultrasound:High-intensity focused ultrasound generates thermal coagulation points at depths up to 4.5 mm.
Capital deployment favors Laser Surgery; patient preference is shifting fastest toward Injectable Fillers.
End User:
Regulatory burden and reimbursement access shape facility selection for procedure delivery.
- Ambulatory Surgical Centers:Licensed outpatient facilities with anesthesia capabilities and emergency protocols perform complex procedures without hospital admission. Thailand and Brazil expand ASC capacity for facial rejuvenation protocols that displace traditional hospital-based surgery.
- Private Practices:Physician-owned clinics with direct patient relationships control scheduling and pricing for elective aesthetic services. Dubai and Mumbai practices build telemedicine pre-consultation channels to reduce acquisition costs.
- Clinics:Multi-physician group practices with shared equipment pools.
- Hospitals:Acute care facilities with full surgical suites and overnight stay capacity.
Procedure volume concentrates in Private Practices; capacity expansion is accelerating fastest at Ambulatory Surgical Centers.
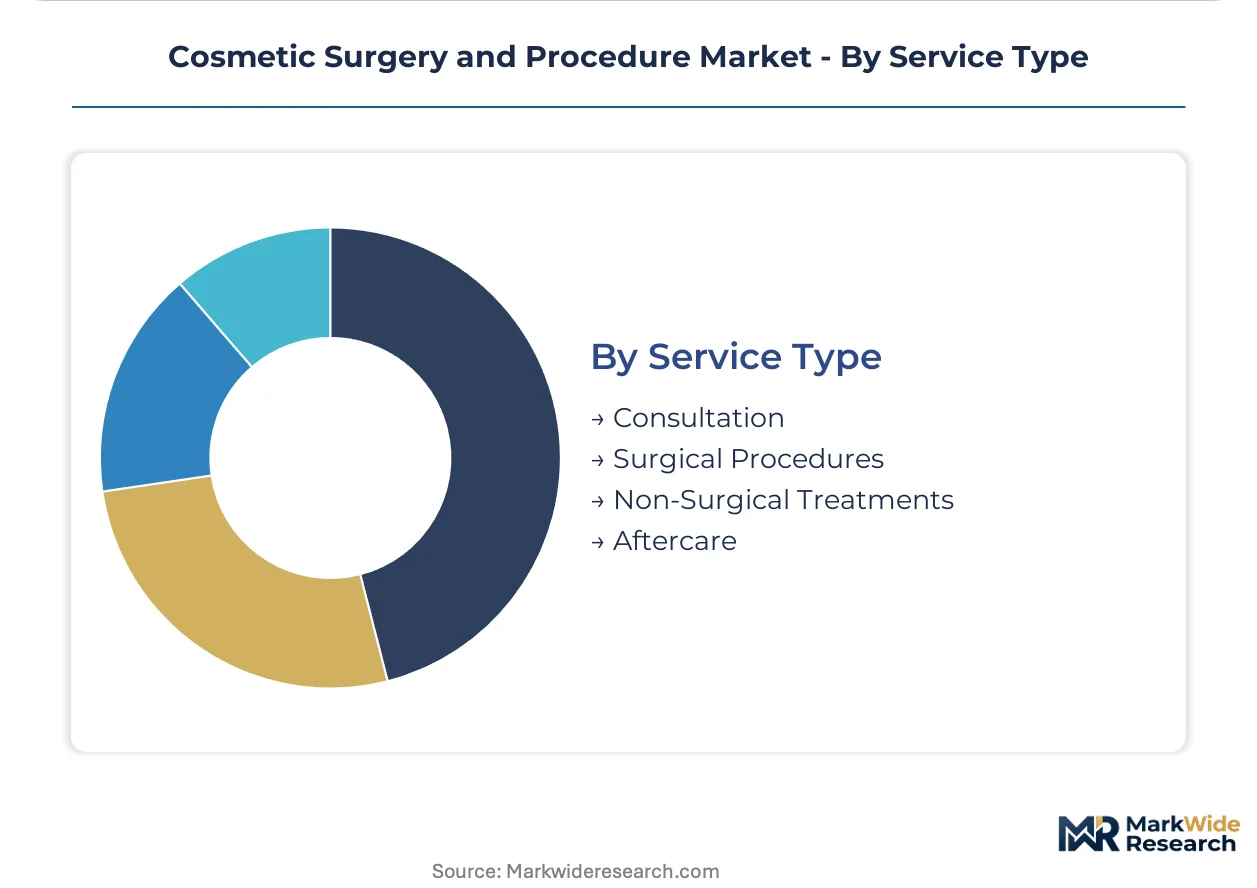
Service Type:
Revenue recurrence and margin structure differentiate service line economics.
- Non-Surgical Treatments:Energy-based procedures and injectable protocols delivered without anesthesia or facility fees. South Korean clinic chains bundle annual neurotoxin and filler regimens into membership models that lock in recurring revenue.
- Surgical Procedures:Operating room-based interventions requiring anesthesia support and post-operative monitoring. São Paulo and Mexico City surgical centers compete on package pricing for combined procedure protocols.
- Consultation:Pre-procedure assessment with imaging and treatment planning.
- Aftercare:Post-procedure follow-up, complication management, and revision planning.
Revenue stability rests with Non-Surgical Treatments; margin expansion is climbing the fastest at Surgical Procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district concentrates more aesthetic clinics per square kilometer than any comparable medical zone worldwide, channeling patient flows from across East Asia and beyond.
United States
Los Angeles and Miami drive demand for minimally invasive facial protocols and body contouring systems. FDA clearance pathways for Class II and III aesthetic devices mandate extensive clinical evidence, concentrating manufacturing scale among established players. Beverly Hills and Manhattan practices pioneer subscription-based neurotoxin membership models that lock in recurring patient revenue.
South Korea
Seoul's aesthetic chains capture medical tourism flows through bundled procedure packages and competitive pricing on HIFU-based skin tightening. MFDS fast-track pathways accelerate laser and ultrasound device approvals, reducing time-to-market for domestic manufacturers. Gangnam's specialized centers differentiate through ethnic preservation rhinoplasty techniques and rapid-recovery facial rejuvenation protocols.
Brazil
São Paulo and Rio de Janeiro anchor surgical volume for breast augmentation and liposuction, with ambulatory surgical centers expanding capacity for same-day discharge protocols. ANVISA registration requirements for implantable devices create compliance barriers for smaller international entrants. The country's surgeon training density supports complex revision work that attracts regional medical tourism from Latin America.
Germany
Munich and Frankfurt practices emphasize premium positioning through CE-marked energy-based devices and integrated dermatology-aesthetics platforms. EU MDR transition friction extends recertification timelines for laser and radiofrequency systems, elevating compliance costs. Baden-Württemberg's precision manufacturing base supplies optical components for aesthetic laser systems deployed across European markets.
United Arab Emirates
Dubai's private practices build telemedicine pre-consultation channels to reduce patient acquisition costs and capture regional demand from Saudi Arabia and Kuwait. MOHAP facility licensing requirements mandate international accreditation for aesthetic centers serving medical tourists. The city's clinic chains compete on package pricing for combined surgical and non-surgical protocols targeting visitors from South Asia and Africa.
Cosmetic Surgery and Procedure Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the aesthetic device and biologics landscape. The market structure concentrates manufacturing scale among diversified health conglomerates while fragmented specialty players occupy niche technology segments. Three archetypes dominate: integrated pharmaceutical-aesthetics platforms with captive biologics supply, pure-play energy-based device manufacturers with consumable revenue models, and multi-brand distributors with regional exclusivity arrangements. Competitive moves center on surgeon training network expansion and backward integration into raw material production.
Within the integrated platform tier, AbbVie Inc. and Johnson & Johnson exemplify the pharmaceutical conglomerate archetype, leveraging existing regulatory infrastructure and physician relationships to dominate injectable segments. Galderma occupies a distinct position bridging prescription dermatology and aesthetic medicine through combined skincare and filler portfolios. Among device specialists, Cynosure and Lumenis represent the capital-intensive technology developer archetype, with geographic identifiers in their names suggesting concentrated engineering and manufacturing footprints in specific metropolitan clusters.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Bausch Health Companies Inc. |
| Johnson & Johnson |
| Galderma |
| Cynosure |
| Merz Pharma |
| Lumenis |
| Solta Medical |
| Evolus Inc. |
| Others |
Cost & Logistics Intelligence
Botulinum toxin fermentation capacity in Ireland and Switzerland feeds into three-tier pricing structures across premium, standard, and economy levels, with FDA and CE marking tiers determining margin capture downstream. Hyaluronic acid raw material costs from Chinese and Japanese suppliers compress margins for mid-market filler brands while premium integrated platforms maintain pricing power through captive biologics supply.
Pricing Analysis
Outcome-based pricing anchors aesthetic procedure economics, with subscription membership models for neurotoxin regimens displacing per-unit transactional purchasing in Los Angeles, London, and Dubai. Price differentiation rests on FDA clearance tier and brand heritage, with AbbVie's Allergan portfolio commanding premium positioning over emerging Korean entrants. Pricing pressure intensifies in commoditized IPL and basic filler segments as chain clinics compete on package bundling. Medical tourism patients in Bangkok and Istanbul exhibit highest price sensitivity; concierge practices in Beverly Hills and Gangnam demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Seoul, São Paulo, and Mumbai operate hub-and-spoke patterns for energy-based devices, with final-mile delivery to ambulatory surgical centers and private practices. Manufacturing concentrates in South Korea for laser systems, Switzerland for neurotoxin bulk fermentation, and Germany for optical components. Raw material dependencies include hyaluronic acid from Japanese bacterial fermentation, rare-earth laser crystals from Chinese processors, and medical-grade silicone from US specialty chemical producers. Single-source vulnerability in Irish botulinum toxin API creates supply chain risk. Distribution runs through exclusive distributor networks with surgeon training obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-intensity focused ultrasound systems are displacing traditional liposuction volumes, compressing recovery windows from weeks to days and forcing capital redeployment across facility networks.
For Market Incumbents: Deploy backward integration into hyaluronic acid raw material production to defend margin position against Korean and Chinese filler entrants. Consolidate surgeon training networks around ultrasound-based body contouring credentials before fellowship pipeline gaps widen. Lock in ambulatory surgical center partnerships through equipment leasing programs that create switching costs. Energy-based device commoditization threatens pricing power; captive consumable revenue models offer defensive moats. For New Entrants and Emerging Players: AI-guided treatment planning algorithms offer technology-first entry into underserved Indian tier-2 cities where Mumbai, Bangalore, and Hyderabad lack proportional aesthetic clinic penetration. Target telemedicine pre-consultation channels to reduce patient acquisition costs below incumbent benchmarks. White-space exists in subscription-based maintenance programs for patients under 40 seeking bundled annual neurotoxin and filler regimens. Go-to-market through Dubai-based medical tourism facilitators accessing Saudi and Kuwaiti demand. For Investors and Strategic Acquirers: MFDS fast-track approval acceleration for domestic Korean manufacturers is the leading indicator that regulatory arbitrage opportunities are narrowing for Western device players. Long-term viability favors integrated pharmaceutical-aesthetics platforms with captive biologics supply over pure-play device manufacturers facing EU MDR compliance cost inflation. Acquisition target archetype: mid-cap energy-based device specialists with ISO 13485 certification and established notified body relationships. Watch for ANVISA registration bottlenecks in Brazil signaling regional consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification timelines favor scaled players with notified body capacity access. |
| Surgeon Training Network Expansion | Mentor and Allergan Aesthetics programs lock in practitioner loyalty before fellowship gaps widen. |
| Backward Integration into Biologics | Captive botulinum toxin fermentation insulates margin from Irish and Swiss supply concentration. |
| Subscription Membership Launch | Annual bundled protocols in Seoul and Los Angeles reduce patient churn and stabilize recurring revenue. |
| Telemedicine Pre-Consultation Channel | Virtual assessment platforms in Dubai and Mumbai cut acquisition costs for medical tourism flows. |
Research Approach
SEC filings, FDA 510(k) clearance databases, and EU MDR notified body registers formed the secondary backbone, supplemented by customs records for energy-based device trade flows. Primary interviews with aesthetic surgeons, ambulatory surgical center administrators, biomedical engineers, and GPO contracts managers validated demand assumptions and pricing dynamics. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Historical trendline analysis of procedure migration from hospital-based surgery to licensed outpatient facilities informed facility-type segmentation modeling. Segmentation dimensions included procedure type, technology platform, end-user facility category, and regional regulatory cluster. CAGRs derived from regression analysis of annual procedure volumes and manufacturer reported sales across the projection horizon. Industry-specific forecast inputs captured MFDS approval velocity and EU MDR transition friction effects on device commercialization timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt reimbursement policy shifts for reconstructive indications or biologics supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Spain Cosmetic Surgery Market
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
UK Cosmetic Surgery Market