
 Dental Implant Motors Market | 2026-2036
Dental Implant Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Implant Motors Market Analysis
Aftermarket service revenue is fragmenting across regional service networks as original equipment manufacturers lose exclusivity on calibration and torque-recertification work. Dentsply Sirona leverages its global dental platform footprint to capture recurring maintenance contracts. NSK anchors premium handpiece and motor replacement cycles through authorized dealer networks in East Asia. Straumann Group competes by bundling implant motors with surgical protocol training, deepening clinician lock-in beyond hardware sales.
Dental implant motors are electromechanical drive systems that deliver precisely controlled rotational torque, typically 20–80 Ncm, to surgical drills during osteotomy preparation and implant site development. These devices integrate brushless DC or pneumatic turbine architectures with real-time feedback sensors to prevent thermal necrosis of alveolar bone during high-speed drilling. Electric motors with brushless technology command the dominant margin pool due to superior torque stability and programmable speed profiles, while wireless technology represents the fastest-expanding configuration as cable-free surgical suites reduce cross-contamination protocols. Pneumatic motors retain share in cost-sensitive dental hospitals where capital budgets prioritize instrument durability over digital integration.
FDA 510(k) premarket notification requirements and EU MDR Class IIa certification obligations shape product development timelines and clinical evidence burdens for motor manufacturers seeking transatlantic market access. ISO 14457 specifications for dental handpieces extend to motor torque-validation protocols, creating compliance harmonization opportunities for multi-regional suppliers. Stakeholders must monitor how FDA software-as-medical-device guidance applies to motors with embedded surgical navigation algorithms, as this determination will reshape R&D allocation between hardware engineering and digital platform development.
Market Dynamics
Brushless DC motor architectures are displacing pneumatic systems as the dominant torque-delivery platform, compressing replacement cycles and forcing recalibration of service revenue models across dental device supply chains.
Growth Catalysts
- EU MDR Class IIa recertification:Accelerated clearance timelines for electric motor platforms with embedded torque sensors are pulling forward upgrade demand from European dental clinics seeking preemptive compliance.
- Surgical navigation convergence:Real-time osteotomy guidance systems require motor-integrated feedback loops, creating pull-through demand for programmable speed-profile hardware in academic medical centers.
- Stuttgart precision engineering cluster:Concentrated supplier networks for high-tolerance brushless stator assemblies reduce component lead times for motor manufacturers serving Central European implantology practices.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium price swings embedded in brushless rotor assemblies compress margin stability for mid-tier motor assemblers lacking long-term supply contracts.
- Single-source torque sensor dependency:German and Japanese suppliers dominate strain-gauge manufacturing for Ncm-precision feedback systems, creating geographic concentration risk in critical sensing subcomponents.
- Pneumatic infrastructure lock-in:Cost-sensitive dental hospitals in Eastern Europe and Southeast Asia retain compressed-air handpiece investments, delaying electric motor conversion despite superior torque stability.
Strategic Opportunities
- South Korean domestic production expansion:Osstem Implant and MegaGen are localizing brushless motor assembly, creating white-space for precision component suppliers to establish captive supply relationships with Seoul-area device manufacturers.
- Wireless surgical suite protocols:Cable-free motor configurations reduce cross-contamination risks, opening channel expansion into infection-control-focused ambulatory surgical centers in Germany and Switzerland.
- FDA software-as-medical-device guidance:Emerging clarity on embedded surgical navigation algorithms creates regulatory tailwind for motor manufacturers investing in digital platform engineering alongside hardware development.
Industry Challenges
- Torque-recertification technician scarcity:Authorized service networks lack sufficient trained personnel to handle brushless motor calibration at scale, creating bottlenecks in aftermarket revenue capture.
- ISO 14457 harmonization delays:Divergent national interpretations of handpiece-motor interface specifications complicate multi-regional product platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Implant Motors Market |
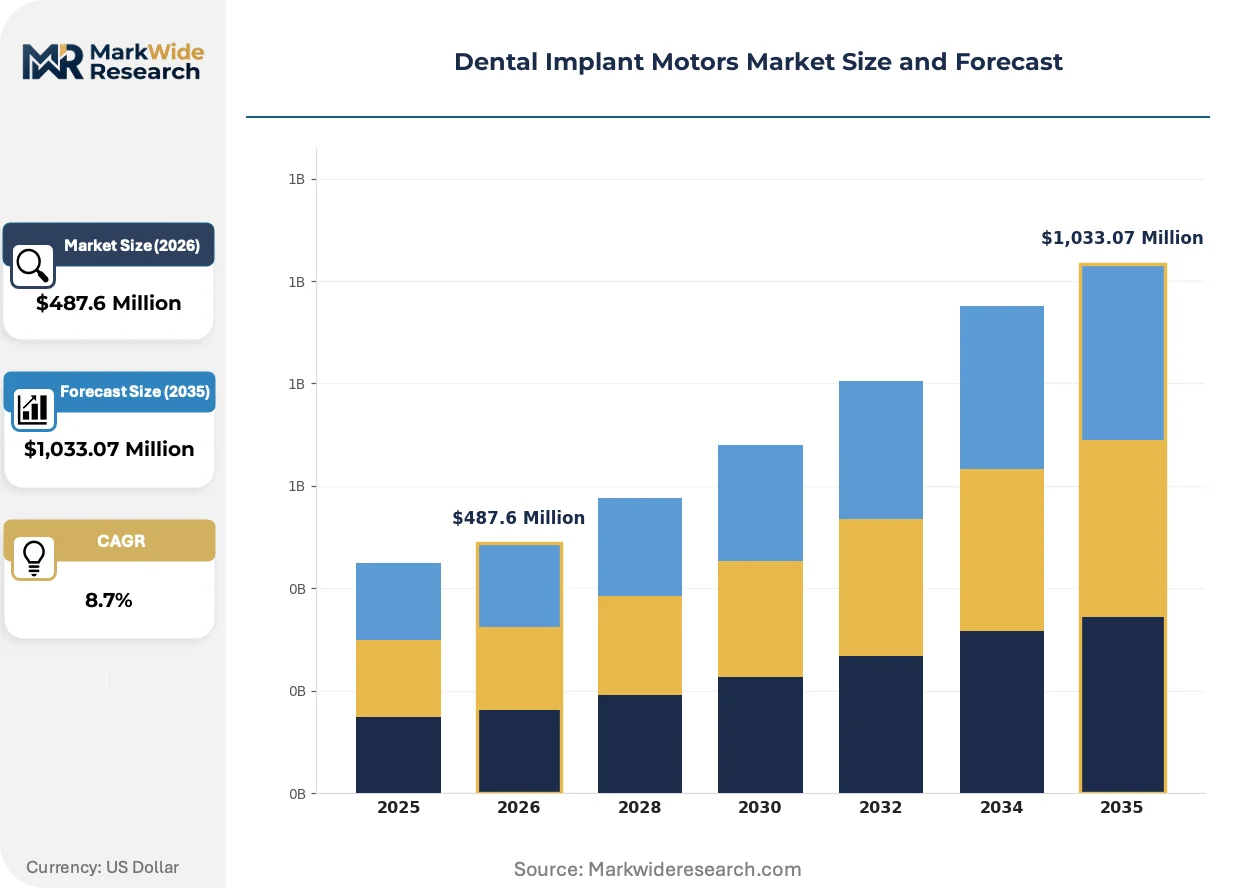
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Motors, Pneumatic Motors, Hybrid Motors, Ultrasonic Motors End User: Dentists, Dental Hospitals, Research Clinics, Dental Laboratories Technology: Brushless Technology, LED Technology, Wireless Technology, Digital Technology Application: Oral Surgery, Implant Surgery, Bone Surgery, Periodontal Surgery |
| Companies Covered | Dentsply Sirona, NSK, Aseptico, Saeshin, Straumann Group, Zimmer Biomet, Envista Holdings, Osstem Implant, MegaGen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Implant Motors Market Emerging Trajectories
Real-time feedback integration and wireless power transmission are restructuring how surgical torque is delivered, measured, and monetized across implantology workflows.
Embedded torque sensing with closed-loop thermal monitoring is digitizing osteotomy safety protocols. Academic medical centers in Germany and Switzerland are adopting these sensor-integrated motors fastest, compressing liability exposure for alveolar bone necrosis events while enabling procedure documentation for training accreditation.
EU MDR recertification timelines are compressing product launch windows for manufacturers seeking European market access. Device firms with legacy pneumatic portfolios face disproportionate evidence-generation burdens compared to electric platform specialists, accelerating portfolio rationalization toward brushless architectures ahead of 2025-2026 renewal peaks.
After-sales service unbundling is fragmenting maintenance revenue across regional calibration networks. Original equipment manufacturers are losing exclusivity on torque-recertification work to third-party biomedical technicians, particularly visible in North American dental service organizations consolidating procurement across multi-state clinic footprints.
Dental Implant Motors Market Segmentation
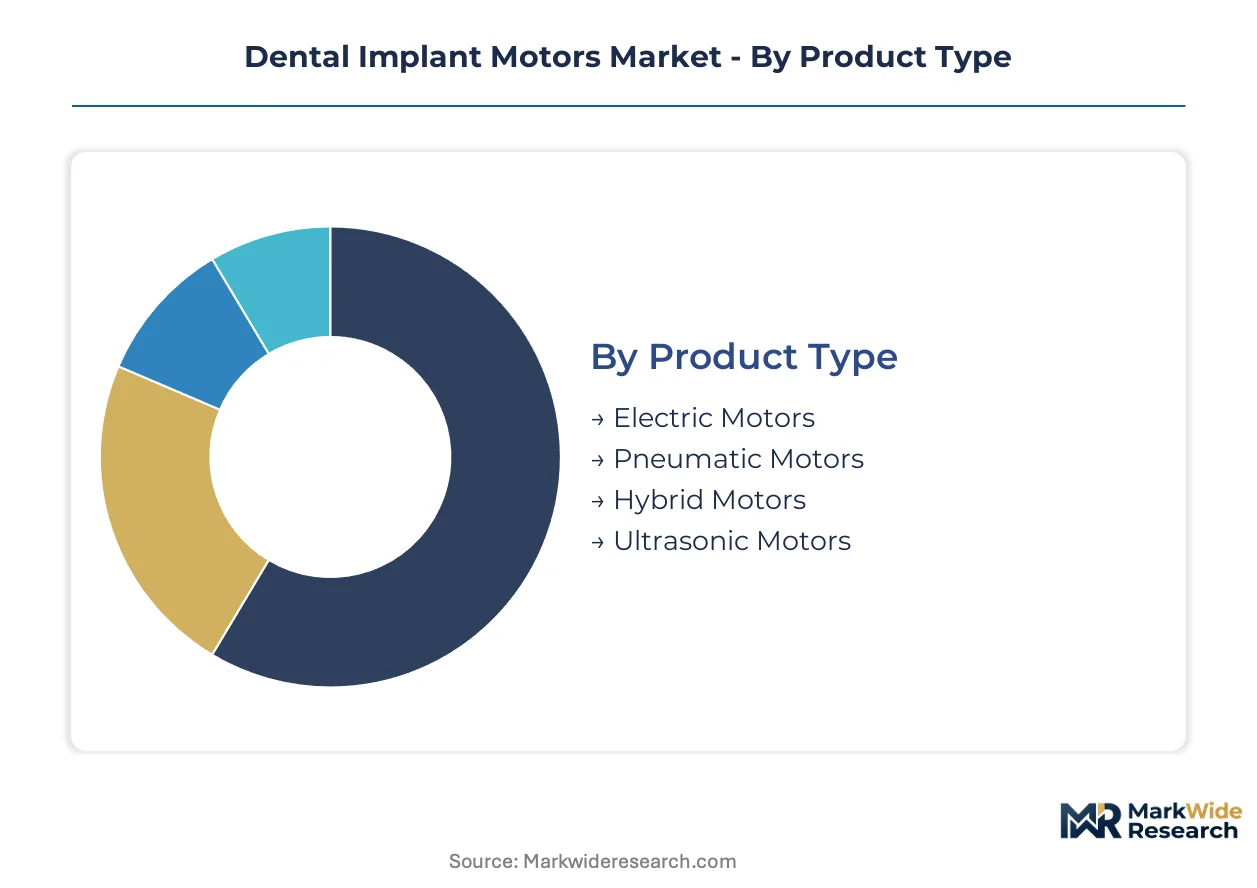
Segmentation in dental implant motors reveals how torque-delivery architectures, clinical settings, and digital integration layers create distinct procurement cycles and margin profiles across the value chain. Each dimension exposes different competitive dynamics, from hardware replacement frequency to software-enabled service revenue capture.
Product Type:
Electric motors turn over fastest at 4-6 year replacement cycles driven by brushless rotor wear and sensor recalibration needs, while pneumatic systems persist longest where compressed-air infrastructure delays capital conversion.
- Electric Motors:Brushless DC architectures dominate premium procurement with programmable torque profiles and real-time thermal feedback. Demand concentrates in Germany's Stuttgart-Munich device cluster where Straumann Group and Dentsply Sirona source high-tolerance stator assemblies for Central European implantology practices facing EU MDR recertification deadlines.
- Pneumatic Motors:Compressed-air turbine systems retain installed base in cost-sensitive Eastern European and Southeast Asian dental hospitals where capital budgets prioritize instrument durability over digital integration. Bulgarian and Vietnamese clinics delay electric conversion despite inferior torque stability, extending replacement cycles to 8-12 years.
- Hybrid Motors:Dual-mode electric-pneumatic configurations serve transitional clinics in Poland and Romania managing mixed handpiece fleets during infrastructure upgrade phases.
- Ultrasonic Motors:Piezoelectric torque systems command niche applications in Swiss and Japanese academic centers requiring sub-Ncm precision for alveolar ridge preservation procedures.
Electric motors anchor the volume base while wireless-enabled configurations gain share at the steepest rate.
End User:
Procurement authority and service contract structures diverge sharply between independent practitioners and institutional buyers, with research clinics representing the most technology-forward but smallest volume tier.
- Dentists:Solo and group practices drive recurring replacement demand through 5-7 year hardware cycles and annual calibration contracts. South Korean general practitioners in Seoul and Busan accelerate brushless motor adoption as Osstem Implant and MegaGen localize domestic production and compress lead times.
- Dental Hospitals:Large institutional buyers in Germany and Switzerland consolidate procurement across surgical suites, prioritizing wireless configurations that reduce cross-contamination protocols in infection-control-focused environments. These buyers negotiate multi-year service agreements with original equipment manufacturers.
- Research Clinics:Academic medical centers in Heidelberg and Zurich adopt sensor-integrated motors fastest, enabling procedure documentation for training accreditation while compressing liability exposure.
- Dental Laboratories:Prosthetic-focused facilities purchase motors for abutment adjustment and restoration work, representing a price-sensitive segment with extended replacement cycles.
Dental hospitals command the largest transaction sizes while research clinics set the technology pace that filters downstream.
Technology:
Technology layers stack from foundational motor architecture through digital enablement, with wireless transmission representing the most recent integration frontier reshaping surgical suite design.
- Brushless Technology:Eliminated commutator friction enables superior torque stability and programmable speed profiles. German precision engineering suppliers around Stuttgart feed motor assembly lines with high-tolerance stator components, reducing lead times for manufacturers serving EU MDR recertification timelines.
- LED Technology:Integrated illumination systems reduce auxiliary equipment in osteotomy procedures. Demand clusters in Japanese and South Korean clinics where surgical field visibility standards exceed European baselines.
- Wireless Technology:Cable-free power transmission eliminates cord contamination risks and enables flexible surgical suite configurations. German and Swiss ambulatory surgical centers adopt fastest, opening channel expansion for infection-control-focused procurement.
- Digital Technology:Embedded surgical navigation algorithms and closed-loop feedback systems create software-as-medical-device regulatory exposure under FDA guidance.
Brushless technology anchors installed base economics while wireless configurations climb the fastest as cable-free protocols standardize.
Application:
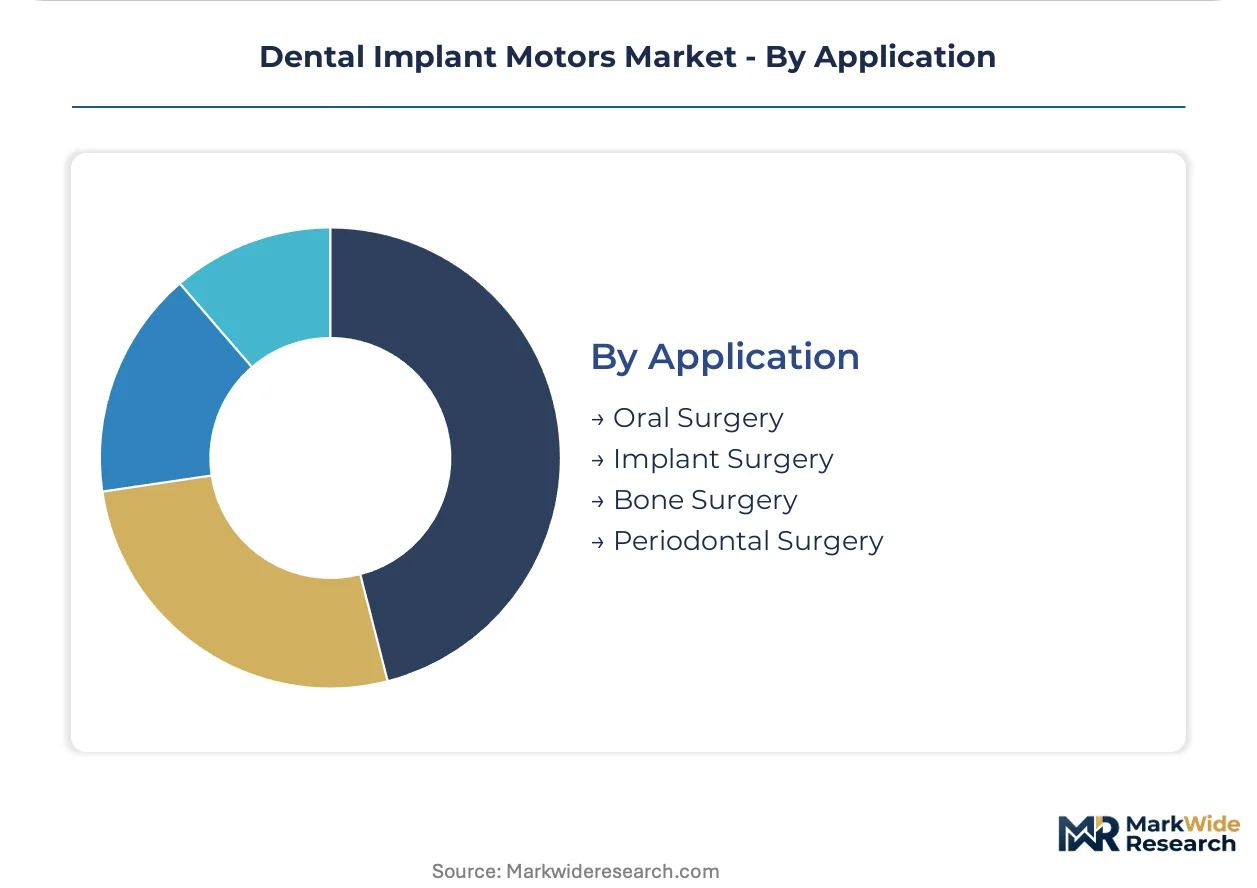
Surgical invasiveness and bone density requirements create distinct torque-precision needs, with implant surgery commanding the most specialized motor specifications.
- Oral Surgery:General extraction and soft-tissue procedures utilize lower-torque motors with broader speed ranges. Polish and Czech dental hospitals retain pneumatic systems for these applications where precision requirements permit cost minimization.
- Implant Surgery:Osteotomy preparation demands 20-80 Ncm torque control with real-time thermal monitoring to prevent alveolar bone necrosis. German and Swiss specialists adopt sensor-integrated brushless motors fastest, enabling procedure documentation and liability reduction.
- Bone Surgery:Ridge augmentation and sinus lift procedures require sustained high-torque delivery. South Korean oral surgeons prioritize Korean-manufactured motors from Osstem Implant and MegaGen for these demanding applications.
- Periodontal Surgery:Delicate soft-tissue and root-surface work utilizes ultrasonic and micro-torque configurations. Japanese periodontal specialists drive demand for piezoelectric systems with sub-Ncm precision.
Implant surgery concentrates premium motor value while bone surgery applications expand most quickly as ridge augmentation volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brushless motor assembly concentrates in precision engineering clusters across Germany, South Korea, Switzerland, and Japan, with each hub feeding distinct regulatory timelines and procurement protocols for dental device manufacturers.
Germany
Dental hospitals in Stuttgart and Munich accelerate brushless motor procurement ahead of EU MDR Class IIa recertification deadlines. The Federal Institute for Drugs and Medical Devices enforces torque-validation protocols under ISO 14457 harmonization requirements. The Stuttgart precision engineering cluster supplies high-tolerance stator assemblies to Straumann Group and Dentsply Sirona assembly lines serving Central European implantology practices.
South Korea
Seoul-area dental hospitals expand procurement of domestically manufactured brushless systems as Osstem Implant and MegaGen localize motor assembly. The Ministry of Food and Drug Safety streamlines premarket notification pathways for electric platforms with embedded torque sensors. The Busan-Ulsan manufacturing corridor houses precision component suppliers establishing captive supply relationships with Korean device manufacturers.
Switzerland
Ambulatory surgical centers in Zurich and Basel adopt wireless motor configurations fastest to reduce cross-contamination protocols in infection-control-focused environments. Swissmedic maintains stringent software-as-medical-device guidance for motors with embedded surgical navigation algorithms. The Basel-Zurich medical technology corridor concentrates R&D facilities for sensor-integrated torque systems with closed-loop thermal monitoring.
United States
Dental service organizations across multi-state clinic footprints consolidate procurement, fragmenting aftermarket service revenue across regional calibration networks. The FDA 510(k) premarket notification pathway compresses product launch cycles for electric motor platforms seeking North American market access. The Greater Boston medical device cluster hosts precision sensor manufacturers supplying strain-gauge feedback systems for Ncm-precision torque control.
Japan
Periodontal specialists in Tokyo and Osaka drive demand for piezoelectric ultrasonic motors with sub-Ncm precision for alveolar ridge preservation procedures. The Pharmaceuticals and Medical Devices Agency evaluates embedded surgical navigation algorithms under evolving software-as-medical-device frameworks. The Nagoya precision manufacturing belt supplies LED-integrated motor components for Japanese clinics where surgical field visibility standards exceed European baselines.
Dental Implant Motors Market Vendor Landscape
Full-line dental device conglomerates and specialized motor manufacturers split the market into distinct competitive tiers with divergent service revenue models and channel strategies. The vendor base concentrates around three strategic archetypes: integrated dental platform operators capturing recurring maintenance contracts, precision electromechanical specialists anchoring premium replacement cycles through authorized networks, and regional device manufacturers localizing assembly to compress lead times. Dominant competitive moves include portfolio rationalization toward brushless architectures ahead of regulatory renewal peaks and geographic expansion through captive supplier relationships in Seoul-area manufacturing corridors.
Within the integrated platform tier, Dentsply Sirona and Straumann Group occupy positions that bundle hardware with surgical protocol training and multi-year service agreements. NSK sits within the precision electromechanical specialist archetype, anchoring premium handpiece and motor replacement cycles. Osstem Implant exemplifies the regional manufacturer archetype, localizing brushless motor assembly to serve domestic South Korean demand.
| Leading Market Players |
|---|
| Dentsply Sirona |
| NSK |
| Aseptico |
| Saeshin |
| Straumann Group |
| Zimmer Biomet |
| Envista Holdings |
| Osstem Implant |
| MegaGen |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on German and Japanese strain-gauge suppliers for Ncm-precision torque sensors compresses margin stability for mid-tier motor assemblers and forces pricing tier spreads that separate sensor-integrated platforms from basic brushless configurations. EU MDR recertification timelines and FDA software-as-medical-device guidance create regulatory chokepoints that concentrate pricing power with full-line device conglomerates capable of absorbing compliance costs while fragmenting aftermarket service revenue across regional calibration networks.
Pricing Analysis
FDA 510(k) and EU MDR Class IIa certification obligations dictate the pricing tier structure across the dental implant motors landscape. Three-tier pricing separates premium sensor-integrated platforms from standard brushless configurations from economy pneumatic systems, with certification grade and after-sales service bundling as the primary differentiation drivers. Cost compression in mid-tier electric motors is intensifying because rare-earth magnet price volatility erodes assembler margins lacking long-term neodymium supply contracts. Dental service organizations consolidating multi-state procurement exhibit highest price sensitivity, while academic medical centers in Germany and Switzerland prioritize liability reduction over unit cost.
Supply Chain Analysis
Neodymium rare-earth feedstock draws from Chinese mining and separation facilities, with German and Japanese suppliers dominating strain-gauge manufacturing for precision torque feedback systems. Brushless stator assemblies feed from Stuttgart precision engineering clusters, while LED-integrated components source from Nagoya manufacturing belts. Single-source vulnerability in torque sensor subcomponents creates geographic concentration risk that could disrupt motor production for EU MDR recertification deadlines. Distribution runs through authorized dealer networks in East Asia and direct hospital system contracts in Central Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless DC architectures are displacing pneumatic platforms as wireless surgical suites reshape infection-control protocols, compressing replacement cycles and fragmenting service revenue models across dental device supply chains.
For Market Incumbents: Entrench market position through backward integration into brushless stator assembly capacity in Stuttgart-area precision engineering clusters, capturing margin pool erosion from component suppliers. Deepen clinician lock-in by bundling implant motors with surgical protocol training and multi-year calibration contracts, defending against third-party biomedical technicians fragmenting aftermarket torque-recertification revenue. For New Entrants and Emerging Players: Eastern European dental hospitals in Bulgaria and Romania present underpenetrated conversion opportunities where pneumatic infrastructure lock-in delays electric motor adoption despite superior torque stability. Target hybrid motor configurations serving transitional clinics managing mixed handpiece fleets, leveraging lower capital thresholds than full brushless platform investments while establishing service relationships for future upgrade cycles. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors precision electromechanical specialists with captive sensor supply relationships and software-enabled service revenue models. Long-term viability hinges on regulatory navigation capabilities across FDA software-as-medical-device determinations and EU MDR recertification timelines. Watch for FDA guidance clarity on embedded surgical navigation algorithms as the inflection signal reshaping R&D allocation between hardware engineering and digital platform development.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Recertification Investment | Accelerates clearance timelines for electric platforms with embedded torque sensors ahead of renewal peaks. |
| Wireless Power Transmission Development | Opens channel expansion into infection-control-focused ambulatory surgical centers in Germany and Switzerland. |
| Captive Strain-Gauge Supplier Relationship | Mitigates single-source dependency risk in Ncm-precision feedback systems from German and Japanese manufacturers. |
| Surgical Navigation Algorithm Integration | Creates software-as-medical-device regulatory exposure under FDA guidance while enabling procedure documentation. |
| Seoul-Area Manufacturing Localization | Compresses lead times for South Korean domestic production expansion by Osstem Implant and MegaGen. |
Methodological Framework
Cross-validation between primary interviews with dental device procurement managers, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and ISO 14457 harmonization documentation. Bottom-up motor shipment estimates from precision engineering clusters in Stuttgart, Seoul, and Nagoya triangulate against top-down dental implant procedure volumes across Germany, South Korea, Switzerland, and Japan.
Calibration against historical replacement cycle data and regulatory timeline compressions shapes the analytical framework across the projection horizon. Segmentation dimensions span torque-delivery architecture, clinical setting, digital integration layer, and regional regulatory cluster. CAGRs derive from installed base turnover rates, EU MDR recertification pull-forward effects, and wireless configuration adoption curves in infection-control-focused environments.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by mid-tier motor assemblers or accelerated FDA software-as-medical-device determinations would shift outcomes beyond modeled parameters. Cross-checking against hospital capital expenditure surveys and dental service organization consolidation trajectories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Needle Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
North America Dental Lab Market
Dental Devices
Digital Facebow Market
Dental Devices
Global Dental Turbine Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
Acrylic Teeth Market
Dental Devices
North America Dental Lasers Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Global Dental Labs Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Europe CBCT Dental Imaging Market