
 Central Venous Catheter Market | 2026-2036
Central Venous Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Central Venous Catheter Market Analysis
Antimicrobial surface engineering is reshaping central venous catheter design priorities across the supply base. Teleflex Incorporated leverages its integrated manufacturing footprint to sustain catheter production at scale for North American hospitals. Becton, Dickinson and Company anchors its position through deep R&D investment in infection-resistant materials. B. Braun Melsungen AG dominates European catheter supply with specialized silicone-based product lines.
A central venous catheter is a thin, flexible tube inserted into a large vein to enable prolonged vascular access for medication delivery, fluid resuscitation, blood sampling, or hemodynamic monitoring, typically constructed from silicone or polyurethane with multi-lumen configurations. Silicone catheters offer superior biocompatibility and extended dwell times for chronically ill patients, while polyurethane variants provide greater tensile strength for acute care settings. Triple lumen configurations command premium positioning in intensive care due to simultaneous multi-therapy requirements, whereas home healthcare channels represent the fastest-growing end-user segment as payors shift reimbursement toward outpatient settings.
The FDA enforces stringent premarket notification requirements under 510(k) pathways for antimicrobial-coated devices, directly shaping product development timelines and clinical evidence standards for manufacturers seeking US market access. The EMA's Medical Device Regulation imposes expanded clinical evaluation obligations that filter lower-capability suppliers from European distribution channels. Stakeholders must monitor evolving reimbursement policies for outpatient catheter care as home-based infusion therapy expands.
Market Dynamics
Antimicrobial surface engineering is forcing catheter manufacturers to reconfigure material supply chains and clinical validation protocols simultaneously. The FDA's updated guidance on antimicrobial coatings compresses development timelines while elevating evidence standards, creating asymmetric pressure across the supplier base.
Growth Catalysts
- Intensive Care Unit Demand:Hospitals in the United States are prioritizing infection prevention protocols, driving volume procurement of multi-lumen systems for simultaneous therapy delivery.
- EMA Medical Device Regulation:Expanded clinical evaluation obligations under MDR are filtering lower-capability suppliers from European distribution channels, concentrating volume with compliant manufacturers.
- Silicone Biocompatibility:Superior dwell times for chronically ill patients are expanding silicone catheter utilization in home healthcare settings where extended vascular access reduces replacement frequency.
Market Restraints
- Polymer Input Volatility:Medical-grade polyurethane and silicone resin prices fluctuate with petrochemical feedstock markets, compressing margin stability for catheter producers.
- Premarket Notification Burden:FDA 510(k) pathway requirements for antimicrobial-coated devices extend validation timelines, delaying revenue recognition for novel surface technologies.
- Peripherally Inserted Central Catheter Substitution:PICC lines are capturing select acute care applications where central venous placement risk outweighs multi-lumen utility.
Strategic Opportunities
- Home Healthcare Expansion:Reimbursement shifts toward outpatient infusion therapy in the United States are accelerating demand for patient-managed catheter systems with simplified maintenance protocols.
- Antimicrobial Coating Convergence:Integration of silver-ion and chlorhexidine technologies is enabling next-generation surface engineering that addresses biofilm resistance.
- Indian Subcontinent Penetration:Underdeveloped critical care infrastructure in tertiary hospitals across India presents white space for standardized triple-lumen catheter deployment.
Industry Challenges
- Clinical Evidence Generation:Randomized controlled trials for infection rate reduction require multi-site coordination, extending time-to-label claims for antimicrobial devices.
- Legacy System Integration:Electronic health record compatibility for catheter tracking and maintenance scheduling demands specialized IT expenditure from mid-sized hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Venous Catheter Market |
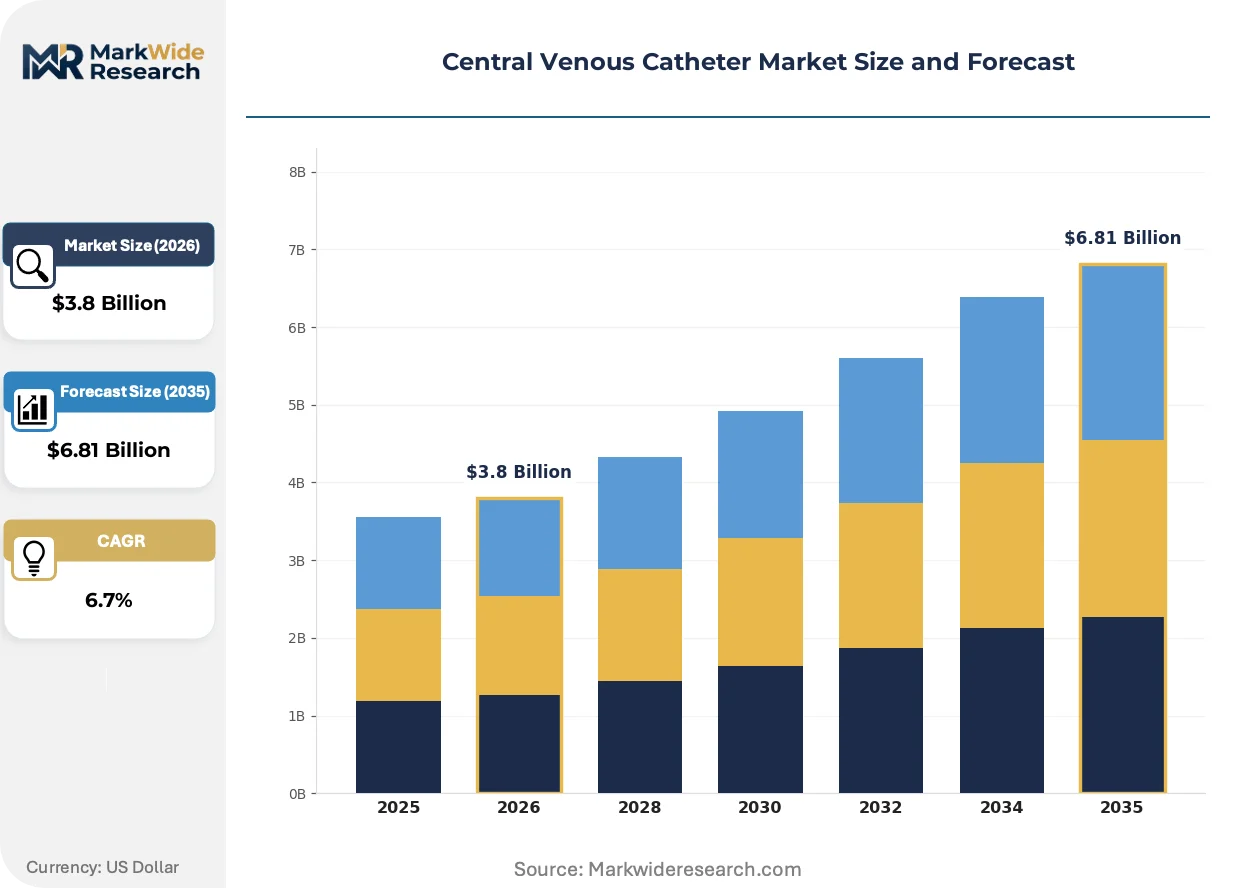
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triple Lumen, Double Lumen, Single Lumen, Tunneled Catheters End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Healthcare Material: PVC, Silicone, Polyurethane, Coated Catheters Insertion Method: Subclavian, Internal Jugular, Femoral, Percutaneous |
| Companies Covered | Teleflex Incorporated, Becton, Dickinson and Company, B. Braun Melsungen AG, ICU Medical, AngioDynamics, Medtronic, Cook Medical, Merit Medical Systems, Lepu Medical Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Venous Catheter Market Emerging Trajectories
Surface engineering and care setting migration are restructuring how catheter value is captured across the supply chain. Material science advances are compressing the traditional trade-off between biocompatibility and mechanical performance.
Antimicrobial coating technology is migrating from passive silver-ion impregnation to active release mechanisms with tunable elution profiles. Intensive care units in the United States are adopting these systems at accelerated pace to meet hospital-acquired infection reduction targets. This technology is migrating from premium positioning toward standard-of-care expectation, compressing pricing power for uncoated alternatives.
EMA Medical Device Regulation implementation is elevating post-market surveillance obligations for silicone-based catheters across European distribution channels. Manufacturers must maintain clinical follow-up registries that document long-term biocompatibility outcomes. German and French health technology assessment bodies are incorporating this surveillance data into procurement qualification criteria, favoring suppliers with established European notified body relationships.
Hospital purchasing consortia are consolidating catheter procurement under standardized vendor agreements that bundle maintenance training with device supply. Group purchasing organizations in the United States are displacing individual hospital negotiations, compressing supplier margin through volume-commitment structures. This concentration is most visible in integrated delivery networks across Texas and California, where system-wide standardization reduces clinical variation.
Central Venous Catheter Market Segmentation
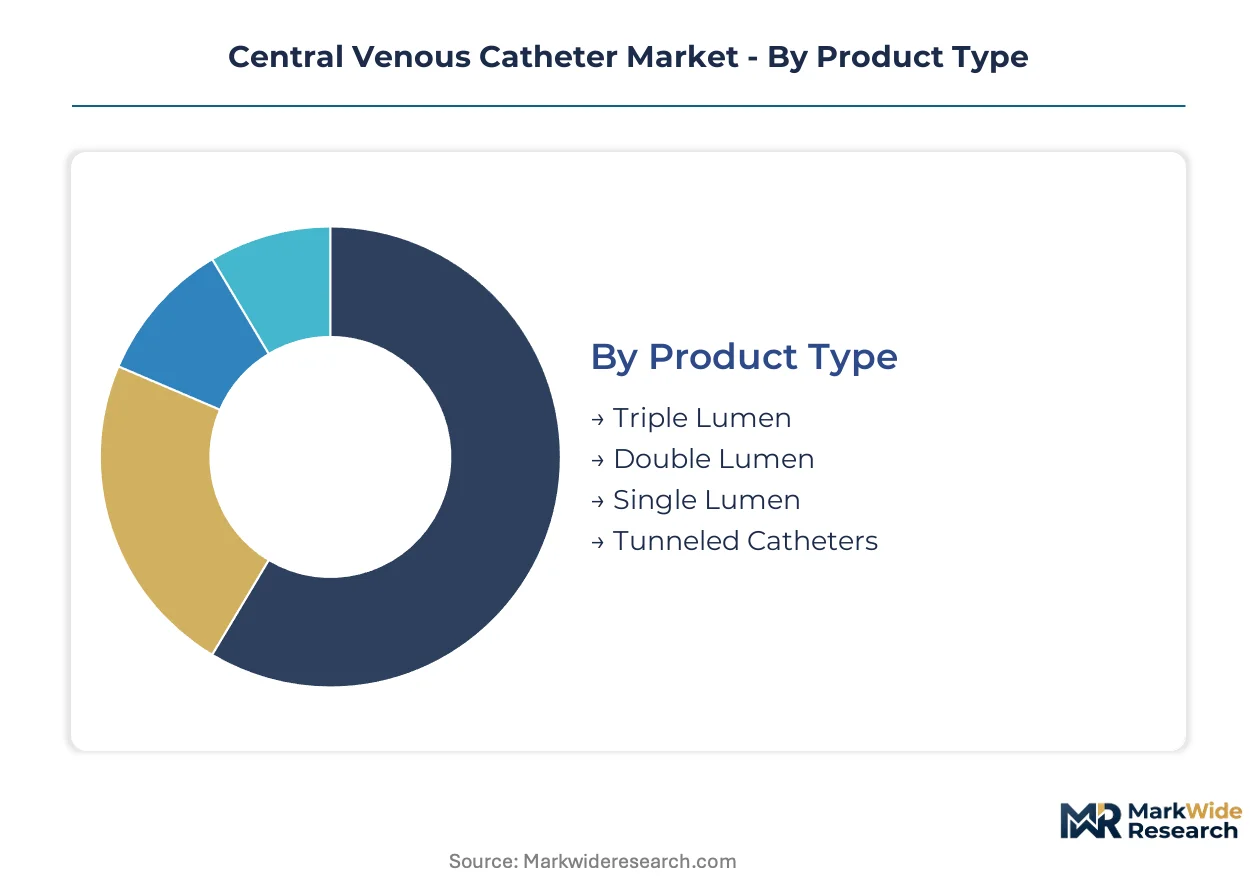
Catheter segmentation reveals how clinical requirements fragment procurement decisions across care settings. Material selection, lumen configuration, and insertion approach each create distinct supply relationships and margin structures for manufacturers serving vascular access needs.
Product Type:
Use-case spectrum spans intensive care multi-therapy delivery through long-term outpatient vascular access.
- Triple Lumen:Three independent channels enable simultaneous infusion of incompatible medications, parenteral nutrition, and hemodynamic monitoring without line conflicts. United States intensive care units drive concentrated procurement of these systems as hospitals consolidate vendor agreements under infection prevention protocols.
- Tunneled Catheters:Subcutaneous tunneling with Dacron cuff creates biological seal against bacterial migration, supporting extended dwell times for hemodialysis and chemotherapy. Home healthcare channels are expanding adoption of these devices as reimbursement shifts toward outpatient infusion therapy.
- Double Lumen:Dual-channel configuration balances access versatility with insertion profile for intermediate-acuity patients requiring limited simultaneous therapies.
- Single Lumen:Simplified construction reduces cost and thrombosis risk for patients needing dedicated medication or fluid delivery without multi-access requirements.
Established volume favors triple lumen configurations in acute care; emerging adoption favors tunneled catheters in shifting reimbursement landscapes.
End User:
Cost tier separation distinguishes capital-intensive hospital systems from distributed outpatient channels.
- Hospitals:Integrated delivery networks in Texas and California negotiate system-wide standardization contracts that bundle device supply with clinical training. Group purchasing organizations concentrate procurement leverage, compressing supplier margins through volume-commitment structures.
- Home Healthcare:Patient-managed catheter systems with simplified maintenance protocols are climbing the fastest as payors redirect reimbursement toward outpatient settings. Silicone-based devices with extended dwell times reduce replacement frequency for chronically ill patients in residential care.
- Ambulatory Surgical Centers:Same-day procedure focus drives preference for pre-assembled kits that minimize preparation time and infection risk in high-throughput environments.
- Clinics:Limited procedure volume and capital constraints favor standardized double-lumen configurations over specialized premium alternatives.
Procurement consolidation favors hospital networks; margin expansion favors home healthcare channels.
Material:
Application requirements create divergent performance priorities between biocompatibility and mechanical strength.
- Silicone:Elastomeric composition permits extended indwelling periods with reduced thrombogenicity and tissue irritation. EMA Medical Device Regulation post-market surveillance obligations favor suppliers with established European notified body relationships for silicone-based product lines.
- Coated Catheters:Silver-ion and chlorhexidine surface engineering addresses biofilm resistance through tunable elution profiles. FDA 510(k) pathway requirements for antimicrobial-coated devices extend validation timelines while elevating evidence standards.
- Polyurethane:Tensile strength and kink resistance suit acute care settings requiring rapid insertion and high-pressure infusion capabilities.
- PVC:Lower material cost supports single-use economics in price-sensitive procurement environments with shorter intended dwell periods.
Clinical evidence generation favors coated alternatives; supply stability favors established silicone and polyurethane supply chains.
Insertion Method:
Volume concentration reflects procedural safety profiles and anatomical accessibility across patient populations.
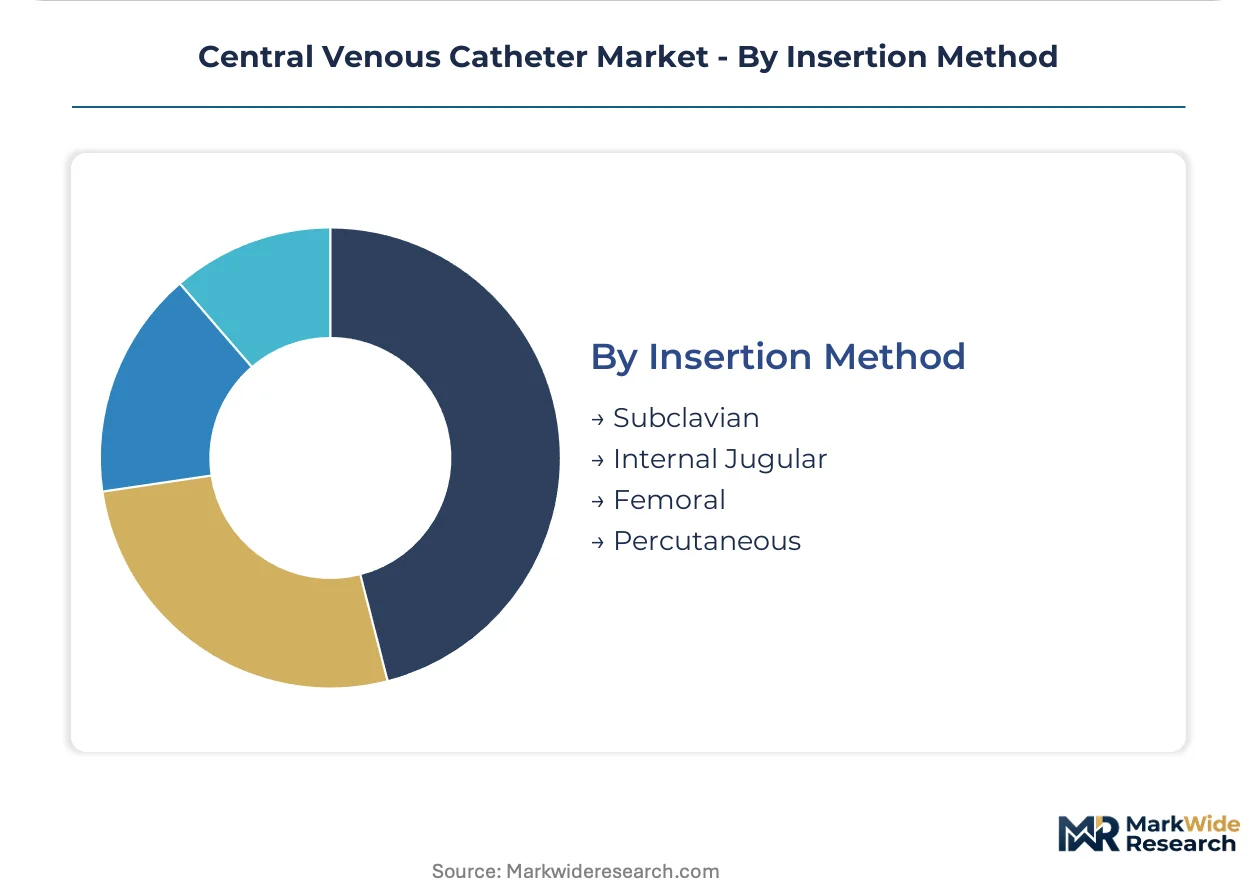
- Internal Jugular:Superficial location and direct path to superior vena cava reduce pneumothorax risk compared to subclavian approaches. United States intensive care units favor ultrasound-guided internal jugular placement as standard protocol for central line insertion.
- Subclavian:Fixed anatomical position enables rapid blind insertion in emergency resuscitation scenarios where ultrasound is unavailable. Catheter malposition and pneumothorax complications limit adoption in elective placement protocols.
- Femoral:Lower infection risk in short-term use and avoidance of thoracic complications make this approach viable for perioperative monitoring and emergency access.
- Percutaneous:Seldinger technique variants enable bedside placement without surgical cutdown, reducing procedure time and resource requirements.
Protocol standardization favors internal jugular placement; emergency access scenarios preserve subclavian and femoral alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate procurement volume for advanced catheter systems, while European hospital consortia and Asia-Pacific tertiary care expansion create distinct demand archetypes across geographies.
United States
Large health systems in Texas and California drive standardized vendor agreements that bundle device supply with clinical training programs. FDA 510(k) premarket notification requirements for antimicrobial-coated devices compress development timelines while elevating evidence standards for manufacturers. The Greater Boston medical technology cluster anchors innovation in infection-resistant materials and surface engineering protocols.
Germany
Hospital purchasing consortia concentrate procurement leverage for silicone-based catheter systems serving chronically ill patient populations. EMA Medical Device Regulation post-market surveillance obligations favor suppliers with established European notified body relationships. The Baden-Württemberg industrial corridor hosts specialized manufacturers with deep R&D investment in biocompatible elastomer formulations.
China
Tertiary hospital expansion in the Yangtze River Delta and Pearl River Delta regions accelerates demand for multi-lumen catheter systems in critical care settings. NMPA medical device registration requirements impose clinical evaluation standards that filter lower-capability domestic suppliers. Shanghai-based medical device clusters are scaling production capacity for polyurethane catheter variants targeting acute care applications.
India
Underdeveloped critical care infrastructure in tertiary hospitals across Maharashtra and Karnataka presents deployment opportunities for standardized triple-lumen catheter systems. CDSCO medical device regulations are tightening quality standards for imported and domestically manufactured vascular access devices. The Delhi-NCR healthcare corridor is attracting catheter suppliers seeking penetration into government hospital procurement channels.
Japan
Aging demographics and chronic disease prevalence expand demand for tunneled catheters supporting extended outpatient infusion therapy. PMDA pharmaceutical and medical device agency requirements maintain stringent clinical evidence standards for antimicrobial surface technologies. The Kanto region surrounding Tokyo concentrates specialized vascular access centers with advanced catheter maintenance protocols.
Central Venous Catheter Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The supplier base concentrates around three archetypes: integrated medical technology conglomerates with diversified vascular access portfolios, specialized catheter manufacturers with focused silicone or polyurethane expertise, and regional fabricators serving price-sensitive procurement channels. M&A activity targets antimicrobial coating capabilities, while strategic partnerships address EMA notified body relationships for European market access.
Within the integrated conglomerate tier, Teleflex Incorporated and Becton, Dickinson and Company exemplify channel-controlling positions through North American hospital system relationships. B. Braun Melsungen AG occupies a specialized position in European silicone catheter supply. These three entities anchor distinct competitive vectors: scale-driven procurement consolidation, infection-resistant material R&D, and regional regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| ICU Medical |
| AngioDynamics |
| Medtronic |
| Cook Medical |
| Merit Medical Systems |
| Lepu Medical Technology |
| Others |
Supply Flow & Price Mechanics
The Port of Rotterdam's medical-grade polymer freight corridors transmit cost volatility from petrochemical feedstock markets into catheter manufacturing economics, concentrating margin pressure on suppliers serving price-sensitive procurement channels while enabling premium pricing for antimicrobial-coated alternatives with validated clinical outcomes.
Pricing Analysis
Cost-plus contracts with medical-grade silicone and polyurethane indexation dominate procurement agreements between catheter manufacturers and hospital group purchasing organizations. Three-tier pricing structure across premium antimicrobial-coated, standard multi-lumen, and economy single-lumen configurations reflects FDA 510(k) certification burden and clinical evidence requirements. Pricing pressure stems from GPO volume-commitment structures that compress supplier margins through system-wide standardization contracts. Ambulatory surgical centers exhibit highest price sensitivity due to limited procedure margins, while integrated delivery networks in Texas and California prioritize infection-rate reduction over unit cost.
Supply Chain Analysis
Supplier-financing instruments including extended payment terms and supply-chain finance facilities have become standard in catheter procurement, with German and Malaysian resin producers anchoring medical-grade silicone supply. The manufacturing base draws from United States, Germany, and China for finished device assembly, with polymer compounding concentrated in Belgium and Japan. Raw material dependencies center on medical-grade polyurethane resin, silver-ion antimicrobial additives, and precision extrusion equipment. Single-source vulnerability in antimicrobial coating chemistry creates supply chain risk. Distribution runs through hospital purchasing consortia and specialized medical device distributors serving outpatient infusion channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA 510(k) and EMA MDR compliance creates durable barriers against unvalidated competitors, locking in incumbent positions for suppliers with established notified body relationships.
For Market Incumbents: Harden antimicrobial coating validation pipelines to preempt biofilm resistance evolution, while consolidating European notified body relationships to filter emerging competitors under expanded MDR surveillance obligations. Capacity expansion in Indian catheter assembly addresses tariff exposure from China-centric supply. Deepen backward integration into medical-grade silicone compounding to defend margin position against petrochemical input volatility. For New Entrants and Emerging Players: Establish a beachhead in Indian government hospital procurement channels where CDSCO quality standard enforcement is elevating entry barriers for unvalidated domestic suppliers. Home healthcare patient-managed catheter systems with simplified maintenance protocols represent the most penetrable white space as United States reimbursement shifts toward outpatient settings. Pursue strategic partnerships with established European notified bodies to accelerate EMA MDR compliance timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core vascular access portfolios, particularly silicone catheter lines requiring specialized biocompatibility expertise. Long-term viability hinges on antimicrobial surface technology differentiation and GPO contract tenure rather than manufacturing scale alone. Monitor FDA guidance evolution on combination product classification as inflection indicator for coating technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket notification for antimicrobial-coated devices accelerates US market access for validated surface technologies. |
| CE Marking Pathway | EMA MDR compliance through European notified body relationships filters lower-capability suppliers from distribution channels. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and California bundle device supply with clinical training programs. |
| Software Companion Development | Electronic health record integration for catheter tracking addresses legacy system compatibility demands from mid-sized hospitals. |
| Reimbursement Strategy | Outpatient infusion therapy coding alignment captures home healthcare channel expansion as payors shift payment models. |
Methodological Framework
Operator-level perspectives from intensive care unit directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract registries, and CMS Medicare reimbursement data. Bottom-up demand modeling across care settings triangulated against top-down manufacturer capacity assessments.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning lumen configuration, material composition, insertion methodology, and end-user channel. CAGRs derived from installed base dynamics, replacement frequency patterns, and antimicrobial technology adoption curves. Forecast inputs incorporated regulatory approval timelines for novel surface coatings and GPO contract renewal cycles at major United States health systems.
Sensitivities concentrate around FDA guidance evolution on antimicrobial device classification, EMA MDR implementation pacing, and polymer feedstock cost trajectories. Forecasts reflect documented assumptions on reimbursement policy continuity and hospital infection prevention protocol standardization. Macroeconomic contraction affecting healthcare capital expenditure, regulatory deviation from current pathways, or breakthrough biofilm-resistant surface technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Injection Practice Pad Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Hemorrhage Control System Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Allografts Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Light Therapy Market
Medical Devices
Spinal Osteosynthesis Units Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Incubator Devices Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
Specimen Retrieval Nets Market