
 Sterilization Box Market | 2026-2036
Sterilization Box Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Box Market Analytics
Ambulatory surgical centers is broadening the end-user mix for sterilization boxes as outpatient procedure volumes shift away from traditional hospital settings. STERIS leverages its installed base of sterilization equipment to bundle container sales with service contracts across North American health systems. B. Braun SE anchors European supply through specialized surgical workflow solutions that integrate container tracking with hospital logistics. MELAG Medizintechnik dominates German-speaking markets with heat-resistant polymer designs engineered for steam and low-temperature sterilization cycles.
A sterilization box is a sealed, perforated container—typically fabricated from surgical-grade stainless steel, anodized aluminum, or medical polymers—designed to hold instruments during autoclave, ethylene oxide, or hydrogen peroxide plasma sterilization while permitting sterilant penetration and maintaining aseptic storage post-cycle. Metal boxes sustain premium positioning in surgical applications where thermal durability and instrument protection justify higher procurement costs against single-use alternatives. Plastic boxes compete aggressively in dental and outpatient settings where weight reduction and color-coded workflow organization drive purchasing decisions. Laboratory applications favor glass and silicone variants where chemical inertness and visibility of contents outweigh durability concerns.
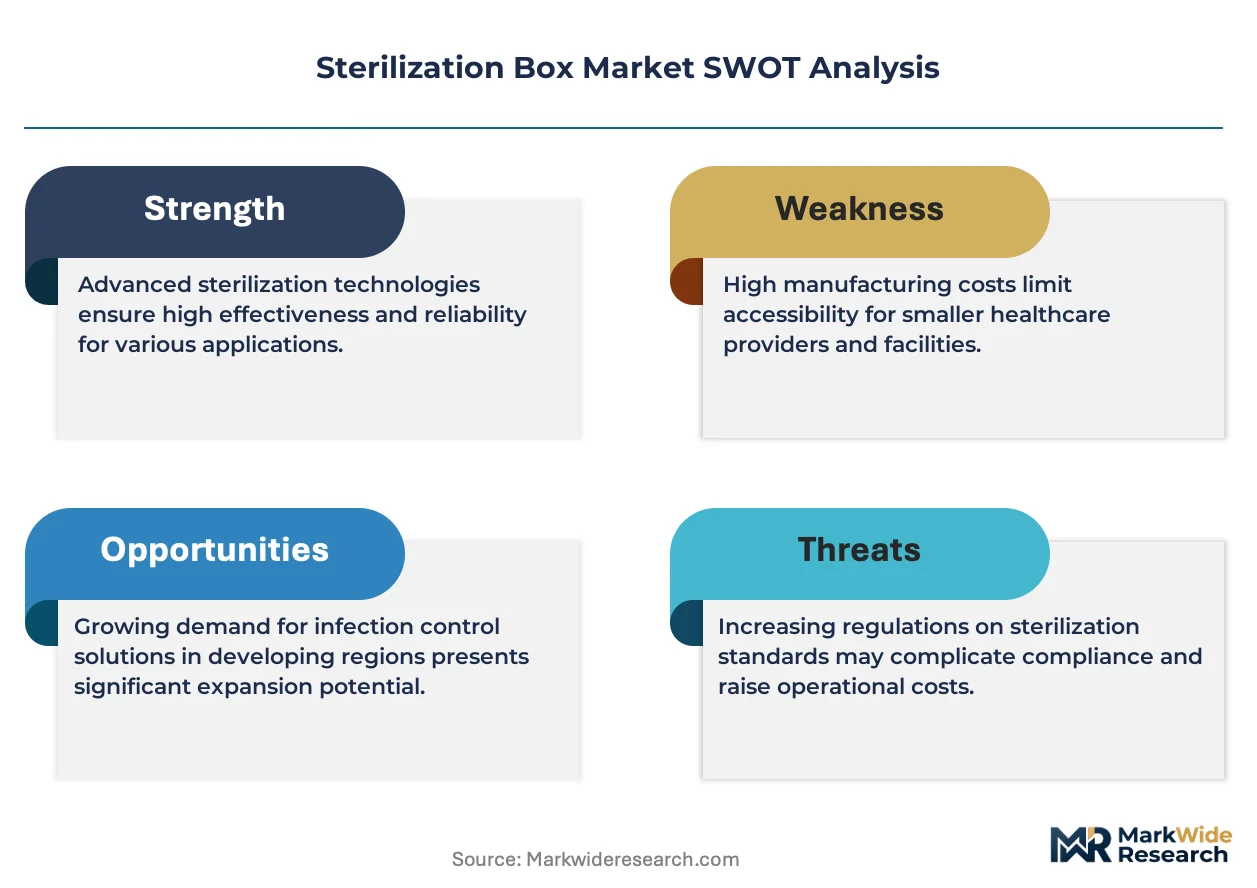
FDA 510(k) clearance requirements and the EU Medical Device Regulation (MDR) impose biocompatibility and validation testing burdens that favor established manufacturers with regulatory affairs infrastructure. ISO 13485 quality management certification functions as a baseline market-access credential for suppliers seeking contracts with integrated delivery networks. The EU F-Gas Regulation and evolving EPA guidelines on ethylene oxide emissions are reshaping sterilization modality preferences, which in turn alters container material specifications and design parameters. Stakeholders must monitor how hospital sustainability mandates and reprocessing liability frameworks alter the trade-off calculus between reusable containers and disposable sterilization wraps.
Market Dynamics
The FDA's updated guidance on reusable medical device reprocessing is tightening validation requirements for container manufacturers, forcing capital redeployment toward quality infrastructure and biocompatibility testing capabilities.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volumes are pulling sterilization box procurement away from traditional hospital supply chains toward specialized distributors serving freestanding surgical facilities.
- EU MDR implementation:The Medical Device Regulation's enhanced traceability mandates are accelerating replacement cycles for legacy containers lacking Unique Device Identification compatibility.
- Heat-resistant polymer engineering:Advanced medical-grade polymers capable of withstanding both steam autoclave and low-temperature hydrogen peroxide plasma cycles are opening dual-protocol flexibility for sterilization departments.
Market Restraints
- Stainless steel input volatility:Surgical-grade 316L stainless steel price fluctuations compress margin stability for metal box manufacturers dependent on commodity-linked supply contracts.
- German supplier concentration:Precision sterilization equipment production clusters heavily around Tuttlingen and Berlin, creating geographic vulnerability to regional logistics disruptions or energy cost spikes.
- Single-use wrap substitution:Disposable sterilization wraps and pouches compete aggressively on upfront capital avoidance, particularly in cost-constrained dental and veterinary settings.
Strategic Opportunities
- Indian hospital infrastructure buildout:Government-funded medical device parks under the PLI scheme create localized manufacturing incentives for sterilization container producers establishing domestic assembly.
- RFID-enabled container tracking:Integration of radio-frequency identification with surgical workflow management systems enables real-time instrument location and sterilization cycle verification.
- EPA ethylene oxide emission limits:Stricter federal air toxics standards are redirecting sterilization modality preferences toward vaporized hydrogen peroxide and steam-compatible container designs.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for medical device suppliers routinely extend 12-18 months, delaying market entry for new container designs.
- Legacy steam autoclave incompatibility:Hospital sterilization departments operate mixed-equipment fleets spanning 20-year replacement cycles, forcing container manufacturers to maintain backward-compatible perforation patterns and gasket specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Box Market |
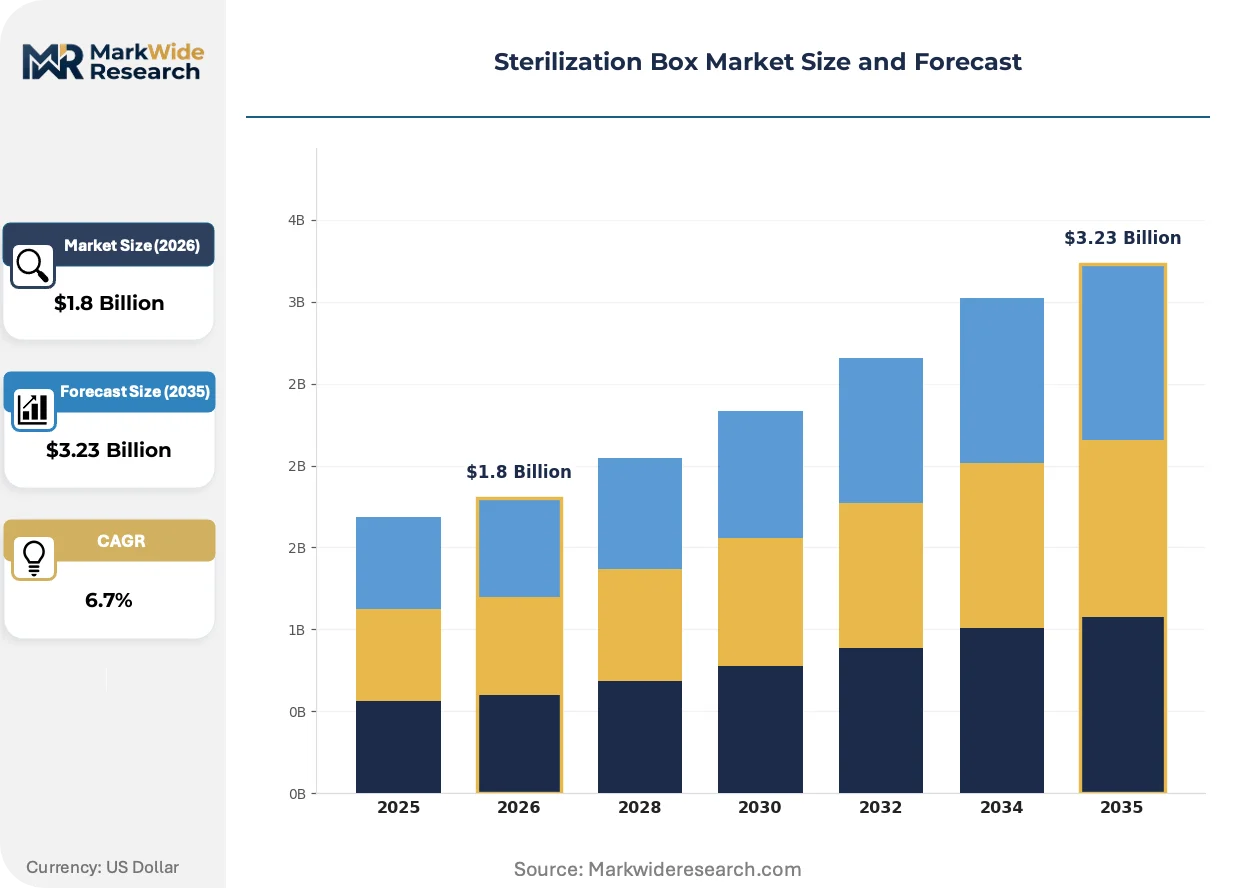
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Boxes, Plastic Boxes, Glass Boxes, Silicone Boxes Application: Dental, Surgical, Laboratory, Pharmaceutical End User: Hospitals, Clinics, Research Institutions, Outpatient Facilities Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Medline Industries, Aesculap, Wagner GmbH, CareFusion, STERIS, B. Braun SE, Integra LifeSciences, MELAG Medizintechnik, KLS Martin Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Box Market Evolving Landscape
Active regulatory pressure on sterilization modalities is forcing material science adaptation, while surgical workflow digitization is embedding intelligence into previously passive containment devices.
Radio-frequency identification tagging is electrifying sterilization box functionality beyond passive containment. RFID-enabled containers transmit sterilization cycle completion, expiration dates, and instrument set contents to hospital information systems. Academic medical centers in the United States are piloting these systems for orthopedic and neurosurgical kits where instrument traceability carries malpractice liability implications. The technology is electrifying competitive differentiation away from material durability toward data integration and surgical workflow optimization.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in medical sterilization equipment manufacturing processes. This policy compresses availability of certain polymer precursors and refrigerants used in low-temperature sterilizer production. Container manufacturers serving European health systems are responding by accelerating heat-resistant polymer validation for steam-only sterilization cycles that bypass fluorinated gas-dependent equipment entirely.
Hospital sterilization departments are unbundling container procurement from equipment service contracts that previously locked buyers into single-source relationships. Integrated delivery networks now negotiate container purchases separately from sterilizer maintenance agreements, opening vendor switching opportunities. This pattern is most visible in Germany and Switzerland where hospital procurement cooperatives aggregate purchasing power across multi-facility networks.
Sterilization Box Market Segmentation
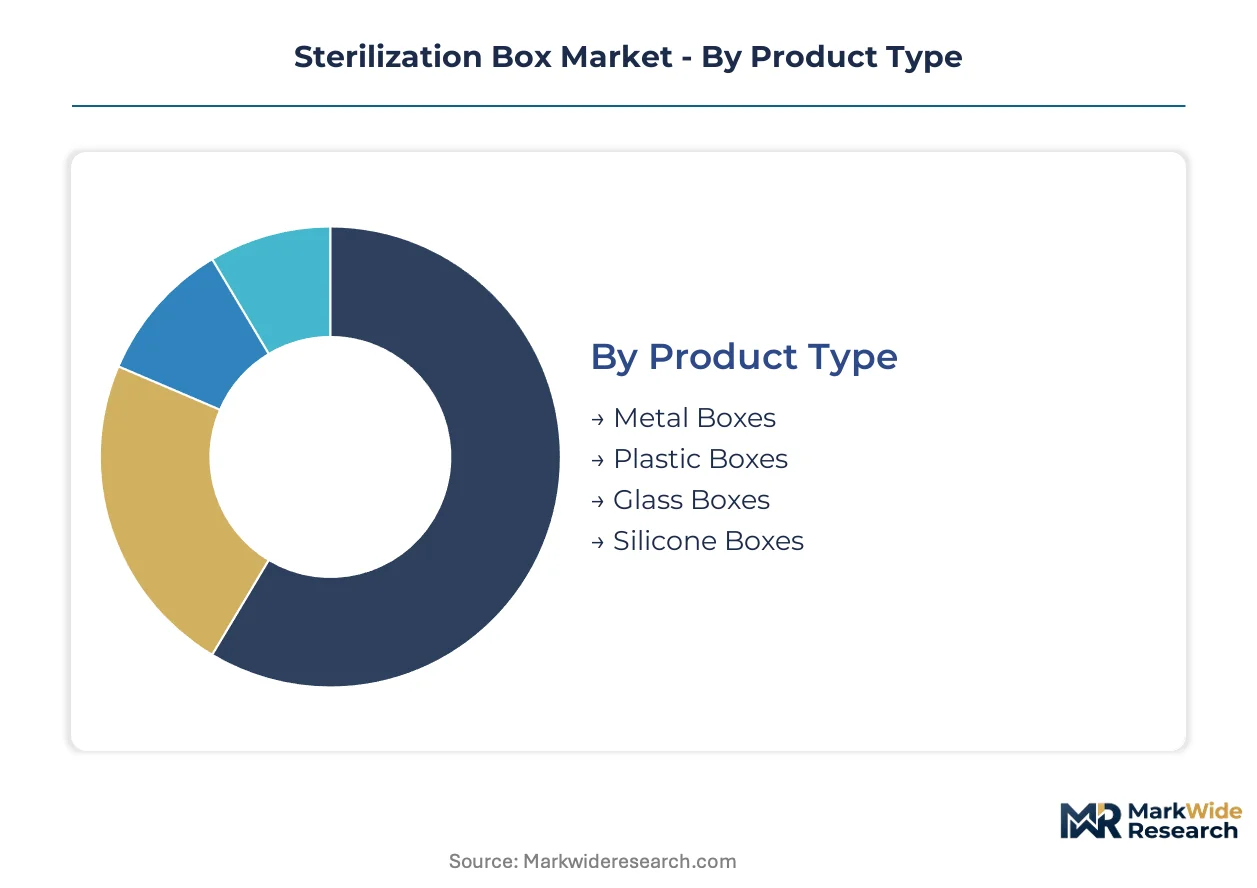
Sterilization box procurement diverges sharply by clinical setting and sterilization modality compatibility. Material selection, distribution channel, and end-user infrastructure maturity create distinct commercial pockets with differentiated margin profiles and replacement cycles.
Product Type:
Metal boxes anchor surgical workflows requiring thermal durability across repeated autoclave cycles, while polymer variants embed into outpatient settings prioritizing weight reduction and color-coded organization.
- Metal Boxes:Fabricated from surgical-grade 316L stainless steel or anodized aluminum, these containers withstand steam autoclave temperatures exceeding 134°C and maintain structural integrity across thousands of reprocessing cycles. Demand concentrates in German hospital networks where MELAG Medizintechnik and KLS Martin Group supply precision-engineered perforation patterns validated for instrument protection. The FDA's tightened reprocessing guidance is forcing manufacturers to redeploy capital toward biocompatibility testing infrastructure.
- Plastic Boxes:Medical-grade polymers—polyphenylsulfone and polyetherimide—deliver dual-protocol flexibility for steam and low-temperature hydrogen peroxide plasma sterilization. Outpatient facilities in the United States are expanding procurement of these lightweight variants as ambulatory surgical center volumes detach from traditional hospital supply chains. Heat-resistant polymer engineering is accelerating validation timelines for containers bypassing fluorinated gas-dependent equipment.
- Glass Boxes:Borosilicate and soda-lime glass variants offer chemical inertness and full content visibility for laboratory applications where instrument traceability is secondary to reagent compatibility.
- Silicone Boxes:Platinum-cured medical silicone provides collapsible, autoclavable containment for flexible endoscopes and delicate instruments requiring cushioned protection during sterilization transport.
Volume placements concentrate in Metal Boxes; the faster expansion belongs to Plastic Boxes.
Application:
Clinical use intensity and regulatory scrutiny intensity vary dramatically across application segments, with surgical and pharmaceutical applications commanding premium validation standards.
- Surgical:Operating theaters demand perforated containers with instrument retention matrices, tamper-evident seals, and RFID compatibility for orthopedic and neurosurgical kits where traceability carries malpractice liability. German-speaking European markets anchor procurement volume through hospital procurement cooperatives aggregating multi-facility purchasing power.
- Dental:Private practices and dental service organizations prioritize color-coded polymer containers for handpiece and bur organization, with procurement flowing through specialized dental distributors rather than hospital supply chains.
- Laboratory:Research institutions specify glass and silicone variants where chemical resistance and visibility outweigh the durability requirements of clinical sterilization workflows.
- Pharmaceutical:Aseptic manufacturing and compounding pharmacies require containers validated for cleanroom transfer with particulate shedding profiles meeting ISO 14644-1 classifications.
Procurement scale favors Surgical applications; Regulatory compliance intensity peaks in Pharmaceutical.
End User:
Capital availability and reprocessing infrastructure maturity segment end users into centralized sterilization departments versus distributed, lower-throughput settings.
- Hospitals:Integrated delivery networks operate centralized sterile processing departments with mixed-equipment fleets spanning 20-year replacement cycles, forcing backward-compatible container specifications. The EU MDR's traceability mandates are accelerating replacement cycles for legacy containers lacking Unique Device Identification.
- Outpatient Facilities:Freestanding ambulatory surgical centers are broadening procurement of reusable sterilization containers as procedure volumes shift away from inpatient settings, with purchasing flowing through specialized distributors.
- Clinics:Physician offices and urgent care centers favor lower-capital disposable wraps or small-format polymer containers with reduced throughput requirements.
- Research Institutions:Academic medical centers pilot RFID-enabled container tracking for instrument location and sterilization cycle verification, embedding intelligence into previously passive containment devices.
Contract value concentrates in Hospitals; the steepest expansion trajectory belongs to Outpatient Facilities.
Distribution Channel:
Channel selection reflects procurement sophistication, with integrated delivery networks unbundling container purchases from sterilizer service contracts.
- Distributors:Specialized surgical and dental distributors dominate European hospital supply, with German procurement cooperatives leveraging aggregated purchasing power across multi-facility networks.
- Direct Sales:STERIS and B. Braun SE deploy field service organizations to bundle container sales with sterilization equipment service contracts, though hospital unbundling trends are eroding this lock-in.
- Online Retail:Dental and veterinary settings procure standardized polymer containers through e-commerce platforms, prioritizing upfront capital avoidance over technical consultation.
- Others:Group purchasing organizations and hospital procurement cooperatives represent non-traditional channels gaining share in cost-constrained markets.
Transaction volume flows through Distributors; margin capture concentrates in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision sterilization equipment manufacturing while the United States and India expand consumption through outpatient infrastructure buildouts. Production clusters in Baden-Württemberg and Berlin supply European hospital networks as Asian markets localize assembly under government incentive schemes.
Germany
Hospital procurement cooperatives aggregate multi-facility purchasing power across Bavaria and North Rhine-Westphalia. The EU Medical Device Regulation's traceability mandates accelerate replacement cycles for legacy containers lacking Unique Device Identification compatibility. Tuttlingen anchors a dense cluster of surgical instrument and sterilization equipment producers serving European health networks.
United States
Ambulatory surgical center expansion pulls procurement away from traditional hospital supply chains toward specialized distributors. The FDA's updated guidance on reusable medical device reprocessing tightens validation requirements for container manufacturers. Academic medical centers in the Northeast pilot RFID-enabled container tracking for orthopedic and neurosurgical kits.
India
Government-funded medical device parks under the Production Linked Incentive scheme create localized manufacturing incentives for domestic assembly. The Central Drugs Standard Control Organization enforces medical device quality standards that align with ISO 13485 certification requirements. Maharashtra and Gujarat host emerging sterilization container production facilities serving South Asian hospital networks.
China
Hospital infrastructure modernization drives demand for heat-resistant polymer containers compatible with mixed sterilization modalities. The National Medical Products Administration implements biocompatibility testing requirements that favor established manufacturers with regulatory affairs infrastructure. The Yangtze River Delta concentrates medical device manufacturing capacity serving domestic and export markets.
Switzerland
Swissmedic maintains stringent device approval processes that reinforce premium positioning for validated sterilization containers. Hospital procurement networks in Zurich and Geneva unbundle container purchases from sterilizer service contracts. The Basel region anchors precision medical technology supply chains integrated with German-speaking European markets.
Sterilization Box Market Competitive Landscape
Top-tier vendors anchor integrated sterilization workflows, while mid-tier specialists compete on material innovation and regional distribution density. The vendor base stratifies across equipment-integrated service providers, precision metal fabricators, and polymer engineering houses. Three archetypes dominate: sterilization equipment bundlers, surgical workflow integrators, and specialized container manufacturers. Competitive moves concentrate on RFID-enabled tracking integration and heat-resistant polymer validation for dual-protocol flexibility.
Among German-based precision manufacturers, MELAG Medizintechnik and KLS Martin Group exemplify the surgical workflow integrator archetype, occupying positions within European hospital procurement networks. STERIS represents the equipment-bundling model, leveraging installed base relationships across North American health systems. These three anchors illustrate how geographic clustering and regulatory infrastructure shape competitive positioning without mandating identical strategic postures.
| Leading Market Players |
|---|
| Medline Industries |
| Aesculap |
| Wagner GmbH |
| CareFusion |
| STERIS |
| B. Braun SE |
| Integra LifeSciences |
| MELAG Medizintechnik |
| KLS Martin Group |
| Others |
Value Network & Pricing Analysis
Family-owned precision metal fabricators in Germany's Tuttlingen cluster anchor supply-side discipline through multi-generational capital stewardship, translating into stable pricing power for surgical-grade sterilization containers even as polymer competitors erode margins in outpatient segments. This ownership structure resists short-term cost-cutting, preserving premium positioning for FDA-validated metal boxes while channeling reinvestment toward biocompatibility testing infrastructure demanded by tightening reprocessing guidance.
Pricing Analysis
Margin tightening in polymer containers traces to aggressive price competition from disposable wrap substitutes and Asian contract manufacturers, while metal box pricing holds firm on ISO 13485 certification premiums and thermal durability guarantees. Three-tier pricing structure across premium surgical-grade stainless steel, validated mid-tier aluminum, and economy polymer separates hospital procurement cooperatives from dental distributors and online veterinary channels. Cost compression accelerates in outpatient-facing SKUs as ambulatory surgical centers prioritize capital avoidance over lifecycle value. Dental clinics exhibit highest price sensitivity, deferring to single-use alternatives; integrated delivery networks show lowest sensitivity, accepting bundled service premiums for traceability-validated containers.
Supply Chain Analysis
Single-source vulnerability sits with German precision equipment clusters concentrated in Baden-Württemberg and Berlin, where energy cost spikes or logistics disruptions would cascade through European hospital supply chains. Raw material dependencies center on surgical-grade 316L stainless steel from specialized European mills, medical-grade polyphenylsulfone resin from limited polymer compounders, and platinum-cured silicone sheeting for flexible instrument protection. Tariff exposure on Chinese polymer feedstocks compounds input cost volatility for dual-protocol container designs. Distribution runs through specialized surgical distributors in German-speaking markets, direct field service organizations for equipment-integrated sales, and e-commerce platforms penetrating cost-constrained dental and veterinary settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterilization box market functions as a cost-of-compliance story where the EU Medical Device Regulation's Unique Device Identification mandates and FDA reprocessing guidance erect regulatory moats favoring established players with quality infrastructure already deployed.
For Market Incumbents: Deploy RFID-enabled tracking integration to lock hospital system relationships against unbundling trends eroding equipment-service contract lock-in. Deepen backward integration into medical-grade polymer compounding to secure dual-protocol container supply chains as the EU F-Gas Regulation phases down hydrofluorocarbon-dependent sterilization equipment. Target acquisition of specialized dental distributors to capture ambulatory surgical center volume migrating from hospital supply chains.
For New Entrants and Emerging Players: Launch via government-funded medical device parks in Maharashtra and Gujarat under India's Production Linked Incentive scheme, leveraging localized assembly incentives and CDSCO-aligned quality standards to bypass entrenched European supply relationships. Target Indian hospital infrastructure buildout as the most penetrable geography, where domestic procurement preferences and greenfield sterilization department investments outpace legacy container replacement cycles in saturated Western markets. Position on heat-resistant polymer validation for steam-only cycles that circumvent fluorinated gas equipment dependencies entirely.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier polymer engineering specialists with ISO 13485 certification infrastructure already amortized, positioned in German-speaking European markets where hospital procurement cooperatives aggregate multi-facility purchasing power. Long-term viability hinges on regulatory compliance durability rather than material cost advantages, with five-to-ten-year windows favoring players whose validation investments outlast commodity price cycles. Watch EPA ethylene oxide emission enforcement as the signal indicator for modality shift acceleration toward vaporized hydrogen peroxide and steam-compatible container designs.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Enabled Container Tracking | Real-time instrument traceability addresses malpractice liability exposure in orthopedic and neurosurgical workflows. |
| Heat-Resistant Polymer Validation | Dual-protocol flexibility bypasses fluorinated gas-dependent sterilization equipment as EU F-Gas restrictions tighten. |
| Hospital Procurement Cooperative Partnerships | Aggregated multi-facility purchasing power in Germany and Switzerland secures volume commitments against unbundling trends. |
| Indian PLI Scheme Manufacturing Localization | Domestic assembly incentives align with CDSCO quality mandates to capture South Asian hospital infrastructure expansion. |
| Biocompatibility Testing Infrastructure Expansion | FDA reprocessing guidance compliance creates barrier-to-entry moat for validated container suppliers. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement database extracts, and GPO contract records, complemented by interviews with sterile processing department managers, biomedical engineers, hospital purchasing committee members, and regulatory affairs directors at container manufacturers. Secondary validation drew from customs trade data, ISO 13485 certification registries, and sterilization equipment service contract disclosures. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel dimensions.
Cross-referencing historical replacement cycle data with expert panel inputs on EU MDR transition timelines and ambulatory surgical center expansion rates anchored the analytical framework across the projection horizon. Segmentation modeling captured material type, sterilization modality compatibility, clinical setting intensity, and regional regulatory cluster variations. CAGRs were derived from fitted growth curves adjusted for modality shift probabilities and infrastructure buildout schedules. Industry-specific forecast inputs included ethylene oxide emission regulation enforcement trajectories and polymer precursor availability under F-Gas phase-down schedules.
Regulatory enforcement delays, raw material price volatility, and sterilization modality substitution rates are the dominant revision risks that could compress or extend projected replacement cycles. Forecasts reflect assumptions about hospital capital allocation priorities and outpatient volume migration patterns that may shift with reimbursement policy changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Luer Plug Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Blood Bags Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Blood Collection Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Global Adhesive Bandages Market