
 Global Disposable Urinary Drainage Bag Market | 2026-2036
Global Disposable Urinary Drainage Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disposable Urinary Drainage Bag Market Analysis
Chinese polymer suppliers and Southeast Asian contract manufacturers are recalibrating resin allocation toward medical-grade PVC and silicone lines as urology device orders climb. C. R. Bard leverages its integrated catheter-to-bag portfolio to capture hospital system contracts across North America. Medline Industries anchors its position through private-label scale and direct distribution to long-term care facilities. Coloplast competes in Europe through specialized hydrophilic-coated systems that reduce catheter-associated urinary tract infection risk.
A disposable urinary drainage bag is a single-use, sterile receptacle manufactured from medical-grade PVC, silicone, or latex, featuring anti-reflux valves, drainage taps, and graduated volume markings; it collects urine from indwelling or external catheters in acute and ambulatory settings. Leg bags dominate ambulatory and home care channels due to discreet wearability and mobility compatibility, while bed bags and high-capacity 2000-5000 ml systems retain institutional preference for immobilized patients. Specialty bags integrating antimicrobial films or metered-output chambers are gaining fastest in premium hospital segments where infection control protocols command procurement priority.
FDA 510(k) clearance requirements and EMA Medical Device Regulation (MDR) conformity assessments govern material biocompatibility, sterility assurance, and clinical performance claims for disposable urinary drainage bags. ISO 10993 biological evaluation standards and REACH chemical substance restrictions further constrain polymer formulation choices and supplier qualification pathways across manufacturing bases. Stakeholders must monitor evolving EPA and MEE environmental regulations on medical plastic waste streams, as extended producer responsibility frameworks threaten to reshape cost structures and regional sourcing decisions for single-use urology products.
Market Dynamics
Hospital procurement consolidation across the United States, Germany, and Japan is compressing supplier margins while simultaneously demanding antimicrobial film integration and metered-output precision from disposable urinary drainage bag manufacturers.
Growth Catalysts
- EMA MDR Conformity Assessments:Stricter biocompatibility documentation requirements under the EU Medical Device Regulation are filtering out marginal suppliers and elevating contract values for qualified manufacturers serving European acute care networks.
- Home Care Channel Expansion:Post-surgical patients and chronic urology cases in Japan are migrating from institutional settings to ambulatory leg bag systems, creating sustained replacement demand outside hospital procurement cycles.
- Antimicrobial Film Adoption:Infection control protocols in German university hospitals now specify silver-ion or chlorhexidine-impregnated PVC layers, pulling premium pricing for compliant product lines.
Market Restraints
- Medical-Grade PVC Resin Volatility:Chinese polymer suppliers face REACH chemical substance restrictions that constrain formulation flexibility and elevate raw material qualification timelines for export-bound production.
- Southeast Asian Contract Manufacturer Concentration:Single-source dependency on Malaysian and Thai converters for silicone component molding creates vulnerability to MEE environmental enforcement actions affecting medical plastic waste processing capacity.
- Catheter-Associated UTI Liability Exposure:Persistent litigation risk around hospital-acquired infections limits willingness to adopt unproven material substitutes even when cost-advantaged.
Strategic Opportunities
- Indian Long-Term Care Facilities:CDSCO regulatory harmonization with ISO 10993 standards is opening import pathways for sterile single-use systems previously blocked by local manufacturing mandates.
- Hydrophilic-Coated System Convergence:Integration of lubricious catheter surfaces with closed-drainage bag architectures reduces bacterial migration pathways, commanding bundled contract premiums in Nordic hospital systems.
- Direct-to-Patient Subscription Models:Digital pharmacy platforms in the United States are bypassing durable medical equipment distributors for recurring leg bag deliveries to spinal cord injury and multiple sclerosis patient cohorts.
Industry Challenges
- FDA 510(k) Clearance Timelines:Novel antimicrobial claims require extensive clinical performance documentation, stretching regulatory approval cycles to 18-24 months and freezing R&D pipeline capital.
- Legacy Sterilization Infrastructure:Ethylene oxide facility closures in the United States following EPA emissions enforcement have forced manufacturers to qualify gamma irradiation alternatives, disrupting supply continuity.
- ISO 10993-5 Cytotoxicity Testing Bottlenecks:Contract laboratory capacity constraints in Germany and Switzerland are delaying biological evaluation completion for new polymer formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disposable Urinary Drainage Bag Market |
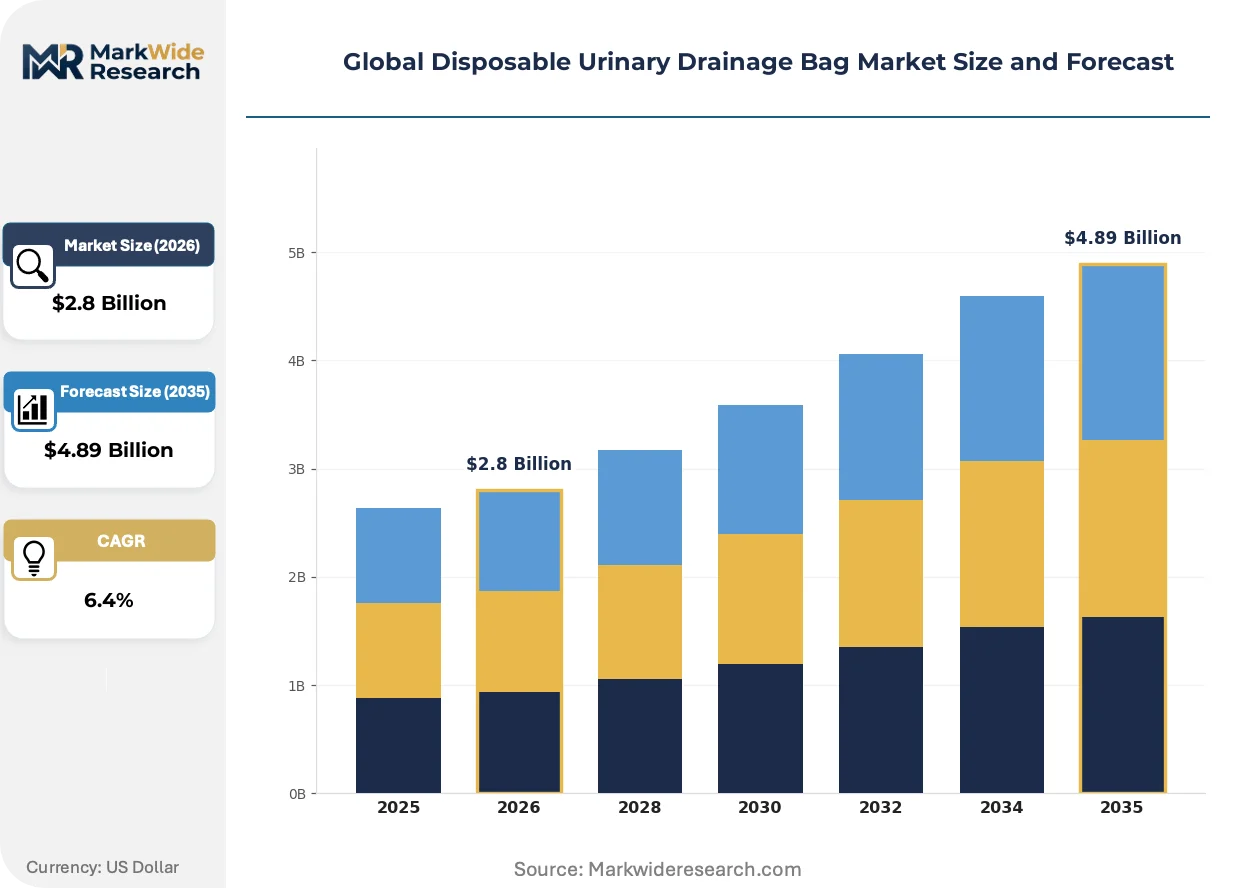
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leg Bags, Bed Bags, Catheter Bags, Specialty Bags Material: Plastic, Latex, PVC, Silicone End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Capacity: 1000 ml, 2000 ml, 3000 ml, 5000 ml |
| Companies Covered | C. R. Bard, Amsino International, Medline Industries, Cardinal Health, Flexicare Medical, Coloplast, Cook Medical, ConvaTec, Covidien (Medtronic), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disposable Urinary Drainage Bag Market Emerging Trajectories
Material science advances and regulatory pressure on single-use plastics are forcing simultaneous innovation in antimicrobial integration, sterilization modality, and closed-system architecture across disposable urinary drainage bag portfolios.
Multi-chamber bag designs with separate sampling ports and anti-reflux valve compartments are modularizing production workflows for manufacturers serving both acute and ambulatory channels. German hospital systems specify these configurations for intensive care units requiring precise output monitoring. The technology is modularizing contract manufacturing arrangements, allowing converters to mix standardized base components with specialty antimicrobial film overlays.
REACH chemical substance restrictions on phthalate plasticizers are compelling PVC formulation shifts toward citrate-based alternatives across European supply chains. Compounders must requalify entire material streams under ECHA authorization timelines. Pediatric and neonatal segments face the steepest compliance burdens, as these applications carry the most stringent extractables testing protocols.
Long-term care facilities in Japan are consolidating supplier relationships around vendors offering predictive replenishment algorithms tied to catheter change protocols. Bundled service contracts now specify volume commitments across leg bag, bed bag, and night drainage configurations. This consolidation is most visible in Tokyo-Osaka corridor procurement, where regional hospital alliances negotiate system-wide agreements displacing fragmented purchasing.
Global Disposable Urinary Drainage Bag Market Segmentation
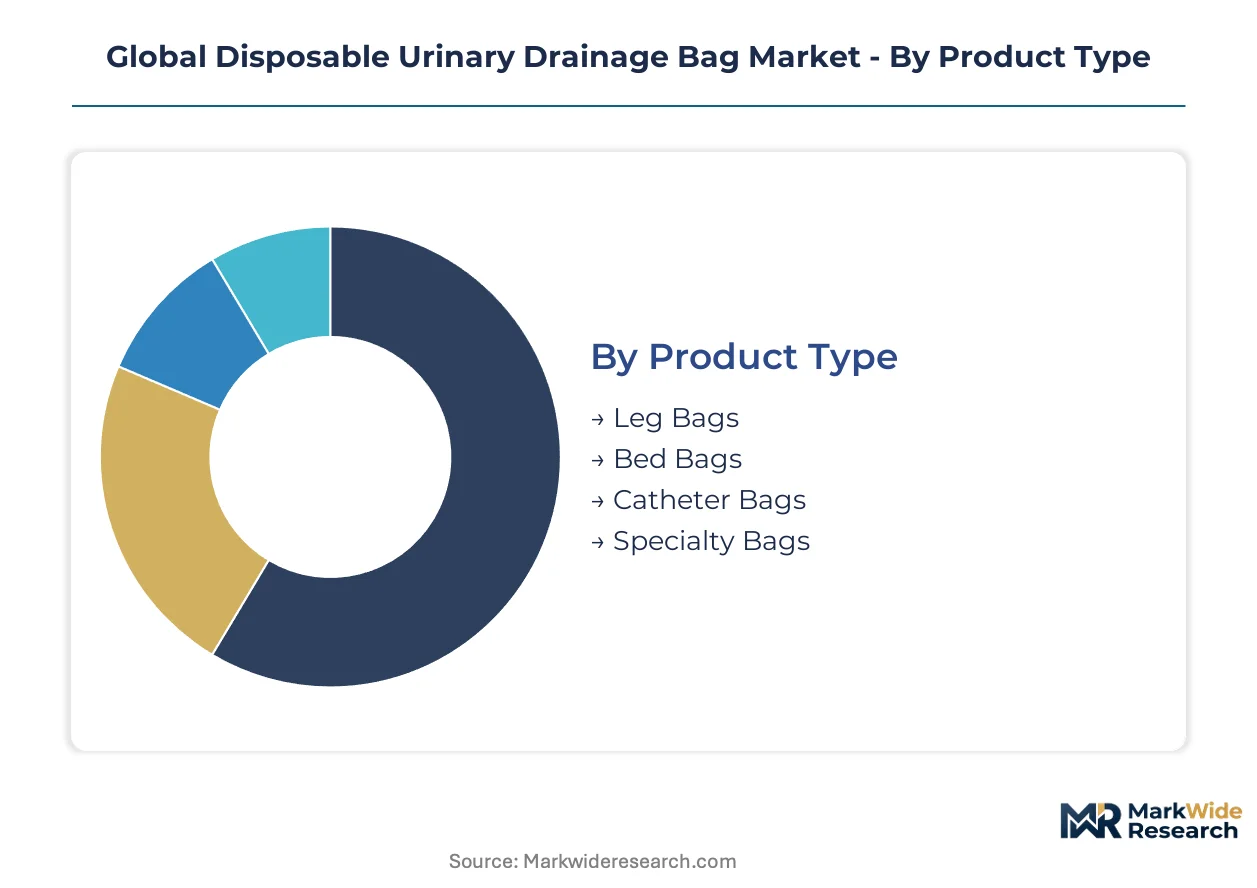
Discrete product architectures versus integrated catheter-drainage systems determine procurement pathways across acute and ambulatory channels. Segmentation clarity enables manufacturers to align sterilization protocols, material qualification timelines, and distribution infrastructure with specific use environments.
Product Type:
Standalone drainage bags serve catheter systems from multiple suppliers, while proprietary bag-catheter combinations lock in recurring revenue through closed architectures.
- Leg Bags:Compact 500-1000 ml reservoirs with fabric straps and anti-reflux valves attach directly to thigh or calf for ambulatory patients. Post-surgical discharge protocols in Japanese home care settings specify leg bag systems with 7-day replacement cycles, creating predictable recurring demand outside hospital purchasing.
- Bed Bags:High-capacity 2000-5000 ml systems with hanging hooks and metered drainage taps serve immobilized ICU and long-term care patients. German university hospitals now require antimicrobial film integration for bed bag contracts, elevating material compliance costs for standard configurations.
- Catheter Bags:Pre-connected closed systems with integrated tubing reduce bacterial migration pathways during catheterization. These configurations dominate operating room and emergency department procurement where sterile field maintenance is non-negotiable.
- Specialty Bags:Multi-chamber designs with separate sampling ports and metered-output chambers serve nephrology and critical care applications requiring precise fluid balance monitoring.
Bed bags lead volumes today; specialty bags are gaining share fastest.
Material:
Polymer selection dictates sterilization modality compatibility, extractables profiles, and regulatory approval timelines across manufacturing bases.
- Plastic:Generic term encompassing polypropylene and polyethylene blends used in economy-tier products for developing market tenders. These formulations face REACH chemical substance restrictions limiting phthalate plasticizer content in European-bound production.
- Latex:Natural rubber formulations persist in cost-sensitive segments despite allergen concerns, primarily serving institutional bulk purchasing in markets without stringent biocompatibility mandates.
- PVC:Medical-grade polyvinyl chloride with DEHP or citrate plasticizers dominates volume production due to weldability, clarity, and gamma sterilization tolerance. Chinese polymer suppliers are recalibrating resin allocation toward medical-grade lines as urology device orders climb.
- Silicone:Platinum-cured elastomers command premium positioning for long-term indwelling applications requiring superior biocompatibility and reduced encrustation. Southeast Asian contract manufacturers in Malaysia and Thailand concentrate silicone component molding capacity.
PVC dominates manufacturing throughput; silicone commands the steepest expansion trajectory.
End User:
Procurement authority and replacement frequency vary sharply across institutional versus patient-directed purchasing environments.
- Hospitals:Centralized purchasing departments negotiate system-wide contracts specifying antimicrobial film integration and metered-output precision. FDA 510(k) clearance and EMA MDR conformity documentation filter supplier pools aggressively.
- Clinics:Outpatient surgical centers and urology practices prioritize pre-sterilized single-use convenience over capital equipment investment. These facilities generate concentrated demand for leg bag and catheter bag configurations.
- Home Care:Patient-directed purchasing through durable medical equipment suppliers and digital pharmacy platforms is displacing traditional distributor relationships for spinal cord injury and multiple sclerosis cohorts.
- Long-term Care Facilities:Nursing homes and skilled nursing facilities in the United States and Japan are consolidating supplier relationships around vendors offering predictive replenishment algorithms tied to catheter change protocols.
Hospitals anchor procurement value; home care channels are climbing the fastest.
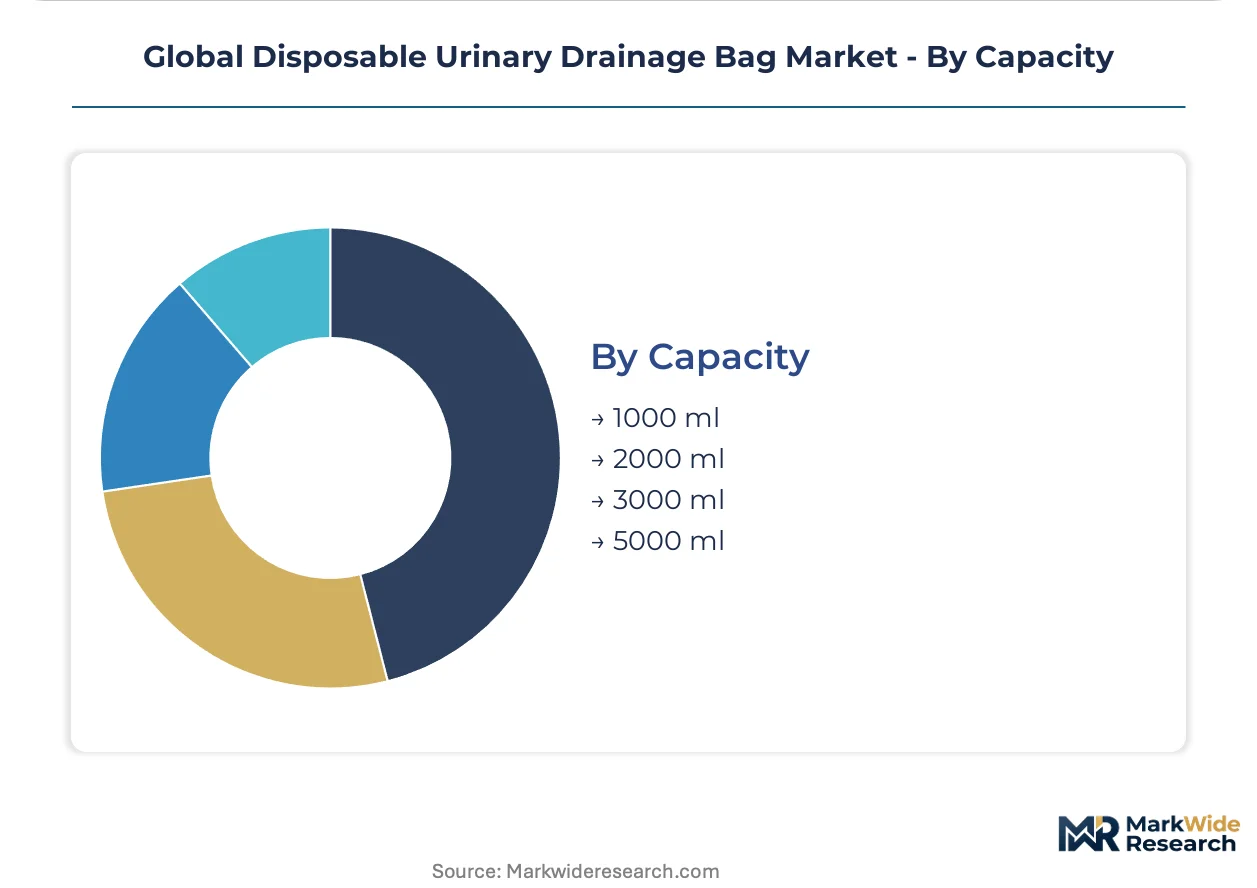
Capacity:
Volume specifications align with patient mobility status, drainage frequency, and clinical monitoring requirements.
- 1000 ml:Standard leg bag capacity balancing wearability with adequate reservoir volume for daytime ambulatory use. This specification dominates post-surgical discharge kits in Japanese home care markets.
- 2000 ml:Intermediate capacity serving overnight drainage and moderately mobile patients requiring extended collection intervals. German long-term care facilities specify 2000 ml systems for standard ward configurations.
- 3000 ml:High-capacity bed bag specification for ICU and step-down units where nursing staff access is limited. These systems integrate reinforced hanging straps and anti-kink tubing.
- 5000 ml:Maximum capacity systems for bariatric patients, extended anesthesia cases, and nephrology applications requiring substantial fluid collection without interruption. Metered-output chambers are standard at this capacity tier.
2000 ml configurations lead institutional procurement; 5000 ml systems are expanding most quickly in critical care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital procurement consolidation contrasts with Japan's home care channel migration, while the United States anchors institutional volume through integrated health system contracting. Regulatory divergence across these three markets filters supplier participation and elevates compliance costs for cross-border manufacturers.
United States
Hospital procurement consolidation and spinal cord injury patient cohorts drive leg bag demand through durable medical equipment channels. FDA 510(k) clearance requirements filter supplier pools aggressively, stretching antimicrobial claim approvals to 18-24 months. The Midwest and Southeast corridors concentrate sterilization infrastructure as ethylene oxide facility closures force gamma irradiation qualification.
Germany
University hospital infection control protocols specify silver-ion impregnated PVC layers for bed bag contracts, pulling premium pricing for compliant configurations. EMA MDR conformity assessments under REACH chemical substance restrictions constrain phthalate plasticizer formulations. The Rhine-Ruhr and Bavarian medical device clusters host compounders requalifying citrate-based alternatives under ECHA authorization timelines.
Japan
Post-surgical discharge protocols and aging demographics expand ambulatory leg bag replacement cycles outside hospital purchasing. METI reimbursement frameworks favor predictive replenishment algorithms tied to catheter change protocols. The Tokyo-Osaka corridor consolidates regional hospital alliances around system-wide vendor agreements displacing fragmented procurement.
China
Domestic urology device orders climb as polymer suppliers recalibrate resin allocation toward medical-grade PVC lines. NMPA biocompatibility documentation and MEE environmental enforcement on medical plastic waste processing constrain export-bound production flexibility. Yangtze River Delta converters face extended qualification timelines under tightening sterilization assurance standards.
India
CDSCO regulatory harmonization with ISO 10993 standards opens import pathways for sterile single-use systems previously blocked by local manufacturing mandates. Long-term care facility expansion in Maharashtra and Karnataka creates concentrated demand for economy-tier configurations. Central government procurement consolidation is compressing supplier margins while elevating volume commitment requirements.
Global Disposable Urinary Drainage Bag Market Vendor Landscape
North American producers anchor the premium-tier hospital contracting segment; Southeast Asian specialists hold economy-scale conversion capacity for developing market tenders. Market structure stratifies across three archetypes: integrated catheter-to-bag portfolio vendors, private-label scale distributors, and specialized hydrophilic-coated system manufacturers. Competitive positioning depends on backward integration into polymer compounding and captive sterilization infrastructure. M&A activity concentrates on antimicrobial film technology licensing and regional distribution network acquisition.
Among integrated portfolio vendors, C. R. Bard and Coloplast exemplify archetypes differentiated by geographic focus and coating specialization. Medline Industries occupies a position within the private-label scale tier, leveraging direct distribution infrastructure to long-term care facilities. Cardinal Health and ConvaTec sit within the hospital system contracting vector, where procurement consolidation demands bundled service specifications across leg bag, bed bag, and night drainage configurations.
| Leading Market Players |
|---|
| C. R. Bard |
| Amsino International |
| Medline Industries |
| Cardinal Health |
| Flexicare Medical |
| Coloplast |
| Cook Medical |
| ConvaTec |
| Covidien (Medtronic) |
| Others |
Supply Flow & Price Mechanics
Antimicrobial certification tiers bifurcate the disposable urinary drainage bag landscape into premium silver-ion or chlorhexidine-impregnated configurations and standard PVC alternatives, with this divergence manifesting in both hospital contract premiums and raw material qualification pathways across Chinese polymer suppliers and Southeast Asian converters.
Pricing Analysis
Distributor margins compress most acutely in the home care channel where digital pharmacy platforms bypass traditional durable medical equipment intermediaries. Three-tier pricing structure across premium antimicrobial, standard medical-grade, and economy non-certified levels separates German university hospital contracts from Japanese long-term care tenders from Indian central government procurement. Cost compression in the standard tier intensifies because REACH chemical substance restrictions force citrate-based plasticizer reformulation. Home care patients exhibit highest price sensitivity; ICU procurement committees prioritize infection control compliance over unit cost.
Supply Chain Analysis
FDA 510(k) and EMA MDR qualification gating concentrates sterile finished goods production in the United States, Germany, and Japan while component molding feeds from Chinese resin compounders and Malaysian silicone specialists. Medical-grade PVC resin, platinum-cured silicone elastomers, and antimicrobial film overlays constitute the critical input trinity. Single-source vulnerability in Southeast Asian contract manufacturing exposes the supply chain to MEE environmental enforcement actions on medical plastic waste processing. Distribution runs through hospital group purchasing organizations in North America and regional hospital alliances in the Tokyo-Osaka corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in disposable urinary drainage bags rests on antimicrobial film adoption pulling premium pricing and sterilization infrastructure consolidation capturing economies of scale.
For Market Incumbents: Lock in catheter-to-bag bundled contracts with predictive replenishment algorithms that tie leg bag replacement cycles to catheter change protocols. Backward integration into polymer compounding secures resin allocation priority as Chinese suppliers recalibrate toward medical-grade lines. Capacity expansion in gamma irradiation sterilization defends against ethylene oxide facility closures forcing modality switches. For New Entrants and Emerging Players: Direct-to-patient subscription platforms offer the lowest barrier entry point for spinal cord injury and multiple sclerosis cohorts bypassing distributor control. Target Indian long-term care facilities where CDSCO regulatory harmonization opens import pathways previously blocked by local manufacturing mandates. White-label manufacturing for private-label distributors accelerates volume scale without hospital system contracting infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where antimicrobial film technology licensing creates differentiation moats and sterilization infrastructure scarcity elevates asset values. Five-to-ten year viability favors manufacturers with captive gamma irradiation capacity and EMA MDR conformity documentation already complete. Watch FDA 510(k) clearance timelines for novel antimicrobial claims as inflection indicator for R&D pipeline capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Film Integration | Silver-ion or chlorhexidine-impregnated PVC layers command premium pricing in German infection control protocols. |
| Sterilization Infrastructure Qualification | Gamma irradiation capacity expansion captures volume displaced by ethylene oxide facility closures under EPA enforcement. |
| Direct-to-Patient Channel Development | Digital pharmacy platforms bypass durable medical equipment distributors for recurring leg bag deliveries to ambulatory cohorts. |
| Regulatory Conformity Documentation | EMA MDR biocompatibility dossiers filter marginal suppliers and elevate contract values for qualified manufacturers. |
| Predictive Replenishment Algorithm Deployment | Catheter change protocol integration locks in recurring revenue across leg bag, bed bag, and night drainage configurations. |
Methodological Framework
Multiple input streams — hospital procurement database analysis, GPO contract review, and regulatory filing examination — were reconciled with primary interviews across biomedical engineers, hospital purchasing committee members, GPO contracts managers, and urology clinicians. Secondary validation drew from FDA 510(k) clearances, EMA MDR conformity assessments, CMS Medicare reimbursement data, and hospital system annual procurement disclosures. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Historical volume trajectories were cross-referenced against expert panel input on antimicrobial adoption curves and sterilization modality shifts. Segmentation dimensions modeled include product architecture, material grade tier, end-user procurement authority, and capacity specification across acute and ambulatory channels. CAGRs were derived from regression analysis on replacement cycle frequencies and patient discharge protocol evolution. Raw material qualification timelines and regulatory approval cycle lengths fed directly into supply-side capacity assumptions.
Catheter-associated UTI liability rulings, ethylene oxide facility closure announcements, and REACH chemical substance restriction amendments are the dominant revision risks to base case assumptions. A model refresh is warranted upon material change in FDA antimicrobial claim documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Luer Plug Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Anti Venom Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Mexico Hospital Supplies Market
Medical Supplies
Cryotubes Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Microtome Knife Sharpeners Market