
 Global Sterilization Wrap Market | 2026-2036
Global Sterilization Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sterilization Wrap Market Foresight
Modular pouch configurations paired with reel-based dispensing systems is realigning how surgical centers and diagnostic laboratories manage sterile instrument workflows. Cardinal Health leverages its distribution network to sustain hospital supply chain integration across North America. Ahlstrom-Munksjo anchors its position through specialty nonwoven manufacturing scale in European medical packaging. DuPont de Nemours, Inc. differentiates via material science leadership in high-barrier polymer substrates for steam and gamma sterilization applications.
Sterilization wrap denotes breathable, porous barrier materials engineered to maintain sterility of surgical instruments and medical devices after terminal sterilization cycles, typically constructed from polypropylene, SMS fabric, or spunlace nonwovens with specified bacterial filtration efficiency and moisture vapor transmission rates. The material type dimension shows SMS fabric and polypropylene commanding the largest volume share due to their balance of cost and barrier performance, while spunlace alternatives are gaining traction in dental and veterinary settings where softer drape compatibility matters. The sterilization method dimension reflects steam as the dominant protocol in surgical centers, though gamma radiation is expanding fastest in diagnostic laboratories handling pre-packaged disposable instruments.
FDA enforces Class II medical device controls over sterilization wrap under 21 CFR requirements, while EPA regulates ethylene oxide sterilization emissions that directly constrain wrap compatibility with specific sterilization cycles. ISO 11607 standards govern sterile barrier system validation, creating compliance thresholds that filter out non-certified suppliers from hospital procurement lists. Stakeholders must monitor evolving EU MDR requirements and China's NMPA registration pathways, as these frameworks are tightening documentation demands for imported medical packaging materials.
Market Dynamics
Hospital consolidation and the shift toward same-day surgical procedures are compressing instrument turnover cycles, forcing sterilization wrap suppliers to engineer faster-cooling, higher-throughput barrier materials that withstand accelerated steam sterilization protocols without compromising bacterial filtration efficiency.
Growth Catalysts
- EPA Ethylene Oxide Emission Controls:Stricter EPA caps on EtO sterilization byproducts are driving demand for wraps compatible with alternative terminal sterilization methods, particularly steam and gamma radiation protocols in US surgical centers.
- Ambulatory Surgery Center Expansion:The proliferation of ASCs in the United States, Germany, and China is creating concentrated demand for compact, reel-based sterilization wrap systems that optimize limited sterile processing department footprints.
- SMS Fabric Technology Maturation:Advances in spunbond-meltblown-spunbond nonwoven manufacturing are delivering improved moisture vapor transmission rates at lower basis weights, reducing material consumption per sterilization cycle.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer price swings tied to naphtha cracking economics compress margins for nonwoven manufacturers serving medical packaging applications.
- Supply Concentration in Spunbond Equipment:Reicofil and Oerlikon Neumag dominate meltblown and spunbond line supply, creating equipment bottlenecks that constrain capacity expansion timelines for new market entrants.
- Gamma Radiation Infrastructure Gaps:Limited cobalt-60 sterilization facility availability outside major metropolitan clusters restricts adoption of gamma-compatible high-barrier polymer wraps in secondary surgical markets.
Strategic Opportunities
- India Hospital Infrastructure Buildout:Ayushman Bharat scheme expansion and private hospital construction in tier-2 cities create demand for cost-optimized sterilization wrap configurations compliant with CDSCO medical device packaging regulations.
- Veterinary Specialty Surgery Growth:Soft-tissue veterinary procedures in the United States and Western Europe are adopting spunlace sterilization wraps for instrument compatibility with delicate surgical drapes.
- EU MDR Documentation Services:Tightened sterile barrier system validation requirements under EU MDR Article 10 create adjacent revenue streams for wrap suppliers offering technical file compilation and biocompatibility testing support.
Industry Challenges
- ISO 11607 Validation Timeline Compression:Accelerated product development cycles in surgical instrument OEMs are squeezing the 12-18 month sterile barrier system validation windows that wrap suppliers must accommodate.
- Sterile Processing Technician Shortage:Limited supply of certified central service technicians in the United States and Germany is increasing error rates in wrap application, driving demand for foolproof dispensing system design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sterilization Wrap Market |
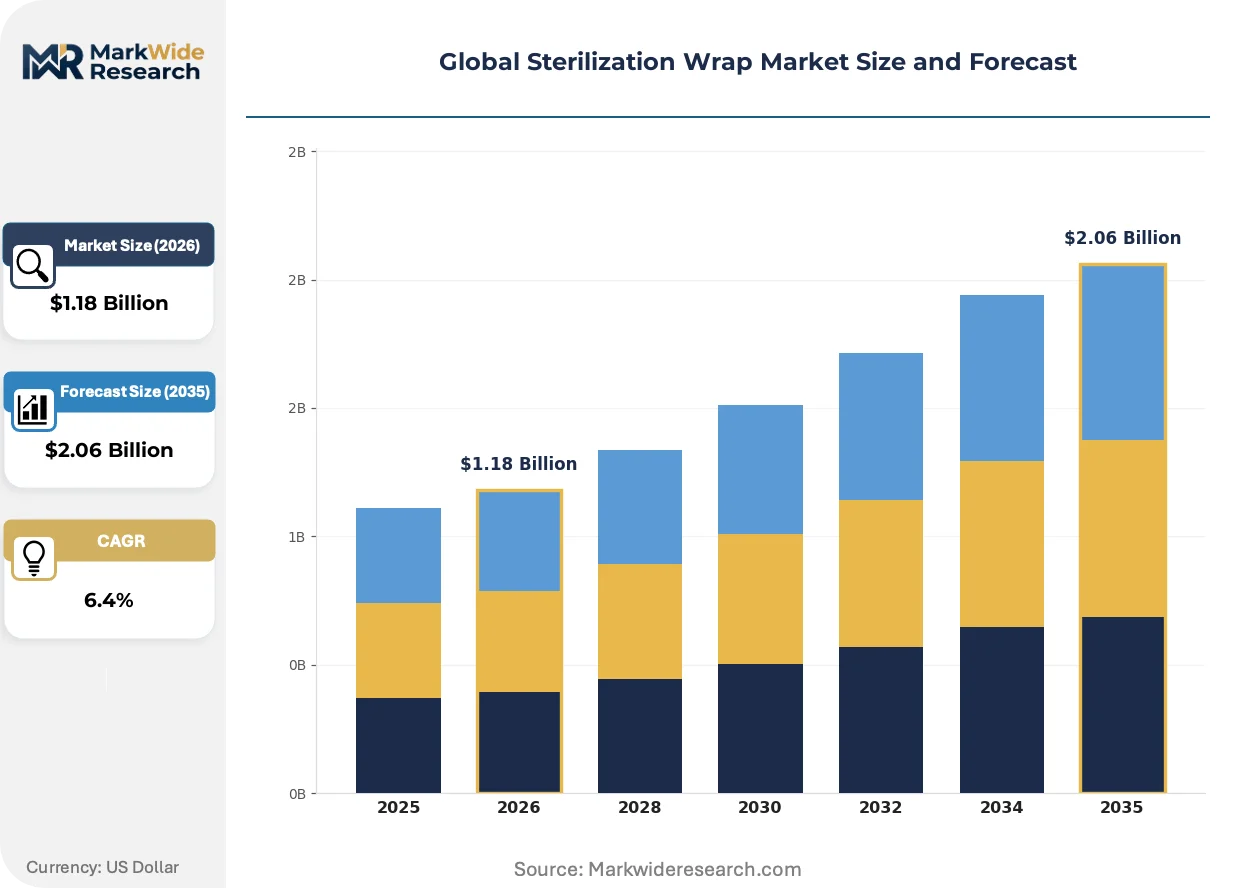
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyester, Spunlace, SMS Fabric, Cellulose, Polyethylene Sterilization Method: Steam, Ethylene Oxide, Gamma Radiation, Plasma, Formaldehyde End Use Facility: Surgical Centers, Diagnostic Laboratories, Dental Clinics, Veterinary Clinics, Research Institutes Packaging Format: Single Layer, Double Layer, Reel, Pouch, Roll Stock |
| Companies Covered | Owens & Minor, Ahlstrom-Munksjo, Cardinal Health, Medline Industries, LP, 3M Company, STERIS, Dynarex Corporation, DuPont de Nemours, Inc., Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sterilization Wrap Market Shifts & Advancements
Material science convergence with automated sterile processing workflows is redefining performance benchmarks for barrier materials, as hospitals prioritize throughput velocity and error reduction over incremental cost savings.
Antimicrobial-integrated SMS laminates are integrating silver-ion or copper-based additives directly into meltblown layers to deliver sustained surface bioburden reduction between sterilization and opening. Academic medical centers in the United States are piloting these materials in orthopedic and neurosurgical instrument sets where contamination tolerance approaches zero. The technology is integrating with RFID-enabled tracking systems that log wrap integrity throughout supply chain transit.
EU MDR Annex I general safety and performance requirements are mandating enhanced clinical evidence for sterile barrier systems, compelling wrap manufacturers to sponsor real-world usability studies in simulated surgical environments. German notified bodies are interpreting these provisions most stringently, rejecting technical files lacking human factors validation data. Diagnostic laboratories with pre-sterilized disposable instruments are absorbing the largest compliance cost increases as they retrofit packaging configurations to meet post-2021 certification thresholds.
Consolidated procurement through integrated delivery networks is displacing individual hospital purchasing autonomy in the United States, with IDNs standardizing on two to three wrap SKUs across 50-plus facility footprints. Cardinal Health and Owens & Minor are capturing these contracts through vendor-managed inventory programs that guarantee 48-hour replenishment. This concentration is most visible in the Southeast and Midwest IDN clusters where hospital system merger activity has accelerated since 2020.
Global Sterilization Wrap Market Segmentation
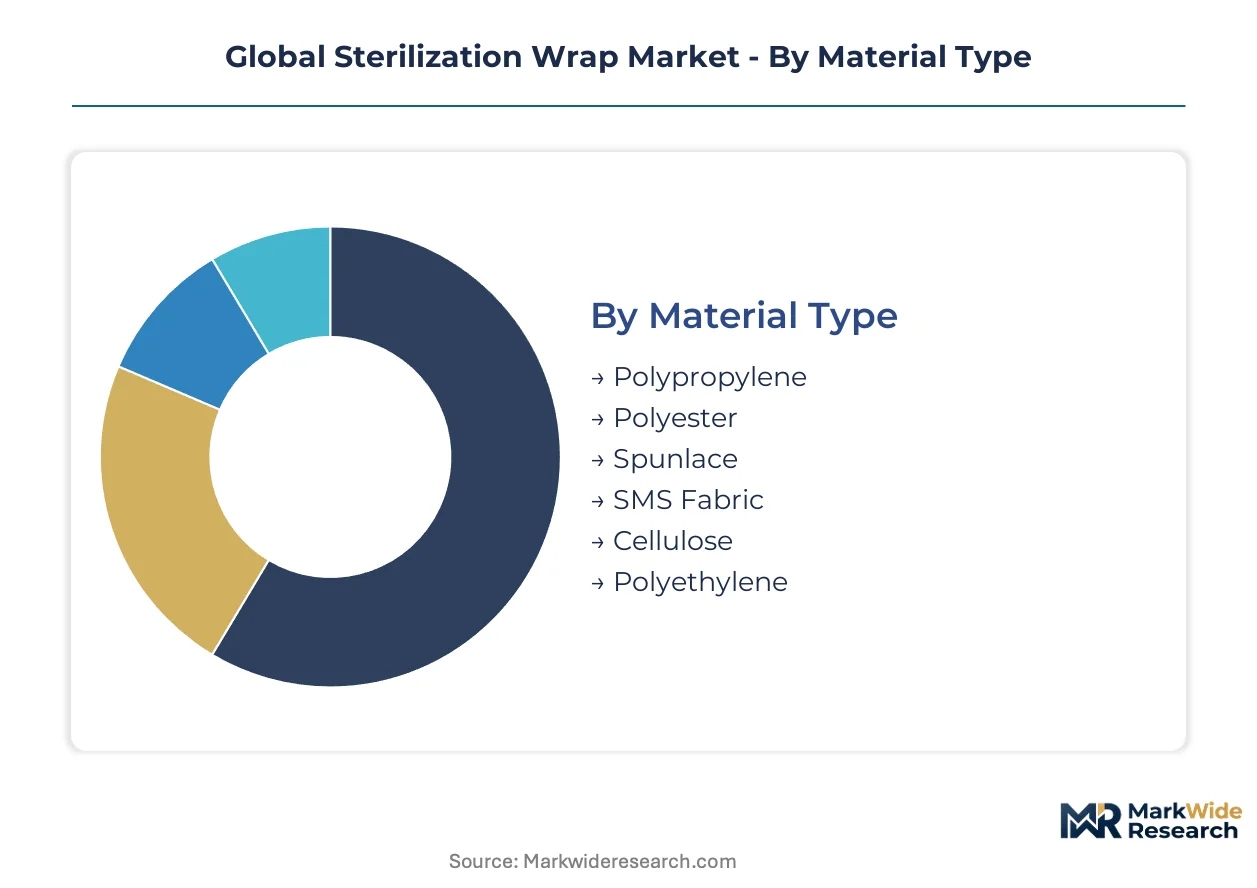
Sterilization wrap purchasing decisions cascade through material specifications, sterilization compatibility, facility workflows, and packaging automation requirements. Each dimension carries distinct capital commitments and regulatory validation burdens that shape supplier selection and procurement consolidation.
Material Type:
Spunbond-meltblown-spunbond lines demand the heaviest upfront investment, with Reicofil and Oerlikon Neumag equipment packages running into eight figures per production train.
- SMS Fabric:Spunbond-meltblown-spunbond laminates deliver calibrated bacterial filtration efficiency through layered density gradients. United States surgical centers specify SMS for high-throughput sterile processing departments where steam sterilization dominates and moisture vapor transmission rates determine throughput speed.
- Polypropylene:Spunbond nonwovens offer the most established supply base with proven steam and gamma compatibility. German hospital procurement networks standardize on polypropylene for instrument sets requiring validated sterile barrier systems under EU MDR compliance timelines.
- Spunlace:Hydroentangled cellulose-polyester blends provide softer drape compatibility for delicate instrument protection. Demand concentrates in United States and Western European veterinary soft-tissue surgery suites.
- Polyester:High-tenacity spunbond structures resist tearing during automated dispensing workflows. Research institutes specify polyester for reusable instrument cycles requiring extended durability.
- Cellulose:Crepe paper variants serve cost-sensitive applications with limited reuse requirements. Dental clinics in India and China deploy cellulose for single-use instrument protection under constrained sterile processing budgets.
- Polyethylene:Cast film substrates provide moisture barriers for ethylene oxide sterilization cycles with extended aeration requirements. Limited adoption outside specialized pharmaceutical packaging applications.
Most installed capacity flows through SMS Fabric. Expansion is steepest in Spunlace.
Sterilization Method:
Steam infrastructure saturates developed markets while gamma radiation requires cobalt-60 facility proximity that segments geographic adoption patterns.
- Steam:Saturated steam under pressure remains the dominant terminal sterilization protocol for reusable surgical instruments. United States ambulatory surgery centers specify steam-compatible wraps for same-day procedure turnover where cooling time directly impacts room utilization rates.
- Gamma Radiation:Cobalt-60 irradiation penetrates pre-packaged disposables without thermal stress. Diagnostic laboratories in the United States and Germany adopt gamma-compatible high-barrier polymers for molecular diagnostic consumables where sterility assurance levels must reach 10^-6.
- Ethylene Oxide:Low-temperature gas sterilization persists for heat-sensitive polymers and electronics. EPA emission caps in the United States are compressing EtO-compatible wrap demand as facilities convert to alternative methods.
- Plasma:Hydrogen peroxide vapor systems serve temperature-sensitive endoscopes and robotic instruments. Limited wrap compatibility due to material oxidation sensitivity constrains segment scale.
- Formaldehyde:Aldehyde-based low-temperature sterilization retains niche application in European pharmaceutical manufacturing. Regulatory scrutiny from ECHA is accelerating phase-out timelines.
Steam retains the largest installed base. Gamma radiation is climbing the fastest.
End Use Facility:
Surgical centers command premium pricing for validated sterile barrier systems while dental and veterinary segments prioritize cost optimization over documentation depth.
- Surgical Centers:Hospital sterile processing departments and ambulatory surgery centers drive specification authority for instrument wrap selection. United States integrated delivery networks consolidate procurement across 50-plus facility footprints, forcing suppliers into vendor-managed inventory arrangements with 48-hour replenishment guarantees.
- Diagnostic Laboratories:Pre-sterilized disposable instrument demand concentrates in molecular diagnostics and clinical chemistry workflows. EU MDR Annex I compliance costs are reshaping packaging configurations as German notified bodies demand human factors validation data.
- Dental Clinics:Smaller instrument sets and lower sterilization cycle volumes favor compact pouch formats. Cost pressure from reimbursement compression in United States dental markets is driving reel-based dispensing adoption.
- Veterinary Clinics:Soft-tissue and orthopedic procedures in companion animal practice are adopting spunlace wraps for drape compatibility. United States specialty veterinary hospitals represent the fastest-expanding demand cluster.
- Research Institutes:Animal research facilities and academic medical centers require documented sterile barrier validation for regulatory compliance. Protocol diversity forces suppliers to maintain broad SKU portfolios with limited volume per configuration.
Surgical Centers absorb the largest volume share. Veterinary Clinics are gaining share fastest.
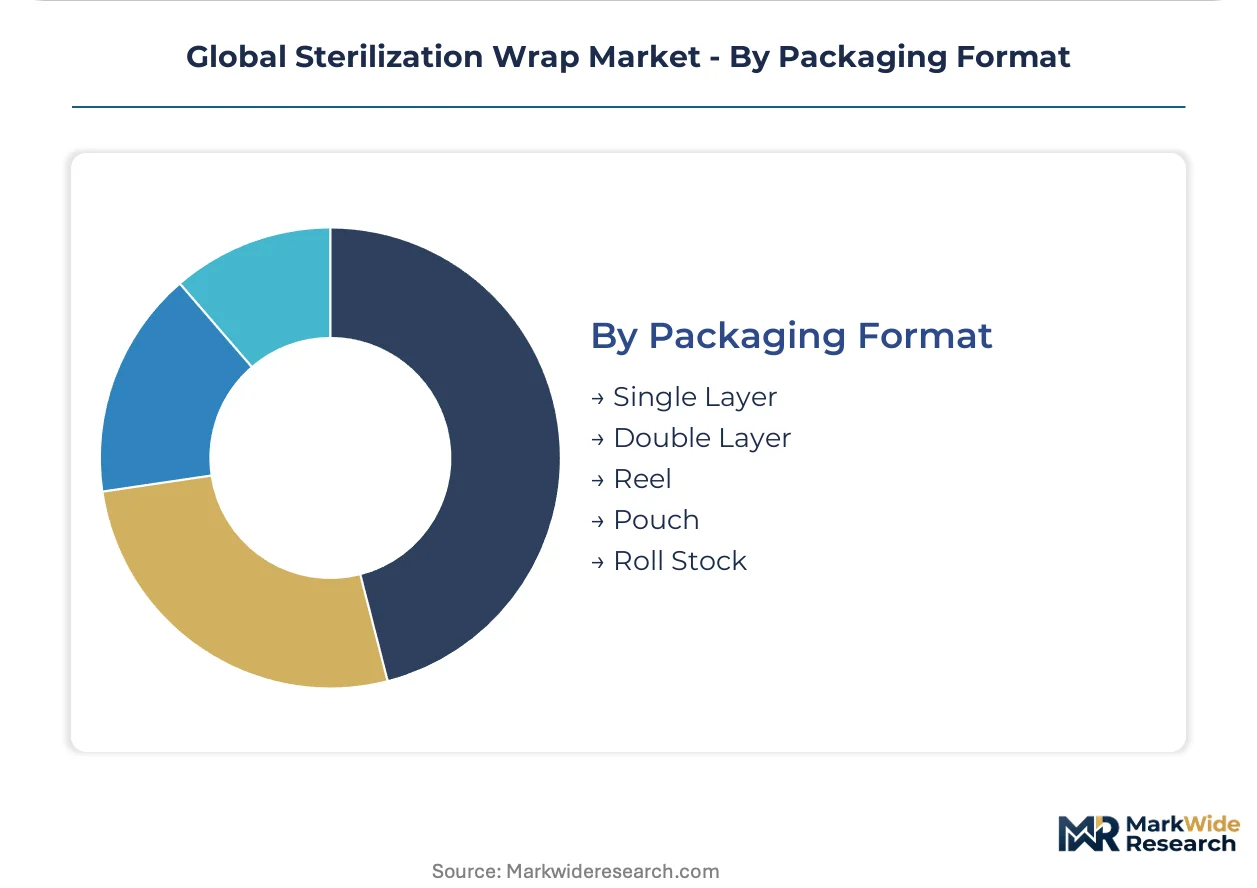
Packaging Format:
Automation readiness and sterile processing technician labor availability determine format selection across facility tiers.
- Reel:Continuous roll formats enable automated cutting and sealing systems that reduce technician handling time. United States hospital systems with certified central service technician shortages specify reel-based workflows to minimize application error rates.
- Pouch:Pre-formed configurations with self-sealing adhesive strips serve low-volume instrument sets and point-of-care sterilization. Dental clinics and veterinary practices favor pouches for workflow simplicity.
- Double Layer:Dual-wrap protocols provide redundant bacterial barrier protection for implantable devices and orthopedic instrument sets. Academic medical centers in the United States mandate double layer for neurosurgical and cardiovascular procedures.
- Single Layer:Standard wrap configurations serve routine instrument sets where contamination tolerance permits streamlined processing. Cost optimization in Indian and Chinese hospital construction projects favors single-layer specifications.
- Roll Stock:Unconverted material feeds in-house pouch fabrication or custom-sized wrap cutting. Research institutes and specialty device manufacturers maintain roll stock for protocol-specific packaging requirements.
Reel formats dominate new automation investments. Pouch configurations show the steepest expansion trajectory in outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sterilization wrap industry traces its commercial origins to mid-20th century United States textile innovation, where DuPont developed spunbond nonwoven technologies for surgical barrier applications. European specialty paper and nonwoven manufacturers subsequently scaled production through the 1970s-1980s, establishing the dual-continent supply architecture that persists today. Asian manufacturing integration accelerated after 2000 as hospital infrastructure buildouts created localized demand clusters.
United States
FDA Class II device controls under 21 CFR and EPA ethylene oxide emission caps are reshaping sterilization method preferences. Ambulatory surgery center proliferation across Texas, Florida, and the Southeast is concentrating demand for reel-based dispensing systems. The Mayo Clinic Rochester cluster and Cleveland Clinic network anchor specification authority for validated sterile barrier systems.
Germany
EU MDR Annex I general safety requirements and notified body interpretation in Berlin and Munich are extending sterile barrier system validation timelines. Baden-Württemberg's medical technology corridor around Tuttlingen hosts instrument OEMs that cascade wrap specifications through European procurement networks. North Rhine-Westphalia's integrated hospital systems are consolidating vendor-managed inventory contracts.
China
NMPA medical device packaging registration pathways and tier-2 city hospital construction under the 14th Five-Year Plan are expanding addressable demand. Yangtze River Delta manufacturing clusters around Shanghai are developing domestic SMS fabric capacity to reduce import dependency. Guangdong Province's private hospital chains are adopting international-standard sterilization protocols.
India
CDSCO medical device packaging regulations and Ayushman Bharat health scheme expansion are creating compliance thresholds for imported materials. Maharashtra's Mumbai-Pune hospital corridor represents the largest private healthcare construction pipeline. Gujarat's specialty chemical and nonwoven feedstock integration is attracting regional manufacturing investment.
Japan
METI industrial standards and PMDA quality system requirements maintain stringent barrier material specifications. Kansai region Osaka-Kobe medical device manufacturing clusters source validated wrap configurations for export-oriented instrument production. Aging demographics are expanding surgical volume in Tokyo metropolitan tertiary centers.
Global Sterilization Wrap Market Competitive Landscape
The competitive structure tilts toward diversified healthcare conglomerates with captive distribution networks. Three to five multinational suppliers command procurement specification authority through integrated delivery network contracts, while regional nonwoven specialists serve cost-optimized segments. Two strategic archetypes dominate: vertically integrated material science leaders controlling polymer substrate innovation, and distribution-anchored healthcare suppliers leveraging hospital supply chain integration. Competitive moves center on vendor-managed inventory program expansion and sterile barrier system validation service bundling.
Among diversified healthcare suppliers, Cardinal Health and Owens & Minor occupy positions defined by North American hospital supply chain penetration and IDN procurement consolidation. Ahlstrom-Munksjo represents the specialty nonwoven manufacturing archetype with European production scale. DuPont de Nemours, Inc. anchors the material science tier through polymer substrate leadership for high-barrier sterilization applications. These three companies exemplify the capability configurations—distribution density, manufacturing scale, and material innovation—that separate specification leaders from commodity suppliers.
| Leading Market Players |
|---|
| Owens & Minor |
| Ahlstrom-Munksjo |
| Cardinal Health |
| Medline Industries, LP |
| 3M Company |
| STERIS |
| Dynarex Corporation |
| DuPont de Nemours, Inc. |
| Berry Global Inc. |
| Others |
Supply & Pricing Matrix
Propylene monomer costs cascade through SMS fabric and polypropylene nonwoven manufacturing before stratifying into hospital procurement tiers. Naphtha cracking economics in Asian petrochemical hubs transmit volatility downstream, compressing margins for medical packaging converters serving cost-sensitive Indian and Chinese hospital construction projects.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated sterile barrier systems under FDA and EU MDR compliance from commodity cellulose wraps. Price differentiation hinges on ISO 11607 certification depth and vendor-managed inventory bundling. Cost compression in economy tiers intensifies because Indian and Chinese domestic manufacturers scale unbranded capacity. Dental clinics and tier-2 Chinese hospitals exhibit highest price sensitivity; United States academic medical centers show lowest.
Supply Chain Analysis
Regional distribution centers in Chicago, Rotterdam, and Shanghai anchor hub-and-spoke replenishment networks serving hospital systems with 48-hour delivery guarantees. Manufacturing concentrates in the United States, Germany, and China. Raw material flows draw from Saudi propylene crackers, Finnish pulp mills, and Yangtze River Delta chemical complexes. Single-source vulnerability in Reicofil and Oerlikon Neumag spunbond equipment constrains capacity expansion timelines. Distribution runs through integrated delivery network vendor-managed inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterilization wrap market represents a late-cycle quality story as United States integrated delivery networks consolidate procurement around validated sterile barrier systems with full regulatory documentation. Demand is shifting toward premium SMS fabric configurations with antimicrobial integration and RFID-enabled tracking.
For Market Incumbents: Deepen backward integration into polypropylene resin sourcing to buffer naphtha cracking volatility. Expand sterile barrier system validation service bundling to capture EU MDR compliance revenue streams. Defend against regional nonwoven specialists by locking multi-year vendor-managed inventory contracts with Southeast and Midwest IDN clusters.
For New Entrants and Emerging Players: Begin with veterinary specialty surgery segments in the United States where spunlace demand outpaces established supply. Target India's tier-2 city hospital construction under Ayushman Bharat with CDSCO-compliant cost-optimized configurations. Deploy reel-based dispensing system partnerships as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Consolidation pressure builds where sterile barrier system validation capabilities concentrate among fewer suppliers under tightening EU MDR and FDA documentation demands. The 5-10 year viability window favors material science-led platforms with captive polymer substrate innovation. Acquire specialty nonwoven manufacturers with SMS line capacity in European medical packaging corridors. Watch EPA ethylene oxide emission enforcement intensity as the signal for sterilization method shift timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Services | Captures adjacent revenue as German notified bodies demand human factors validation data. |
| Antimicrobial SMS Laminate Development | Integrates silver-ion additives for orthopedic instrument sets at Mayo Clinic and Cleveland Clinic networks. |
| Vendor-Managed Inventory Expansion | Locks 48-hour replenishment guarantees with United States integrated delivery networks. |
| India Manufacturing Footprint | Addresses Ayushman Bharat demand with CDSCO-compliant domestic production in Gujarat. |
| RFID-Enabled Tracking Integration | Logs wrap integrity through supply chain transit for academic medical center procurement. |
Research Methodology
Direct dialogue with sterile processing department managers, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EU MDR technical file databases, hospital procurement contract disclosures, and spunbond nonwoven trade flow data. Bottom-up and top-down triangulation cross-checked volume estimates against installed sterilization equipment base and surgical procedure throughput metrics.
Analytical lenses combined bottom-up facility-level demand aggregation with top-down healthcare expenditure allocation modeling across the projection horizon. Segmentation dimensions included material type, sterilization method compatibility, end-use facility tier, and packaging format automation readiness. CAGRs were derived from surgical procedure volume trajectories, ambulatory surgery center expansion rates, and regulatory compliance cost absorption curves.
Caveats apply where EPA ethylene oxide emission enforcement intensity, EU MDR notified body interpretation variance, or polypropylene feedstock price spikes could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Crutch Pads Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Compression Socks Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Sterile Container Market
Medical Supplies
Suture Tapes Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Face Mask Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Nitrile Gloves Market