
 Mobile Sterile Units Market | 2026-2036
Mobile Sterile Units Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Sterile Units Market Outlook
Market Context with Strategic Players
Germany is narrowing its engineering advantage in transportable container sterilization systems for NATO field deployments. Steris Corporation leverages integrated infection control platforms to sustain long-term service contracts with US Veterans Health Administration facilities. Getinge Group anchors its position through captive supply of steam sterilization modules purpose-built for mobile clinic configurations. Shinva Medical Instrument Co., Ltd. dominates domestic procurement channels for People's Liberation Army medical brigades while extending its distribution network across Belt and Road hospital infrastructure projects.
Technical Definition and Structural Segments
Mobile sterile units are self-contained decontamination and aseptic environment systems engineered for rapid deployment, typically incorporating HEPA filtration rated at 99.97% efficiency for 0.3-micron particles and ultraviolet-C irradiation chambers delivering 253.7-nanometer wavelength exposure. These units serve critical functions in infection control, patient isolation, and surgical readiness where fixed infrastructure is compromised, unavailable, or requires supplemental surge capacity. Modular units and transportable containers command the dominant share of current procurement budgets due to their compatibility with military logistics chains and disaster relief airlift protocols, while mobile clinics represent the fastest-expanding category as health systems invest in pandemic preparedness and rural access equity. Ultraviolet sterilization technology leads technology adoption in North American and European defense contracts, whereas thermal disinfection maintains strong positioning in emerging markets where capital constraints favor proven, lower-maintenance equipment platforms.
Regulatory Framework and Outlook
The FDA enforces 510(k) clearance pathways for mobile sterilization devices marketed to US healthcare facilities, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements on Class IIa and above decontamination equipment sold in Europe. China's NMPA aligns mobile medical device registration with GB standards for biosafety containment, creating divergent compliance burdens for manufacturers pursuing multi-jurisdictional certification. Stakeholders must monitor evolving MDR transition timelines and national stockpile replenishment cycles to calibrate production capacity and regional certification investments.
Market Dynamics
Defense health agencies and emergency response frameworks are consolidating procurement around containerized sterilization platforms that integrate HEPA filtration with ultraviolet-C irradiation, compressing supplier margins while elevating technical certification barriers for market entry.
Growth Catalysts
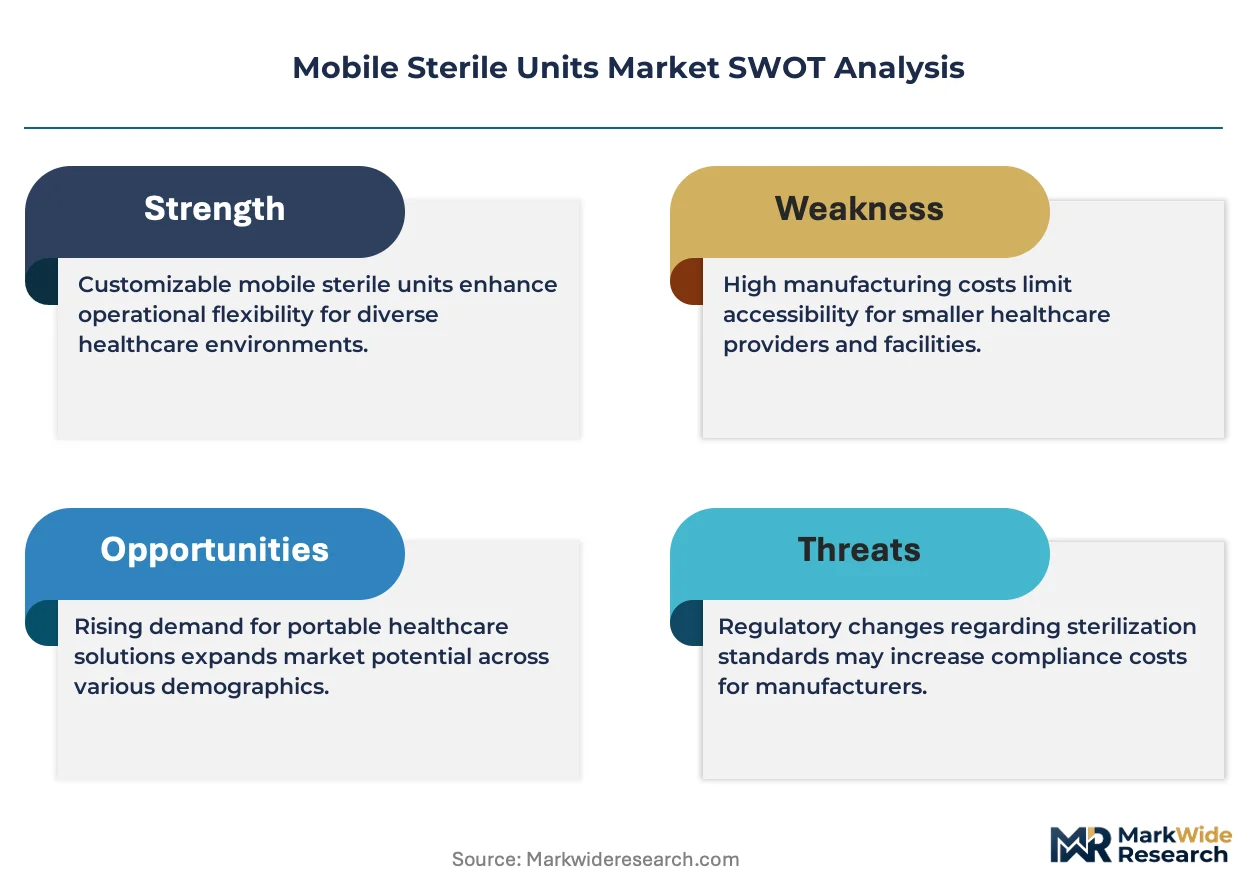
- EU MDR Compliance Deadlines:European defense procurement offices are accelerating replacement cycles for legacy chemical decontamination equipment ahead of stricter clinical evidence requirements for Class IIa sterilization devices.
- PLA Medical Brigade Modernization:China's military health service is field-testing transportable container systems for Belt and Road hospital infrastructure, creating pull-through demand for modular sterilization modules.
- Ultraviolet-C Chamber Adoption:NATO field medical units are specifying 253.7-nanometer wavelength exposure systems for surgical readiness in contested logistics environments.
Market Restraints
- Stainless Steel Input Volatility:Transportable container fabrication depends on austenitic steel grades subject to nickel price swings and Russian supply disruption.
- German Engineering Concentration:Precision filtration component supply clusters around Baden-Württemberg and Bavaria, creating single-source vulnerability for NATO-compatible systems.
- Thermal Disinfection Lock-in:Emerging market health ministries favor lower-capital steam sterilization platforms, slowing ultraviolet technology penetration in price-sensitive procurement channels.
Strategic Opportunities
- Rural Access Equity Mandates:US Veterans Health Administration facilities are expanding mobile clinic deployment to address geographic care gaps, opening service contract opportunities for integrated infection control platforms.
- GB Standard Alignment:China's NMPA is streamlining mobile medical device registration for biosafety containment systems, reducing certification friction for domestic manufacturers targeting Belt and Road projects.
- Drone-Deployable Miniaturization:Converging advances in solid-state ultraviolet emitters and lithium-ion power density are enabling backpack-scale sterilization units for special operations medical teams.
Industry Challenges
- 510(k) Evidence Generation:FDA clearance pathways for novel ultraviolet sterilization devices require extensive microbial lethality documentation, extending time-to-market for platform upgrades.
- Field Service Technician Scarcity:Military and disaster relief operators lack personnel trained to maintain HEPA filtration integrity and irradiation chamber calibration in austere conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Sterile Units Market |
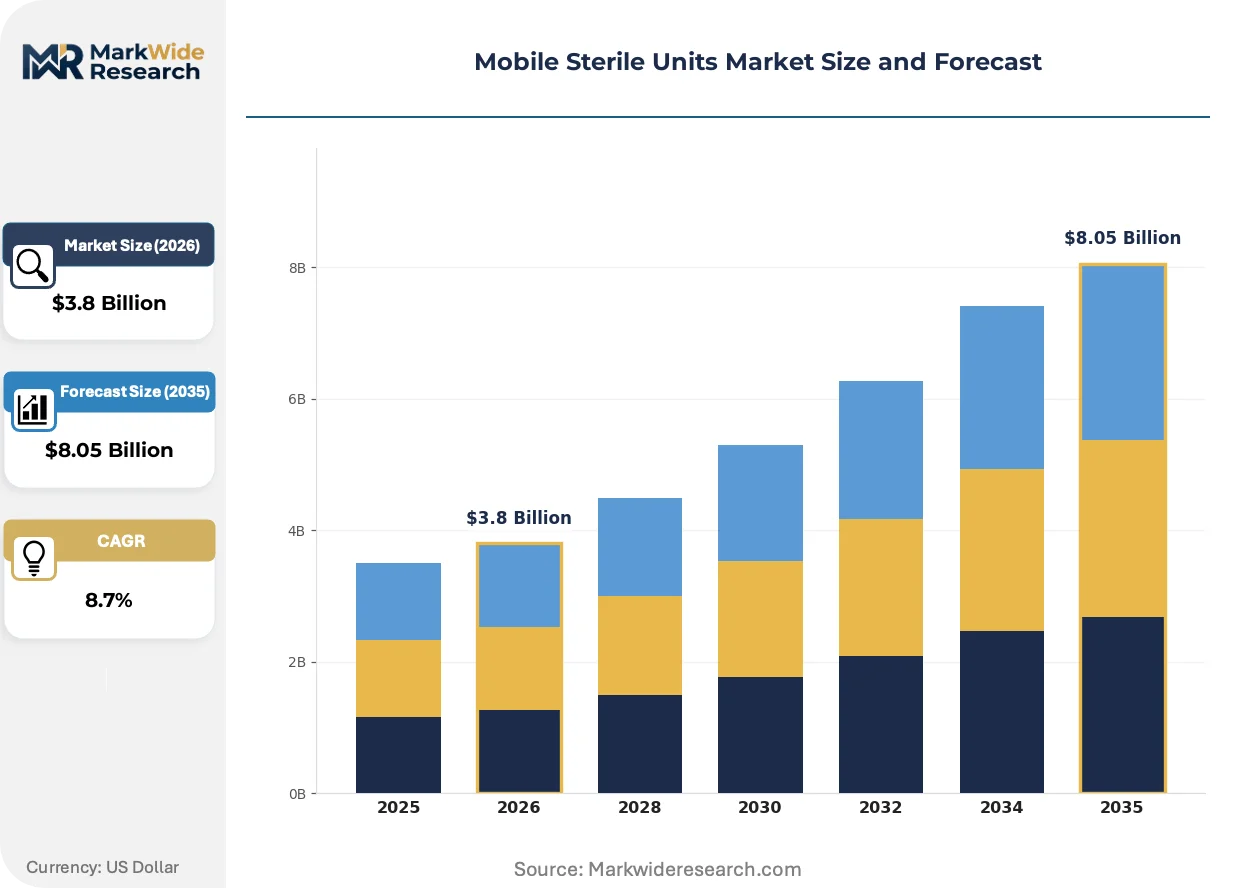
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Units, Transportable Containers, Mobile Clinics, Hygiene Stations Technology: Ultraviolet Sterilization, HEPA Filtration, Thermal Disinfection, Ozone Treatment End User: Healthcare Facilities, Emergency Services, Disaster Relief Organizations, Military Application: Infection Control, Patient Isolation, Medical Camps, Field Hospitals |
| Companies Covered | Steris Corporation, Getinge Group, Shinva Medical Instrument Co., Ltd., Belimed AG, Systec GmbH, Astell Scientific Ltd., Steelco S.p.A., Fedegari Autoclavi S.p.A., Tuttnauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Sterile Units Market Strategic Shifts
Ultraviolet-C and advanced filtration technologies are compressing the operational role of chemical-based decontamination while regulatory harmonization efforts fragment across defense and civilian health procurement channels.
Photocatalytic oxidation systems incorporating titanium dioxide-coated substrates and 365-nanometer LED arrays are achieving log-6 reduction rates for multidrug-resistant organisms. US Army Medical Research and Development Command is evaluating these platforms for forward surgical team deployment. Legacy hydrogen peroxide vapor systems are rendering obsolete in rapid-response scenarios where chemical residue detection threatens operational security.
China's NMPA is tightening GB standard alignment for mobile biosafety containment equipment, requiring domestic manufacturers to submit expanded clinical validation data for ultraviolet sterilization claims. This regulatory elevation is compressing supplier margins while advantaging state-backed champions with captive testing infrastructure. Belt and Road hospital projects are absorbing the compliance burden through bundled procurement with PLA medical brigade specifications.
Defense health agencies are unbundling equipment purchase from long-term service contracts, shifting vendor relationships toward availability-based performance metrics. Steris Corporation and Getinge Group are restructuring pricing to capture recurring revenue from filtration module replacement and irradiation lamp lifecycle management. This transition is most advanced in US Veterans Health Administration facilities, where total cost of ownership models now dominate capital committee evaluations.
Mobile Sterile Units Market Segmentation
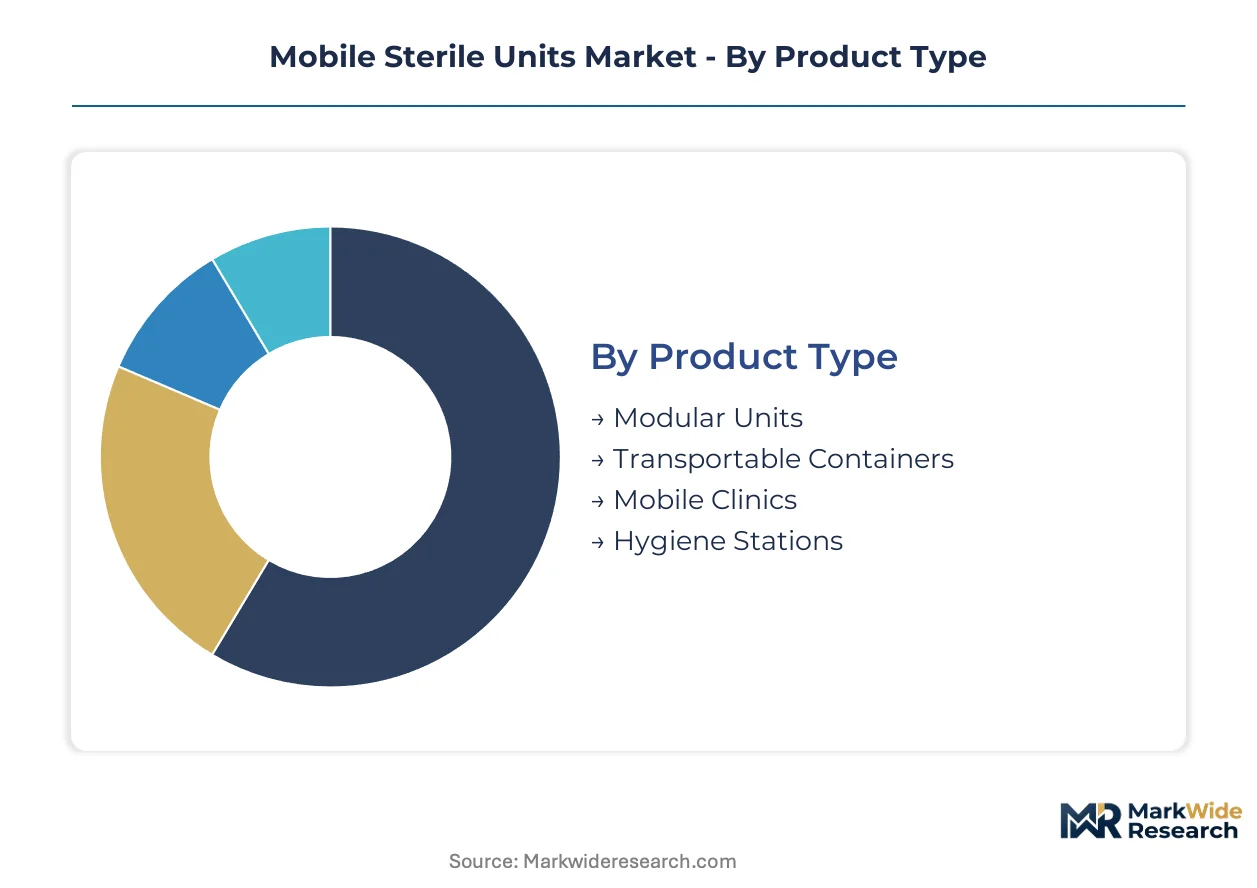
Mobile sterile units serve divergent operational requirements across defense logistics, civilian emergency response, and rural healthcare access. Segmentation reveals how procurement priorities shift between rapid deployability, sterilization throughput, and regulatory compliance across these use cases.
Product Type:
Procurement volume concentrates on platforms compatible with military airlift protocols and disaster relief supply chains.
- Modular Units:Interconnecting containerized components allow field hospitals to scale sterilization capacity incrementally. NATO defense health agencies in Germany and the United States specify these for surge deployment alongside fixed medical infrastructure.
- Transportable Containers:Self-contained 20-foot and 40-foot ISO-compliant units integrate HEPA filtration with ultraviolet-C chambers for standalone surgical readiness. China's PLA medical brigades field-test these for Belt and Road hospital infrastructure projects.
- Mobile Clinics:Vehicle-mounted configurations address rural access equity mandates from US Veterans Health Administration facilities.
- Hygiene Stations:Compact personnel decontamination pods serve entry control points at medical camps and field hospitals.
Established volume favors transportable containers; emerging adoption favors mobile clinics.
Technology:
Defense contracts are displacing legacy chemical methods with physical sterilization technologies that eliminate residue detection risks.
- Ultraviolet Sterilization:Solid-state 253.7-nanometer emitters achieve log-6 reduction rates without thermal load or chemical residue. US Army Medical Research and Development Command evaluates these for forward surgical team deployment in contested logistics environments.
- HEPA Filtration:99.97% efficiency at 0.3-micron particle retention underpins all NATO-compatible containerized systems. German precision filtration component supply clusters around Baden-Württemberg create single-source vulnerability for these specifications.
- Thermal Disinfection:Steam sterilization platforms maintain strong positioning in price-sensitive emerging market procurement channels.
- Ozone Treatment:Residual gas detection challenges limit adoption in operational security-sensitive military applications.
Defense procurement climbs fastest for ultraviolet sterilization; emerging market ministries favor thermal disinfection for capital efficiency.
End User:
Customer archetypes span institutional healthcare, sovereign defense apparatus, and humanitarian logistics operators with divergent certification requirements.
- Healthcare Facilities:US Veterans Health Administration and comparable national health services deploy mobile units for geographic care gap closure and pandemic surge capacity.
- Emergency Services:Municipal and regional response frameworks specify rapid-deployment sterilization for mass casualty incidents.
- Disaster Relief Organizations:International NGOs operating in conflict zones prioritize containerized platforms compatible with United Nations humanitarian airlift standards.
- Military:Defense health agencies consolidate procurement around availability-based performance metrics unbundling equipment from long-term service contracts.
Military procurement commands premium pricing; healthcare facility expansion drives volume scaling.
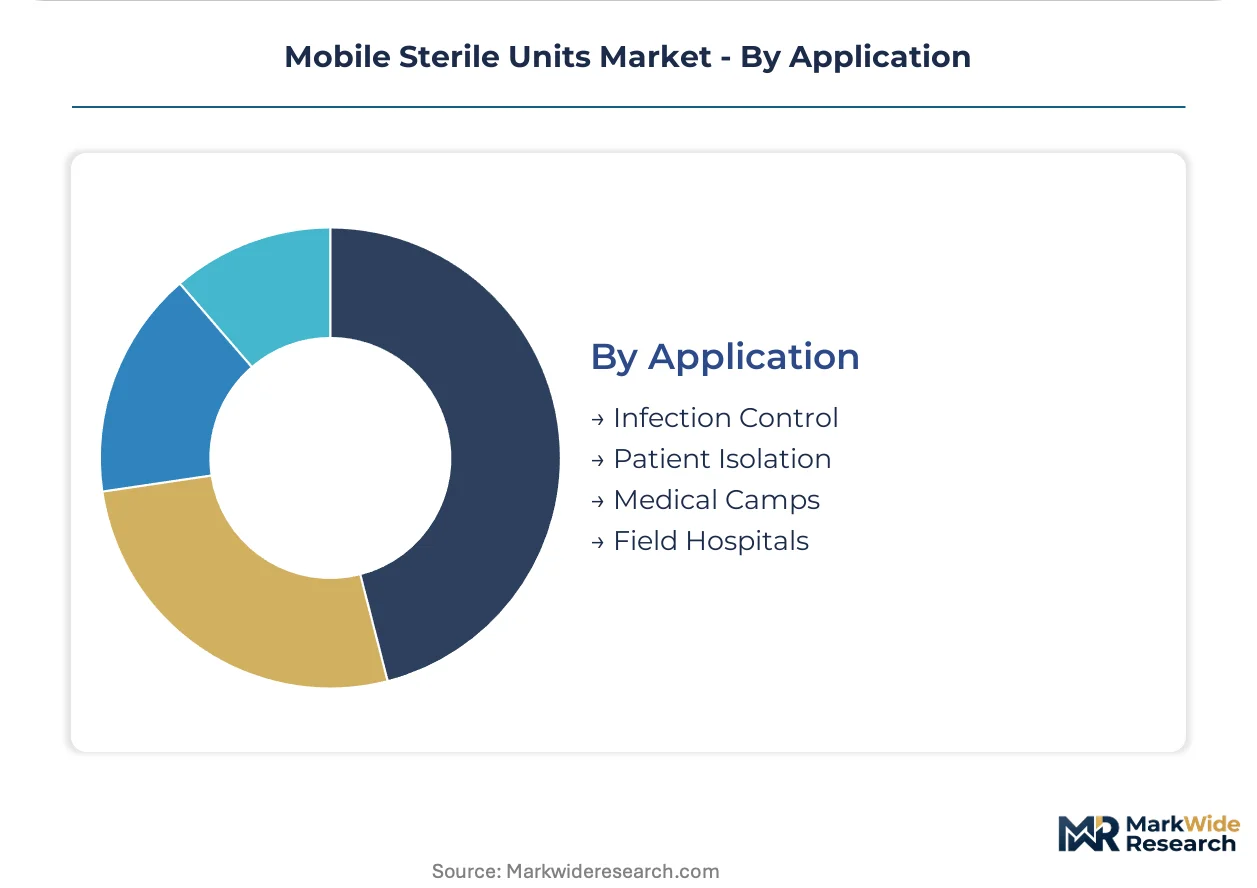
Application:
Functional deployment scenarios determine technical specifications for containment integrity, throughput capacity, and environmental resilience.
- Infection Control:Steris Corporation and Getinge Group capture recurring revenue from filtration module replacement and irradiation lamp lifecycle management in US healthcare facilities.
- Patient Isolation:Negative pressure configurations with HEPA exhaust filtration serve airborne pathogen containment requirements from China's NMPA GB standards.
- Medical Camps:Temporary installations in disaster-prone areas demand rapid assembly and minimal technical personnel for operation.
- Field Hospitals:Surgical readiness requirements in austere conditions drive specification of integrated sterilization-autoclave workflows.
Infection control absorbs mature service contract value; field hospital deployment commands highest unit specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense health agencies in the United States deploy transportable containers for field surgical readiness, while China's PLA medical brigades prioritize Belt and Road hospital infrastructure, and German engineering clusters supply precision filtration components to NATO-compatible systems.
United States
The Veterans Health Administration is expanding mobile clinic deployment to close geographic care gaps in rural areas. FDA 510(k) clearance pathways govern mobile sterilization devices marketed to domestic healthcare facilities. Ohio-based Steris Corporation anchors integrated infection control platforms through long-term service contracts with federal health agencies.
Germany
NATO defense procurement offices are accelerating replacement cycles for legacy chemical decontamination equipment ahead of stricter EU MDR compliance deadlines. The EU Medical Device Regulation imposes elevated clinical evidence requirements on Class IIa sterilization devices sold across Europe. Baden-Württemberg and Bavaria host precision filtration component supply clusters that create single-source vulnerability for NATO-compatible system specifications.
China
The People's Liberation Army medical service is field-testing transportable container systems for Belt and Road hospital infrastructure projects. The National Medical Products Administration aligns mobile medical device registration with GB standards for biosafety containment. Zibo-based Shinva Medical Instrument dominates domestic procurement channels while extending distribution networks across overseas hospital infrastructure.
Japan
Ministry of Defense health services are evaluating ultraviolet-C chamber systems for disaster response and pandemic surge capacity. The Ministry of Economy, Trade and Industry supports domestic manufacturers through technology development programs for medical device miniaturization. Kanto region industrial clusters concentrate advanced materials sourcing for solid-state ultraviolet emitter production.
United Kingdom
National Health Service trusts are procuring modular sterilization units for emergency surge capacity in mass casualty scenarios. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements for medical devices post-Brexit. Midlands-based engineering firms supply containerized platform fabrication for both domestic health services and export defense contracts.
Mobile Sterile Units Market Competitive Environment
Capability concentration sits with precision filtration and ultraviolet sterilization specialists; scale advantage sits with diversified infection control conglomerates. The market exhibits tiered structure with premium-tier integrated platform providers, mid-tier modular component fabricators, and emerging specialists in miniaturized field-deployable systems. Dominant competitive moves include backward integration into HEPA filtration membrane production and geographic expansion through Belt and Road infrastructure bundling.
Among diversified infection control conglomerates, Steris Corporation and Getinge Group exemplify the premium-tier archetype through integrated platform offerings and long-term service contract structures. Zibo-based Shinva Medical Instrument Co., Ltd. occupies a distinct position as a state-backed champion with captive testing infrastructure and dominant domestic procurement access. Precision sterilization specialists including Belimed AG and Systec GmbH represent the mid-tier engineering-focused segment concentrated in German-speaking Europe.
| Leading Market Players |
|---|
| Steris Corporation |
| Getinge Group |
| Shinva Medical Instrument Co., Ltd. |
| Belimed AG |
| Systec GmbH |
| Astell Scientific Ltd. |
| Steelco S.p.A. |
| Fedegari Autoclavi S.p.A. |
| Tuttnauer |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg and Bavaria precision filtration component clusters anchor NATO-compatible system specifications, concentrating margin capture downstream with integrated platform providers who bundle long-term service contracts with equipment deployment.
Pricing Analysis
Long-term availability-based service contracts dominate procurement structures for defense health agencies and Veterans Health Administration facilities, displacing transactional equipment sales. Price differentiation separates FDA 510(k)-cleared systems from EU MDR Class IIa-certified platforms, with certification tier and after-sales service bundling driving premium positioning. Pricing pressure stems from procurement offices unbundling equipment purchase from lifecycle service agreements, compressing upfront margins while elevating recurring revenue capture. Emerging market health ministries exhibit highest price sensitivity, favoring thermal disinfection platforms over ultraviolet-C systems for capital efficiency.
Supply Chain Analysis
Austenitic stainless steel feedstock draws from German, Chinese, and South Korean metallurgical suppliers, with nickel price volatility and Russian supply disruption creating input cost uncertainty. HEPA filtration membranes, solid-state ultraviolet emitters, and lithium-ion power modules constitute critical component dependencies. Single-source vulnerability concentrates in Baden-Württemberg precision filtration engineering clusters, threatening NATO field deployment readiness. Distribution runs through military logistics chains, UN humanitarian airlift protocols, and GPO contracts with federal health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of field service technicians trained to maintain HEPA integrity and irradiation chamber calibration in austere conditions constrains market expansion, privileging vendors with captive training infrastructure and remote diagnostic capabilities.
For Market Incumbents: Harden supply chain resilience by securing captive filtration membrane production or dual-source agreements with Bavaria engineering clusters to mitigate single-source exposure. Deepen backward integration into ultraviolet emitter manufacturing as solid-state technology displaces legacy lamp architectures. Priority defensive moves center on locking in Veterans Health Administration long-term service contracts before procurement offices complete their shift to availability-based metrics.
For New Entrants and Emerging Players: Rural healthcare access equity mandates in the United States represent the most penetrable white-space opportunity, with mobile clinic configurations underserved by incumbent platform providers. Target drone-deployable miniaturization for special operations medical teams as a technology-led entry vector. Go-to-market execution should emphasize software companion development for remote diagnostics, bypassing incumbent field service technician advantages.
For Investors and Strategic Acquirers: Capital is best deployed toward precision sterilization specialists with captive GB standard testing infrastructure and Belt and Road distribution access, as China's NMPA regulatory elevation compresses margins for non-compliant suppliers. Long-term viability across the projection horizon favors state-backed champions and diversified infection control conglomerates with recurring revenue contract structures. Signal to monitor: EU MDR transition timeline acceleration and national stockpile replenishment cycle announcements as demand inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HEPA Filtration Membrane Production | Secures supply continuity for NATO field hospital specifications while capturing margin pools from German engineering clusters. |
| CE Marking Pathway Acceleration for EU MDR Class IIa Devices | Unlocks defense procurement office replacement cycles ahead of stricter clinical evidence deadlines. |
| Hospital System Partnership with Veterans Health Administration | Locks in recurring revenue from filtration module replacement and irradiation lamp lifecycle management. |
| Software Companion Development for Remote Diagnostics | Addresses field service technician scarcity through predictive maintenance and calibration automation. |
| Geographic Expansion through Belt and Road Infrastructure Bundling | Leverages PLA medical brigade specifications to penetrate China's overseas hospital infrastructure pipeline. |
Study Parameters
The analysis maps transportable container systems, modular units, mobile clinics, and hygiene stations, each validated through defense procurement officers, biomedical engineers, hospital purchasing committees, and GPO contracts managers. Primary interview intelligence triangulates against FDA 510(k) filings, EU MDR submission databases, NMPA registration records, and NATO defense procurement disclosures. Secondary validation draws from customs trade data, SEC 10-K equipment revenue disclosures, and hospital procurement database extracts. Bottom-up unit deployment estimates reconcile with top-down defense health agency budget appropriations across the analysis window.
The assumption set holds EU MDR transition timelines, nickel price volatility bands, and PLA medical brigade modernization schedules within observed planning horizons. Segmentation dimensions modeled include product type configuration, sterilization technology architecture, end-user institutional category, and functional application scenario. CAGRs derive from logistic curve penetration modeling for ultraviolet-C adoption and replacement cycle analysis for legacy thermal disinfection platforms. Forecast inputs incorporate defense stockpile replenishment cycles and rural access equity mandate funding trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed manufacturers or accelerated EU MDR enforcement would shift outcomes meaningfully. Cross-checking against NATO defense procurement pipeline announcements and Veterans Health Administration mobile clinic deployment schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Global Laboratory Washers Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Orbital Shakers Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Pipettes and Accessories Market
Laboratory Equipment
Microplate Instrumentation and Supplies Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Global Pipettes and Pipettors Market