
 Prepackaged Medical Kits and Trays Market | 2026-2036
Prepackaged Medical Kits and Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Prepackaged Medical Kits and Trays Market Intelligence
Demand for prepackaged solutions from large-scale hospitals is rotating toward ambulatory surgery centers and specialty clinics seeking greater operational efficiency and inventory control. Cardinal Health leverages its extensive distribution network to serve this fragmented customer base. Medtronic Plc specializes in high-margin kits for specific cardiovascular and orthopedic procedures, while Owens & Minor competes on supply chain efficiency and customized kitting services for major health systems.
Prepackaged medical kits and trays are single-use, sterilized containers holding all necessary instruments, drapes, and consumables arranged for a specific medical procedure. These kits are sealed to maintain sterility until the point of use, with components often organized in procedural sequence. Surgical kits for orthopedic and cardiovascular procedures constitute the largest product category by value. Diagnostic kits and wound care kits, however, are seeing accelerated adoption within the rapidly expanding ambulatory surgery center and specialty clinic end-user segments.
Regulatory compliance is a critical barrier to entry, governed by bodies like the US Food and Drug Administration (FDA) and China's National Medical Products Administration (NMPA). The European Union's Medical Device Regulation (MDR) imposes stringent unique device identification (UDI) and traceability requirements, influencing kit design and supply chain logistics. Looking ahead, stakeholders must decide whether to prioritize investments in advanced sterilization technologies or focus on creating highly customized, procedure-specific kits to secure market position.
Market Dynamics
The market's central structural force is the rotation of procedural volume from large, centralized hospitals to smaller, more cost-conscious ambulatory surgery centers. This shift prioritizes operational efficiency, inventory control, and procedural standardization over bulk purchasing power.
Growth Catalysts
- Ambulatory Surgery Centers:The rapid expansion of specialty clinics and ambulatory surgery centers, particularly in North America, creates demand for kits that maximize procedural throughput and minimize setup time.
- EU MDR Compliance:The European Union's Medical Device Regulation (MDR) and its strict traceability mandates encourage the adoption of pre-certified kits, as they simplify compliance for healthcare providers.
- Healthcare Modernization in China:Significant government investment in upgrading China's healthcare infrastructure, coupled with a growing elderly demographic, is accelerating the adoption of single-use procedural solutions.
Market Restraints
- Component Cost Volatility:Fluctuation in the price of medical-grade polymers, specialty metals, and sterilization gases creates margin pressure for kit manufacturers, which can be difficult to pass on to customers.
- Regulatory Fragmentation:Divergent and evolving requirements from bodies like the US FDA, the EU's MDR, and China's NMPA increase the cost and complexity of achieving and maintaining market access across multiple regions.
- Preference for In-House Kitting:Some large hospital systems with established central sterile services departments (CSSDs) maintain a preference for assembling their own trays to control component selection and costs.
Strategic Opportunities
- Procedure-Specific Customization:Developing highly specialized kits for emerging, high-value procedures in fields like robotic surgery, interventional cardiology, or cell therapy offers a path to higher margins and customer loyalty.
- Emerging Market Penetration:Healthcare systems in Latin America and Southeast Asia represent significant growth opportunities as they modernize and adopt more stringent infection control standards.
- Smart Kit Integration:Incorporating RFID or NFC tags into kits enables automated inventory management, UDI tracking, and consumption analytics, offering a value-added service to healthcare providers.
Industry Challenges
- Supply Chain Complexity:Managing the procurement and sterilization of hundreds of individual components from diverse suppliers for a single kit presents a significant logistical challenge, vulnerable to disruption.
- SKU Proliferation:The demand for high levels of customization from individual surgeons and clinics leads to an explosion in the number of stock-keeping units (SKUs), complicating manufacturing and inventory management.
- Sterilization Compatibility:Ensuring a chosen sterilization method is effective for all components in a kit—from metal instruments to sensitive electronics and drapes—without degrading any material is a persistent technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prepackaged Medical Kits and Trays Market |
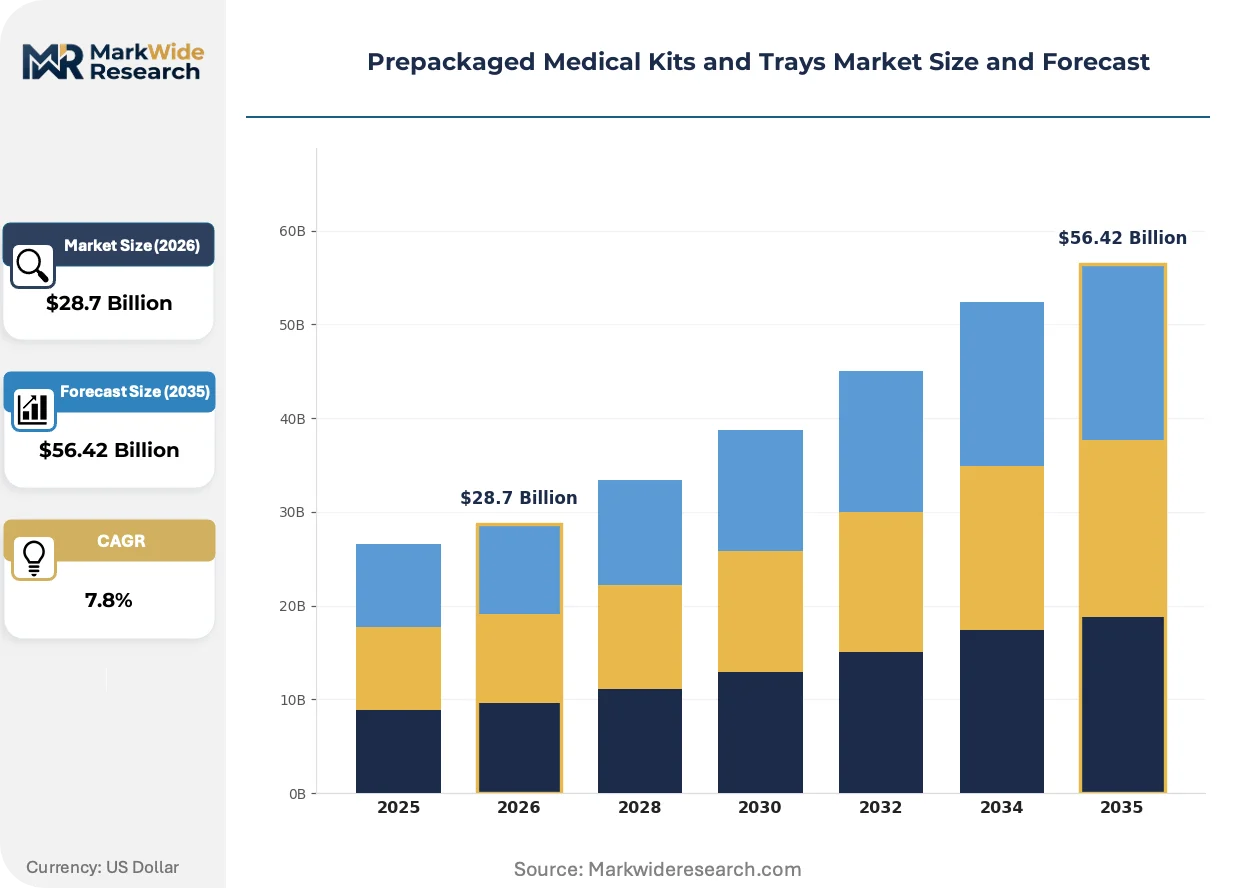
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $56.42 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Kits, Diagnostic Kits, Emergency Kits, Wound Care Kits, Dental Trays, Sterilization Trays Application: Orthopedic Surgery, Cardiovascular Procedures, General Surgery, Dental Care, Emergency Response, Veterinary Treatment End User: Hospitals, Ambulatory Surgery Centers, Dental Clinics, Veterinary Clinics, Emergency Medical Services, Specialty Clinics Distribution Channel: Direct Sales, Medical Distributors, E-Commerce Platforms, Wholesale Suppliers, Group Purchasing Organizations, Government Procurement |
| Companies Covered | Cardinal Health, Owens & Minor, Mölnlycke Health Care AB, Medtronic Plc, Medline Industries, LP, PAUL HARTMANN AG, STERIS, Boston Scientific Corporation, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prepackaged Medical Kits and Trays Market Strategic Shifts & Innovations
The convergence of demands for greater customization and stricter regulatory oversight is shaping product development. Manufacturers are innovating with new materials and integrated tracking technologies to meet the dual needs of clinical efficiency and supply chain transparency.
Advanced sterilization techniques that operate at lower temperatures are gaining traction for kits containing sensitive electronics or advanced polymers. Methods like vaporized hydrogen peroxide (VHP) are being adopted by manufacturers of specialized ophthalmic and endoscopic kits. This technology is displacing traditional ethylene oxide (EtO) sterilization in niche applications, mitigating risks associated with material degradation and regulatory scrutiny from bodies like the EPA.
Regulatory frameworks are becoming a primary design constraint, particularly the European Union's Medical Device Regulation (MDR). The MDR's mandate for Unique Device Identification (UDI) on all components forces a complete overhaul of supply chain logistics and data management systems. Kit assemblers and component suppliers are most affected, investing heavily in traceability software and automated labeling to ensure continued market access.
A notable behavioral shift involves the decentralization of purchasing decisions away from hospital-wide contracts. This move toward procedure-specific, just-in-time ordering by individual departments or ambulatory surgery centers disrupts traditional distribution models. This trend is most visible in the United States, where the growth of specialty clinics and ASCs fragments the customer base and rewards suppliers with flexible logistics.
Prepackaged Medical Kits and Trays Market Segmentation
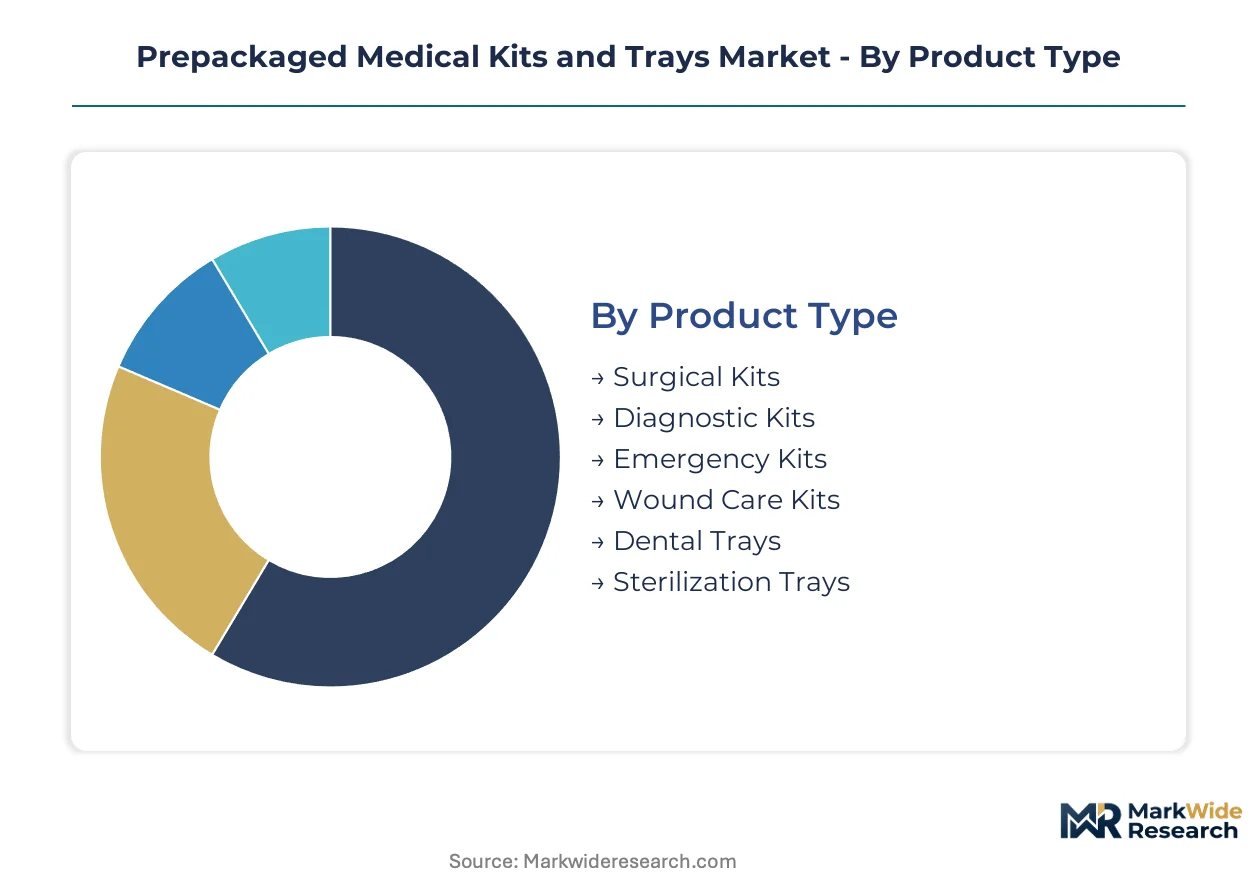
Segmentation within the prepackaged medical kits and trays market reveals distinct operational and regulatory influences. Analyzing these granular categories provides insights into evolving procurement strategies and specialized clinical demands. Understanding these segments helps manufacturers align product development with diverse end-user requirements.
Product Type:
Regulatory bodies like the US FDA and EU MDR significantly differentiate prepackaged medical kits based on product type, influencing design and compliance pathways.
- Surgical Kits:These kits contain instruments, drapes, and consumables arranged for specific surgical procedures, maintaining sterility until use. Demand concentrates in large hospitals and ambulatory surgery centers seeking procedural standardization and efficiency in the United States and Germany.
- Diagnostic Kits:These solutions package reagents, consumables, and collection devices for various diagnostic tests, crucial for rapid and accurate patient assessment. China's expanding healthcare infrastructure drives significant adoption, particularly for infectious disease screening and chronic condition monitoring.
- Emergency Kits:These pre-assembled sets provide essential supplies for immediate medical response in trauma or critical care situations.
- Wound Care Kits:These kits streamline the process of cleaning, dressing, and protecting wounds, supporting efficient patient recovery.
- Dental Trays:These trays organize instruments and materials required for specific dental procedures, enhancing clinic workflow.
- Sterilization Trays:Designed to hold instruments during sterilization cycles, these trays ensure items remain sterile until required for use.
Surgical Kits handles the majority of throughput; Diagnostic Kits is the fastest mover on share.
Application:
Application-specific kits highlight the diverse clinical needs driving product innovation and customization across various medical specialties.
- Orthopedic Surgery:These specialized kits support bone and joint procedures, containing implants, instruments, and drapes tailored for specific orthopedic interventions. Ambulatory surgery centers in the United States are increasingly utilizing these kits to optimize efficiency and reduce turnaround times for common procedures.
- Cardiovascular Procedures:Kits for cardiovascular interventions include catheters, guidewires, and specialized tools, ensuring sterile and organized access for complex heart and vascular surgeries. Demand for these high-value kits is strong in advanced healthcare systems like those in Germany and Japan, focusing on precision.
- General Surgery:These kits provide essential instruments and consumables for a broad range of common surgical operations.
- Dental Care:Kits for dental procedures streamline routine examinations, restorative work, and oral surgeries in dental clinics.
- Emergency Response:These pre-configured kits facilitate rapid and effective medical intervention during acute emergencies.
- Veterinary Treatment:Tailored kits support various animal healthcare procedures, improving efficiency in veterinary clinics.
Orthopedic Surgery applications command significant market value; Cardiovascular Procedures applications are experiencing rapid uptake in specialized centers.
End User:
End-user categories reflect distinct procurement behaviors and operational priorities influencing kit design and distribution logistics.
- Hospitals:Large hospitals utilize a broad spectrum of prepackaged kits for diverse surgical and diagnostic departments, often through centralized procurement systems. Procurement patterns in these facilities prioritize bulk purchasing and integration with existing supply chain management systems in countries like China and India.
- Ambulatory Surgery Centers:These centers favor kits that enhance procedural throughput and minimize setup time for outpatient procedures, driving demand for highly standardized solutions. Their growth in North America fragments the customer base, rewarding suppliers with flexible logistics and just-in-time delivery capabilities.
- Dental Clinics:These facilities rely on prepackaged kits for efficient organization of instruments and consumables for dental procedures.
- Veterinary Clinics:Veterinary practices increasingly adopt specialized kits to standardize animal treatment and improve procedural efficiency.
- Emergency Medical Services:EMS providers use pre-assembled kits for rapid, on-site medical interventions in emergency situations.
- Specialty Clinics:These focused healthcare providers seek customized kits tailored to their specific procedural requirements, optimizing their specialized services.
Hospitals remain a foundational end-user segment; Ambulatory Surgery Centers are driving significant market transformation and volume shifts.
Distribution Channel:
Distribution channels illustrate the varied routes to market for prepackaged medical kits, reflecting differing customer needs and logistical complexities.
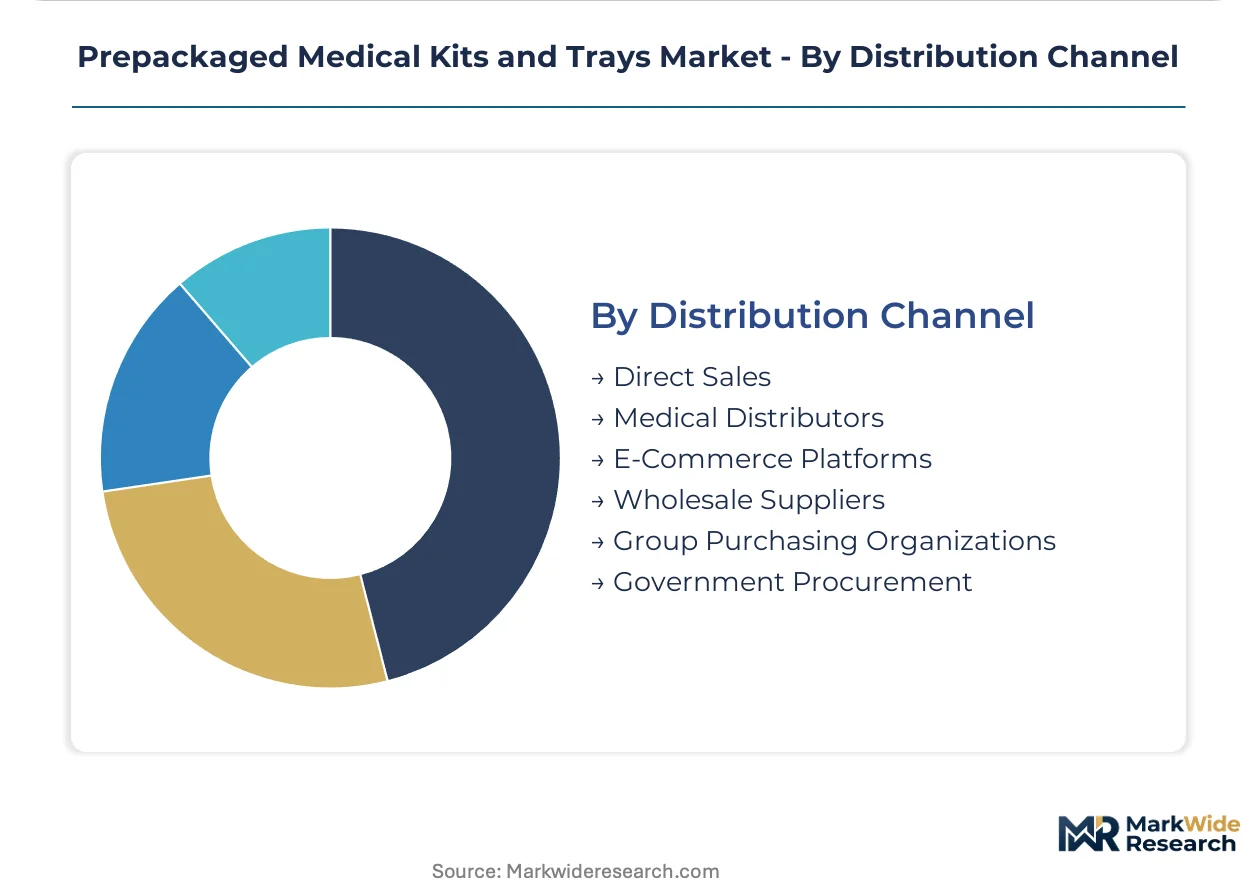
- Medical Distributors:These entities manage logistics and inventory for a wide range of medical products, serving a fragmented customer base from hospitals to specialty clinics. Distribution runs through these partners, particularly in regions like Europe and the United States, providing extensive market reach.
- Direct Sales:Manufacturers engage directly with large health systems or specialized clinics, offering customized solutions and closer technical support. This channel is critical for high-value, procedure-specific kits, especially for Medtronic Plc's offerings in cardiovascular and orthopedic procedures.
- E-Commerce Platforms:Online platforms offer convenience for smaller clinics and individual practitioners, streamlining procurement of standard kits.
- Wholesale Suppliers:These suppliers provide bulk quantities of kits to larger healthcare networks, often at competitive price points.
- Group Purchasing Organizations:GPOs negotiate favorable pricing and terms for their member healthcare providers, centralizing purchasing power.
- Government Procurement:Public health systems and military medical facilities acquire kits through structured tender processes and government contracts.
Medical Distributors facilitate broad market access; Direct Sales emphasizes tailored relationships and specialized product delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trade-flow corridor from European manufacturers to North American healthcare providers remains significant for prepackaged medical kits and trays. This global market sees diverse regional dynamics, driven by varying healthcare infrastructure, regulatory landscapes, and patient demographics. Demand for advanced procedural solutions shapes investment priorities across key geographies.
United States
Demand for prepackaged kits in the United States is driven by the expansion of ambulatory surgery centers and a focus on procedural standardization. The US Food and Drug Administration (FDA) mandates stringent quality and sterility requirements for all medical devices, including kits. Major medical device clusters in states like California and Massachusetts actively develop advanced kit components and sterilization technologies.
Germany
Germany's market for prepackaged medical kits is propelled by its advanced healthcare system and high surgical volumes, particularly in orthopedic and cardiovascular procedures. The European Union's Medical Device Regulation (MDR) imposes strict traceability and safety standards, influencing kit design and supply chain. The Rhine-Main region, with its strong medical technology presence, fosters innovation in kit customization and logistics.
China
China's market experiences robust demand from significant healthcare infrastructure modernization and an expanding elderly population requiring more medical interventions. The National Medical Products Administration (NMPA) is tightening regulations on imported and domestically produced medical devices, including kits. Healthcare hubs in cities like Shanghai and Beijing are centralizing procurement for large hospital systems, driving volume.
Japan
Japan's market prioritizes high-precision kits for complex cardiovascular and orthopedic surgeries, reflecting its aging population and advanced medical practices. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict oversight of medical device approvals and post-market surveillance. Tokyo and Osaka serve as key centers for medical device R&D and distribution, supporting specialized kit development.
India
India's market for prepackaged kits is growing due to rising healthcare expenditure and a push for better infection control in hospitals and clinics. The Central Drugs Standard Control Organization (CDSCO) is strengthening regulatory frameworks for medical devices, including manufacturing and import standards. Major metropolitan areas like Mumbai and Bangalore are witnessing increased adoption of kits to enhance surgical efficiency.
Prepackaged Medical Kits and Trays Market Key Industry Players
Player mix skews toward established medical device manufacturers and specialized kitting service providers in the prepackaged medical kits and trays market. The market exhibits a tiered structure, with large conglomerates offering broad portfolios and niche players focusing on high-value, procedure-specific solutions. Key competitive moves include strategic partnerships for distribution and continuous investment in supply chain efficiency to manage complexity.
Specialists in high-margin, procedure-specific kits include Medtronic Plc, which occupies a position focusing on cardiovascular and orthopedic applications. Cardinal Health represents a broad-portfolio archetype, leveraging its extensive distribution network to serve a fragmented customer base. Owens & Minor exemplifies a supply chain-centric approach, offering customized kitting services for major health systems and competing on operational efficiency.
| Leading Market Players |
|---|
| Cardinal Health |
| Owens & Minor |
| Mölnlycke Health Care AB |
| Medtronic Plc |
| Medline Industries, LP |
| PAUL HARTMANN AG |
| STERIS |
| Boston Scientific Corporation |
| Teleflex |
| Others |
Cost & Logistics Intelligence
Advanced sterilization techniques displacing traditional methods simultaneously reshape supply geography and pricing economics for prepackaged medical kits. This shift influences where components are sourced and how final kits are valued, particularly for sensitive electronics and advanced polymers.
Pricing Analysis
The technology-generation pricing gap differentiates commodity-like standard kits from highly specialized, next-generation solutions integrating smart features. Pricing stratifies across premium, standard, and economy tiers based on customization level and specific regulatory certifications like EU MDR compliance. Component cost volatility, especially for specialty metals and sterilization gases, exerts downward pressure on margins. Ambulatory surgery centers exhibit higher price sensitivity compared to large hospitals procuring high-value, complex cardiovascular kits.
Supply Chain Analysis
The preference for just-in-time ordering by ambulatory surgery centers contrasts with the need for strategic stockpiling of critical components by manufacturers. Supply concentration for medical-grade polymers and specialty metals draws from East Asia and Europe. Single-source vulnerability for advanced electronic components presents a structural supply chain risk. Distribution runs through medical distributors for broad market access, complemented by direct sales channels for high-value, customized kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prepackaged medical kits market is experiencing a cyclical recovery, driven by renewed global healthcare infrastructure investments and procedural decentralization.
For Market Incumbents: Fortify core market positions through strategic investments in advanced sterilization technologies like VHP, mitigating regulatory scrutiny from bodies like the EPA. Consolidate fragmented customer bases by leveraging extensive distribution networks, particularly in North America's expanding ambulatory surgery center segment. Invest in UDI compliance software to manage the complexity of EU MDR traceability requirements, turning regulatory burden into a competitive advantage.
For New Entrants and Emerging Players: Differentiate on procedure-specific customization for high-value, emerging fields such as robotic surgery or cell therapy. Target underpenetrated emerging markets in Latin America and Southeast Asia, where healthcare modernization and infection control standards are evolving. Develop smart kit integration capabilities, incorporating RFID or NFC tags, to offer value-added services like automated inventory management to specialty clinics.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized kitting service providers and advanced sterilization technology firms, offering attractive growth profiles. The long-term viability of this market hinges on continued healthcare decentralization and technological integration. An acquisition target archetype includes firms with robust UDI compliance solutions or strong intellectual property in new material compatibility for sterilization. Revision becomes warranted when adoption rates of smart kit technologies cross thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Sterilization Technology Adoption | Mitigates regulatory risks and allows for the inclusion of sensitive electronic components in kits. |
| UDI Compliance Software Integration | Ensures adherence to stringent traceability mandates from bodies like the EU MDR for market access. |
| Procedure-Specific Kit Development | Captures higher margins and fosters customer loyalty in specialized medical fields. |
| Emerging Market Expansion (LatAm/SEA) | Accesses new patient populations and growing healthcare infrastructure in modernizing regions. |
| Smart Kit (RFID/NFC) Implementation | Automates inventory management and provides valuable consumption analytics for healthcare providers. |
Research Approach
A spread of perspectives from hospital procurement managers, ambulatory surgery center administrators, medical device R&D leads, and regulatory compliance officers converged on the working assumptions. This approach combined primary interviews with industry stakeholders and secondary validation from sources such as FDA filings, EU MDR guidance documents, and NMPA regulations. Bottom-up market sizing was triangulated with top-down validation to ensure accuracy.
The analytical framework modeled segmentation dimensions including product type (surgical, diagnostic), application (orthopedic, cardiovascular), end-user (hospitals, ASCs), distribution channel (direct, distributors), and regional regulatory frameworks across the analysis window. Compound annual growth rates were derived from historical trends and projected growth drivers, incorporating inputs such as healthcare infrastructure investment levels and aging population demographics.
The analysis sits within stated boundaries; outcomes outside unforeseen global supply chain disruptions or significant shifts in regulatory mandates would require recalibration. Forecasts reflect assumptions documented through extensive research and expert consensus. Revision becomes warranted when major economic downturns affecting healthcare spending cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Sterile IV Containers Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Plasma Expanders Market