
 Global Hypodermic Needles Market | 2026-2036
Global Hypodermic Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hypodermic Needles Market Foresight
The capital-intensity divergence between automated safety-mechanism producers and conventional needle fabricators is unwinding competitive stability across the supply base. Becton, Dickinson and Company leverages vertically integrated polymer-to-needle manufacturing to dominate high-volume safety needle contracts. Terumo Corporation anchors its position through precision grinding technology leadership in ultra-thin gauge insulin delivery systems.
Hypodermic needles are hollow, beveled-tip stainless steel instruments designed to pierce skin and deliver or extract fluids through a syringe barrel, typically manufactured via cannula drawing, tip grinding, and electro-polishing processes to achieve burr-free surfaces and controlled bevel angles for minimal tissue trauma. Safety needles now command premium positioning as OSHA needlestick prevention regulations and EU MDR sharp-injury protocols mandate retractable or shielded designs across healthcare settings. Standard needles retain volume dominance in emerging clinical infrastructures where cost sensitivity overrides safety premium absorption, while butterfly needles occupy specialized margin pools in phlebotomy and pediatric vascular access where winged stabilization proves clinically essential.
FDA enforcement of the Needlestick Safety and Prevention Act shapes US demand by requiring engineered sharps injury protections in covered healthcare environments, while EMA MDR compliance and Japan's PMDA quality management standards govern market access across their respective jurisdictions. ISO 7864 and ISO 9626 standards further define dimensional and performance benchmarks that manufacturers must satisfy for cross-border commercialization. Stakeholders must monitor evolving national implementation timelines for sharps safety mandates to align product portfolio transitions with procurement cycle windows.
Market Dynamics
The hypodermic needles market is undergoing a fundamental reconfiguration as safety-engineered device mandates from OSHA and EMA MDR force accelerated replacement of conventional needle platforms across hospital systems, outpatient clinics, and home healthcare settings worldwide.
Growth Catalysts
- OSHA Needlestick Safety and Prevention Act:US healthcare facilities must deploy engineered sharps injury protections, driving systematic conversion to retractable and shielded needle designs in acute care environments.
- Diabetes management expansion:Rising insulin injection therapy volumes in Germany, Japan, and the United States are amplifying demand for ultra-thin gauge precision needles in chronic disease protocols.
- Polymer-to-needle integration:Advanced in-house manufacturing of safety mechanisms and cannula components is compressing production cycles and improving device reliability.
Market Restraints
- Stainless steel price volatility:Cannula-grade 304 and 316L steel input costs fluctuate with nickel and chromium commodity markets, squeezing margin structures for standard needle fabricators.
- EMA MDR compliance timelines:Extended technical documentation and clinical evaluation requirements for safety needle platforms are delaying product launches and freezing procurement decisions.
- Prefilled syringe substitution:Integrated drug-delivery systems with fixed needles are capturing share in vaccination and biologics administration, reducing standalone needle attach rates.
Strategic Opportunities
- Brazil ANVISA safety mandate preparation:Anticipated sharps injury prevention regulations will open conversion windows for safety needle suppliers ahead of formal compliance deadlines.
- Home healthcare channel expansion:Direct-to-patient distribution models for self-injection therapy are bypassing traditional hospital procurement, creating new margin pools for patient-centric packaging and disposal solutions.
- ISO 80369 small-bore connector convergence:Luer-lock standardization with enteral and neuraxial device protocols is enabling platform engineering across multiple delivery modalities.
Industry Challenges
- Precision grinding specialist scarcity:Ultra-thin gauge needle production requires skilled technicians operating CNC grinding equipment, with talent pipelines failing to match capacity expansion needs.
- Legacy sterilization validation:Ethylene oxide and gamma sterilization facility upgrades demand substantial capital outlays, particularly for mid-scale manufacturers seeking EMA MDR and FDA dual certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hypodermic Needles Market |
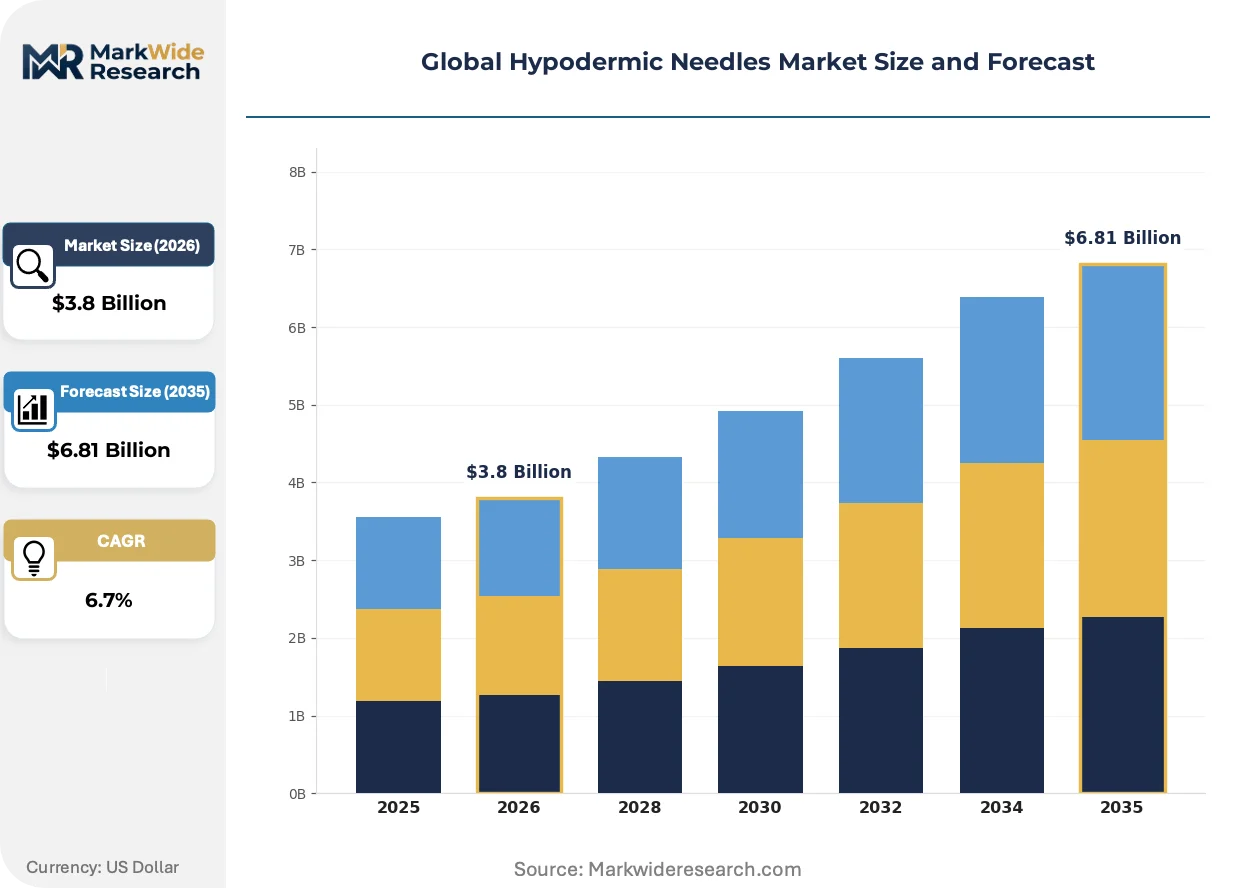
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Needles, Safety Needles, Insulin Needles, Spinal Needles, Butterfly Needles Application: Diabetes Management, Vaccination, Blood Sampling, Anesthesia Administration, Intravenous Therapy End User: Hospitals, Clinics, Diagnostic Laboratories, Ambulatory Care Centers, Nursing Homes Technology: Sterilization Methods, Needle Coating, Needle Gauge, Bevel Design, Safety Mechanisms |
| Companies Covered | Becton, Dickinson and Company (BD), Terumo Corporation, B. Braun Melsungen AG, Nipro Corporation, Cardinal Health Inc., Medline Industries LP, Retractable Technologies Inc., Smiths Medical Inc., ICU Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hypodermic Needles Market Shifts & Advancements
Active needle design evolution is compressing the competitive window between premium safety platforms and conventional offerings, with manufacturing technology and procurement behavior shifting in parallel across developed and emerging healthcare systems.
Passive safety needle mechanisms are displacing active user-activated designs in high-volume hospital contracts. These devices deploy automatic shielding upon needle withdrawal without clinician intervention, reducing training burden and compliance failure rates. Major US health systems and German hospital procurement consortiums are specifying passive platforms in tender documents, forcing active-mechanism suppliers to defend position through price concessions or dual-mode hybrid engineering.
EMA MDR Article 10 clinical evidence requirements are reshaping product development resource allocation for safety needle manufacturers. Technical documentation must now include systematic risk-benefit analysis and post-market surveillance planning, extending time-to-market by 12-18 months for novel designs. Japanese PMDA quality management standards are converging toward similar rigor, prompting multinational suppliers to harmonize submission dossiers across FDA, EMA, and PMDA jurisdictions.
Hospital procurement consortiums are consolidating supplier relationships through multi-year safety needle framework agreements that bundle volume commitments with technical service provisions. These arrangements displace spot purchasing and distributor-mediated transactions, concentrating award decisions among vertically integrated manufacturers capable of offering training, disposal logistics, and compliance reporting. The United Kingdom's NHS Supply Chain and France's RESAH are deploying this model most aggressively, with German university hospital networks following suit.
Global Hypodermic Needles Market Segmentation
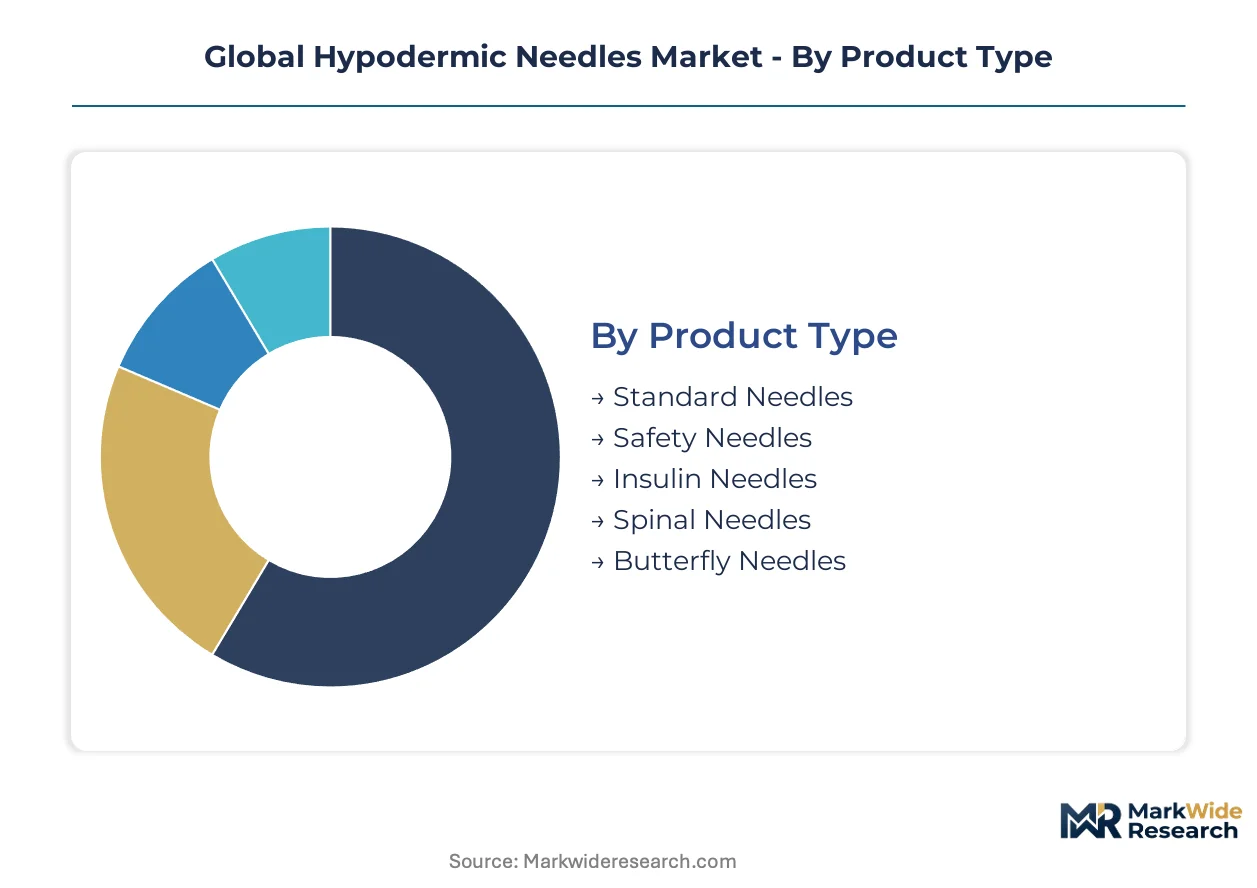
Hypodermic needle procurement patterns diverge sharply across product categories, with regulatory mandates and clinical workflow requirements dicting portfolio composition. Each segmentation dimension reveals distinct margin structures and competitive dynamics that suppliers must navigate.
Product Type:
FDA and EMA safety-engineered device mandates have fragmented the competitive landscape between legacy standard platforms and premium retractable designs.
- Safety Needles:Retractable and shielded mechanisms deploy automatic needle withdrawal or protective barriers post-injection to eliminate clinician exposure. Demand concentrates in United States hospital systems where OSHA enforcement drives systematic conversion from conventional platforms.
- Standard Needles:Fixed stainless steel cannulas with luer-lock compatibility remain the lowest-cost option for high-volume immunization campaigns and emerging market procurement where cost sensitivity overrides safety premiums.
- Insulin Needles:Ultra-thin gauge designs with short bevel angles minimize subcutaneous tissue trauma for frequent self-injection regimens.
- Butterfly Needles:Winged stabilization platforms with flexible tubing optimize vascular access precision in phlebotomy and pediatric applications.
- Spinal Needles:Pencil-point or cutting-tip configurations engineered for dural puncture with reduced post-dural puncture headache incidence.
Safety needles handle the majority of throughput in regulated healthcare systems; insulin needles are expanding most quickly on share as diabetes prevalence climbs across developed economies.
Application:
Clinical protocol standardization and patient volume intensity determine procurement scale and specification requirements across therapeutic categories.
- Diabetes Management:Daily insulin injection regimens drive the highest per-patient needle consumption rates globally. Japan and Germany maintain the steepest per-capita demand curves for ultra-thin gauge precision platforms.
- Vaccination:Mass immunization campaigns and routine pediatric schedules generate seasonal volume spikes with intense price competition. United States federal stockpiling contracts and WHO prequalification programs dominate procurement channels.
- Blood Sampling:Diagnostic laboratory throughput demands high-velocity venipuncture with minimal hemolysis risk.
- Anesthesia Administration:Regional block procedures require specialized bevel geometries and hub designs for nerve proximity detection.
- Intravenous Therapy:Infusion initiation and maintenance protocols utilize standard or safety configurations depending on institutional policy.
Diabetes management generates the steepest volume trajectory; vaccination commands the largest absolute procurement tonnage during pandemic response windows.
End User:
Capital availability and regulatory exposure create distinct purchasing behaviors across care delivery settings.
- Hospitals:Integrated delivery networks with consolidated procurement functions leverage multi-year framework agreements for safety needle platforms. United States health systems and German university hospital networks are standardizing on passive safety mechanisms.
- Clinics:Outpatient facilities balance cost constraints with OSHA compliance requirements through mixed standard-safety portfolios.
- Diagnostic Laboratories:High-throughput phlebotomy operations prioritize speed and patient throughput over safety premium absorption.
- Ambulatory Care Centers:Same-day surgical and infusion services require specialized access devices with rapid turnaround compatibility.
- Nursing Homes:Long-term care settings with variable staff training levels favor intuitive safety designs with minimal activation steps.
Hospitals absorb the dominant procurement volume; ambulatory care centers are climbing the fastest as surgical migration accelerates.
Technology:
Manufacturing process control and material science differentiation determine performance tier placement and pricing power.
- Safety Mechanisms:Passive automatic shielding systems are displacing active user-activated designs in high-volume contracts. German hospital procurement consortiums and United Kingdom NHS Supply Chain specifications now mandate passive platforms.
- Needle Gauge:Ultra-thin wall technology enables larger internal diameters at equivalent outer dimensions for reduced patient discomfort.
- Sterilization Methods:Ethylene oxide and gamma irradiation validation protocols govern market access under EMA MDR and FDA quality system requirements.
- Needle Coating:Silicone and polymer lubricant layers reduce insertion force and tissue drag.
- Bevel Design:Lancet, short, and intradermal tip geometries match specific tissue penetration requirements.
Safety mechanisms command the premium pricing tier; needle gauge optimization is gaining share fastest as patient-centric design priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for hypodermic needles diverge sharply across major healthcare systems. The United States prioritizes safety-engineered devices under OSHA mandates, while Germany and Japan emphasize precision manufacturing for chronic disease management, and emerging markets balance cost constraints with gradual regulatory convergence.
United States
Hospital procurement consortiums and federal stockpiling programs drive the highest absolute needle consumption volumes globally. OSHA enforcement of the Needlestick Safety and Prevention Act mandates engineered sharps injury protections across covered healthcare environments. New Jersey and North Carolina host concentrated manufacturing clusters where safety mechanism assembly integrates with polymer hub production.
Germany
University hospital networks and outpatient diabetes clinics sustain Europe's steepest per-capita injection therapy rates. EMA MDR compliance timelines and BfArM quality surveillance govern market access for safety needle platforms. Baden-Württemberg's precision engineering corridor houses specialized grinding equipment manufacturers serving ultra-thin gauge insulin needle fabricators.
Japan
Aging demographics and universal health coverage amplify demand for patient-centric injection devices in chronic disease protocols. PMDA quality management standards and JIS dimensional specifications regulate domestic commercialization and export certification. Tokyo-Osaka pharmaceutical corridors concentrate R&D partnerships between device manufacturers and biologics developers.
Brazil
Expanding immunization campaigns and private hospital network growth are elevating procurement volumes ahead of anticipated ANVISA safety mandates. Federal Ministry of Health tender programs dominate public sector acquisition channels. São Paulo's medical device distribution hub channels imports from North American and European suppliers to Southeast Asian clinics.
India
Massive vaccination infrastructure and rising diabetes prevalence generate volume demand across public health programs and private specialty clinics. CDSCO medical device rules and state-level procurement centralization are gradually elevating quality standards. Gujarat and Karnataka host emerging domestic fabrication clusters serving regional hospital networks with cost-optimized standard needle platforms.
Global Hypodermic Needles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the hypodermic needles supply base. Vertically diversified manufacturers with captive polymer compounding and precision grinding capabilities command premium positioning in safety needle contracts. Mid-scale fabricators concentrate on standard platforms for emerging market tenders. Competitive dynamics center on multi-year framework agreements with hospital procurement consortiums and accelerated M&A to secure sterilization validation capabilities.
Within the integrated manufacturing tier, Becton, Dickinson and Company and Terumo Corporation exemplify archetypes of polymer-to-needle vertical control. B. Braun Melsungen AG occupies a position bridging European hospital system relationships with precision device engineering. These three entities represent the dominant competitive anchors across safety-engineered and conventional needle segments.
| Leading Market Players |
|---|
| Becton, Dickinson and Company (BD) |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Nipro Corporation |
| Cardinal Health Inc. |
| Medline Industries LP |
| Retractable Technologies Inc. |
| Smiths Medical Inc. |
| ICU Medical Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for cannula-grade stainless steel now govern margin stability across safety needle fabricators, compressing pricing power for mid-scale producers while rewarding vertically integrated manufacturers with polymer-to-needle control. This lead-time sensitivity concentrates procurement leverage among hospital consortiums in the United States and Germany, who exploit supplier working capital constraints during contract renegotiations.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement, with three-year framework contracts bundling volume commitments against technical service provisions. Price differentiation hinges on ISO 13485 certification tier and passive safety mechanism reliability, with premium tiers capturing training and disposal logistics. Pricing pressure stems from prefilled syringe substitution in vaccination protocols. Emerging market tenders exhibit highest price sensitivity; integrated delivery networks in Japan and Germany absorb safety premiums most readily.
Supply Chain Analysis
Strait of Malacca transit risk underwrites logistics planning for Asian-sourced polymer hub components, with concentration in China, Japan, and South Korea for precision grinding equipment. Raw material dependencies center on nickel-chromium alloy pricing, medical-grade silicone lubricants, and gamma sterilization capacity. Single-source vulnerability in ethylene oxide sterilization facilities poses structural risk. Distribution runs through GPO-mediated channels in the United States and direct hospital consortium relationships in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-as-a-service models for safety needle platforms are expanding faster than standalone hardware procurement, with disposal logistics and compliance reporting emerging as high-margin recurring layers. This service-attach dynamic rewards manufacturers who bundle training, tracking software, and waste management into multi-year agreements.
For Market Incumbents: Secure sterilization validation capacity ahead of EMA MDR enforcement waves, locking dual-certified facilities before mid-scale competitors complete facility upgrades. Defend against prefilled syringe substitution by embedding safety needles into closed-system drug-device combination partnerships with biologics developers. For New Entrants and Emerging Players: Lead with Brazil's anticipated ANVISA safety mandate as the most penetrable conversion window, targeting private hospital networks ahead of formal compliance deadlines. Capture share through patient-centric packaging for home healthcare self-injection therapy, bypassing entrenched GPO relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across passive safety mechanism manufacturing, favoring acquirers with balance sheet capacity to fund CNC grinding equipment and polymer compounding lines. Target mid-scale fabricators with FDA 510(k) clearances but underutilized sterilization assets. Watch for ANVISA regulation publication as the signal triggering consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Technical Documentation Investment | Accelerates market access for safety needle platforms ahead of compliance deadlines. |
| Hospital System Partnership Agreements | Locks multi-year procurement volume through bundled training and disposal services. |
| Backward Integration into Polymer Compounding | Reduces hub component cost volatility and compresses production cycle times. |
| Home Healthcare Distribution Channel Development | Captures direct-to-patient margin pools outside traditional GPO structures. |
| ISO 80369 Small-Bore Connector Certification | Enables platform engineering across enteral and neuraxial delivery modalities. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors at safety needle manufacturers, then refined against FDA 510(k) databases, EMA MDR technical documentation filings, hospital procurement consortium tender records, and WHO prequalification reports. Bottom-up volume estimates triangulated with top-down market sizing across the analysis window.
Variance decomposition across product type, application, end user, and regional regulatory cluster shaped the analytical framework, with CAGRs derived from systematic regression against diabetes prevalence trajectories and safety mandate implementation timelines. Modeled inputs included insulin injection therapy volume curves, OSHA enforcement intensity indices, and EMA MDR approval velocity assumptions.
Underlying assumptions cover stainless steel price stability and EMA MDR timeline adherence, with deviation risk concentrated in prefilled syringe substitution rates and Brazil ANVISA mandate delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Intranasal Splints Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Global Lancets Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Asia-Pacific Surgical Glue Market