
 Global Synthetic Absorbable Sutures Market | 2026-2036
Global Synthetic Absorbable Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synthetic Absorbable Sutures Market Foresight
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for synthetic absorbable suture manufacturers serving European healthcare systems. Johnson & Johnson (Ethicon) leverages its vertically integrated polymer supply chain to sustain margin structures under stricter conformity assessment requirements. B. Braun Melsungen AG anchors its competitive position through specialized manufacturing of polydioxanone monofilaments for cardiovascular applications. Medtronic competes by extending its hospital contracting networks across Western European markets.
Synthetic absorbable sutures are implantable medical devices manufactured from biodegradable polymers such as polyglycolic acid, polylactic acid, and polydioxanone, designed to maintain tensile strength for 14 to 60 days before hydrolytic degradation eliminates the need for removal. Their primary commercial purpose is to close surgical incisions and ligate tissues in procedures where follow-up suture removal would burden clinical workflows or patient compliance. Polyglycolic acid multifilament configurations dominate procedural volume in general surgery due to established handling characteristics and predictable absorption profiles. Monofilament polydioxanone segments command premium positioning in cardiovascular and orthopedic applications where extended wound support is clinically necessary.
The FDA enforces Class II medical device controls requiring biocompatibility testing under ISO 10993 standards for all synthetic absorbable sutures distributed in the United States. Japan's PMDA and South Korea's MFDS impose comparable premarket quality system requirements that shape product development timelines for manufacturers seeking multi-regional approvals. Stakeholders must monitor evolving polymer degradation standards and antimicrobial coating claims as regulatory scrutiny intensifies on long-term implantable device safety profiles.
Market Dynamics
The EU Medical Device Regulation's expanded biocompatibility testing protocols are restructuring competitive economics for synthetic absorbable suture manufacturers, forcing polymer science investments and third-party conformity assessment costs that favor scaled producers with captive laboratory infrastructure.
Growth Catalysts
- Ambulatory surgical center procurement upgrades:United States outpatient facilities are mandating higher-grade synthetic absorbable sutures for laparoscopic and endoscopic procedures, pulling volume from traditional hospital purchasing.
- REACH-compliant polymer innovation:European chemical safety frameworks are accelerating development of bioabsorbable copolymers with controlled hydrolysis profiles that meet both clinical performance and environmental release standards.
- Polydioxanone cardiovascular applications:Cardiac surgery departments in tertiary hospitals are specifying extended-absorption monofilament configurations for sternal closure and vascular anastomosis where long-term tensile support is critical.
Market Restraints
- Caprolactone and glycolide feedstock volatility:Petrochemical-derived monomer costs fluctuate with crude oil indices, compressing margin predictability for manufacturers without backward integration into polymer synthesis.
- Single-source sterilization infrastructure concentration:Gamma irradiation and ethylene oxide terminal sterilization capacity clusters in Germany and the Netherlands, creating geographic chokepoints for European distribution.
- Catgut and metal clip substitution in cost-sensitive settings:Traditional suture materials and mechanical wound closure devices retain procedural share in emerging market public health systems where reimbursement rates constrain synthetic polymer adoption.
Strategic Opportunities
- India's PLI scheme for medical device manufacturing:Production-linked incentive frameworks are attracting synthetic suture assembly and polymer compounding investments to serve domestic surgical volume and export markets.
- Antimicrobial triclosan and chlorhexidine coating convergence:Combination devices integrating infection prevention pharmacology with absorbable polymer matrices command premium positioning in orthopedic and diabetic wound closure.
- Direct-to-hospital digital procurement platforms:E-procurement networks are disintermediating traditional surgical distributor relationships, enabling manufacturer price transparency and volume contracting with integrated delivery networks.
Industry Challenges
- ISO 10993-6 implantation study timeline compression:Extended biocompatibility testing protocols for absorbable devices demand 26-week histopathology evaluations that extend product development cycles and defer revenue recognition.
- Polymer extrusion and braiding equipment capex intensity:Precision monofilament drawing towers and multifilament braiding machines require seven-figure capital commitments that strain mid-tier manufacturer balance sheets.
- Legacy ERP integration with UDI compliance systems:Unique device identification mandates under FDA and EU MDR frameworks force retrofitting of manufacturing execution systems with serialization and aggregation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synthetic Absorbable Sutures Market |
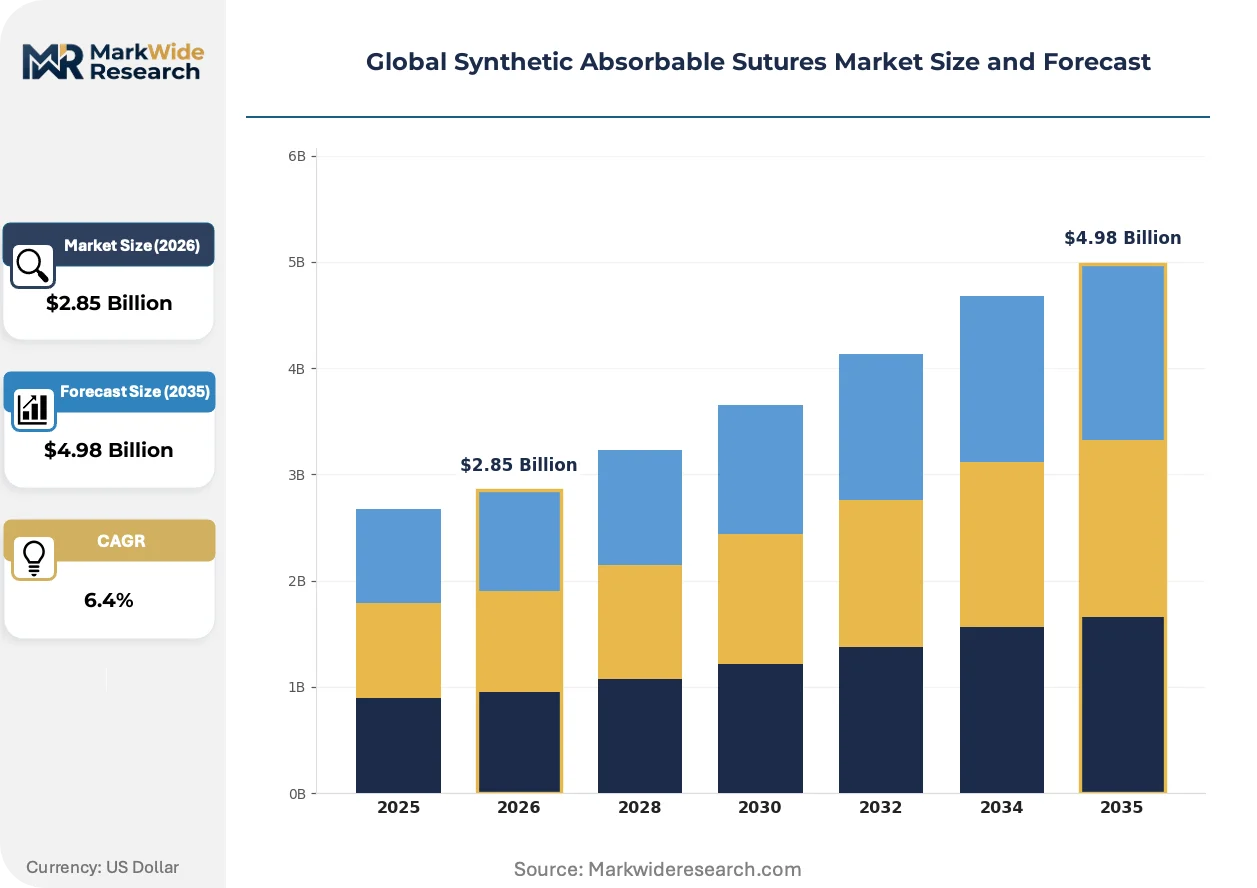
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyglycolic Acid, Polylactic Acid, Polyglecaprone, Polydioxanone, Caprolactone Copolymer Application: General Surgery, Orthopedic Procedures, Cardiovascular Surgery, Gynecological Surgery, Plastic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Form: Monofilament, Multifilament, Braided, Coated |
| Companies Covered | Johnson & Johnson (Ethicon), Medtronic, B. Braun Melsungen AG, DemeTECH Corporation, Boston Scientific Corporation, Smith & Nephew, Teleflex Incorporated, Zimmer Biomet Holdings, Lotus Surgicals Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synthetic Absorbable Sutures Market Shifts & Advancements
Bioresorbable polymer chemistry is advancing beyond simple homopolymer formulations toward tailored degradation kinetics that match specific tissue healing timelines, while regulatory frameworks on both sides of the Atlantic tighten evidentiary requirements for long-term implantable safety profiles.
Multifunctional suture architectures incorporating drug-eluting reservoirs and bioactive surface modifications are converging with minimally invasive surgical platforms to enable localized therapeutic delivery without secondary implantation procedures. Cardiovascular surgery units in German university hospitals are piloting vascular endothelial growth factor-coated polydioxanone for coronary bypass grafting. This convergence is compressing the traditional boundary between mechanical wound closure and pharmaceutical intervention, forcing manufacturers to build biologics capabilities or cede premium segments.
The EU Medical Device Regulation's 2021 implementation deadline and subsequent guidance documents on absorbable implantable devices are extending conformity assessment timelines for novel polymer formulations. Notified bodies in Ireland and the Netherlands are requiring extended degradation kinetic data and particulate characterization that exceeds prior MEDDEV standards. Small-cap manufacturers without established quality management system maturity are withdrawing legacy product lines rather than absorbing recertification costs, consolidating shelf presence for scaled competitors with dedicated regulatory affairs infrastructure.
Hospital value analysis committees are consolidating suture purchasing across previously autonomous surgical service lines, replacing surgeon-specific preference cards with standardized formularies tied to outcome metrics and total procedural cost. Integrated delivery networks in Texas and Florida are negotiating multi-year synthetic absorbable suture contracts with performance guarantees on infection rates and dehiscence complications. This behavioral shift is most pronounced in United States metropolitan markets where health system consolidation has concentrated purchasing leverage and procurement functions report directly to chief financial officers rather than materials management departments.
Global Synthetic Absorbable Sutures Market Segmentation
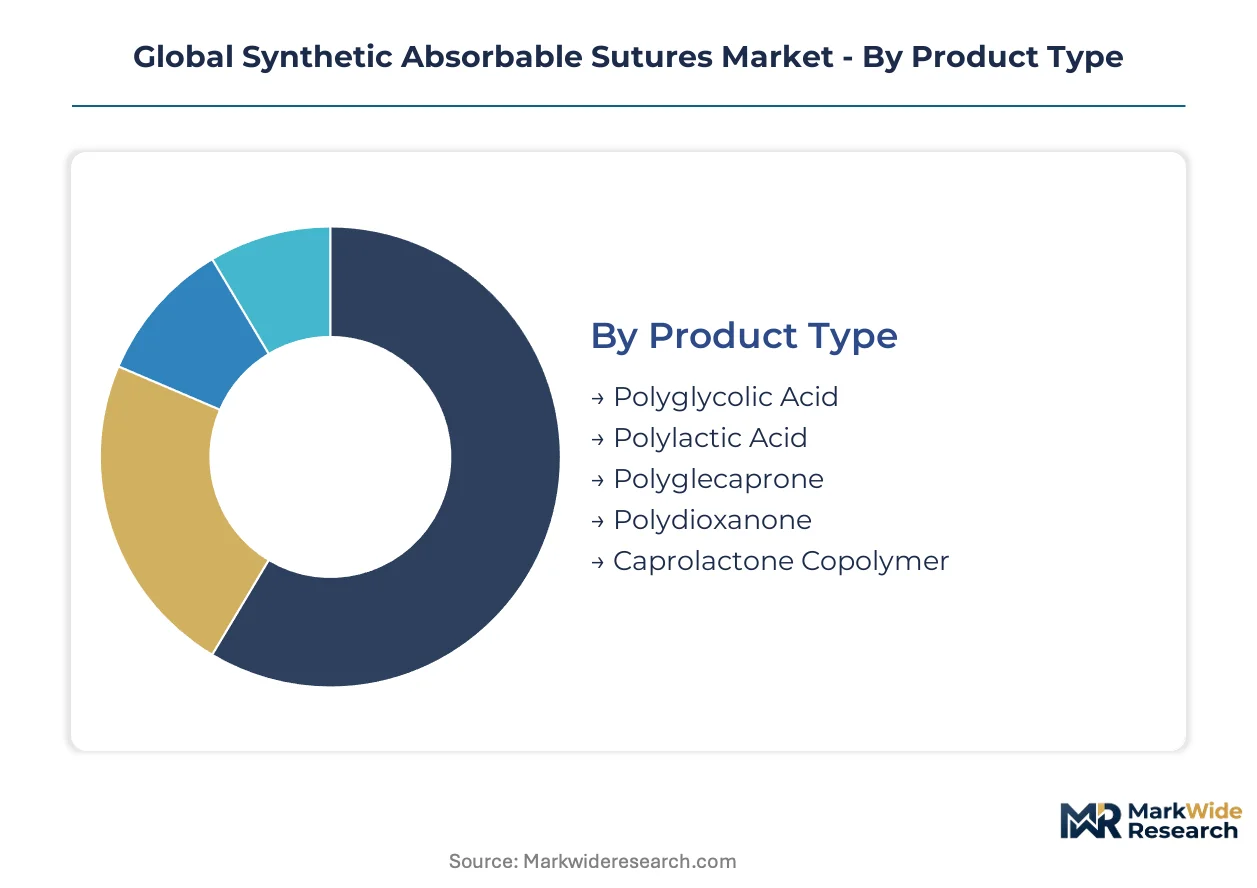
Synthetic absorbable sutures segment across polymer chemistry, surgical application, and physical construction. Each dimension carries distinct margin profiles and regulatory pathways that reshape manufacturer resource allocation and competitive positioning.
Product Type:
Hospital procurement committees are upgrading suture specifications as biocompatibility testing requirements tighten, forcing polymer selection decisions that balance absorption kinetics against sterilization compatibility.
- Polyglycolic Acid:Multifilament braided configurations dominate general surgery volume due to predictable 60-90 day absorption profiles and established handling characteristics. United States ambulatory surgical centers specify PGA for laparoscopic closure where follow-up removal would burden outpatient workflows.
- Polydioxanone:Extended tensile strength retention over 180 days positions monofilament PDS for cardiovascular and orthopedic applications. German university hospitals specify PDS for sternal closure where long-term wound support reduces dehiscence risk.
- Polylactic Acid:Slower hydrolysis rates suit orthopedic soft tissue repair requiring 90+ day structural integrity.
- Polyglecaprone:Rapid absorption within 60-70 days finds use in plastic surgery and subcuticular closure.
- Caprolactone Copolymer:Tailored degradation kinetics enable customized formulations for specific tissue healing timelines.
Polyglycolic Acid sits at the top of the volume ranking, with Polydioxanone climbing the fastest as cardiac surgery departments upgrade to extended-absorption monofilaments.
Application:
Procedure-specific reimbursement rates and outcome accountability measures are concentrating demand in surgical specialties where suture performance directly impacts complication metrics.
- General Surgery:Laparoscopic and open abdominal procedures consume the highest suture volume across health systems. United States integrated delivery networks negotiate standardized formularies for cholecystectomy, appendectomy, and hernia repair that favor synthetic absorbable over traditional catgut.
- Cardiovascular Surgery:Sternal closure and vascular anastomosis demand extended tensile support that polydioxanone monofilaments provide. Japanese PMDA quality system requirements shape product development timelines for manufacturers targeting this high-value segment.
- Orthopedic Procedures:Soft tissue repair and ligament approximation drive demand for high-strength braided configurations.
- Gynecological Surgery:Hysterectomy and pelvic floor reconstruction specify rapid-absorption materials to minimize foreign body reaction.
- Plastic Surgery:Subcuticular closure and cosmetic applications prioritize minimal tissue reaction and scar formation.
General Surgery captures the largest procedure volume, while Cardiovascular Surgery generates the steepest expansion trajectory as aging populations drive cardiac intervention demand.
End User:
Facility-type procurement authority is shifting as health system consolidation centralizes purchasing decisions away from individual surgeons toward value analysis committees.
- Hospitals:Tertiary academic medical centers and community hospitals remain the dominant consumption point for synthetic absorbable sutures. Texas and Florida health systems negotiate multi-year contracts with infection rate performance guarantees that reshape supplier relationships.
- Ambulatory Surgical Centers:United States outpatient facilities are mandating higher-grade synthetic absorbable specifications for endoscopic procedures. FDA Class II device controls and ISO 10993 compliance requirements filter supplier options to scaled manufacturers with established quality systems.
- Specialty Clinics:Dermatology and ophthalmology practices consume specialized microsuture configurations.
- Research Institutions:Preclinical and clinical trial applications drive demand for novel polymer formulations and drug-eluting prototypes.
Hospitals maintain the highest absolute consumption, with Ambulatory Surgical Centers gaining share fastest as procedure migration accelerates.
Form:
Physical construction determines handling characteristics, knot security, and tissue drag—factors that surgeons weigh against absorption profiles when selecting sutures for specific procedures.
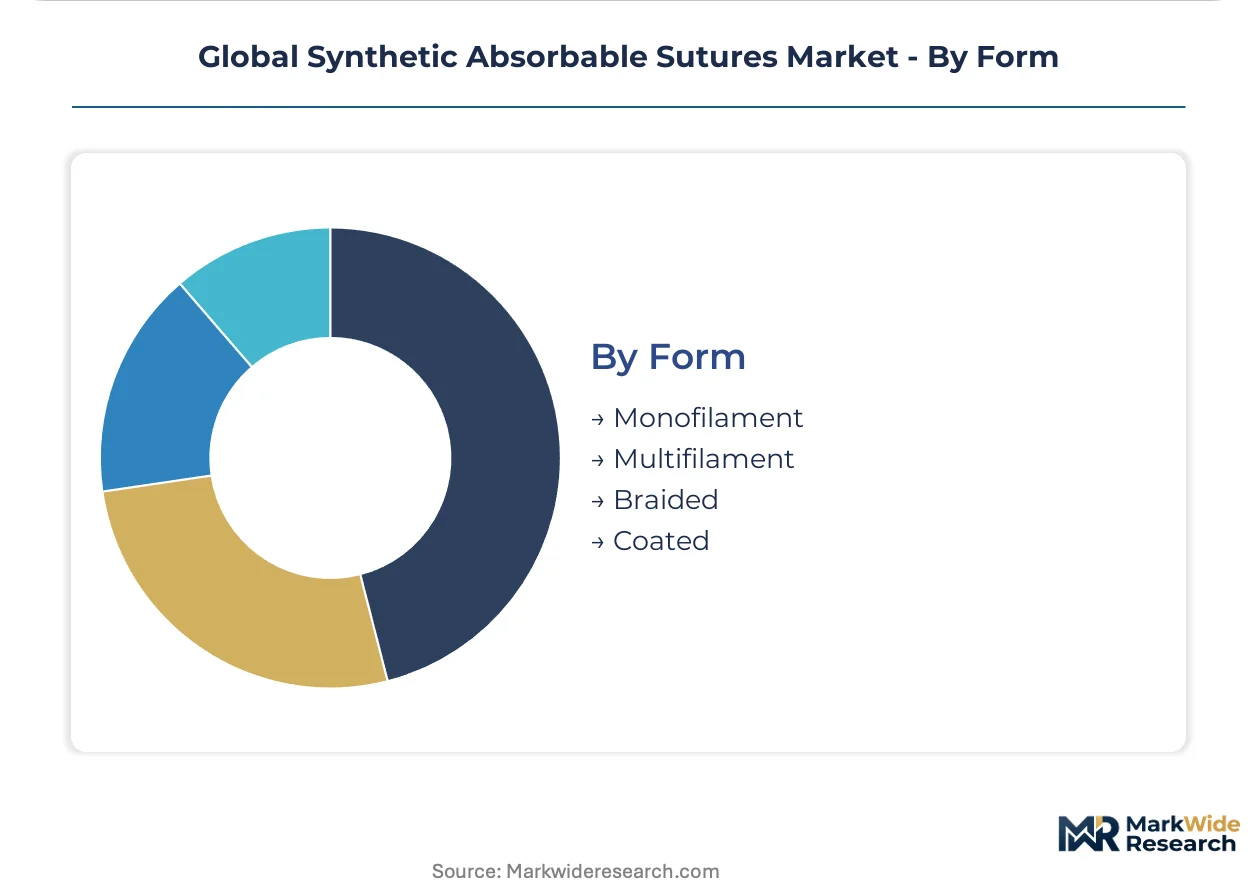
- Multifilament:Braided polyglycolic acid configurations offer superior knot security and pliability that general surgeons prefer for soft tissue approximation. REACH-compliant polymer innovation is accelerating development of bioabsorbable multifilaments that meet both clinical performance and European chemical safety frameworks.
- Monofilament:Smooth polydioxanone surfaces reduce tissue drag and bacterial adherence in cardiovascular applications. India's PLI scheme for medical device manufacturing is attracting monofilament extrusion investments to serve domestic surgical volume.
- Braided:Interwoven fiber architectures maximize tensile strength for orthopedic and general surgery applications.
- Coated:Antimicrobial and lubricant surface modifications command premium positioning in infection-sensitive procedures.
Multifilament leads procedural volume, with Monofilament expanding most quickly as cardiac surgery departments specify extended-absorption configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and surgical device engineers cluster in Germany, the United States, and Japan, anchoring regional innovation capacity for next-generation absorbable sutures.
United States
Ambulatory surgical centers in Texas and Florida are mandating higher-grade synthetic absorbable specifications for laparoscopic procedures. FDA Class II device controls under ISO 10993 standards filter supplier options to scaled manufacturers with established quality systems. Integrated delivery networks in Houston and Miami negotiate multi-year contracts with infection rate performance guarantees.
Germany
Cardiac surgery departments in Munich and Berlin university hospitals specify extended-absorption polydioxanone monofilaments for sternal closure. ECHA REACH compliance requirements accelerate development of bioabsorbable copolymers meeting clinical performance and environmental release standards. Notified bodies in Ireland and the Netherlands extend conformity assessment timelines for novel polymer formulations.
Japan
PMDA quality system requirements shape product development timelines for manufacturers targeting cardiovascular and orthopedic applications. Tokyo and Osaka medical device clusters concentrate precision monofilament extrusion capacity. Aging demographics drive cardiac intervention demand, pulling premium suture consumption.
India
Production-linked incentive schemes attract synthetic suture assembly and polymer compounding investments to serve domestic surgical volume. CDSCO medical device regulations tighten biocompatibility testing protocols for implantable materials. Manufacturing investments cluster in Maharashtra and Gujarat to access export markets.
China
NMPA premarket approval requirements extend product registration timelines for absorbable polymer devices. Yangtze River Delta medical device manufacturing zones concentrate multifilament braiding capacity. Tertiary hospitals in Shanghai and Beijing upgrade procurement standards for minimally invasive procedures.
Global Synthetic Absorbable Sutures Market Competitive Landscape
The competitive structure tilts toward diversified medical device conglomerates with captive polymer supply chains. Three to five scaled producers control shelf presence in regulated markets, while mid-tier specialists serve cost-sensitive segments. Strategic archetypes include vertically integrated polymer manufacturers, surgical device pure-plays, and regional contract assemblers. Capacity expansion and regulatory certification investments represent the dominant competitive moves as EU MDR timelines compress.
Among diversified healthcare conglomerates, Johnson & Johnson (Ethicon) and Medtronic exemplify scale-driven archetypes with established hospital contracting networks. B. Braun Melsungen AG occupies a position within the European specialist tier. These anchors reflect the market's bifurcation between global suppliers with quality management system maturity and regional fabricators competing on procurement cost.
| Leading Market Players |
|---|
| Johnson & Johnson (Ethicon) |
| Medtronic |
| B. Braun Melsungen AG |
| DemeTECH Corporation |
| Boston Scientific Corporation |
| Smith & Nephew |
| Teleflex Incorporated |
| Zimmer Biomet Holdings |
| Lotus Surgicals Pvt Ltd |
| Others |
Supply & Pricing Matrix
Ambulatory surgical center procurement upgrades in the United States are mandating higher-grade synthetic absorbable specifications, compelling manufacturers to absorb polymer science investments and third-party conformity assessment costs that reshape margin structures across tiers.
Pricing Analysis
The bundled service split between suture-only procurement and procedure-kit integration dominates transactional patterns. Three-tier pricing structure across premium, standard, and economy levels separates polydioxanone monofilaments for cardiovascular applications from polyglycolic acid multifilaments for general surgery and uncoated alternatives for cost-sensitive settings. Cost compression in economy tiers is intensifying because India's PLI scheme attracts regional contract assemblers competing on procurement cost. Ambulatory surgical centers exhibit the highest price sensitivity due to fixed reimbursement rates, while German university hospitals prioritize performance guarantees over unit cost.
Supply Chain Analysis
Caprolactone and glycolide feedstock supply rests on petrochemical-derived monomer production clustered in Germany, the United States, and Japan. Precision monofilament drawing towers and multifilament braiding machines draw from specialized equipment manufacturers in Switzerland and Italy, while gamma irradiation and ethylene oxide terminal sterilization capacity concentrates in Germany and the Netherlands. Single-source sterilization infrastructure concentration creates geographic chokepoints for European distribution. Distribution runs through traditional surgical distributors and emerging direct-to-hospital digital procurement platforms serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic absorbable sutures market functions as a stable compounder anchored by aging demographics driving cardiac and orthopedic intervention demand that sustains premium segment expansion.
For Market Incumbents: Deepen captive polymer supply chain control to sustain margin structures under EU MDR biocompatibility testing cost inflation. Expand sterilization infrastructure investments in the Netherlands and Germany to mitigate geographic chokepoint vulnerability. Prioritize antimicrobial coating R&D to defend premium positioning against drug-eluting suture substitutes. For New Entrants and Emerging Players: Begin with India's PLI scheme for medical device manufacturing to access domestic surgical volume and export markets with favorable cost structures. Target ambulatory surgical center procurement in Texas and Florida where standardized formularies create entry pathways for ISO 10993-compliant alternatives. Pursue direct-to-hospital digital procurement platform partnerships to disintermediate traditional distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier European specialists possessing notified body relationships and REACH-compliant polymer capabilities. The five-to-ten year viability window favors manufacturers with demonstrated EU MDR conformity assessment timelines. Watch for small-cap manufacturer withdrawal from legacy product lines as a consolidation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Investment | Notified bodies in Ireland and the Netherlands require extended degradation kinetic data exceeding prior MEDDEV standards. |
| Antimicrobial Coating Development | Triclosan and chlorhexidine integration commands premium positioning in orthopedic and diabetic wound closure applications. |
| India PLI Manufacturing Footprint | Production-linked incentives attract polymer compounding investments to serve domestic surgical volume and export markets. |
| Direct-to-Hospital Digital Procurement | E-procurement networks enable manufacturer price transparency with integrated delivery networks in Texas and Florida. |
| Backward Integration into Polymer Synthesis | In-house production of caprolactone and glycolide monomers insulates margin predictability from crude oil index volatility. |
Research Methodology
Bottom-up hospital and ambulatory surgical center demand modeling reconciled against top-down polymer production capacity tracking forms the analytical core. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement data, and hospital procurement database records. Triangulation between demand-side consumption patterns and supply-side manufacturing capacity establishes volume and value estimates.
Input-output matrices map polymer chemistry segments against surgical application demand across the projection horizon. Segmentation dimensions modeled include product type, application specialty, end-user facility category, and physical construction form. CAGRs derive from procedure volume growth trajectories, reimbursement rate evolution, and polymer adoption elasticity coefficients. Forecast inputs incorporate EU MDR implementation timelines, ambulatory surgical center migration rates, and antimicrobial coating penetration assumptions.
Several conditions sit outside the modeled scope, including unforeseen polymer degradation safety events, abrupt feedstock price dislocations, and regulatory timeline accelerations or delays. Forecasts reflect documented assumptions regarding health system consolidation trajectories and procurement centralization patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Tongue Depressors Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Global Hemostats Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Intraosseous Infusion Kits Market