
 Global Dental Syringes Market | 2026-2036
Global Dental Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Syringes Market Foresight
Germany is narrowing its manufacturing gap in precision dental instruments through dedicated industrial zones near Stuttgart and Freiburg. Dentsply Sirona leverages its integrated design-to-distribution network across European dental clinics. Septodont sustains its anesthesia cartridge dominance through proprietary glass-barrel technology. 3M Company anchors its position via adhesive and delivery system synergies that extend into dental syringe accessories.
Dental syringes are precision aspiration and injection instruments, typically fabricated from medical-grade stainless steel barrels with silicone-sealed plungers and Luer-lock or proprietary thread fittings, engineered to deliver exact dosages of local anesthetic agents into periodontal, periapical, or maxillofacial tissue. Safety syringes lead product type revenue due to institutional procurement mandates, while auto-disable variants represent the fastest-growing category driven by WHO injection safety protocols and cross-contamination concerns in emerging clinic networks. Mechanical technology occupies the dominant share among manual, mechanical, battery-operated, jet injection, and cartridge systems, though battery-operated aspiration-assist mechanisms are gaining traction in periodontal treatment applications where tactile feedback precision matters.
FDA 510(k) clearance pathways and EU MDR Class IIa designation govern dental syringe market access, with OSHA Bloodborne Pathogens Standard and EU sharps injury directives directly shaping safety-feature procurement specifications across dental clinics and teaching institutions. ISO 7886-2 sterilizable syringe standards and WHO best-injection practices further constrain reusable product viability while privileging single-use safety architectures. Stakeholders must monitor evolving EUDAMED registration requirements and state-level dental board instrument sterilization audits to anticipate compliance-driven replacement cycles.
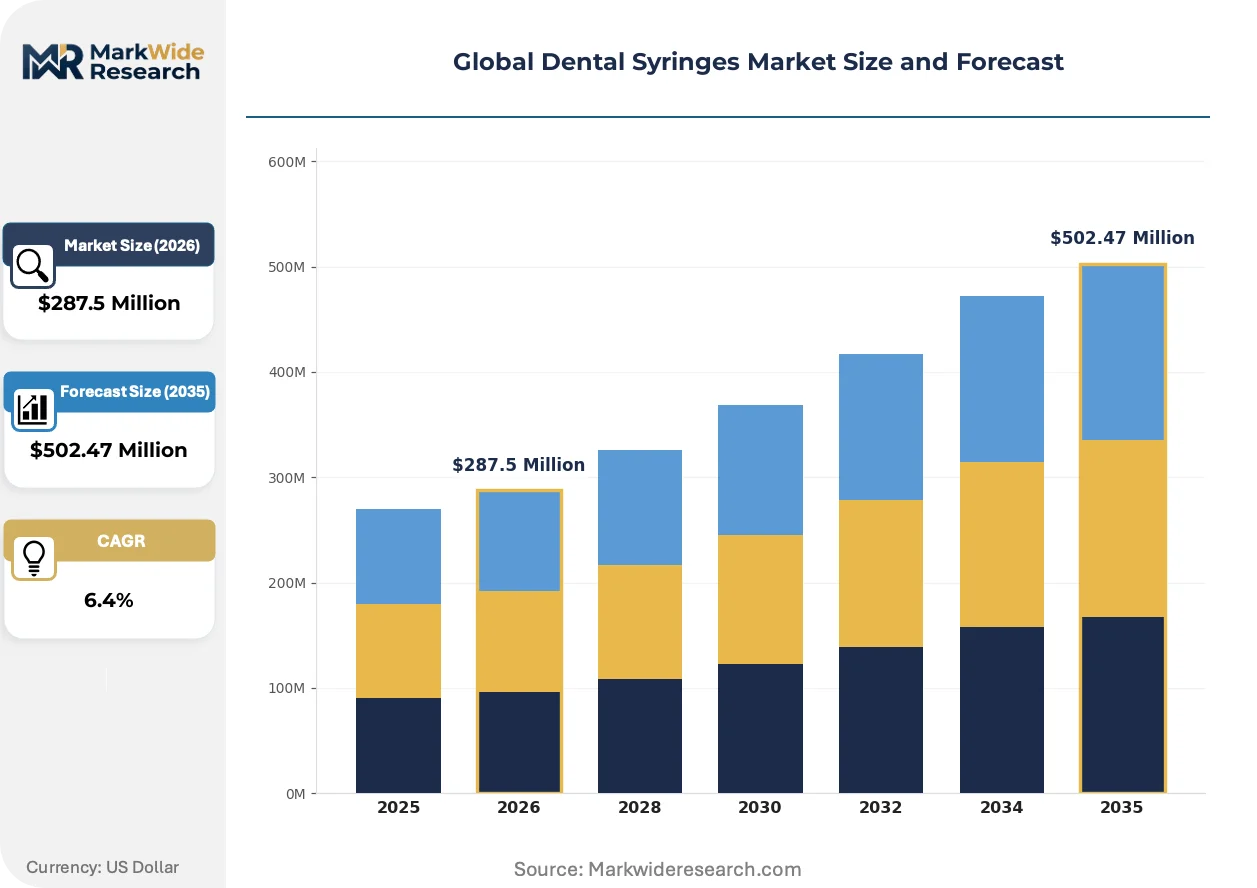
Market Dynamics
The dental syringes market is experiencing a fundamental reconfiguration as safety-engineered devices displace conventional reusable instruments under needlestick prevention mandates. Institutional procurement protocols now prioritize sharps injury protection over unit cost, compressing replacement cycles and elevating compliance documentation requirements across dental clinic networks.
Growth Catalysts
- EU MDR Class IIa designation:The Medical Device Regulation mandates enhanced safety features for reusable dental instruments, accelerating clinic-level conversions to auto-disable and retractable-needle architectures across German, French, and Italian dental practices.
- OSHA Bloodborne Pathogens Standard:US dental clinics face documented exposure incident thresholds that trigger mandatory safety device adoption, creating institutional pull-through for engineered sharps protection in periodontal and endodontic procedures.
- Jet injection technology:Needle-free anesthetic delivery systems are penetrating pediatric and anxiety-sensitive patient segments, expanding addressable procedure volumes beyond traditional invasive injection protocols.
Market Restraints
- Medical-grade stainless steel volatility:Barrel fabrication depends on 316L and 17-4 PH alloy supply chains concentrated in German and Japanese specialty steel mills, exposing manufacturers to nickel and chromium price swings.
- Single-use plastic dependency:Safety syringe dominance locks producers into petroleum-based polymer feedstocks, creating circular economy compliance friction under EU Green Deal packaging directives.
- ISO 7886-2 sterilization validation:Reusable product viability faces collapsing as steam sterilization cycle documentation requirements exceed clinic administrative capacity, eliminating cost advantages of metal-barrel alternatives.
Strategic Opportunities
- Brazilian clinic network expansion:ANVISA regulatory harmonization with ISO standards is reducing import friction for safety-engineered devices into São Paulo and Rio de Janeiro dental service chains.
- Battery-operated aspiration-assist convergence:Integration of tactile feedback electronics with precision mechanical barrels addresses periodontal pocket depth measurement accuracy, opening premium positioning in Japanese specialist practices.
- WHO injection safety protocol adoption:Auto-disable syringe mandates in emerging clinic networks across Southeast Asia create first-mover advantages for manufacturers with existing AD mechanism production lines.
Industry Challenges
- Biocompatibility testing timelines:Novel elastomer plunger seal materials face extended ISO 10993 cytotoxicity and sensitization study durations, compressing product development windows against regulatory submission deadlines.
- Legacy instrument sterilization audit complexity:Dental clinic compliance officers struggle to reconcile state dental board instrument tracking requirements with EUDAMED unique device identifier submissions, creating administrative bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Syringes Market |
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $502.47 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringes, Safety Syringes, Anaesthetic Syringes, Auto-Disable Syringes, Reusable Syringes Technology: Manual, Mechanical, Battery Operated, Jet Injection, Cartridge Application: Local Anesthesia, Periodontal Treatment, Endodontic Procedures, Oral Surgery, Pediatric Dentistry End User: Dental Clinics, Dental Laboratories, Dental Teaching Institutions, Mobile Dental Units |
| Companies Covered | Dentsply Sirona, Septodont, 3M Company, Integra LifeSciences Corporation, A. Titan Instruments, Power Dental USA, 4tek S.r.l, Ultradent Products, Kerr Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Syringes Market Shifts & Advancements
Active materials integration and connected device architectures are redefining precision delivery expectations in dental anesthesia. The convergence of mechanical reliability with electronic feedback systems is compressing the performance gap between manual expertise and standardized outcomes.
Smart syringe platforms incorporating pressure-sensing cartridges and Bluetooth-enabled dose logging are hybridizing traditional aspiration safety with digital procedure documentation. Specialist periodontal practices in Germany and Japan are piloting these systems to correlate injection pressure profiles with post-operative paresthesia rates. The technology is hybridizing liability risk management with clinical outcome tracking, forcing instrument manufacturers to develop software validation competencies alongside mechanical engineering.
REACH Annex XVII restrictions on phthalate plasticizers are compelling seal material reformulation across European supply chains. Manufacturers serving German and French dental distributors must validate alternative elastomer compounds without compromising plunger glide friction specifications. The regulatory pressure is most acute in safety syringe segments where single-use disposability limits material recovery options.
Consolidated buying groups in US dental service organizations are unbundling instrument procurement from anesthetic cartridge supply agreements. Large multi-clinic operators in Texas and California now negotiate syringe specifications separately from Septodont and 3M cartridge contracts, fragmenting traditional bundled purchasing power. This disintermediation is most visible in DSO-affiliated practices where standardization mandates override individual clinician instrument preferences.
Global Dental Syringes Market Segmentation
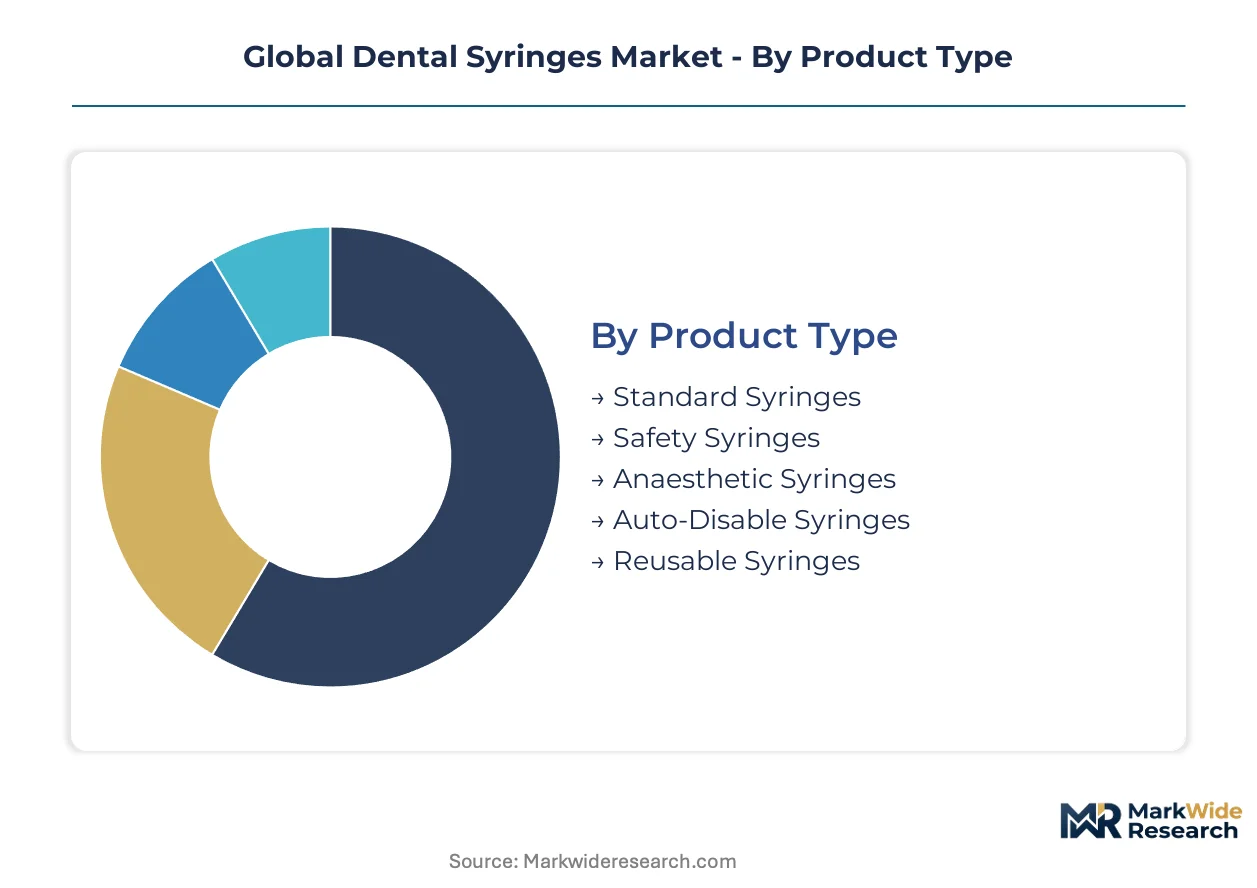
Dental syringe procurement splits across safety mandates, procedural specialization, and clinic infrastructure tiers. Understanding these divisions clarifies where compliance costs concentrate and where technology premiums command pricing power.
Product Type:
Mature reusable architectures now compete with emerging single-use safety designs as institutional procurement pivots toward sharps injury prevention.
- Safety Syringes:Retractable-needle and shielded-barrel designs dominate hospital-affiliated dental clinics under OSHA and EU sharps injury directives. German and French group purchasing organizations now mandate these specifications for all anesthetic delivery contracts.
- Auto-Disable Syringes:Single-use mechanisms with irreversible locking functions address WHO injection safety protocols in emerging clinic networks. Southeast Asian public health procurement is standardizing these devices for cross-contamination control.
- Standard Syringes:Basic Luer-lock disposable barrels persist in cost-sensitive private practices outside regulated procurement networks.
- Anaesthetic Syringes:Cartridge-compatible precision barrels with aspiration functionality target periodontal and endodontic specialists requiring tactile feedback.
- Reusable Syringes:Medical-grade stainless steel barrels with sterilizable components face collapsing demand as ISO 7886-2 documentation requirements exceed clinic administrative capacity.
Safety syringes handle the majority of throughput; auto-disable syringes are gaining share fastest on public health procurement expansion.
Technology:
Cost tier separation runs from commodity manual instruments through premium electronic aspiration-assist systems.
- Mechanical:Spring-loaded aspiration mechanisms and precision plunger drives balance reliability with cost in high-volume European and Japanese clinics. Stuttgart-area manufacturers specialize in these hybrid architectures.
- Battery Operated:Electronic aspiration-assist with pressure sensing addresses periodontal pocket depth measurement accuracy. Japanese specialist practices pilot these systems for paresthesia risk correlation.
- Manual:Basic finger-grip aspiration remains standard in training institutions and developing clinic networks where capital constraints limit technology adoption.
- Jet Injection:Needle-free anesthetic delivery penetrates pediatric and anxiety-sensitive patient segments, expanding addressable procedure volumes beyond invasive protocols.
- Cartridge:Integrated anesthetic cartridge systems from Septodont and 3M streamline workflow in high-throughput US dental service organizations.
Mechanical systems anchor volume; battery-operated platforms are climbing the fastest on periodontal specialization.
Application:
Procedure complexity determines instrument specification, with surgical interventions demanding precision aspiration and pediatric cases favoring anxiety-reduction features.
- Local Anesthesia:Routine infiltration and block injections consume the highest instrument volumes across general dental practices in Germany, the United States, and Japan.
- Periodontal Treatment:Pocket depth measurement accuracy requirements drive demand for aspiration-assist mechanisms with tactile feedback calibration.
- Endodontic Procedures:Periapical injection precision necessitates specialized aspirating syringes with minimal dead-space design.
- Oral Surgery:Maxillofacial interventions require high-volume anesthetic delivery with rapid cartridge exchange capability.
- Pediatric Dentistry:Anxiety management protocols favor jet injection and safety-engineered devices with visual distraction features.
Local anesthesia commands the installed base; periodontal applications are expanding most quickly on specialist practice growth.
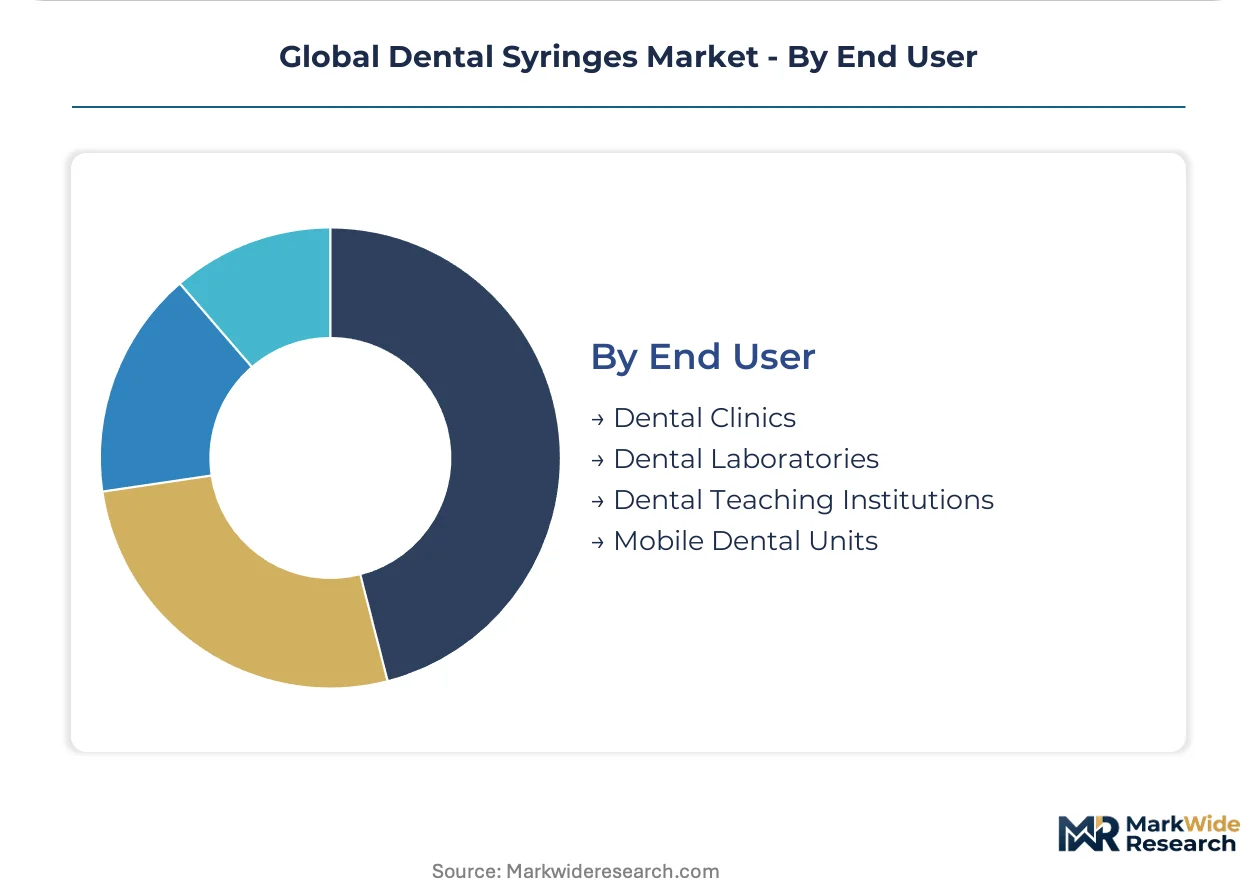
End User:
Customer type segmentation reflects procurement centralization versus clinician autonomy, with consolidated buying groups reshaping vendor relationships.
- Dental Clinics:Independent and group practices in Texas and California drive safety syringe conversion as dental service organization standardization mandates override individual preferences.
- Dental Teaching Institutions:Universities in Germany and Japan pilot smart syringe platforms with Bluetooth-enabled dose logging for outcome correlation studies.
- Dental Laboratories:Prosthetic and orthodontic fabrication facilities require auxiliary syringes for material delivery rather than anesthetic administration.
- Mobile Dental Units:Outreach programs in Brazil and Southeast Asia prioritize auto-disable devices for infection control in non-clinical settings.
Dental clinics absorb the dominant procurement volume; mobile units are gaining share fastest on public health network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA Bloodborne Pathogens Standard enforcement in US dental clinics is accelerating safety syringe procurement faster than any other single regulatory mechanism worldwide. German industrial clusters near Stuttgart and Freiburg are narrowing precision manufacturing gaps through dedicated medical device zones. Japanese specialist practices in periodontal segments are piloting battery-operated aspiration-assist systems for paresthesia risk correlation.
United States
Texas and California dental service organizations are unbundling syringe procurement from anesthetic cartridge contracts, fragmenting traditional bundled purchasing power. OSHA exposure incident thresholds trigger mandatory safety device adoption across periodontal and endodontic practices. Houston and Dallas clinic networks drive standardization mandates that override individual clinician instrument preferences.
Germany
EU MDR Class IIa designation mandates enhanced safety features for reusable dental instruments, accelerating clinic-level conversions to auto-disable architectures. Stuttgart-area manufacturers specialize in spring-loaded aspiration mechanisms and precision plunger drives. Freiburg industrial zones concentrate glass-barrel technology production for anesthesia cartridge compatibility.
Japan
Aging demographics require more complex oral surgical interventions, elevating demand for precision aspiration instruments with tactile feedback. METI standards govern battery-operated aspiration-assist mechanism approvals. Nagoya and Osaka specialist periodontal practices pilot smart syringe platforms correlating injection pressure profiles with post-operative outcomes.
Brazil
ANVISA regulatory harmonization with ISO standards is reducing import friction for safety-engineered devices into São Paulo and Rio de Janeiro dental service chains. Public health network expansion prioritizes auto-disable syringes for mobile outreach units. Southeast Asian WHO protocol adoption creates spillover demand for manufacturers with existing AD mechanism production lines.
France
REACH Annex XVII restrictions on phthalate plasticizers compel seal material reformulation across European supply chains. French dental distributors demand validated alternative elastomer compounds without compromised plunger glide friction specifications. Paris and Lyon group purchasing organizations now mandate retractable-needle specifications for all anesthetic delivery contracts.
Global Dental Syringes Market Competitive Landscape
Integrated conglomerates and precision instrument specialists split the market along capability depth versus portfolio breadth lines. The vendor base concentrates around three strategic archetypes: full-service dental equipment conglomerates with design-to-distribution networks, anesthesia delivery specialists with proprietary cartridge technologies, and regional precision metal fabricators serving institutional procurement channels. Dominant competitive moves include backward integration into medical-grade stainless steel supply chains and technology licensing agreements for auto-disable mechanism patents.
Within the conglomerate tier, Dentsply Sirona and 3M Company exemplify integrated positioning through adhesive and delivery system synergies that extend into dental syringe accessories. Septodont occupies a specialist anchor position in anesthesia cartridge dominance through proprietary glass-barrel technology. Among precision instrument fabricators, Integra LifeSciences Corporation and Kerr Corporation represent mechanical reliability archetypes serving high-throughput clinic networks.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Septodont |
| 3M Company |
| Integra LifeSciences Corporation |
| A. Titan Instruments |
| Power Dental USA |
| 4tek S.r.l |
| Ultradent Products |
| Kerr Corporation |
| Others |
Supply & Pricing Matrix
Stuttgart-area precision manufacturing clusters command disproportionate pricing leverage through captive 316L stainless steel forging capacity and integrated glass-barrel anesthesia cartridge production. German industrial zones near Freiburg translate upstream material control into premium positioning for safety-engineered dental instruments across EU procurement networks, while Japanese specialty steel mills in Nagoya anchor cost structures for battery-operated aspiration-assist systems.
Pricing Analysis
Price spreads between German-manufactured safety syringes and Asian-sourced standard alternatives exceed 40% at the distributor level, reflecting ISO 13485 certification premiums and EU MDR compliance documentation costs. Three-tier pricing structure across premium, standard, and economy levels separates auto-disable mechanisms with Bluetooth logging from basic retractable-needle designs and commodity Luer-lock disposables. Pricing pressure stems from petroleum-based polymer feedstock volatility under EU Green Deal packaging directives. Dental service organizations in Texas and California exhibit highest price sensitivity through unbundled procurement mandates, while Japanese periodontal specialist practices show lowest sensitivity due to outcome-based reimbursement alignment.
Supply Chain Analysis
Contract manufacturing for safety syringe auto-disable mechanisms concentrates among German precision metal fabricators and selected Japanese electronics assemblers with ISO 13485 medical device certification. Medical-grade 316L and 17-4 PH stainless steel draws from German and Japanese specialty mills, while petroleum-based polymer feedstocks for single-use barrels source from integrated petrochemical complexes in Germany and the United States. Single-source vulnerability in nickel and chromium alloy supply creates exposure to commodity price swings. Distribution runs through dental service organization central procurement offices in Texas and California, hospital-affiliated group purchasing organizations in Germany and France, and specialized dental distributors serving independent Japanese practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental service organization consolidation across Texas and California has shifted procurement leverage from individual clinicians to centralized buying committees, fragmenting traditional manufacturer-distributor relationships and compressing pricing power for undifferentiated instrument suppliers.
For Market Incumbents: Harden defensive positions through backward integration into medical-grade stainless steel supply chains near Stuttgart industrial zones, eliminating exposure to nickel price volatility. Deepen software validation competencies for smart syringe platforms as Bluetooth-enabled dose logging becomes standard in German and Japanese teaching institutions. Prioritize EUDAMED registration completion ahead of state dental board sterilization audit harmonization to capture compliance-driven replacement cycles. For New Entrants and Emerging Players: Establish a beachhead in Brazilian dental service chains through ANVISA regulatory harmonization with ISO standards, targeting São Paulo and Rio de Janeiro clinic networks with auto-disable device portfolios. Penetrate Southeast Asian public health procurement channels by leveraging WHO injection safety protocol adoption in emerging clinic networks. Lead with disposable safety syringe offerings that bypass legacy sterilization documentation requirements burdening reusable instrument competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision instrument fabricators with captive elastomer seal formulation capabilities and existing auto-disable mechanism production lines. Five-to-ten year viability hinges on REACH Annex XVII phthalate compliance and battery-operated aspiration-assist convergence in periodontal segments. Target acquisition archetypes include German mid-cap manufacturers with EU MDR Class IIa clearance pipelines and Japanese specialists with METI-approved electronic feedback systems. Monitor quarterly EUDAMED unique device identifier submission volumes and state dental board sterilization audit completion rates as inflection indicators for compliance-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Supply | Captive 316L and 17-4 PH alloy sourcing near Stuttgart eliminates nickel price exposure for barrel fabrication. |
| Smart Syringe Platform Development | Bluetooth-enabled dose logging addresses liability risk management in German periodontal specialist practices. |
| EUDAMED Registration Acceleration | Early compliance with EU MDR Class IIa unique device identifier requirements secures procurement eligibility. |
| Elastomer Seal Material Reformulation | REACH Annex XVII phthalate alternatives validation preserves plunger glide specifications for French distributors. |
| Battery-Operated Aspiration-Assist Launch | Pressure-sensing electronics target paresthesia risk correlation studies in Nagoya and Osaka specialist clinics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR EUDAMED registrations, OSHA enforcement incident reports, and ISO 7886-2 sterilization validation standards. Primary interviews engaged dental clinic procurement officers, hospital biomedical engineers, GPO contracts managers, and regulatory affairs specialists at precision instrument manufacturers. Secondary validation incorporated hospital procurement database analysis, dental service organization supply chain disclosures, and customs records for medical-grade stainless steel trade flows. Bottom-up demand modeling from clinic-level instrument replacement cycles triangulates against top-down market sizing from anesthesia cartridge consumption patterns.
Forecast inputs span product type segmentation across safety, auto-disable, and reusable architectures; technology tiers from mechanical through battery-operated systems; application specialization in periodontal, endodontic, and oral surgery procedures; and end-user categories including dental clinics, teaching institutions, and mobile outreach units. CAGRs derive from regression analysis of historical procurement volumes against regulatory mandate implementation timelines, with specific weighting for OSHA Bloodborne Pathogens Standard enforcement intensity and EU MDR transition completion rates across German, French, and Italian dental practices.
Macroeconomic conditions sit as an overlay; deviation in medical-grade stainless steel alloy prices, petroleum-based polymer feedstock costs, or central bank interest rate environments would shift the trajectory of capital-intensive battery-operated platform adoption. Forecasts reflect assumptions regarding regulatory harmonization timelines and procurement standardization mandates without guarantee of implementation pace. Quarterly review of EUDAMED registration completion rates, state dental board sterilization audit findings, and dental service organization procurement unbundling announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Laparoscopic Retrieval Bags Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Blood Collection Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market