
 Western Europe Sterile Gloves Market | 2026-2036
Western Europe Sterile Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Western Europe Sterile Gloves Market Analysis
Multi-source procurement among Western European hospital systems is recalibrating competitive dynamics across the sterile gloves supply base. Ansell Ltd leverages its manufacturing footprint to sustain premium positioning in surgical-grade nitrile. Cardinal Health Inc anchors its position through direct distribution contracts with national health services. MEDLINE INDUSTRIES competes on scale, extending broad catalog coverage across clinics and research labs.
Western Europe sterile gloves are single-use barrier devices manufactured from latex, nitrile, polyisoprene, or vinyl, typically meeting EN 455 and EN 374 standards for permeation resistance and sterility assurance; they serve to prevent pathogen transmission during invasive procedures and clinical examinations. Nitrile formulations now lead product-type demand due to latex allergy prevalence and superior chemical resistance, while polyisoprene gains traction in surgical applications where tactile sensitivity rivals natural rubber. Among end users, hospitals command the largest volume commitment, though research labs represent a faster-growing segment as biotechnology investment expands across the region.
The EU Medical Device Regulation and REACH framework govern material safety, biocompatibility, and post-market surveillance, compelling manufacturers to maintain exhaustive technical documentation and clinical evidence portfolios. EMA-aligned notified bodies conduct conformity assessments that determine market access for sterile gloves classified as Class IIa medical devices. Stakeholders must monitor evolving standard revisions and national health technology assessment criteria that increasingly weight lifecycle environmental impact alongside clinical performance.
Market Dynamics
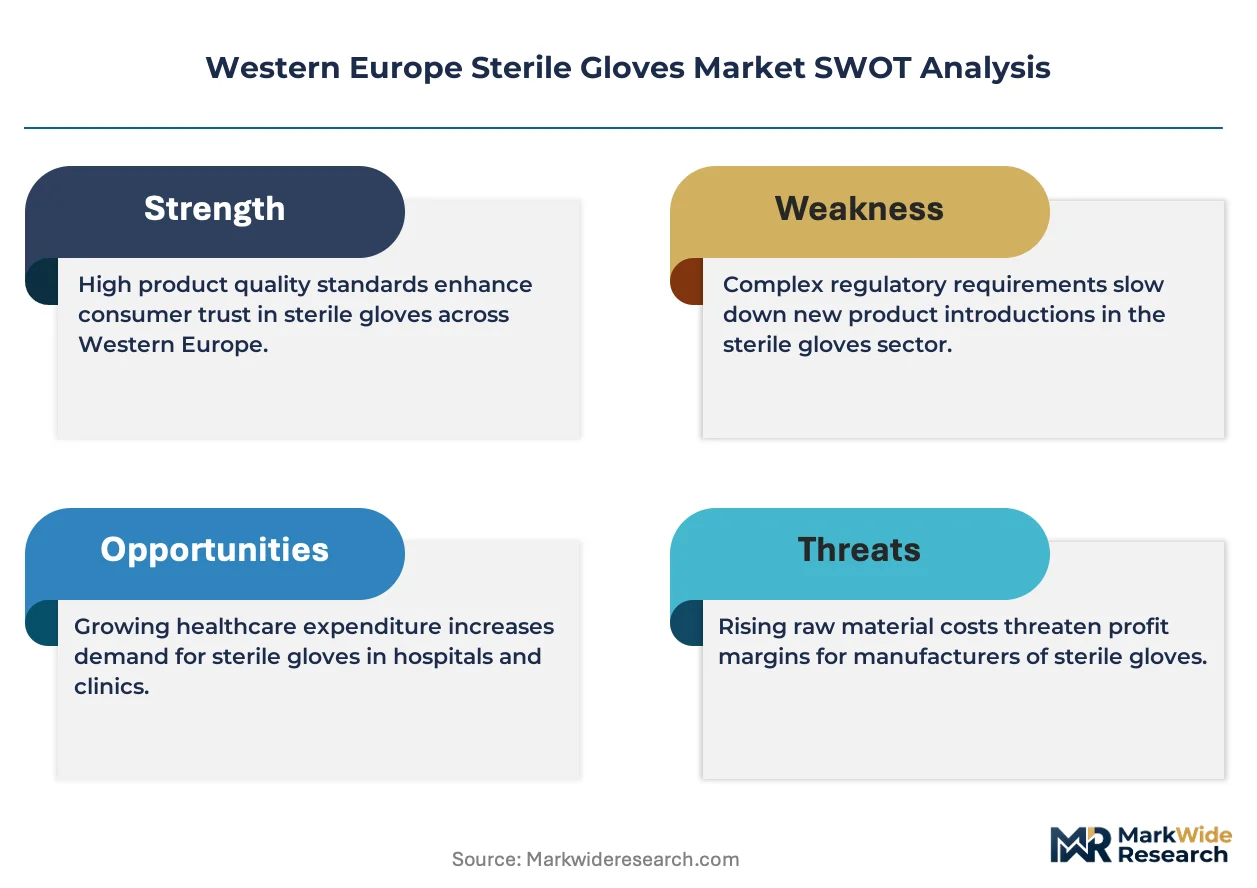
REACH and the EU Medical Device Regulation are forcing manufacturers to abandon latex formulations and rebuild supply chains around synthetic alternatives, compressing margins while elevating compliance costs across the sterile gloves value chain.
Growth Catalysts
- Nitrile Material Transition:Germany's surgical centers are accelerating procurement of nitrile sterile gloves as REACH restrictions on chemical sensitizers eliminate latex options from hospital tenders.
- EMA Conformity Pathways:Streamlined notified body assessments under the EU MDR are reducing time-to-market for Class IIa sterile glove submissions, expanding manufacturer participation.
- France Hospital Network Consolidation:Regional health authority mergers in France are creating larger procurement pools that favor suppliers with scale and documentation depth.
Market Restraints
- Butadiene Cost Volatility:Nitrile rubber feedstock prices fluctuate with petrochemical markets, squeezing compounders that lack long-term supply contracts.
- Asian Supply Concentration:Over 70 percent of nitrile glove manufacturing capacity sits in Malaysia and Thailand, exposing Western European buyers to shipping disruptions and currency swings.
- Biocompatibility Testing Bottlenecks:Extended cytotoxicity and sensitization studies under EN ISO 10993 delay product launches by 12-18 months for novel materials.
Strategic Opportunities
- Swiss Research Lab Expansion:Basel and Zurich biotech clusters are outpacing hospital growth in sterile glove consumption, rewarding specialized distributors with technical service capabilities.
- EU Green Deal Alignment:Manufacturers developing bio-based nitrile alternatives can access CSRD-linked procurement preferences in Netherlands and Belgium hospital systems.
- Direct Hospital Contracting:Bypassing traditional medical distributors through GPO partnerships is opening margin recovery paths for compliant manufacturers.
Industry Challenges
- Polymer Chemistry Talent Scarcity:Formulation expertise for nitrile-polyisoprene hybrids is concentrated among retiring specialists, constraining R&D pipelines.
- Legacy ERP Integration:Hospital procurement platforms require EDI connectivity that smaller glove manufacturers struggle to implement against tight deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Western Europe Sterile Gloves Market |
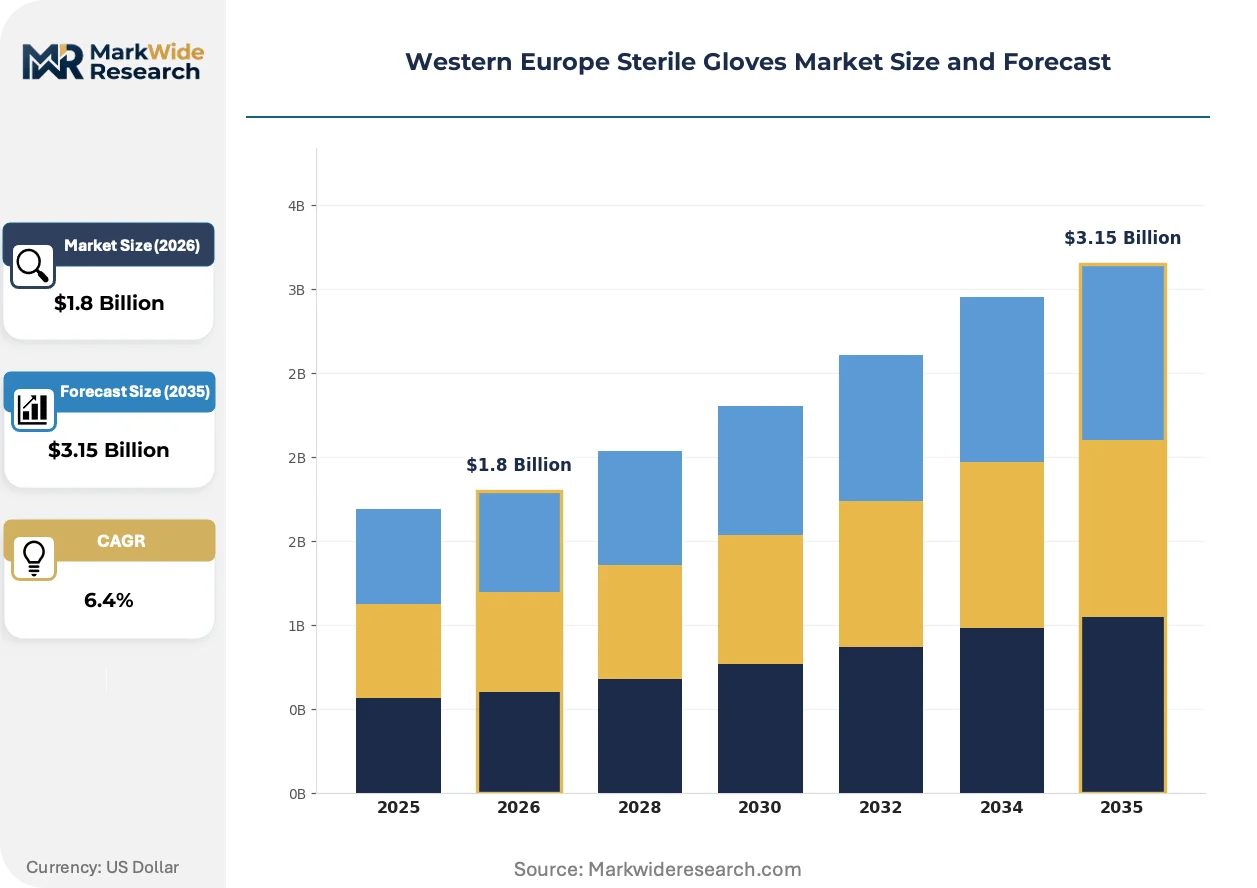
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex, Nitrile, Vinyl, Polyisoprene End User: Hospitals, Clinics, Research Labs, Home Care Application: Surgical, Examination, Dental, Laboratory Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Ansell Ltd, Cardinal Health Inc, MEDLINE INDUSTRIES, BERNER INTERNATIONAL GmbH, SHIELD SCIENTIFIC, MEDITRADE GmbH, TOP GLOVE CORPORATION BHD, KOSSAN RUBBER INDUSTRIES BHD, Semperit AG Holding, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Western Europe Sterile Gloves Market Emerging Trajectories
Synthetic material breakthroughs and regulatory digitization are compressing product development cycles while elevating performance benchmarks for sterile barrier devices across Western European healthcare networks.
Chlorinated nitrile formulations with enhanced tensile strength are electrifying surgical glove performance standards by delivering puncture resistance comparable to double-gloving protocols. German university hospitals are piloting these materials in orthopedic and cardiovascular theaters, replacing older nitrile grades within 18-month procurement windows. The technology is electrifying competitive positioning by enabling premium pricing for manufacturers that master chlorination chemistry without compromising tactile sensitivity.
REACH Annex XIV substance restrictions are eliminating certain plasticizers and accelerators from glove manufacturing, compelling reformulation of curing agents across the supply base. Compounders in Italy and Spain are investing in alternative vulcanization systems to maintain market access. Surgical glove lines containing restricted substances face phased withdrawal from German and French tenders starting 2026.
Consolidated purchasing consortia in France and Belgium are compressing supplier lists and demanding real-time inventory visibility through vendor-managed inventory programs. Traditional distributors with limited logistics integration are losing share to platform-enabled competitors. The shift is most pronounced in Paris and Brussels hospital networks, where procurement teams now prioritize supply chain transparency over brand heritage.
Western Europe Sterile Gloves Market Segmentation
Segmentation in the Western Europe sterile gloves market reveals how regulatory pressure and procurement consolidation are reshaping supplier priorities. Each dimension exposes different margin structures and compliance burdens that determine competitive viability.
Product Type:
Capital intensity varies sharply across polymer platforms, with nitrile and polyisoprene requiring specialized compounding equipment and cleanroom infrastructure that vinyl and latex lines avoid.
- Nitrile:Acrylonitrile-butadiene copolymer formulations deliver puncture resistance and chemical protection superior to natural rubber. German surgical centers in Bavaria and North Rhine-Westphalia are converting entire glove portfolios to nitrile as REACH Annex XVII restrictions on thiuram accelerators eliminate latex from tenders.
- Latex:Natural rubber formulations retain dominance in microsurgical applications where tactile sensitivity remains unmatched. French university hospitals in Paris and Lyon maintain latex lines for neurosurgery and ophthalmology despite allergy documentation requirements.
- Vinyl:Polyvinyl chloride gloves occupy economy-tier examination roles with minimal polymer investment.
- Polyisoprene:Synthetic isoprene polymers bridge the gap between latex sensitivity and nitrile stiffness for extended procedures.
Nitrile absorbs the bulk of installed capacity; polyisoprene is expanding most quickly.
End User:
Customer scale determines contract structure, with national health service frameworks demanding integrated supply chain visibility that smaller purchasers waive.
- Hospitals:Acute care facilities command volume commitments through multi-year framework agreements. France's regional health agency consolidations are compressing supplier lists to manufacturers with EMA-notified body certification and vendor-managed inventory capabilities.
- Research Labs:Biotechnology and pharmaceutical R&D facilities in Basel and Cambridge require specialized glove grades for containment protocols. Swiss and UK lab networks are outpacing hospital procurement growth as cell therapy manufacturing expands.
- Clinics:Outpatient and primary care settings purchase through group purchasing organizations with standardized specifications.
- Home Care:Post-acute and dialysis-at-home segments drive smaller-format packaging requirements.
Hospitals anchor procurement volume; research labs are climbing the fastest.
Application:
Performance certification tiers separate segments, with surgical applications requiring EN 455 and EN 374 compliance that examination grades bypass.
- Surgical:Sterile barrier devices for invasive procedures demand powder-free formulations with documented endotoxin limits. German orthopedic theaters are piloting chlorinated nitrile grades that eliminate double-gloving protocols without compromising tensile strength.
- Examination:Non-sterile and sterile variants for diagnostic contact carry lighter documentation burdens. France's general practitioner networks are consolidating purchases through regional procurement hubs that prioritize cost over performance differentiation.
- Dental:Oral surgery and hygiene protocols require specialized cuff lengths and textured fingertips.
- Laboratory:Biosafety level containment drives chemical permeation resistance specifications.
Surgical applications command premium positioning; laboratory use is gaining share fastest.
Distribution Channel:
Channel economics reflect logistics integration depth, with direct contracting capturing margin that wholesaler networks dissipate.
- Direct Sales:Manufacturer-to-hospital contracts bypass distributor markups for large volume accounts. Netherlands and Belgium hospital systems are mandating EDI connectivity and real-time inventory visibility that only direct relationships satisfy.
- Wholesalers:Medical supply distributors maintain broad catalog coverage for mid-tier clinics and smaller facilities. German regional distributors are losing share to platform-enabled competitors as procurement digitization accelerates.
- Online:E-procurement portals serve research labs and smaller clinics with fragmented purchasing patterns.
- Retail:Pharmacy and medical supply stores address home care and emergency replacement demand.
Direct sales channels dominate value capture; online platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Butadiene feedstock corridors through the Port of Rotterdam and Antwerp chemical clusters anchor Western Europe's sterile gloves supply architecture, with nitrile compounders clustering near these petrochemical gateways to minimize logistics friction.
Germany
Bavarian surgical centers and North Rhine-Westphalian hospital networks are converting entire glove portfolios to nitrile formulations. REACH Annex XVII restrictions on thiuram accelerators eliminate latex from public tenders, forcing procurement officers to rewrite supplier specifications. The Rhine-Ruhr industrial corridor hosts compounding facilities that serve these hospital systems with just-in-time delivery contracts.
France
Regional health agency consolidations in Île-de-France and Auvergne-Rhône-Alpes are compressing supplier lists to manufacturers with EMA-notified body certification. The EU Medical Device Regulation mandates exhaustive technical documentation that smaller compounders cannot sustain. Paris and Lyon university hospitals maintain specialized latex lines for neurosurgery despite allergy documentation burdens.
Netherlands
CSRD-linked procurement preferences in Randstad hospital systems reward manufacturers developing bio-based nitrile alternatives. The Dutch national health service mandates EDI connectivity and real-time inventory visibility that only direct manufacturer relationships satisfy. Rotterdam's chemical processing infrastructure supports local compounding operations for these sustainability-focused tenders.
Switzerland
Basel and Zurich biotech clusters are outpacing hospital procurement growth in sterile glove consumption. Swissmedic alignment with EMA pathways streamlines conformity assessments for Class IIa devices entering these research-intensive markets. Specialized distributors with technical service capabilities capture share in this high-specification segment.
Belgium
Brussels hospital networks prioritize supply chain transparency over brand heritage in consolidated purchasing consortia. The EU Green Deal framework shapes procurement criteria, with vendor-managed inventory programs becoming mandatory for framework agreement eligibility. Antwerp's petrochemical infrastructure feeds nitrile compounding operations serving these digitized procurement platforms.
Western Europe Sterile Gloves Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers rebuild supply chains around synthetic alternatives to latex. The vendor base organizes into three tiers: multinational medical device conglomerates with direct hospital contracting capabilities, mid-scale European compounders with regional EMA certification, and Asian volume producers supplying through distributor networks. Strategic archetypes include premium surgical-grade specialists, scale-driven examination glove suppliers, and research-lab-focused technical service providers. M&A activity and backward integration into nitrile compounding represent the dominant competitive moves as margins compress under regulatory compliance costs.
Among the multinational tier, Ansell Ltd and Cardinal Health Inc exemplify divergent positioning archetypes—one leveraging manufacturing footprint for premium surgical-grade positioning, the other anchoring through direct distribution contracts with national health services. MEDLINE INDUSTRIES occupies a scale-driven position competing on catalog breadth across clinics and research labs. European specialists including BERNER INTERNATIONAL GmbH, SHIELD SCIENTIFIC, and MEDITRADE GmbH represent the mid-tier certified compounder archetype with focused regional EMA alignment. Asian volume producers TOP GLOVE CORPORATION BHD, KOSSAN RUBBER INDUSTRIES BHD, and Semperit AG Holding serve distributor channels with cost-optimized examination and surgical grades.
| Leading Market Players |
|---|
| Ansell Ltd |
| Cardinal Health Inc |
| MEDLINE INDUSTRIES |
| BERNER INTERNATIONAL GmbH |
| SHIELD SCIENTIFIC |
| MEDITRADE GmbH |
| TOP GLOVE CORPORATION BHD |
| KOSSAN RUBBER INDUSTRIES BHD |
| Semperit AG Holding |
| Others |
Supply Flow & Price Mechanics
Butadiene feedstock costs cascade through nitrile compounding operations into three distinct pricing tiers for Western European hospital procurement officers. REACH compliance investments and EMA certification overhead concentrate margin pressure on mid-scale compounders serving regional tenders.
Pricing Analysis
Vendor-managed inventory programs bundle logistics and real-time stock visibility into surgical-grade contracts, while examination glove tenders remain unbundled commodity transactions. Three-tier pricing structure across premium chlorinated nitrile, standard nitrile, and economy vinyl levels separates EN 455-certified surgical lines from EN 374 examination grades. Pricing pressure stems from butadiene volatility and Asian import competition, compressing compounder margins. Research labs in Basel and Cambridge show lowest price sensitivity due to containment protocol requirements, while French regional health consortia drive hardest bargain negotiations.
Supply Chain Analysis
Reverse logistics flows for expired sterile inventory remain underdeveloped, with most hospitals disposing through medical waste contractors rather than manufacturer take-back programs. Nitrile manufacturing concentrates in Malaysia, Thailand, and Indonesia, with European compounding operations clustered near Rotterdam and Antwerp petrochemical gateways. Raw material dependencies span acrylonitrile, butadiene, and sulfur-based vulcanization accelerators. Single-source vulnerability runs through the Strait of Malacca shipping corridor. Distribution runs through direct manufacturer contracts for large hospital systems and wholesaler networks for mid-tier clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over nitrile compounding capacity and EMA-notified body certification determines long-term viability. Players are pursuing backward integration into butadiene supply contracts and chlorination chemistry expertise as the decisive upstream lever.
For Market Incumbents: To counter margin compression from REACH compliance costs and Asian import pricing, Ansell Ltd and Cardinal Health Inc should deepen captive nitrile compounding capacity in the Rhine-Ruhr corridor while acquiring specialized chlorination technology assets. Direct hospital contracting capabilities must expand to capture GPO consolidation benefits in France and Belgium. For New Entrants and Emerging Players: Swiss research lab distributors with technical service capabilities offer the most penetrable entry channel, as Basel and Zurich biotech clusters outpace hospital procurement growth. Specialized containment-grade glove lines for cell therapy manufacturing provide differentiation against commoditized surgical portfolios. Partnering with EMA-notified bodies early accelerates conformity assessment timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European compounders with existing EMA certification and regional hospital framework agreements in Germany and France. Long-term viability hinges on chlorination chemistry mastery and bio-based nitrile R&D pipelines. Practitioners should monitor CSRD-linked procurement preference adoption rates in Netherlands and Belgium hospital systems as inflection signals for sustainability premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Compounding | Captive butadiene supply contracts insulate margins from petrochemical volatility near Rotterdam. |
| EMA-Notified Body Certification Investment | Streamlined Class IIa conformity assessments accelerate market access for German surgical centers. |
| Chlorination Chemistry R&D Partnership | Enhanced tensile strength formulations command premium positioning in Bavarian orthopedic theaters. |
| Direct Hospital GPO Contracting | EDI-enabled inventory visibility satisfies Netherlands national health service procurement mandates. |
| Bio-Based Nitrile Alternative Development | CSRD-aligned formulations access preferential tender scoring in Belgian consolidated purchasing consortia. |
Methodological Framework
Trade databases, EMA medical device registration filings, and EU procurement tender records formed the secondary backbone for volume and value estimation. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and nitrile compounder technical directors validated supply-side capacity assumptions and demand patterns. Bottom-up hospital procurement data triangulated against top-down petrochemical feedstock consumption trends.
Historical trendline analysis of nitrile glove import volumes through Rotterdam and Antwerp established baseline growth trajectories across the analysis window. Segmentation modeling incorporated product type, end user, application, and distribution channel dimensions with regional regulatory cluster differentiation. CAGRs derived from polynomial curve-fitting of procurement volume trends, adjusted for REACH implementation phase-in effects and EU MDR transition timelines.
Several conditions sit outside the modeled scope, including sudden butadiene supply disruptions, accelerated REACH substance restrictions, and major Asian manufacturer capacity expansions. Forecasts reflect assumptions about EMA-notified body capacity and hospital procurement digitization adoption rates. Practitioners should monitor thiuram accelerator ban enforcement timelines and chlorinated nitrile clinical trial outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
US Hospital Consumables Market
Medical Supplies
Specimen Retrieval Bags Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Europe Ostomy Care and Accessories Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Medical Specialty Bags Market