
 Pharmacy Accessory Bagging System (PABS) Market | 2026-2036
Pharmacy Accessory Bagging System (PABS) Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacy Accessory Bagging System (PABS) Market Analytics
The gap between premium automated bagging lines and commodity manual systems is repositioning competitive dynamics across pharmacy fulfillment. Medical Packaging Inc. leverages its MPI-certified automation platforms to dominate hospital central fill operations. Sharp Packaging Systems anchors the retail pharmacy segment with specialized compliance-ready bagging configurations. McKesson Corporation extends distribution control by bundling bagging hardware with its pharmaceutical supply contracts.
Pharmacy Accessory Bagging Systems are automated or semi-automated units that sort, label, seal, and dispense medication into purpose-built bags at throughput rates exceeding 1,000 scripts per hour in high-volume configurations. These systems integrate barcode verification, tamper-evident sealing, and patient-specific labeling to ensure chain-of-custody integrity from pharmacist to patient. The end-user dimension splits sharply: hospital pharmacies command the highest automation penetration due to 24/7 dispensing volume and Joint Commission accountability requirements, while retail pharmacies still operate substantial manual bagging footprints that face gradual replacement. Material selection is bifurcating as well, with recyclable materials gaining formulary preference against conventional plastic where health systems publish sustainability scorecards.
FDA enforcement of Drug Supply Chain Security Act track-and-trace provisions and USP <800> hazardous drug containment standards directly shape bagging system specifications, particularly mandating integrated verification scanners and specialized containment interfaces. State boards of pharmacy in California, New York, and Texas layer additional labeling and patient-counseling documentation requirements that vendors must accommodate in regional system configurations. Stakeholders should monitor whether CMS reimbursement shifts toward outcomes-based pharmacy models will accelerate capital deployment into fully integrated bagging-to-dispensing workflows or prolong existing equipment lifecycles through retrofit strategies.
Market Dynamics
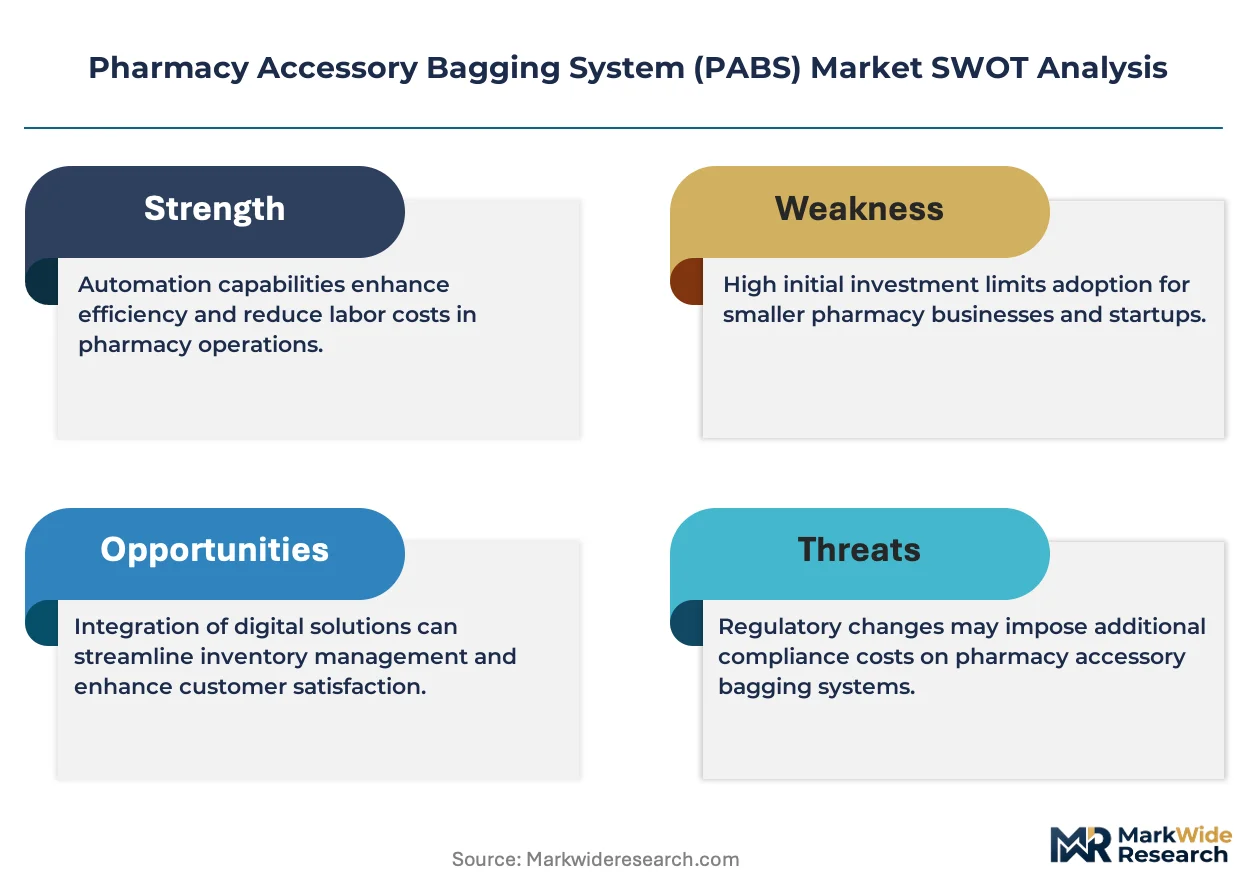
Hospital pharmacy consolidation into centralized fill operations is compressing equipment procurement cycles and forcing vendors to bundle verification software with hardware platforms.
Growth Catalysts
- USP <800> hazardous drug containment:The standard mandates specialized bagging interfaces for oncology and cytotoxic medications, compelling hospital pharmacies to upgrade legacy systems.
- California health system density:Kaiser Permanente, Cedars-Sinai, and Stanford Health Care operate high-throughput central fill facilities that normalize automation investments for peer institutions.
- Barcode verification integration:Track-and-trace requirements under DSCSA are electrifying demand for bagging systems with embedded 2D scanner arrays.
Market Restraints
- Stainless steel and medical-grade polymer costs:Input material volatility compresses margin structures for mid-tier equipment vendors unable to pass through price adjustments.
- Single-source component dependencies:Precision servo motors and thermal printheads concentrate supply in German and Japanese manufacturing clusters, exposing lead time risk.
- Substitution by pouch packaging:Unit-dose pouch systems for long-term care facilities bypass bagging entirely in medication adherence applications.
Strategic Opportunities
- Texas Medicaid expansion counties:Rio Grande Valley and El Paso health districts are building de novo pharmacy infrastructure without legacy equipment constraints.
- 340B contract pharmacy growth:Eligible entities are electrifying demand for compliance-ready bagging configurations that document chain-of-custody for manufacturer rebate programs.
- Cloud-based fleet management:Remote diagnostics and predictive maintenance modules create recurring revenue attachment to hardware sales.
Industry Challenges
- Pharmacy informatics specialist scarcity:Health systems struggle to staff integration projects connecting bagging systems to EHR and inventory management platforms.
- FDA 510(k) clearance timelines:Novel verification scanner configurations face 12-18 month regulatory review periods that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacy Accessory Bagging System (PABS) Market |
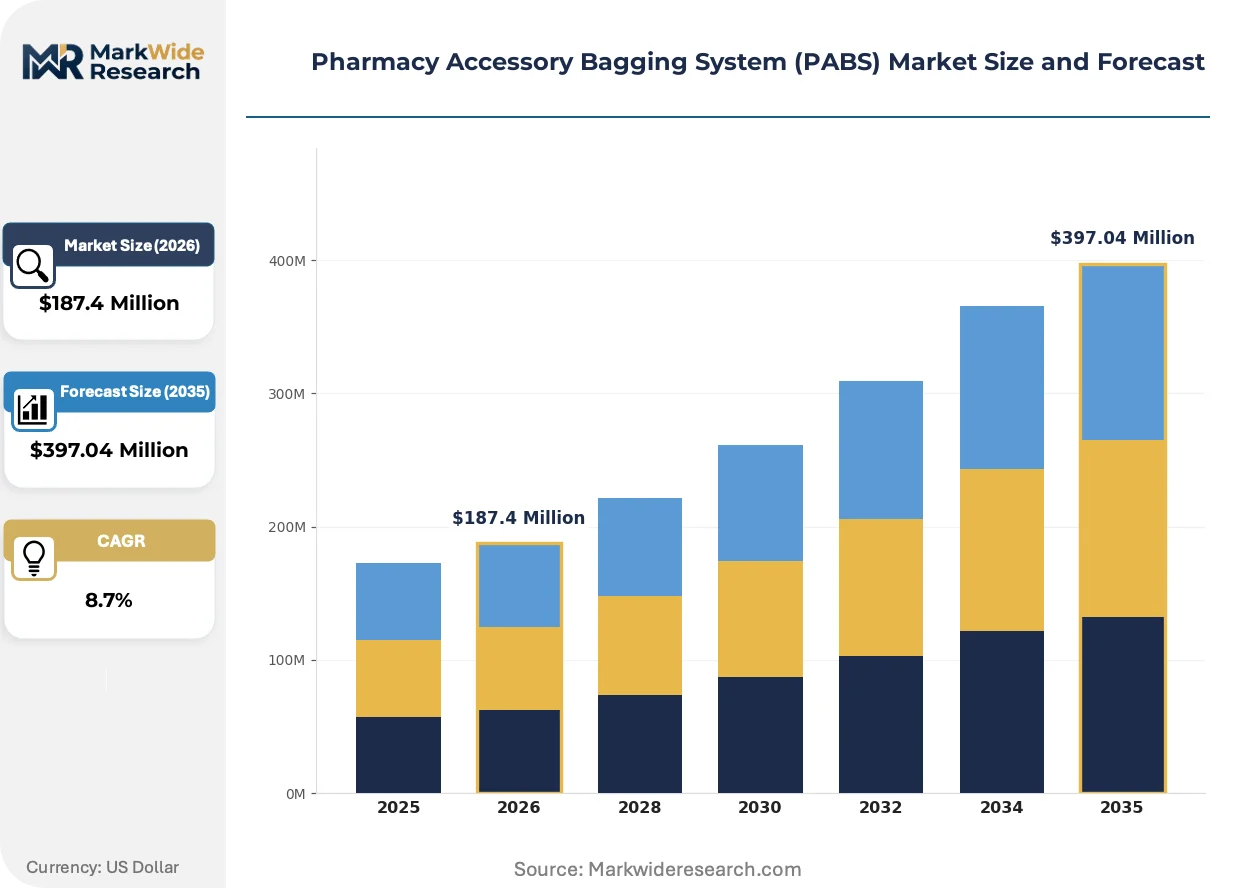
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Custom Bags, Biodegradable Bags, Child-resistant Bags Material: Plastic, Paper, Polyester, Recyclable Materials End User: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Specialty Pharmacies Delivery Mode: In-store, Home Delivery, Digital Platforms, Automated Dispensing |
| Companies Covered | Medical Packaging Inc. (MPI), Sharp Packaging Systems, McKesson Corporation, Becton Dickinson and Company, Omnicell Inc., ARxIUM, Swisslog Holding Ltd., Syntegon Technology GmbH, ScriptPro LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacy Accessory Bagging System (PABS) Market Evolving Landscape
Automation vendors are electrifying their platforms with AI-driven vision systems and sustainability-focused material science, reshaping how pharmacies justify capital expenditure.
Vision-guided robotic pick-and-place modules are electrifying bagging throughput in high-volume hospital central fills. Systems now achieve sub-100 millisecond cycle times for irregular-shaped items like inhalers and insulin pens. This compression is electrifying the economic case for full automation in facilities previously served by semi-automated lines.
FDA enforcement of DSCSA electronic pedigree requirements is forcing bagging system architectures to embed EPCIS-compliant event capture. Manufacturers must now certify that every scan, seal, and label application generates auditable transaction records. Hospital pharmacies in Florida and New York are prioritizing vendors with pre-validated software stacks to accelerate deployment timelines.
Consolidated health systems are electrifying procurement toward enterprise-wide standardization agreements. Single-source bagging contracts spanning inpatient, outpatient, and mail-order operations are displacing site-by-site equipment decisions. This concentration is most visible in California, where Sutter Health and Dignity Health operate unified pharmacy technology platforms across dozens of facilities.
Pharmacy Accessory Bagging System (PABS) Market Segmentation
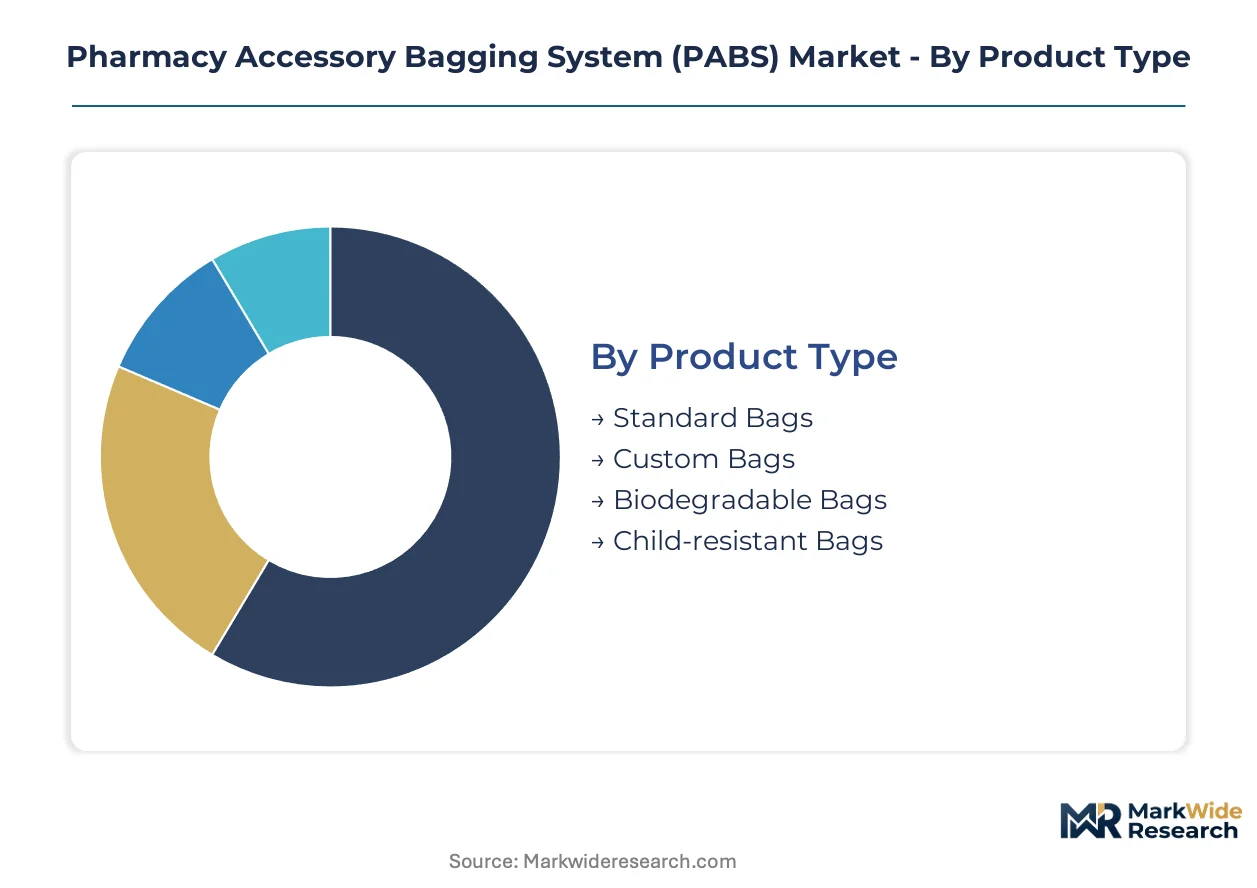
Equipment refresh cycles and regulatory compliance deadlines force distinct purchasing patterns across bagging system categories. Segmentation reveals which product tiers capture capital allocation versus maintenance spending.
Product Type:
Upgrade momentum concentrates where USP <800> mandates and DSCSA serialization deadlines collide with aging installed bases.
- Standard Bags:Polyethylene constructions with pre-printed pharmacy branding dominate high-volume retail chains. Kaiser Permanente and CVS Health standardize these across central fill networks to minimize SKU complexity and procurement overhead.
- Custom Bags:Hospital systems commission tamper-evident configurations with integrated barcode panels and color-coded hazard warnings. Stanford Health Care and Cedars-Sinai deploy these for oncology units where USP <800> traceability requirements demand patient-specific identifiers.
- Biodegradable Bags:PLA and starch-based films serve sustainability scorecard commitments at California health systems.
- Child-resistant Bags:ASTM D3475-certified zipper and slider mechanisms address pediatric safety mandates in Texas and Florida Medicaid programs.
Standard Bags sit at the top of the volume ranking, with Custom Bags climbing the fastest.
Material:
Raw material cost tiers are forcing procurement teams to rebalance performance specifications against sustainability commitments.
- Plastic:LDPE and HDPE formulations retain dominance in high-throughput hospital central fills. The material's moisture barrier properties and thermal seal compatibility support 1,000+ script-per-hour automation lines at Sutter Health facilities.
- Recyclable Materials:Mono-material PE constructions qualify for store-drop recycling streams. Dignity Health's California network mandates these for outpatient pharmacy operations to meet enterprise carbon reduction targets.
- Paper:Kraft and glassine options serve short-cycle medication courses in European hospital pharmacies subject to ECHA packaging waste directives.
- Polyester:PET films provide dimensional stability for automated handling of irregular-shaped inhalers and insulin pens.
Plastic commands the highest procurement volume, while Recyclable Materials gain share fastest among systems publishing sustainability metrics.
End User:
Capital deployment intensity varies sharply by accountability structure and dispensing volume economics.
- Hospital Pharmacies:24/7 central fill operations with Joint Commission oversight drive automation penetration. These facilities integrate bagging systems with robotic dispensing cabinets and EHR platforms, requiring FDA 510(k)-verified software stacks.
- Retail Pharmacies:CVS, Walgreens, and Rite Aid operate mixed fleets of automated and manual bagging. DSCSA compliance deadlines are accelerating replacement of legacy thermal printers and standalone sealers.
- Specialty Pharmacies:Limited-distribution oncology and rare-disease medications demand cold-chain-compatible bagging with temperature-logging interfaces.
- Online Pharmacies:Mail-order fulfillment centers prioritize throughput over verification density, favoring semi-automated lines.
Hospital Pharmacies anchor capital expenditure, with Specialty Pharmacies expanding most quickly on 340B contract pharmacy growth.
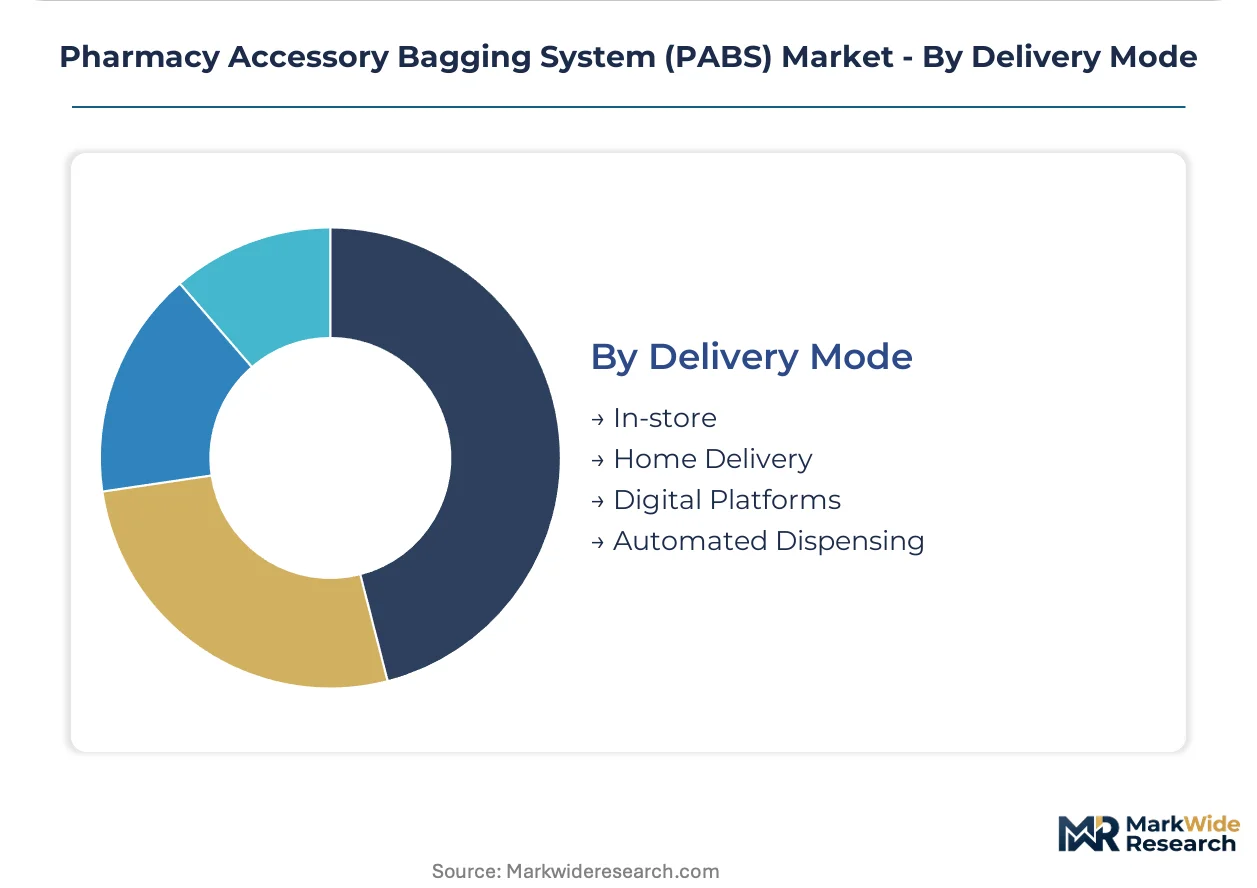
Delivery Mode:
Patient touchpoint location determines bagging system specifications for chain-of-custody documentation.
- In-store:Counter-top bagging units with integrated patient-facing displays dominate Walgreens and CVS locations. These configurations support state-mandated counseling documentation in California, New York, and Texas.
- Home Delivery:Mail-order operations at Express Scripts and OptumRx deploy high-speed lines with automated manifest generation for UPS and FedEx handoff.
- Automated Dispensing:Hospital locker systems and retail pickup kiosks require tamper-evident bags with QR-coded retrieval authentication.
- Digital Platforms:Telehealth-integrated pharmacies use bagging systems with photo-documentation for remote pharmacist verification.
In-store retains the largest installed base, while Home Delivery shows the steepest expansion trajectory on mail-order pharmacy growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy automation specialists cluster in health system-dense corridors where USP 800 and DSCSA enforcement create concentrated upgrade demand. California, Texas, and Florida anchor North American deployment, while Germany and Japan supply precision automation components.
United States
Kaiser Permanente and Sutter Health operate high-throughput central fill facilities that normalize automation investments for peer institutions. FDA serialization mandates under DSCSA and USP 800 hazardous drug containment standards drive system replacements. The California-Texas-Florida corridor concentrates procurement where health system consolidation accelerates capital deployment.
Germany
Precision servo motor and thermal printhead manufacturers anchor component supply for global bagging system vendors. ECHA packaging waste directives push European hospital pharmacies toward recyclable material configurations. The Baden-Württemberg industrial cluster houses automation engineering firms serving pharmaceutical fulfillment applications.
Japan
PMDA quality system regulations shape verification scanner specifications for export-oriented equipment manufacturers. METI industrial automation initiatives support robotics integration into pharmacy fulfillment workflows. The Nagoya-Tokyo manufacturing belt produces high-reliability motion control systems for pharmaceutical packaging lines.
China
NMPA medical device registration requirements extend to automated dispensing equipment with verification capabilities. Domestic health system modernization programs in tier-one cities accelerate central pharmacy investments. The Yangtze River Delta concentration of pharmaceutical manufacturing drives demand for compliance-ready bagging configurations.
India
CDSCO medical device rules increasingly align with FDA quality standards for automated pharmacy equipment. Hospital pharmacy consolidation in metropolitan health networks creates procurement scale for automation vendors. The Maharashtra-Gujarat pharmaceutical manufacturing corridor generates demand for export-compliant packaging systems.
Pharmacy Accessory Bagging System (PABS) Market Competitive Landscape
Top-tier vendors anchor hospital central fill automation, while mid-tier specialists serve retail pharmacy retrofit cycles. The market structure stratifies across three tiers: integrated healthcare technology conglomerates, dedicated packaging automation firms, and regional equipment fabricators. Strategic archetypes include hardware-software bundlers, component specialists, and compliance-focused configurators. Dominant competitive moves encompass enterprise-wide standardization contracts and predictive maintenance service attachments.
Within the integrated healthcare technology tier, McKesson Corporation and Omnicell Inc. exemplify platform vendors bundling bagging hardware with pharmaceutical supply and inventory management ecosystems. Medical Packaging Inc. (MPI) anchors the dedicated automation specialist archetype, while Sharp Packaging Systems occupies a position bridging retail pharmacy compliance requirements with high-volume throughput engineering. These three firms collectively represent the competitive vectors shaping procurement decisions across hospital and retail pharmacy segments.
| Leading Market Players |
|---|
| Medical Packaging Inc. (MPI) |
| Sharp Packaging Systems |
| McKesson Corporation |
| Becton Dickinson and Company |
| Omnicell Inc. |
| ARxIUM |
| Swisslog Holding Ltd. |
| Syntegon Technology GmbH |
| ScriptPro LLC |
| Others |
Value Network & Pricing Analysis
AI-driven vision system integration is compressing per-unit automation costs while concentrating procurement leverage among health systems with enterprise standardization mandates. This dual compression simultaneously reshapes vendor margin structures and buyer negotiating positions across hospital central fill and retail pharmacy segments.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes competitive positioning across the market. Hardware-software subscription tiers dominate hospital central fill contracts, while retail pharmacies favor per-unit transactional models for bagging consumables. Price differentiation rests on FDA 510(k) certification tier and embedded verification scanner density. Pricing pressure stems from stainless steel and medical-grade polymer input volatility. Retail pharmacy chains exhibit highest price sensitivity due to mixed automation footprints, while consolidated health systems leverage volume scale for preferential terms.
Supply Chain Analysis
Warehouse-distribution layer configurations follow hub-and-spoke patterns anchored in California, Texas, and Florida health system clusters. Precision servo motors and thermal printheads draw from German and Japanese manufacturing belts. Raw material dependencies center on medical-grade LDPE, HDPE, and recyclable mono-material PE formulations. Single-source component vulnerability in motion control systems exposes lead time risk. Distribution runs through pharmaceutical supply distributors and direct health system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cloud-based fleet management attachments and premium-tier biodegradable bagging configurations. Cost compression in servo motor integration enables tier upgrades without proportional price increases.
For Market Incumbents: Cement enterprise-wide standardization contracts across inpatient, outpatient, and mail-order pharmacy operations. Deepen backward integration into verification scanner manufacturing to reduce Japanese component dependency. Defend against pouch packaging substitution in long-term care by emphasizing USP 800 compliance documentation. For New Entrants and Emerging Players: USP 800 in the United States opens a window for specialized hazardous drug containment interfaces. Target Texas Medicaid expansion counties and 340B contract pharmacy growth corridors lacking legacy equipment constraints. Pursue cloud-native fleet management modules as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier equipment fabricators with regional health system relationships but limited software capabilities. Long-term viability favors vendors with validated EHR integration stacks and recurring revenue attachments. Monitor FDA 510(k) clearance timelines as the critical inflection signal for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Fleet Management Platform | Remote diagnostics modules at Sutter Health generate recurring revenue beyond hardware sales. |
| Biodegradable Material Certification | PLA and starch-based films satisfy Dignity Health enterprise carbon reduction commitments. |
| Enterprise Standardization Contract | Single-source agreements spanning Kaiser Permanente facilities displace site-by-site procurement. |
| Verification Scanner Integration | EPCIS-compliant event capture satisfies DSCSA enforcement at Florida hospital pharmacies. |
| Predictive Maintenance Module | AI-driven downtime prevention reduces total cost of ownership in 24/7 central fill operations. |
Research Methodology
Direct dialogue with hospital pharmacy directors, retail chain procurement officers, automation vendor sales executives, and GPO contracts managers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, USP documentation, hospital procurement databases, and CMS Medicare pharmacy data. Bottom-up equipment shipment analysis and top-down health system capital expenditure triangulation anchored market sizing.
Bottom-up segmentation by product type, material grade, end-user facility class, and delivery mode informed volume projections across the analysis window. CAGR derivation weighted equipment refresh cycles against regulatory compliance deadlines. Forecast inputs incorporated DSCSA serialization phase-in schedules and USP 800 enforcement intensity by state pharmacy board.
Revisions become necessary when FDA regulatory timelines extend, health system consolidation accelerates beyond modeled rates, or input material costs destabilize vendor pricing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Combat Dressing Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Port Access Needles Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Mortuary Bags Market