
 Cubitainer Market | 2026-2036
Cubitainer Market Size, Share, and Industry Trends Forecast 2026-2036
Cubitainer Market Analysis
Polyethylene terephthalate (PET) is pivoting toward multilayer coextrusion films in cubitainer construction, replacing single-layer HDPE across pharmaceutical and chemical applications where barrier performance commands premium positioning. Scholle IPN leverages its bag-in-box heritage to sustain dominance in liquid dispensing fitments. Smurfit Kappa anchors European supply through integrated corrugated outer-box production paired with flexible inner bladders. DS Smith differentiates via lightweight composite designs that reduce freight costs for agricultural chemical distributors.
A cubitainer is a collapsible, rectangular liquid container comprising an inner flexible plastic bladder encased in a corrugated fiberboard or plastic outer box, typically manufactured through blow molding, form-fill-seal, or thermoforming processes with capacities ranging from 5 to 50 liters. Its primary purpose is to transport and dispense bulk liquids while minimizing residual product, reducing storage footprint, and enabling one-way disposal compared to rigid intermediate bulk containers. Standard cubitainers occupy the mature volume tier for food-grade syrups and edible oils, while insulated variants capture expanding margin pools in temperature-sensitive pharmaceutical logistics. Custom configurations represent the fastest-growing segment as chemical formulators specify proprietary valve systems and UN-certified stacking configurations.
FDA 21 CFR regulations for food-contact substances and pharmaceutical packaging materials shape material selection and migration testing protocols for cubitainer manufacturers serving US markets. REACH and EU Packaging and Packaging Waste Directive compliance requirements in Europe mandate recyclability thresholds and restricted substance limits that filter market access for non-compliant suppliers. EMA good distribution practice guidelines for medicinal products further tighten secondary packaging performance standards. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based material certification schemes to align procurement and R&D decisions with shifting compliance landscapes.
Market Dynamics
Multilayer coextrusion technology is compressing material hierarchies in pharmaceutical and chemical packaging, forcing HDPE suppliers to defend position through cost engineering as PET barrier films capture temperature-sensitive logistics contracts.
Growth Catalysts
- FDA 21 CFR serialization mandates:Pharmaceutical distributors now require traceable secondary packaging for liquid APIs, expanding cubitainer procurement for lot-level tracking compliance.
- German chemical manufacturing clusters:BASF and Bayer supplier networks in Ludwigshafen and Leverkusen drive specialized UN-certified container specifications for agrochemical formulations.
- Insulated bladder technology:Phase-change material integration enables 2-8°C cold chain maintenance for biologics transport without active refrigeration systems.
Market Restraints
- Corrugated fiberboard input volatility:Kraft pulp price swings from Scandinavian mills compress outer-box margins for integrated manufacturers.
- Single-source fitment dependency:Scholle IPN's patent estate on aseptic dispensing valves creates supply concentration risk for European pharmaceutical packagers.
- HDPE barrier limitations:Oxygen transmission rates above 0.5 cc/m²/day disqualify single-layer constructions from EMA good distribution practice guidelines for oxidative-sensitive injectables.
Strategic Opportunities
- Indian pharmaceutical export corridor:CDSCO alignment with ICH Q1A stability guidelines creates demand for validated temperature-monitoring cubitainer systems in Mumbai and Hyderabad formulation hubs.
- Bio-based PE certification:ISCC PLUS chain-of-custody standards open premium positioning for agricultural chemical distributors serving EU Green Deal procurement mandates.
- Smart label integration:NFC-enabled temperature loggers combined with blockchain verification are electrifying traceability offerings for high-value biologics shipments.
Industry Challenges
- Multilayer coextrusion technician scarcity:Operating seven-layer blown film lines requires specialized polymer rheology expertise concentrated among German and Austrian equipment specialists.
- UN 4G certification timelines:Stacking test protocols and drop-test validations for custom valve configurations extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cubitainer Market |
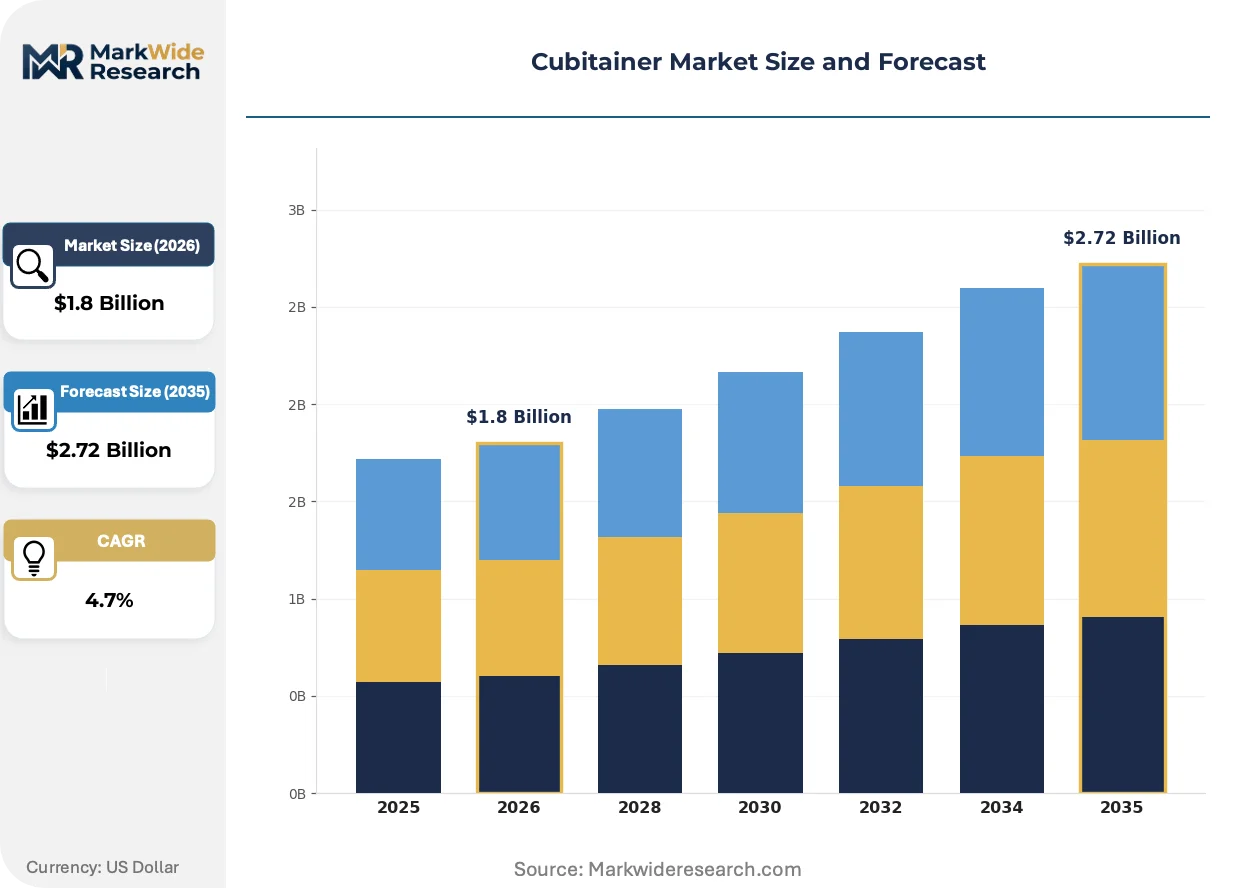
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cubitainers, Insulated Cubitainers, Custom Cubitainers, Collapsible Cubitainers Material: Plastic, Glass, Composite, Metal End User: Food Industry, Chemical Industry, Pharmaceutical Sector, Agriculture Capacity: 5 Liters, 10 Liters, 20 Liters, 50 Liters |
| Companies Covered | Smurfit Kappa, Sealed Air Corporation, DS Smith, Liqui-Box, Scholle IPN, Zacros America, CDF Corporation, Rapak, Changzhou Sanjie Plastic Products Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cubitainer Market Emerging Trajectories
Material science breakthroughs and regulatory serialization mandates are compressing traditional packaging hierarchies, creating openings for barrier-engineered flexible systems to displace rigid IBCs in premium pharmaceutical and chemical logistics.
Ethylene vinyl alcohol copolymer interlayers in five-layer PET structures are electrifying oxygen barrier performance for parenteral solutions. Contract packagers serving Novartis and Roche distribution networks are specifying these constructions for 24-month shelf-life extensions. The technology is compressing aluminum-laminated pouch demand in European temperature-controlled logistics.
EMA Annex 21 serialization requirements for secondary packaging are forcing retrofits of legacy form-fill-seal lines. German and Swiss pharmaceutical logistics operators now mandate 2D matrix codes on every cubitainer outer box for end-to-end traceability. Smaller contract manufacturers in Eastern Europe are consolidating to amortize compliance capital expenditures.
Consolidated buying desks at Sanofi and Merck KGaA are unbundling container procurement from freight contracts, creating direct supplier relationships that bypass traditional distribution intermediaries. Category managers now negotiate bladder specifications, outer-box print standards, and temperature-monitoring subscriptions as separate line items. This pattern is most visible in Rhine-Ruhr chemical logistics corridors serving Benelux distribution hubs.
Cubitainer Market Segmentation
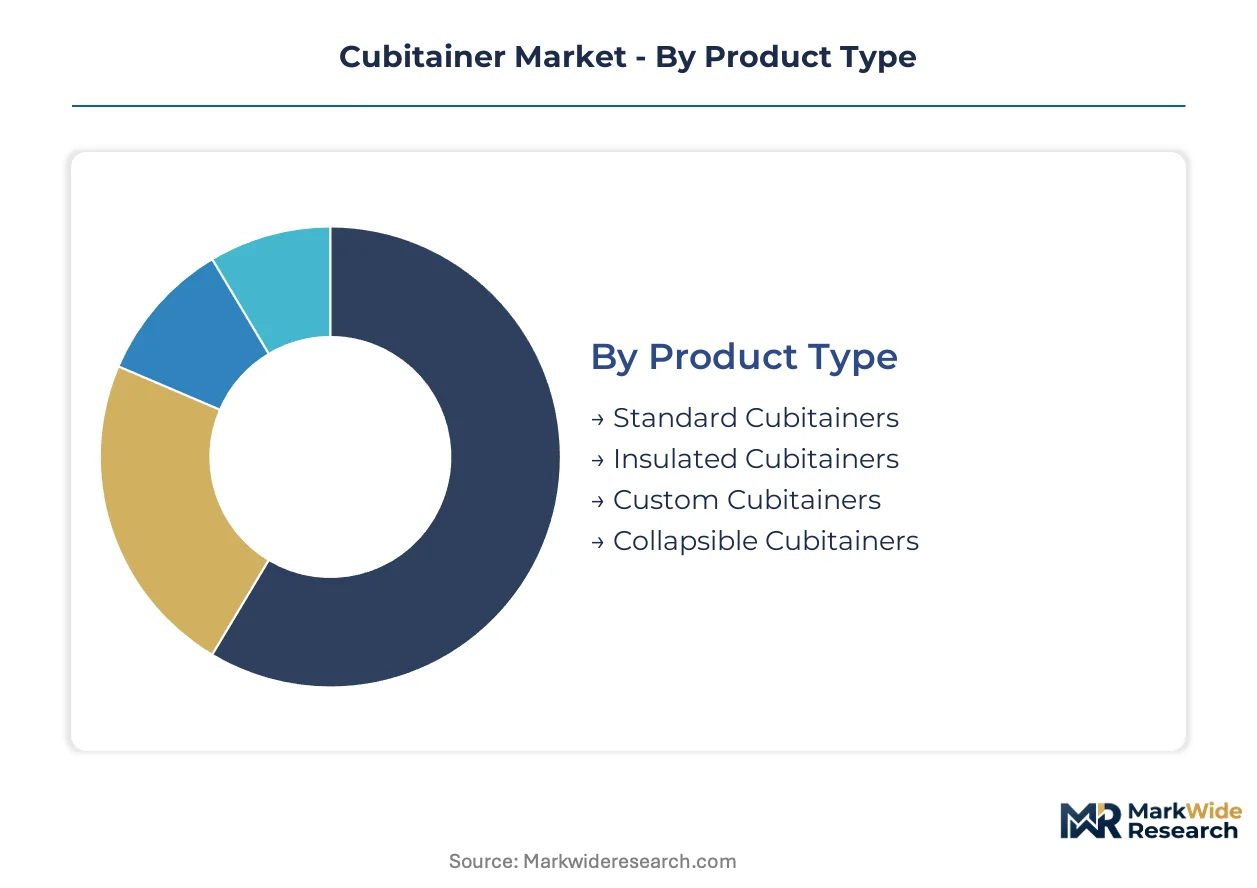
Cubitainer procurement patterns diverge sharply between commodity liquid logistics and validated cold-chain pharmaceutical distribution. Material specifications, capacity configurations, and regulatory certification tiers create distinct margin pools that reshape supplier positioning across end-use verticals.
Product Type:
Customization intensity spans from off-the-shelf food-grade formats to engineered pharmaceutical systems with integrated temperature monitoring.
- Standard Cubitainers:Single-layer HDPE bladders paired with corrugated outer boxes dominate edible oil and syrup logistics. German food manufacturers in Hamburg and Munich procurement clusters specify these for high-volume, short-shelf-life liquid transport where barrier performance requirements remain minimal.
- Insulated Cubitainers:Phase-change material integration and multilayer PET-EVOH constructions enable passive 2-8°C maintenance for biologics. Swissmedic-validated systems from Basel-area contract packagers are displacing active refrigerated containers in European parenteral distribution networks.
- Custom Cubitainers:Proprietary valve geometries and UN 4G-certified stacking configurations serve agrochemical formulators. Bayer supplier networks in Leverkusen specify these for hazardous material compliance.
- Collapsible Cubitainers:Reduced return freight costs drive adoption among French wine cooperatives and Italian olive oil exporters prioritizing circular logistics.
Most installed capacity flows through Standard Cubitainers. Expansion is steepest in Insulated Cubitainers.
Material:
Barrier performance hierarchies and recyclability mandates are compressing traditional material preferences across regulatory jurisdictions.
- Plastic:HDPE remains dominant for food-contact applications. PET multilayer coextrusion with EVOH interlayers is capturing pharmaceutical share due to oxygen transmission rates below 0.1 cc/m²/day required for oxidative-sensitive injectables under EMA guidelines.
- Glass:Borosilicate and soda-lime formats persist in parenteral solutions requiring absolute oxygen impermeability. Swiss and German compounding pharmacies specify these for light-sensitive biologics despite weight penalties.
- Composite:Lightweight fiber-reinforced designs reduce freight costs for agricultural chemical distributors serving Benelux markets.
- Metal:Stainless steel cubitainer variants retain niche positioning for solvent-based coatings and flammable chemical transport under ATEX directives.
Plastic commands the largest production footprint. Composite formulations are climbing fastest as freight cost pressures intensify.
End User:
Regulatory stringency and product value density create divergent procurement specifications across vertical demand pools.
- Food Industry:FDA 21 CFR food-contact compliance and migration testing protocols govern material selection. German edible oil processors and Dutch dairy ingredient suppliers drive volume procurement of standard HDPE configurations.
- Chemical Industry:UN-certified constructions with specialized valve systems serve BASF and Covestro distribution networks. REACH compliance and restricted substance limits filter supplier access in European markets.
- Pharmaceutical Sector:EMA good distribution practice guidelines and serialization mandates reshape secondary packaging requirements. CDSCO-aligned Indian export corridors are emerging as validation-intensive demand centers.
- Agriculture:Bio-based PE certification under ISCC PLUS standards opens premium positioning for EU Green Deal procurement mandates serving French and German agrochemical distributors.
Chemical Industry absorbs the greatest material tonnage. Pharmaceutical Sector applications are expanding most quickly.
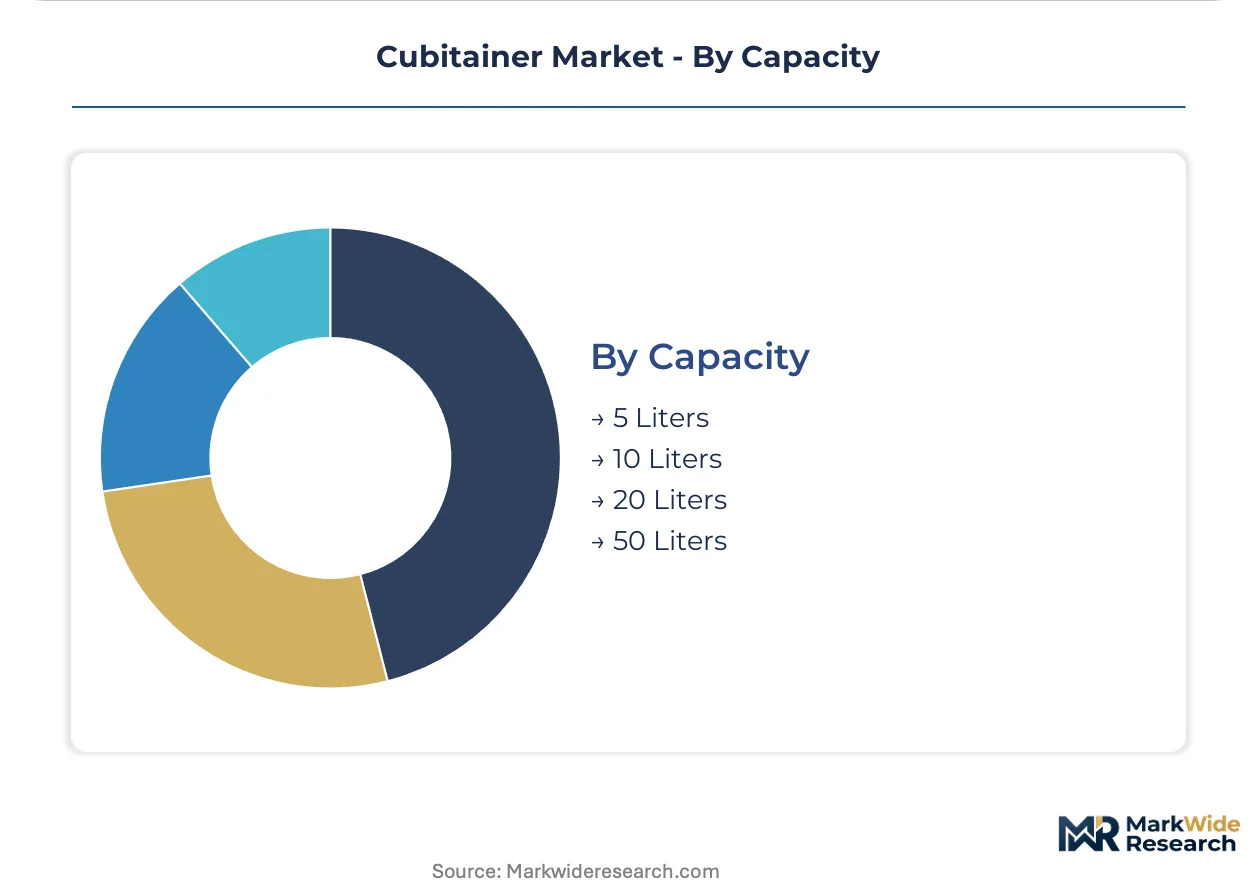
Capacity:
Volume configurations align with handling infrastructure, regulatory thresholds, and last-mile logistics constraints across end-use applications.
- 5 Liters:Compact formats suit laboratory-scale chemical distribution and specialty pharmaceutical sampling programs. Swiss and German clinical trial logistics operators specify these for investigator-site shipments.
- 10 Liters:Mid-range capacity balances handling efficiency with residual minimization for food ingredient and cosmetic precursor transport.
- 20 Liters:Standard palletization optimization drives adoption across European chemical distribution networks serving automotive coatings and industrial adhesives.
- 50 Liters:Maximum single-person handling limits define this tier for agricultural chemical formulations and bulk food syrup logistics in French and Italian processing facilities.
20 Liter configurations dominate installed throughput. 5 Liter formats are gaining share fastest in pharmaceutical validation workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr chemical corridor anchors cubitainer procurement intensity, with Ludwigshafen and Leverkusen manufacturing clusters driving specialized UN-certified container specifications for temperature-sensitive liquid logistics.
Germany
BASF and Bayer supplier networks in North Rhine-Westphalia sustain demand for custom valve configurations and multilayer barrier constructions. REACH compliance and EU Packaging and Packaging Waste Directive recyclability thresholds filter supplier access, favoring integrated manufacturers with in-house corrugated production. The Ludwigshafen chemical park alone accounts for substantial specialized procurement volumes.
United States
FDA 21 CFR serialization mandates for pharmaceutical secondary packaging expand cubitainer adoption for lot-level traceability compliance. Food-contact substance regulations govern material selection for edible oil and syrup logistics concentrated in Midwest processing facilities. California and Texas distribution hubs drive West Coast and Gulf Coast procurement clusters respectively.
Switzerland
Swissmedic validation requirements for temperature-controlled pharmaceutical distribution elevate insulated cubitainer specifications. Basel-area contract packagers specify phase-change material integration for passive 2-8°C maintenance of parenteral solutions. The country's precision logistics infrastructure supports premium positioning for barrier-engineered flexible systems.
India
CDSCO alignment with ICH Q1A stability guidelines creates demand for validated temperature-monitoring systems in Mumbai and Hyderabad formulation hubs. Pharmaceutical export corridors serving European and North American markets require EMA- and FDA-compliant secondary packaging. The country's national pharmaceutical regulator tightens distribution practice standards for biologics cold chain integrity.
France
Wine cooperatives and olive oil exporters in Provence-Alpes-Côte d'Azur prioritize collapsible formats for circular logistics cost reduction. Agricultural chemical distributors serving EU Green Deal procurement mandates specify bio-based PE certification under ISCC PLUS chain-of-custody standards. The Île-de-France logistics hub concentrates import-export handling infrastructure.
Cubitainer Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit legacy lines for multilayer coextrusion capability. The vendor base stratifies across integrated packaging conglomerates with captive corrugated supply, specialized flexible film converters, and regional fabricators serving niche UN-certified specifications. Three archetypes define competitive positioning: integrated outer-box producers, barrier film specialists, and fitment technology licensors. Geographic expansion into Indian pharmaceutical corridors and strategic partnerships for smart label integration represent the dominant competitive moves.
Among integrated European packaging groups, Smurfit Kappa, DS Smith, and Scholle IPN exemplify distinct strategic archetypes. Smurfit Kappa anchors supply through corrugated outer-box production paired with flexible inner bladder integration. DS Smith occupies a position emphasizing lightweight composite designs that reduce freight costs for agricultural chemical distribution. Scholle IPN sits within the fitment technology tier, leveraging bag-in-box heritage for liquid dispensing systems. These three represent the structural concentration points around which mid-scale regional fabricators and specialized converters organize their market participation.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Sealed Air Corporation |
| DS Smith |
| Liqui-Box |
| Scholle IPN |
| Zacros America |
| CDF Corporation |
| Rapak |
| Changzhou Sanjie Plastic Products Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Multilayer coextrusion technician scarcity concentrated in German and Austrian equipment specialist clusters widens labor-cost differentials between barrier-engineered pharmaceutical tiers and commodity food-grade configurations. This skills gap translates into pricing-tier spreads where EVOH-interlayer PET constructions command substantial premiums over single-layer HDPE alternatives.
Pricing Analysis
Input-cost pass-through from kraft pulp volatility and EVOH resin pricing governs contract structures across integrated and non-integrated manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates Swissmedic-validated insulated systems with phase-change integration from standard HDPE food-grade formats and collapsible returnable designs for agricultural chemicals. Pricing pressure stems from corrugated fiberboard margin compression as Scandinavian mill supply tightens. Chemical distributors in Benelux corridors exhibit highest price sensitivity due to freight-cost optimization mandates, while Basel-area pharmaceutical contract packagers prioritize barrier performance over unit economics.
Supply Chain Analysis
Reverse-logistics flows for collapsible cubitainers reduce return freight costs for French wine cooperatives and Italian olive oil exporters, creating circular economics that reshape procurement calculus. Manufacturing concentration centers on Germany, Switzerland, and the United States, with the Rhine-Ruhr corridor anchoring specialized UN-certified production. Raw material dependencies rest on kraft pulp from Scandinavian mills, EVOH barrier resins, and pharmaceutical-grade PET feedstocks. Single-source fitment vulnerability around Scholle IPN's aseptic valve patents constitutes structural supply risk. Distribution runs through integrated packaging conglomerates with captive corrugated supply serving direct relationships with Sanofi and Merck KGaA procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cubitainer market functions as a geographic-arbitrage play where EMA serialization compliance costs in Europe exceed CDSCO-aligned validation expenses in India, enabling cost-optimized supply repositioning for pharmaceutical export corridors.
For Market Incumbents: Acquire multilayer coextrusion technician training programs and Austrian equipment specialist relationships to defend barrier-film capabilities against emerging Asian converters. Consolidate backward integration into captive EVOH resin sourcing to mitigate single-supplier dependency. Invest in UN 4G certification acceleration capabilities to compress 8-14 month validation timelines threatening launch cycles.
For New Entrants and Emerging Players: Direct-to-pharmaceutical-procurement-desk digital platforms bypass traditional distribution intermediaries unbundled by consolidated buying desks at Sanofi and Merck KGaA. Target Indian pharmaceutical export corridors in Mumbai and Hyderabad where CDSCO-ICH Q1A alignment creates validation-intensive demand without entrenched incumbent relationships. Lead with NFC-enabled temperature logger and blockchain verification bundles for high-value biologics shipments.
For Investors and Strategic Acquirers: Integrated packaging conglomerates with captive corrugated supply are the most active acquirer in this space, consolidating regional fabricators to amortize EMA serialization compliance capital expenditures. Five-to-ten year viability hinges on bio-based PE certification capabilities under ISCC PLUS standards for EU Green Deal procurement mandates. Monitor CDSCO enforcement intensity for biologics cold chain integrity as inflection indicator for Indian corridor expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Enables EVOH-interlayer PET production for EMA-compliant pharmaceutical barrier specifications. |
| Backward Integration into Corrugated Supply | Secures outer-box margins against Scandinavian kraft pulp price volatility for integrated manufacturers. |
| Smart Label Technology Partnership | Combines NFC temperature loggers with blockchain verification for Basel-area biologics distributors. |
| Bio-based PE Certification Program | Opens premium positioning under ISCC PLUS chain-of-custody standards for EU Green Deal compliance. |
| Indian Pharmaceutical Corridor Validation | Aligns temperature-monitoring systems with CDSCO-ICH Q1A stability guidelines for export markets. |
Methodological Framework
Multiple input streams — primary interviews with packaging procurement managers, regulatory affairs directors at pharmaceutical distributors, and multilayer film equipment specialists; secondary validation through FDA 21 CFR filings, EMA good distribution practice guidelines, and REACH compliance databases; plus customs trade data for corrugated fiberboard and EVOH resin flows — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from German chemical logistics operators and Swiss contract packagers to anchor projections across the analysis window. Segmentation dimensions modeled include product type tier, material barrier specification, end-use regulatory stringency, and regional certification cluster. CAGRs were derived from installed capacity utilization rates and pharmaceutical serialization mandate implementation timelines. Forecast inputs incorporated UN 4G certification backlog estimates and phase-change material integration adoption curves.
The model assumes a particular technology adoption path; alternative pathways for passive cold-chain systems versus active refrigerated containers would alter the outlook. Forecasts reflect underlying assumptions about EMA serialization enforcement consistency and CDSCO alignment pace. Practitioners should monitor kraft pulp futures pricing and multilayer technician training program graduation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Old Corrugated Containers (OCC) Market
Containers
Global Flexitanks Market
Containers
Jars Market
Containers
Trays Market
Containers
Wire Containers Market
Containers
Bulk Containers Market
Containers
PVC Container Market
Containers
Soup Containers Market
Containers
Kuwait Container Glass Market
Containers
Foldable Container Market
Containers
Cups and Lids Market
Containers
Snap Secure Containers Market
Containers
PET Hinged Containers Market
Containers
Trigger Sprayer Market
Containers
Sanitary Cans Market
Containers
Stock Clamshell Packaging Market