
 Foldable Container Market | 2026-2036
Foldable Container Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Container Market Foresight
E-commerce fulfillment is realigning procurement patterns across the foldable container value chain. Schoeller Allibert dominates reusable plastic pooling systems for grocery and retail distribution networks. Shenzhen Enviropack Co. leverages cost-engineered polymer formulations to compete in Asian manufacturing export corridors. CHEP sustains its position through captive fleet scale and direct control over container circulation data.
Foldable containers are collapsible freight units engineered to reduce empty-haul cubic volume by up to 80% when collapsed, typically fabricated from high-density polyethylene, galvanized steel, or engineered plywood with hinged corner posts and interlocking base skids. Their primary purpose is to cut reverse logistics costs in closed-loop supply chains while preserving product integrity through standardized internal dimensions. Plastic foldable containers lead unit volume due to washability and FDA-compliant material grades for food contact, while metal variants anchor the premium tier in cold chain logistics where temperature cycling demands structural durability. Leasing services represent the fastest-growing distribution channel as users shift capital expenditure to operating models.
ISO standards for freight container dimensions and the EU Packaging and Packaging Waste Directive shape product certification requirements and cross-border market access for European suppliers. The US FDA maintains material compliance protocols for food-contact surfaces in reusable transport items. Stakeholders must monitor how carbon border adjustments and extended producer responsibility frameworks reshape total cost of ownership calculations against single-use alternatives.
Market Dynamics
Reverse logistics cost compression is the central structural force reshaping foldable container procurement, as empty-haul charges consume 15-30% of total supply chain spend in closed-loop distribution networks.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility frameworks penalize single-use alternatives, accelerating substitution toward returnable assets in German automotive and pharmaceutical corridors.
- Cold chain infrastructure expansion:Temperature-sensitive biologics and fresh food distribution demand collapsible insulated units that maintain thermal integrity across multi-modal handoffs.
- Polymer formulation advances:High-density polyethylene grades with enhanced UV stabilization and impact resistance extend asset lifecycles in outdoor pooling systems.
Market Restraints
- Steel price volatility:Galvanized steel variants face input cost swings that compress margins for metal-intensive premium tier products.
- Supplier concentration in East Asian molding:Tooling capacity for large-format foldable units clusters in Shenzhen and Ningbo, creating geographic supply risk.
- Dimensional standardization gaps:Absence of universal collapse ratios across pooling networks forces redundant fleet holdings.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO compliance pathways for reusable packaging create first-mover positioning in emerging cold chain lanes.
- Leasing-as-a-service models:Operating expenditure structures displace capital purchases among mid-tier 3PL operators seeking fleet flexibility.
- RFID-embedded track-and-trace convergence:Integration of IoT sensors with collapsible units enables real-time circulation analytics and loss prevention.
Industry Challenges
- ISO 3394 certification timelines:Modular dimension testing and load-bearing validation create 6-12 month product launch delays.
- Legacy WMS integration friction:Enterprise resource planning systems require custom API development to recognize collapsible container status in inventory workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Container Market |
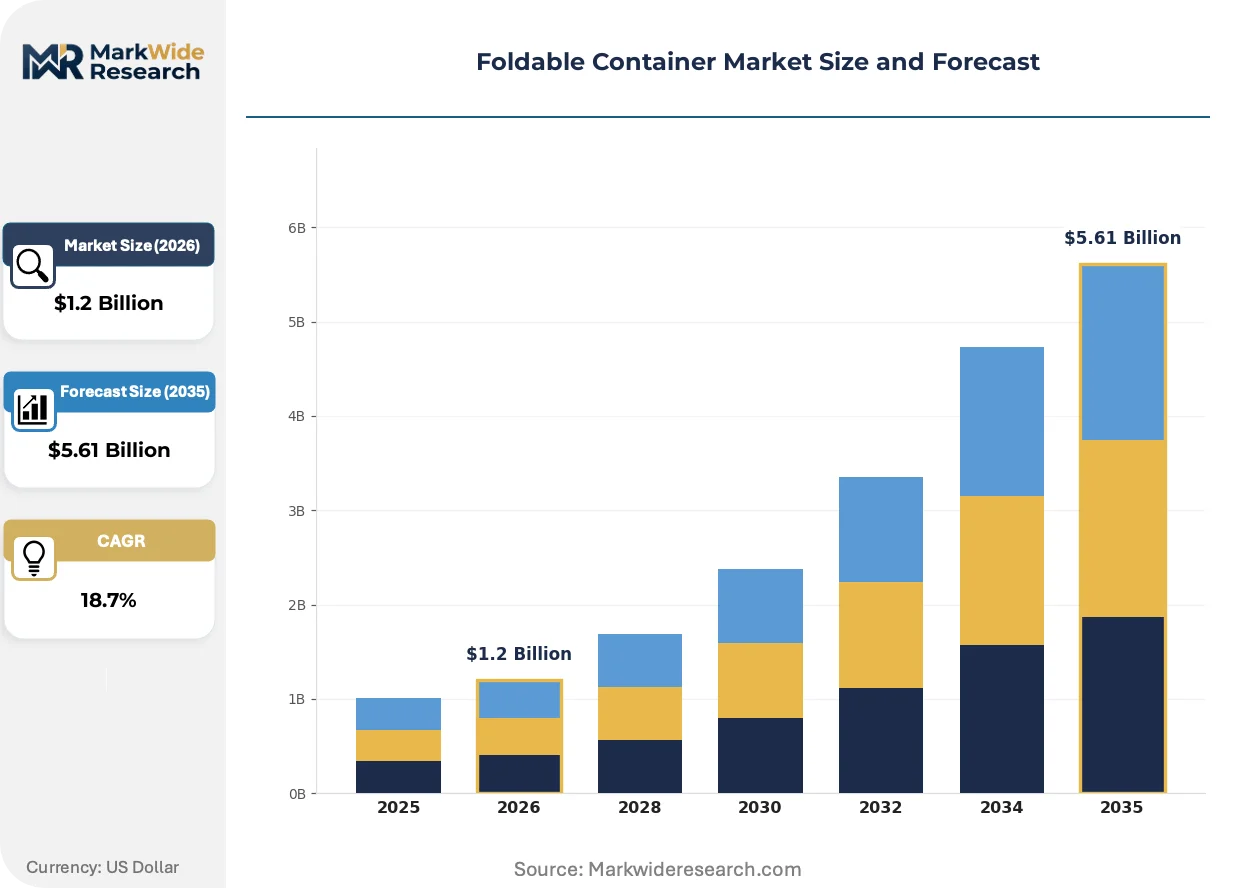
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $5.61 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Foldable Containers, Metal Foldable Containers, Wooden Foldable Containers, Fabric Foldable Containers, Composite Foldable Containers Application: Warehousing, Cold Chain Logistics, Retail Storage, E-commerce Fulfillment, Agricultural Produce Transport Industry Vertical: Consumer Goods, Food & Beverage Processing, Pharmaceutical Manufacturing, Electronics Assembly, Textile Production Distribution Channel: Direct Sales, Online Marketplaces, Industrial Distributors, Retail Chains, Leasing Services |
| Companies Covered | RPP Containers, Sonoco Products Company, Schoeller Allibert, Shenzhen Enviropack Co., Supreme Industries Ltd., WestRock Company, Smurfit Kappa Group, Pack One Srl, CHEP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Container Market Shifts & Advancements
Active materials intelligence and circular service architectures are compressing traditional asset ownership models while embedding compliance automation directly into container hardware.
Embedded RFID and NFC tracking modules is rewriting how fleet operators monitor container location, cycle count, and hygiene status. Pharmaceutical distributors and grocery retailers are deploying these units at scale. The technology is rewriting liability allocation between lessors and lessees by generating immutable usage records.
REACH substance restrictions on phthalates and heavy metal stabilizers are forcing reformulation of legacy polypropylene compounds. European converters face 18-month recertification windows for food-contact grades. Cold chain operators in Germany and the Netherlands are absorbing premium pricing for compliant engineered polymers to maintain EU market access.
Third-party pooling intermediaries are capturing share from direct manufacturer sales by offering consolidated fleet management and sanitation services. Automotive tier suppliers in Stuttgart and Wolfsburg are outsourcing container procurement entirely. This shift concentrates negotiating power among four major European pooling networks.
Foldable Container Market Segmentation
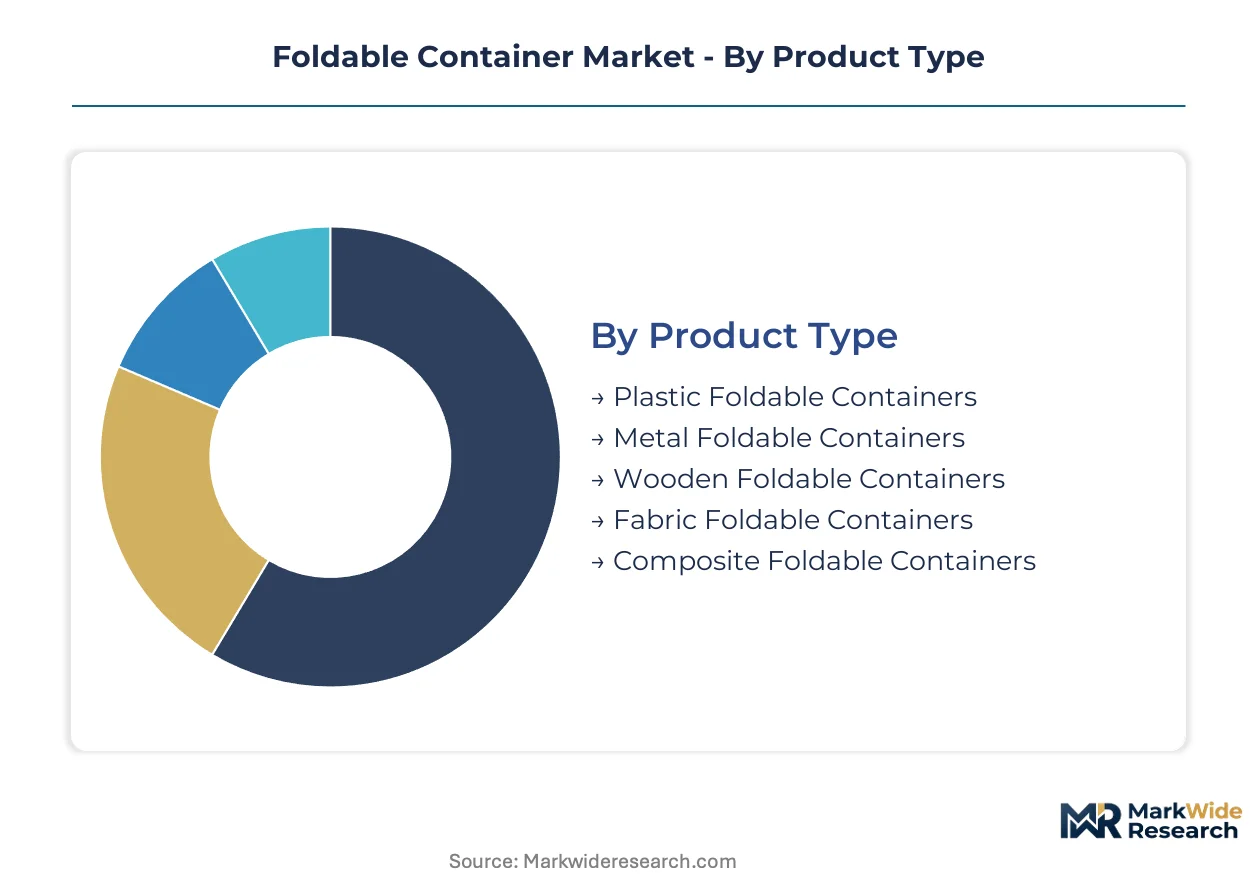
Foldable container procurement patterns diverge sharply across material grades, thermal performance requirements, and capital deployment preferences. Understanding these segment boundaries clarifies why polymer formulations dominate unit volumes while metal variants command premium positioning in regulated cold chains.
Product Type:
Material selection determines collapse ratio efficiency, washability protocols, and compliance pathways for food-contact or pharmaceutical applications.
- Plastic Foldable Containers:High-density polyethylene construction delivers 80% volume reduction when collapsed and supports FDA-compliant grades for grocery retail pooling systems. Demand concentrates in German automotive supplier networks where Schoeller Allibert operates returnable packaging pools for just-in-sequence assembly lines.
- Metal Foldable Containers:Galvanized steel frameworks withstand temperature cycling in pharmaceutical cold chains and support heavier load ratings for industrial components. Stuttgart and Wolfsburg automotive clusters specify these units for engine block transport where structural rigidity outweighs weight penalties.
- Wooden Foldable Containers:Engineered plywood with hinged corner posts serves agricultural export corridors requiring ISPM-15 heat treatment certification for cross-border phytosanitary compliance.
- Fabric Foldable Containers:Reinforced textile walls on collapsible frames reduce tare weight for air freight applications where dimensional weight pricing dominates cost calculations.
- Composite Foldable Containers:Hybrid polymer-steel constructions balance impact resistance with moderate weight for mid-tier 3PL operators seeking asset versatility across multiple customer verticals.
Plastic foldable containers lead on scale; composite variants are climbing the fastest as operators seek single-fleet flexibility.
Application:
Operational environment dictates insulation requirements, sanitation frequency, and tracking technology integration intensity.
- Cold Chain Logistics:Collapsible insulated units maintain thermal integrity across multi-modal handoffs for temperature-sensitive biologics and fresh food distribution. EU Green Deal packaging mandates accelerate substitution of single-use expanded polystyrene in Netherlands grocery distribution.
- E-commerce Fulfillment:Returnable packaging systems compress reverse logistics costs in closed-loop last-mile networks where empty-haul charges consume 15-30% of supply chain spend.
- Warehousing:Standardized base dimensions enable automated storage and retrieval system compatibility for high-velocity consumer goods distribution centers.
- Retail Storage:Nestable designs maximize backroom cube utilization for supermarket chains operating on tight real estate footprints.
- Agricultural Produce Transport:Ventilated sidewall configurations reduce respiration heat buildup in field-to-processor harvest logistics.
Cold chain logistics anchors premium pricing power; e-commerce fulfillment is gaining share fastest as procurement shifts toward operating expenditure models.
Industry Vertical:
Regulatory stringency and batch traceability requirements create divergent specification thresholds across end-use sectors.
- Pharmaceutical Manufacturing:CDSCO compliance pathways in India and EMA serialization mandates demand RFID-embedded track-and-trace capabilities for reusable packaging assets.
- Food & Beverage Processing:REACH substance restrictions on phthalates force 18-month recertification windows for European converters supplying food-contact grades.
- Consumer Goods:High-volume retail distribution networks prioritize washability and rapid cycle turnaround over structural load ratings.
- Electronics Assembly:Electrostatic discharge protection specifications govern material selection for semiconductor component transport.
- Textile Production:Lightweight fabric containers reduce shipping costs for garment export corridors from Bangladesh and Vietnam manufacturing zones.
Pharmaceutical manufacturing leads on specification intensity; food and beverage processing shows steepest expansion trajectory as EU extended producer responsibility frameworks penalize single-use alternatives.
Distribution Channel:
Capital deployment preferences and fleet management capabilities determine procurement pathway selection.
- Leasing Services:Operating expenditure structures displace capital purchases among mid-tier 3PL operators seeking flexibility without asset ownership burdens. CHEP sustains market position through captive fleet scale and circulation data control.
- Industrial Distributors:Consolidated procurement relationships serve fragmented manufacturing bases with standardized specification catalogs and regional stocking points.
- Direct Sales:Large automotive OEMs negotiate multi-year supply agreements with dedicated pooling providers for just-in-sequence assembly support.
- Online Marketplaces:Digital procurement platforms capture spot demand from small and mid-sized enterprises with irregular volume requirements.
- Retail Chains:Vertically integrated grocery operators source directly from container manufacturers for private fleet deployment.
Leasing services lead on revenue momentum; industrial distributors retain widest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and pharmaceutical clusters anchor foldable container procurement intensity across Europe, with Stuttgart and Wolfsburg assembly corridors driving just-in-sequence returnable packaging demand.
Germany
Automotive tier suppliers in Stuttgart and Wolfsburg specify galvanized steel foldable units for engine block transport where structural rigidity outweighs weight penalties. EU Green Deal extended producer responsibility frameworks penalize single-use alternatives, accelerating substitution toward returnable assets. Bavarian pharmaceutical distributors deploy RFID-embedded units to maintain EMA serialization compliance across temperature-sensitive biologics distribution.
United States
FDA material compliance protocols for food-contact surfaces shape procurement specifications in grocery retail pooling systems. Cold chain infrastructure expansion for temperature-sensitive pharmaceuticals drives collapsible insulated unit adoption. Midwest distribution corridors around Chicago consolidate demand for high-density polyethylene containers supporting automated storage and retrieval compatibility.
China
Shenzhen and Ningbo tooling capacity clusters dominate large-format foldable unit manufacturing for Asian export corridors. MIIT industrial standardization initiatives pressure domestic converters toward ISO 3394 modular dimension compliance. Yangtze River Delta pharmaceutical manufacturers source compliant engineered polymers to maintain access to EU and US export markets under tightening substance restrictions.
India
CDSCO compliance pathways for reusable packaging create first-mover positioning in emerging pharmaceutical cold chain lanes. Maharashtra and Gujarat pharmaceutical export corridors demand track-and-trace capable assets for serialization mandates. Bangalore-based 3PL operators are testing leasing-as-a-service models to displace capital purchases with operating expenditure structures.
Netherlands
EU Packaging and Packaging Waste Directive enforcement accelerates substitution of single-use expanded polystyrene in grocery distribution networks. Rotterdam port logistics operators deploy collapsible units for multi-modal handoffs between barge, rail, and road corridors. Amsterdam-area cold chain facilities specify REACH-compliant polymer grades to maintain cross-border market access under substance restriction protocols.
Foldable Container Market Competitive Landscape
Strategic partnerships dominate the current landscape as pooling intermediaries consolidate fleet management capabilities and sanitation services under unified service architectures. The vendor base distributes across three tiers: captive fleet operators with direct circulation data control, specialized pooling intermediaries offering consolidated logistics services, and regional fabricators competing on cost-engineered polymer formulations. Two strategic archetypes have emerged: scale-driven lessors leveraging asset ownership for pricing power, and technology-integrated specialists embedding RFID track-and-trace directly into container hardware. Geographic expansion and portfolio diversification represent the dominant competitive moves, with operators seeking density in high-velocity pharmaceutical and automotive corridors.
Within the captive fleet tier, CHEP exemplifies scale-driven positioning through direct control over container circulation data and consolidated pooling network density. Schoeller Allibert occupies a position representing European reusable plastic pooling specialization for grocery and retail distribution networks. Shenzhen Enviropack Co. anchors the cost-engineered fabrication archetype, competing in Asian manufacturing export corridors through polymer formulation efficiency. These three company profiles illustrate the structural divergence between asset-heavy lessors, regional pooling specialists, and manufacturing-cost optimizers reshaping procurement alternatives across the value chain.
| Leading Market Players |
|---|
| RPP Containers |
| Sonoco Products Company |
| Schoeller Allibert |
| Shenzhen Enviropack Co. |
| Supreme Industries Ltd. |
| WestRock Company |
| Smurfit Kappa Group |
| Pack One Srl |
| CHEP |
| Others |
Supply & Pricing Matrix
EU Green Deal extended producer responsibility frameworks are forcing automotive and pharmaceutical buyers toward REACH-compliant polymer grades, compelling suppliers to absorb 18-month recertification costs that stratify pricing across compliance tiers.
Pricing Analysis
High-density polyethylene resin pass-through dominates cost structures for plastic foldable containers, with galvanized steel input volatility compressing margins in premium metal variants. Three-tier pricing structure across premium, standard, and economy levels separates RFID-embedded track-and-trace units from basic pooling assets and spot-market commodity containers. Pricing pressure stems from Shenzhen and Ningbo tooling capacity competition in Asian export corridors. Mid-tier 3PL operators exhibit highest price sensitivity due to operating expenditure conversion, while pharmaceutical distributors prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse logistics flows for collapsed container returns concentrate refurbishment and sanitation cycles in Stuttgart and Wolfsburg automotive clusters, where just-in-sequence assembly demands rapid turnaround. Manufacturing capacity clusters in China, Germany, and the Netherlands feed raw material dependencies on high-density polyethylene resin, galvanized steel coil, and engineered plywood with ISPM-15 certification. Single-source vulnerability concentrates in East Asian large-format molding tooling. Distribution runs through captive fleet operators and third-party pooling intermediaries with consolidated sanitation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foldable container market represents a late-cycle quality story as pharmaceutical serialization mandates and EU substance restrictions displace commodity-grade alternatives with premium specification assets.
For Market Incumbents: To counter margin compression from Shenzhen-based cost-engineered competitors, deepen backward integration into polymer formulation capabilities and secure exclusive pooling contracts with Stuttgart automotive tier suppliers. Prioritize RFID-embedded hardware differentiation to maintain pricing power against commoditized alternatives. For New Entrants and Emerging Players: Technology-first track-and-trace convergence creates entry pathways in Indian pharmaceutical cold chain corridors where CDSCO compliance gaps persist. Target Maharashtra and Gujarat export zones with leasing-as-a-service models that displace capital purchases among Bangalore-based 3PL operators testing operating expenditure structures. For Investors and Strategic Acquirers: Asymmetric upside sits with regional pooling specialists combining captive fleet scale with embedded IoT analytics capabilities. Five-to-ten year viability favors operators consolidating sanitation and circulation management under unified service architectures. Monitor REACH substance restriction expansion timelines as inflection indicators for polymer reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | REACH-compliant grade control secures EU market access against recertification delays. |
| RFID-Embedded Hardware Deployment | Real-time circulation analytics rewrites liability allocation between lessors and lessees. |
| Leasing-as-a-Service Model Expansion | Operating expenditure conversion captures mid-tier 3PL operators seeking fleet flexibility. |
| Regional Pooling Network Consolidation | Density in Stuttgart and Wolfsburg corridors strengthens just-in-sequence assembly support. |
| CDSCO Compliance Pathway Investment | First-mover positioning in Indian pharmaceutical export corridors builds regulatory moats. |
Research Methodology
Coverage spans Germany, United States, China, India, and Netherlands, with primary inputs from each market combining interviews with logistics procurement directors, automotive tier supplier material planners, pharmaceutical distribution executives, 3PL fleet managers, and polymer conversion plant engineers. Secondary validation draws from EU Packaging and Packaging Waste Directive filings, FDA food-contact material compliance databases, MIIT industrial standardization notices, CDSCO reusable packaging guidelines, and customs trade flow records. Bottom-up unit shipment modeling triangulates against top-down value estimates across material grades and application segments.
Granularity-level modeling disaggregates volume and value projections across plastic, metal, wooden, fabric, and composite product types; cold chain, e-commerce, warehousing, retail, and agricultural applications; and leasing, distributor, direct sales, marketplace, and retail channel pathways. CAGRs derive from regression analysis of historical procurement intensity against regulatory mandate implementation timelines and polymer price elasticity coefficients. Cold chain infrastructure expansion rates and automotive just-in-sequence adoption curves serve as industry-specific forecast inputs across the projection horizon.
The model holds under stable REACH and FDA regulatory enforcement; deviation in substance restriction scope or carbon border adjustment implementation would shift total cost of ownership calculations. Practitioners should monitor EU extended producer responsibility framework expansion and MIIT ISO 3394 compliance pressure for early signals of procurement pattern disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Flexitanks Market
Containers
Thin Wall Plastic Containers Market
Containers
Compartment Take-Out Container Market
Containers
Water Resistant Packing Cubes Market
Containers
Screw Top Lids Market
Containers
PVC Container Market
Containers
Modular Container Market
Containers
Pails Market
Containers
Sample Containers Market
Containers
Single Wall Jars Market
Containers
Snap-Lock Container Market
Containers
Collapsible Sleeve Containers Market
Containers
PET Hinged Containers Market
Containers
Global Food Storage Container Market
Containers
Kuwait Container Glass Market
Containers
Cups and Lids Market