
 Plastic Ready Meal Trays Market | 2026-2036
Plastic Ready Meal Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Ready Meal Trays Market Outlook
Aftermarket recycling revenue is narrowing as European supermarkets enforce extended producer responsibility take-back schemes. Amcor plc leverages its multi-layer barrier film expertise to sustain premium positioning in modified-atmosphere ready meal applications. Faerch A/S anchors its competitive standing through closed-loop PET recycling infrastructure across Nordic retail channels. Genpak, LLC competes on thermoformed polypropylene scale, dominating quick-service restaurant tray supply in North American fast-casual chains.
Plastic ready meal trays are thermoformed or injection-molded food-contact containers, typically manufactured from polypropylene, PET, or crystallized polystyrene with wall thicknesses of 0.3 to 1.2 millimeters, engineered to withstand temperatures from freezer storage through microwave reheating cycles. Polypropylene formulations lead material type volumes due to cost-efficient thermoforming and broad microwave compatibility, while PLA biopolymer grades represent the fastest-expanding segment as retail buyers impose renewable content thresholds. Multi-compartment product forms command margin premiums by enabling protein-starch-vegetable separation that reduces sauce migration and extends chilled shelf life.
The EU's Packaging and Packaging Waste Regulation, the US FDA's food contact substance notification requirements, and Germany's national LUCID packaging registry collectively reshape material selection and recyclability verification obligations across export markets. Compliance documentation burdens favor suppliers with pre-certified polymer streams and established recycling partnerships. Stakeholders must monitor evolving extended producer responsibility fee structures and single-use plastic restriction scopes to anticipate tray format obsolescence risks.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is forcing material substitution across ready meal tray supply chains, compressing timelines for recyclability verification while supermarkets demand extended producer responsibility compliance documentation from all suppliers.
Growth Catalysts
- Chilled ready-meal shelf expansion:Retail chains in Germany, the United Kingdom, and France are dedicating additional cold-chain infrastructure to prepared food sections, driving tray procurement volumes through centralized distribution networks.
- REACH-compliant polymer streams:Pre-certified material pathways through Nordic closed-loop recycling infrastructure reduce compliance documentation burdens for exporters serving EU member states.
- Microwave-compatible polypropylene formulations:Thermoformed PP grades withstand freezer-to-reheat temperature cycles, maintaining structural integrity across the full prepared meal consumption journey.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin prices fluctuate with crude oil derivatives, squeezing thermoformer margins on fixed-price annual contracts with retail buyers.
- Single-layer technical ceiling:Standard PET and CP trays lack oxygen barrier properties for extended chilled shelf life, limiting penetration into premium modified-atmosphere applications without multi-layer coextrusion.
- Germany's LUCID packaging registry:Registration and fee obligations for non-domestic suppliers create administrative friction for exporters lacking established EU legal entities.
Strategic Opportunities
- PLA biopolymer grade adoption:Renewable content thresholds imposed by retail sustainability procurement teams open substitution pathways for compostable tray formulations in quick-service restaurant channels.
- Multi-compartment product forms:Protein-starch-vegetable separation designs command margin premiums by reducing sauce migration and extending chilled shelf life in premium ready meal segments.
- Extended producer responsibility tailwinds:EU Green Deal implementation timelines accelerate closed-loop infrastructure investment, rewarding suppliers with pre-established recycling partnerships.
Industry Challenges
- Recyclability certification timelines:Third-party verification of food-contact material streams for EFSA compliance creates 12-18 month product development cycles, delaying new tray launches.
- Legacy thermoforming equipment retrofit costs:Transitioning production lines from crystallized polystyrene to PET or PP formats demands capital expenditure for mold redesign and heating system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Ready Meal Trays Market |
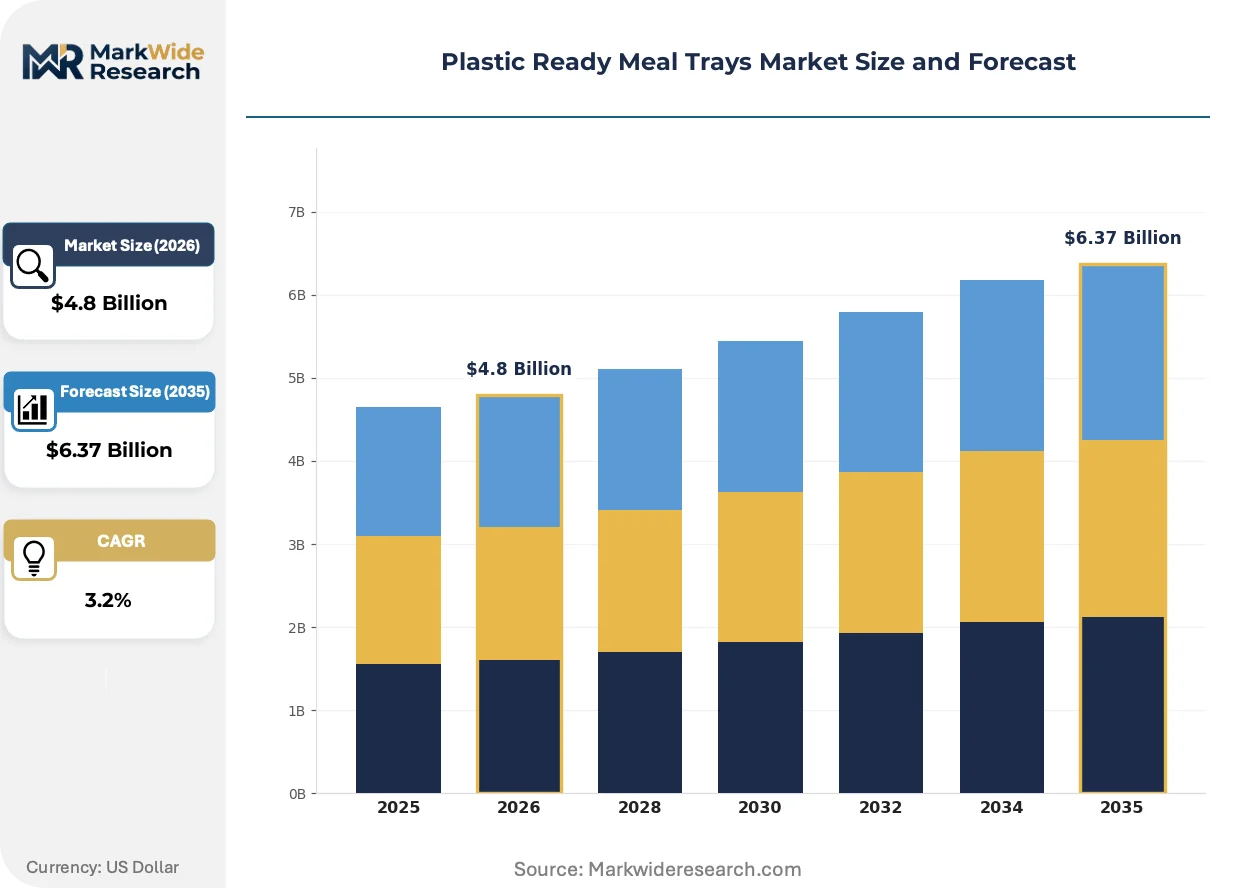
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, PET, PVC, PLA Product Form: Single Compartment, Multi-Compartment, Leak-Resistant, Reusable End User: Food Service, Retail, Catering, Fast Food Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Amcor plc, DS Smith, Huhtamäki Oyj, Sonoco Products Company, Faerch A/S, Sealed Air, Genpak, LLC, Sunmarks, LLC, Sabert Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Ready Meal Trays Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape competitive positioning in food-contact packaging, with sustainability verification becoming as critical as functional performance in buyer selection criteria.
Barrier film technology is hybridizing oxygen-scavenging layers with conventional PET substrates to extend chilled ready meal shelf life without aluminum lamination. Premium retail private labels in France and the United Kingdom are specifying these structures for high-margin ethnic cuisine lines. The hybridizing approach enables mono-material classification under EU recyclability protocols while maintaining the gas barrier performance previously requiring multi-material constructions.
The EU's Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds and standardized recyclability labeling across all single-use food contact materials sold in member states. Thermoformers serving export markets must revalidate polymer streams and redesign tray geometries to meet these specifications. Nordic retail channels are responding fastest, with closed-loop PET collection infrastructure already operational across Denmark, Sweden, and Norway.
Retail buyer consolidation is compressing supplier negotiation cycles and unbundling tray procurement from full packaging system contracts. Category managers at major German and British supermarket chains are demanding direct material traceability documentation and separate pricing for tray, lidding film, and label components. This disintermediation is most visible in the United Kingdom, where four retailers control over seventy percent of chilled ready meal volumes and have established dedicated sustainable packaging procurement teams.
Plastic Ready Meal Trays Market Segmentation
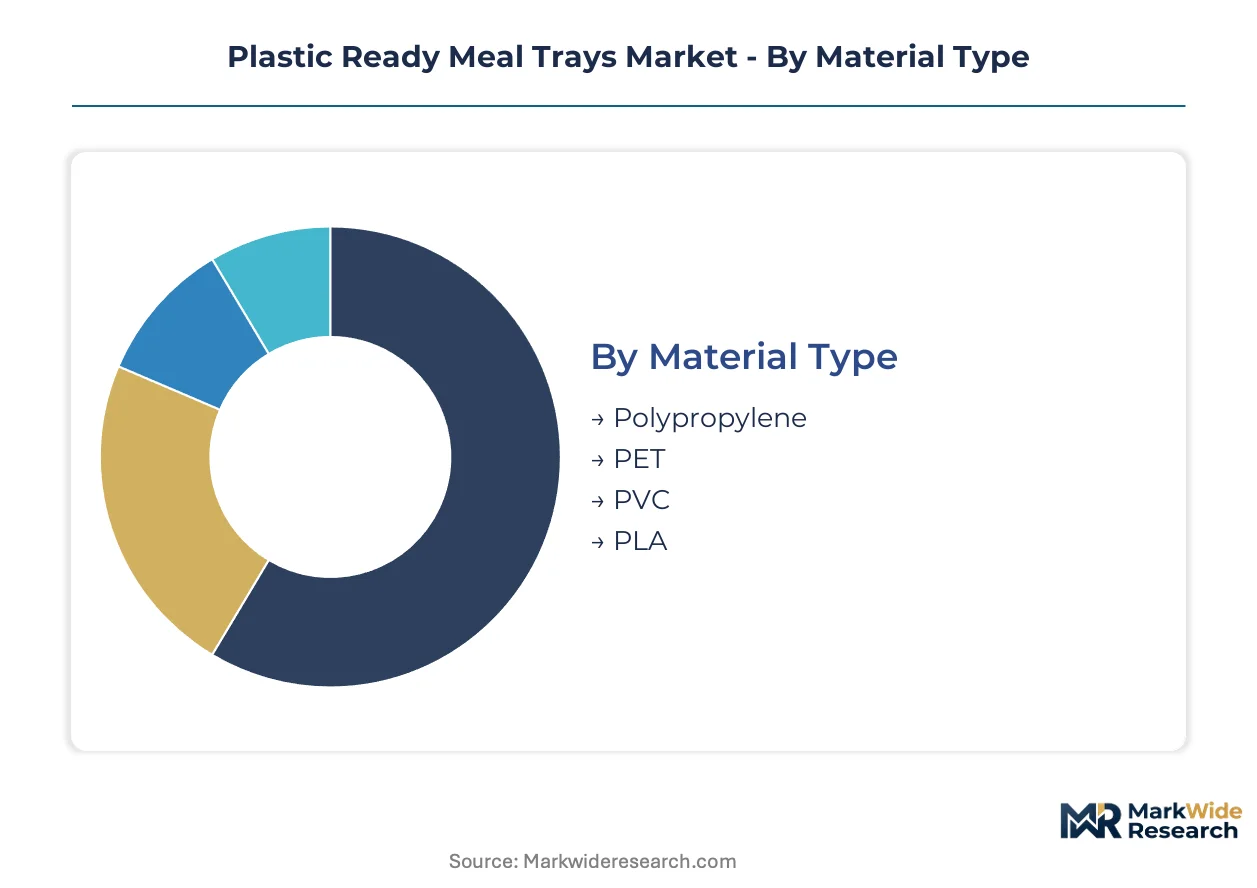
Segmentation in plastic ready meal trays reveals how material specifications, functional designs, and channel configurations align with distinct buyer requirements across food service and retail procurement. Understanding these divisions exposes margin concentration points and technology substitution risks.
Material Type:
Use-case spectrum spans freezer-stable commodity grades through compostable biopolymers serving sustainability-mandated contracts.
- Polypropylene:Thermoformed homopolymer and random copolymer grades dominate microwave-reheat applications due to thermal stability across -20°C to 120°C cycles. German and British retail chains specify PP for high-volume chilled ready meal lines where cost efficiency outweighs barrier performance requirements.
- PET:Amorphous and crystallized grades offer clarity and oxygen barrier properties for modified-atmosphere packaging. French premium private labels favor PET for ethnic cuisine segments where visual presentation drives shelf appeal.
- PVC:Rigid formulations persist in specific quick-service restaurant applications requiring high-frequency sealing compatibility.
- PLA:Polylactic acid biopolymer grades serve Nordic retail channels with established industrial composting infrastructure and mandated renewable content thresholds.
Established volume favors polypropylene; emerging adoption favors PLA.
Product Form:
Functional differentiation separates commodity single-use containers from engineered multi-chamber designs commanding procurement premiums.
- Multi-Compartment:Thermoformed partitions enable protein-starch-vegetable separation that reduces sauce migration and extends chilled shelf life. United Kingdom retailers specify these structures for premium ready meal tiers where presentation quality justifies higher unit pricing.
- Single Compartment:Standard one-chamber designs serve cost-sensitive prepared food segments across fast-casual restaurant chains and institutional catering.
- Leak-Resistant:Engineered seal geometries and ribbed perimeters contain liquid contents through distribution vibration and temperature fluctuation.
- Reusable:Durable PP formulations withstand industrial washing cycles for closed-loop food service systems in corporate catering and airline meal operations.
Margin capture concentrates in multi-compartment engineering; standardization pressure weighs on single-compartment procurement.
End User:
Buyer type determines volume scale, specification stringency, and sustainability documentation requirements.
- Retail:Supermarket chains and chilled ready meal specialists drive tray specification through centralized procurement teams with dedicated sustainable packaging mandates.
- Food Service:Contract caterers and institutional meal providers prioritize stackability, nesting efficiency, and logistics optimization over material premiumization.
- Catering:Event and hospitality segments demand presentation-grade clarity and custom branding compatibility for premium buffet and plated service applications.
- Fast Food:Quick-service restaurant chains specify standardized formats for operational consistency across franchise networks with high-frequency inventory turns.
Specification authority sits with retail buyers; volume scale concentrates in food service procurement.
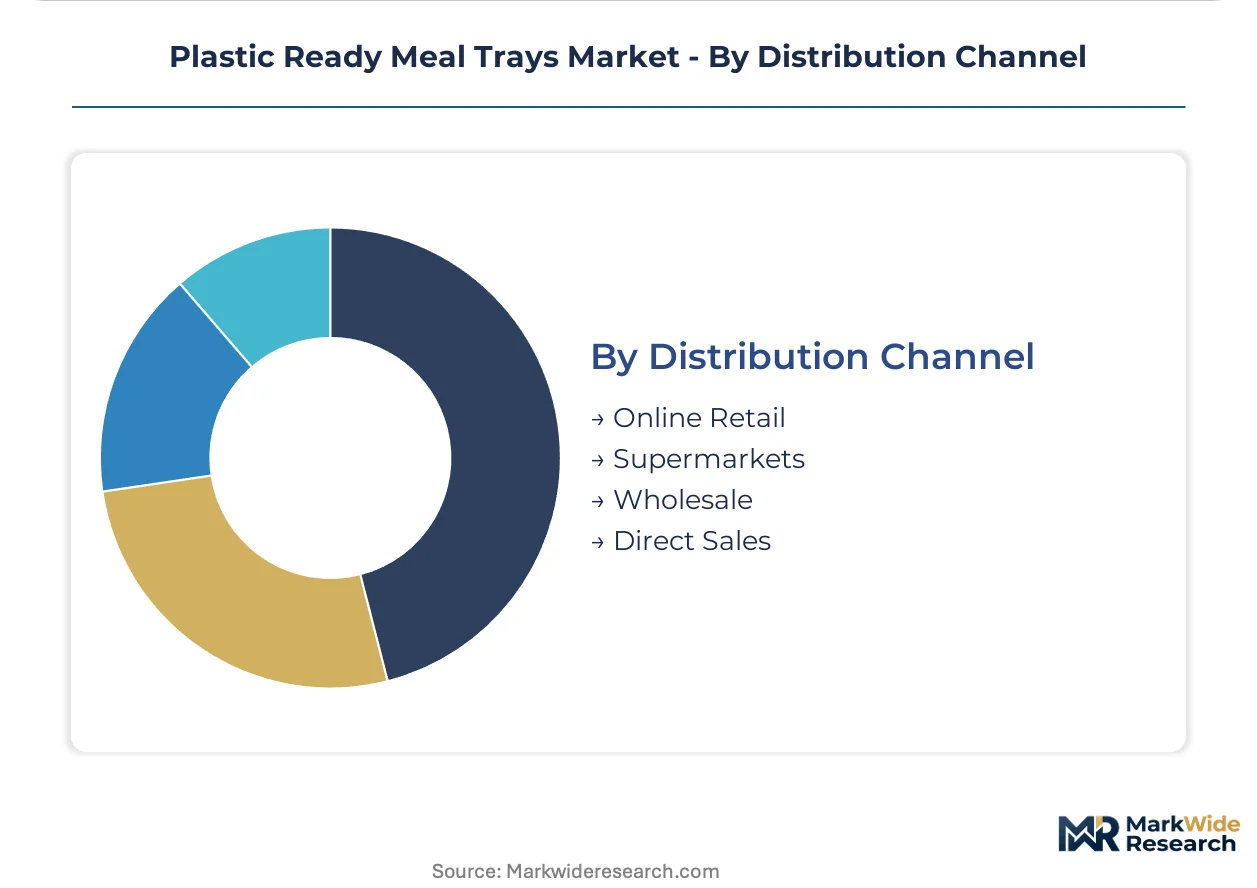
Distribution Channel:
Channel structure shapes order fragmentation, lead time compression, and direct supplier relationships versus intermediary dependence.
- Supermarkets:Centralized category management at major German and British chains consolidates tray procurement with direct manufacturer negotiations and EPR compliance documentation requirements.
- Online Retail:E-commerce grocery platforms introduce smaller order quantities and mixed-SKU fulfillment complexity that challenges thermoformer production scheduling.
- Wholesale:Foodservice distributors aggregate fragmented restaurant and catering demand through inventory-holding intermediaries with private-label tray programs.
- Direct Sales:Large-format food manufacturers and quick-service chains bypass distribution intermediaries for contract-negotiated volume commitments and custom mold development.
Channel consolidation favors supermarket direct procurement; fragmentation persists through wholesale intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United Kingdom show the highest price elasticity for standard single-compartment trays, while French premium private labels absorb material premiums for modified-atmosphere barrier designs. Nordic retail channels demonstrate intermediate elasticity, trading cost for verified circularity credentials.
Germany
Centralized retail distribution through Aldi, Lidl, and REWE drives high-volume PP tray procurement with stringent microwave compatibility specifications. The LUCID packaging registry mandates registration and fee obligations for all suppliers, creating administrative friction for exporters lacking established EU legal entities. The Rhine-Ruhr industrial corridor hosts thermoforming clusters serving chilled ready meal manufacturers with just-in-time delivery contracts.
United Kingdom
Four retailers control over seventy percent of chilled ready meal volumes, consolidating procurement through dedicated sustainable packaging teams with direct manufacturer negotiations. The UK Environment Agency enforces extended producer responsibility compliance documentation for all single-use food contact materials. Greater Manchester and West Midlands thermoforming facilities supply quick-service restaurant chains with standardized formats for franchise network consistency.
France
Premium private labels in ethnic cuisine segments specify PET clarity and oxygen barrier properties where visual presentation drives shelf appeal. ANSM enforces food contact substance notification requirements parallel to EU EFSA standards. The Île-de-France region concentrates modified-atmosphere packaging innovation, with barrier film hybridization advancing in Saint-Quentin-en-Yvelines research clusters.
United States
Fast-casual restaurant chains dominate thermoformed polypropylene consumption, prioritizing operational consistency across high-frequency inventory turns. The FDA's food contact substance notification requirements govern material selection for interstate commerce. Ohio and Indiana thermoforming corridors supply Genpak-scale production for quick-service tray programs with annual contract pricing.
Denmark
Nordic retail channels mandate renewable content thresholds, accelerating PLA biopolymer adoption through established industrial composting infrastructure. The Danish EPA implements EU Packaging and Packaging Waste Regulation timelines with closed-loop PET collection operational across Copenhagen retail networks. Faerch A/S anchors closed-loop recycling infrastructure, validating polymer streams for EFSA compliance in Aarhus manufacturing facilities.
Plastic Ready Meal Trays Market Competitive Environment
Capability concentration sits with multi-layer barrier film specialists; scale advantage sits with high-volume thermoforming operators serving quick-service restaurant networks. The market structures around three tiers: integrated packaging conglomerates with film-to-tray systems, regional thermoformers with retail channel specialization, and biopolymer pioneers with compostable certification. Consolidation pressure intensifies as retail buyer consolidation compresses supplier negotiation cycles. Dominant competitive moves include strategic partnerships for closed-loop recycling infrastructure and portfolio diversification into mono-material barrier designs.
Within the integrated packaging tier, Amcor plc represents multi-layer barrier expertise sustaining premium positioning, while DS Smith exemplifies fiber-based diversification pressures on plastic incumbents. Among specialized thermoformers, Faerch A/S occupies a position anchoring Nordic circular infrastructure, and Genpak, LLC sits within the scale-driven North American quick-service segment. These three names illustrate the capability-scale tension reshaping procurement relationships.
| Leading Market Players |
|---|
| Amcor plc |
| DS Smith |
| Huhtamäki Oyj |
| Sonoco Products Company |
| Faerch A/S |
| Sealed Air |
| Genpak, LLC |
| Sunmarks, LLC |
| Sabert Corporation |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Ruhr industrial corridor anchors European thermoforming capacity, with clustered production facilities enabling just-in-time delivery contracts that compress lead times and sustain margin premiums for compliant suppliers serving Aldi, Lidl, and REWE procurement teams.
Pricing Analysis
Aftermarket recycling revenue streams are narrowing as extended producer responsibility take-back schemes consolidate financial obligations upstream. Three-tier pricing structure across premium barrier-grade, standard microwave-compatible, and economy single-layer tiers separates multi-compartment engineered designs from commodity single-chamber formats. Pricing pressure stems from petrochemical feedstock volatility squeezing thermoformer margins on fixed-price annual contracts. Retail chains in Germany and the United Kingdom exhibit highest price elasticity for standard trays, while French premium private labels absorb material premiums for modified-atmosphere barrier specifications.
Supply Chain Analysis
Polypropylene resin feedstock draws from petrochemical complexes in Germany, Belgium, and the Netherlands, with crystallized polystyrene and PET granules sourcing from integrated polymer producers. Raw material dependencies center on crude oil derivatives, calcium carbonate fillers, and oxygen-scavenging additive packages. Single-source vulnerability concentrates in specialty barrier film coextrusion equipment. Distribution runs through centralized retail procurement at major German and British supermarket chains, with direct manufacturer negotiations displacing wholesale intermediation in high-volume chilled ready meal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
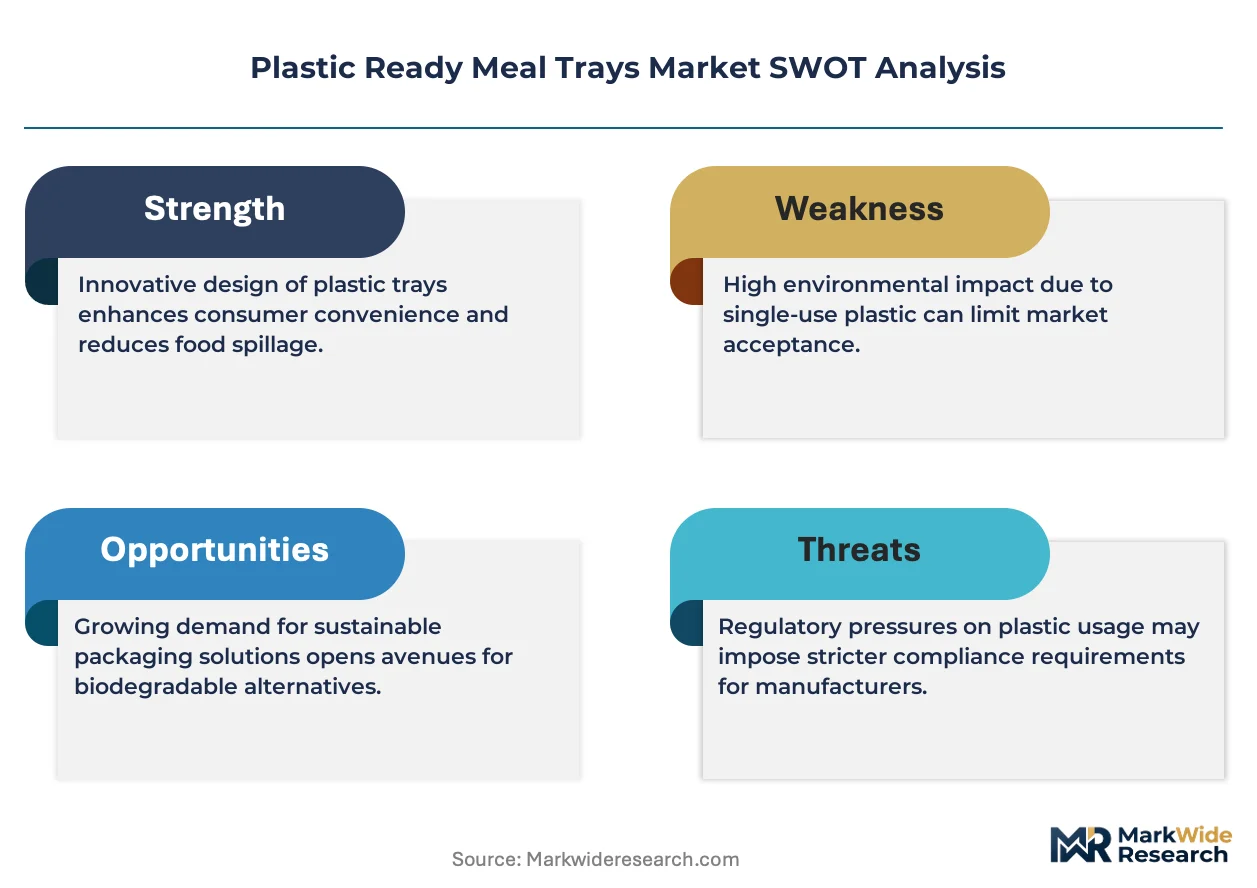
This market structures as a regulatory entrenchment moat, where EFSA compliance documentation and LUCID registry obligations create switching costs that cement incumbent relationships with centralized retail buyers.
For Market Incumbents: Build certification moats through pre-validated polymer streams and closed-loop recycling partnerships that compress new entrant product development timelines. Invest in mono-material barrier R&D to sustain premium positioning as EU recyclability mandates tighten. Threat of PLA biopolymer substitution from compostable specialists demands backward integration into Nordic circular infrastructure. Leverage existing EPR compliance documentation to defend shelf space at consolidated retail buyers. For New Entrants and Emerging Players: Nordic retail channels with mandated renewable content thresholds represent the most penetrable entry point for PLA biopolymer tray specialists lacking legacy thermoforming scale. Quick-service restaurant chains in North America seeking sustainability credentials without modified-atmosphere requirements offer secondary white-space. Go-to-market through industrial composting infrastructure partnerships that validate end-of-life claims for procurement teams. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mono-material barrier specialists over multi-layer incumbents facing redesign cycles. Long-term viability hinges on recyclability certification capabilities rather than raw scale. Acquisition targets should demonstrate established EFSA compliance pathways and closed-loop collection partnerships. Signal to watch is acceleration of EU Green Deal implementation timelines for recycled content thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Development | Enables EU recyclability compliance while maintaining oxygen barrier performance for premium chilled ready meals. |
| Closed-Loop Recycling Infrastructure | Faerch A/S validates polymer streams for EFSA compliance through Nordic retail channel partnerships. |
| PLA Biopolymer Grade Scale-Up | Industrial composting certification opens quick-service restaurant procurement with renewable content mandates. |
| Multi-Compartment Mold Engineering | Protein-starch-vegetable separation designs command margin premiums at British premium ready meal retailers. |
| EPR Compliance Documentation Systems | LUCID registry and extended producer responsibility fee structures favor suppliers with pre-certified pathways. |
Study Parameters
Initial hypotheses were tested against primary input from thermoforming plant managers, retail category buyers at German and British supermarket chains, sustainability procurement leads, and quick-service restaurant supply chain directors, and refined through secondary validation across customs trade data, SEC filings of listed packaging conglomerates, EU EFSA food contact substance notifications, and national packaging registry records. Bottom-up volume estimates from production facility capacities were triangulated against top-down demand calculations from chilled ready meal retail scan data.
Demand-supply balance dynamics across material grade segments, product form configurations, and end-user procurement channels anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include material type, compartment architecture, distribution channel structure, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends. Industry-specific inputs incorporated EU Packaging and Packaging Waste Regulation implementation timelines and petrochemical feedstock price correlation coefficients.
Macroeconomic conditions sit as an overlay; deviation in crude oil derivatives pricing, EU EPR fee structures, or single-use plastic restriction scopes would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation pacing and retail buyer consolidation trends. Quarterly review of EFSA compliance certification timelines and closed-loop infrastructure investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
Plastic Tubes Market