
 Trays Market | 2026-2036
Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Trays Market Outlook
China is fragmenting tray production capacity as domestic converters add thermoforming and molded fiber lines to serve Asia-Pacific food retail expansion. Huhtamaki Oyj leverages its global fiber and molded pulp technology base to capture premium quick-service accounts. Pactiv Evergreen Inc. anchors North American foodservice supply through integrated resin-to-tray manufacturing and direct distribution. Sonoco Products Company differentiates via engineered paperboard and recycled-content structures for temperature-sensitive applications.
Trays are rigid, flat-bottomed containers engineered with raised edges or lips to secure contents during handling, transport, or presentation, typically manufactured through thermoforming, injection molding, die-cutting, or press-molding processes depending on material and duty requirements. Their primary commercial purpose spans food containment, retail merchandise display, industrial component organization, and hospitality service logistics. Plastic trays retain volume leadership across food service and industrial applications due to cost efficiency and design flexibility, though fiber and molded pulp alternatives are gaining structural share as operators face single-use plastic restrictions. Food trays command the deepest margin pools in quick-service and delivery channels where grease resistance, stackability, and brand-printing capabilities determine supplier selection.
The FDA governs food-contact tray materials in the United States through 21 CFR standards that specify allowable substances and migration limits, while the EU's Single-Use Plastics Directive and REACH framework constrain polymer choices and mandate extended producer responsibility schemes across European markets. China's SAMR enforces GB standards for food packaging safety that shape both domestic production and export qualification requirements. Stakeholders must monitor evolving extended producer responsibility obligations and substrate certification timelines as regulatory divergence between jurisdictions complicates material platform standardization and cross-border product qualification.
Market Dynamics
Single-use plastic bans across European Union member states and China's dual carbon goals are forcing material transitions in tray manufacturing, redirecting capital from polypropylene thermoforming lines toward molded pulp and fiber-based alternatives.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive mandates phase-outs of expanded polystyrene food containers, creating immediate substitution demand for fiber-based trays in quick-service restaurant channels.
- Quick-service restaurant delivery expansion:Food service operators are scaling tray procurement for takeout formats as third-party delivery platforms penetrate suburban and tertiary city markets.
- Molded pulp thermoforming:Advances in precision molding technology enable grease-resistant fiber trays to match plastic performance at commercial scale.
Market Restraints
- Recycled pulp fiber cost volatility:Input prices for OCC (old corrugated containers) fluctuate with Chinese import restrictions on waste paper, compressing converter margins.
- Supply concentration in petroleum-based resins:Polypropylene and polystyrene production clusters along the US Gulf Coast and Middle Eastern petrochemical corridors create geographic vulnerability.
- Barrier coating limitations:Current PLA and bio-PBS coatings lack the heat tolerance and grease resistance of conventional polyethylene linings for hot-food applications.
Strategic Opportunities
- India's organized food retail expansion:Modern trade and food court infrastructure in tier-2 cities remains underpenetrated for branded tray supply.
- Reusable container-as-a-service models:Logistics platforms are piloting return-loop systems for durable polypropylene trays in corporate catering and university food service.
- China's GB standards alignment:Export-oriented converters can capture dual domestic-international qualification by certifying to SAMR food-contact safety requirements.
Industry Challenges
- Molded fiber tooling lead times:Custom thermoformed die production for proprietary tray geometries requires 16-24 week procurement cycles that delay customer onboarding.
- Extended producer responsibility compliance:Operators must track packaging waste fees across divergent national schemes in Germany, France, and Italy without unified reporting standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trays Market |
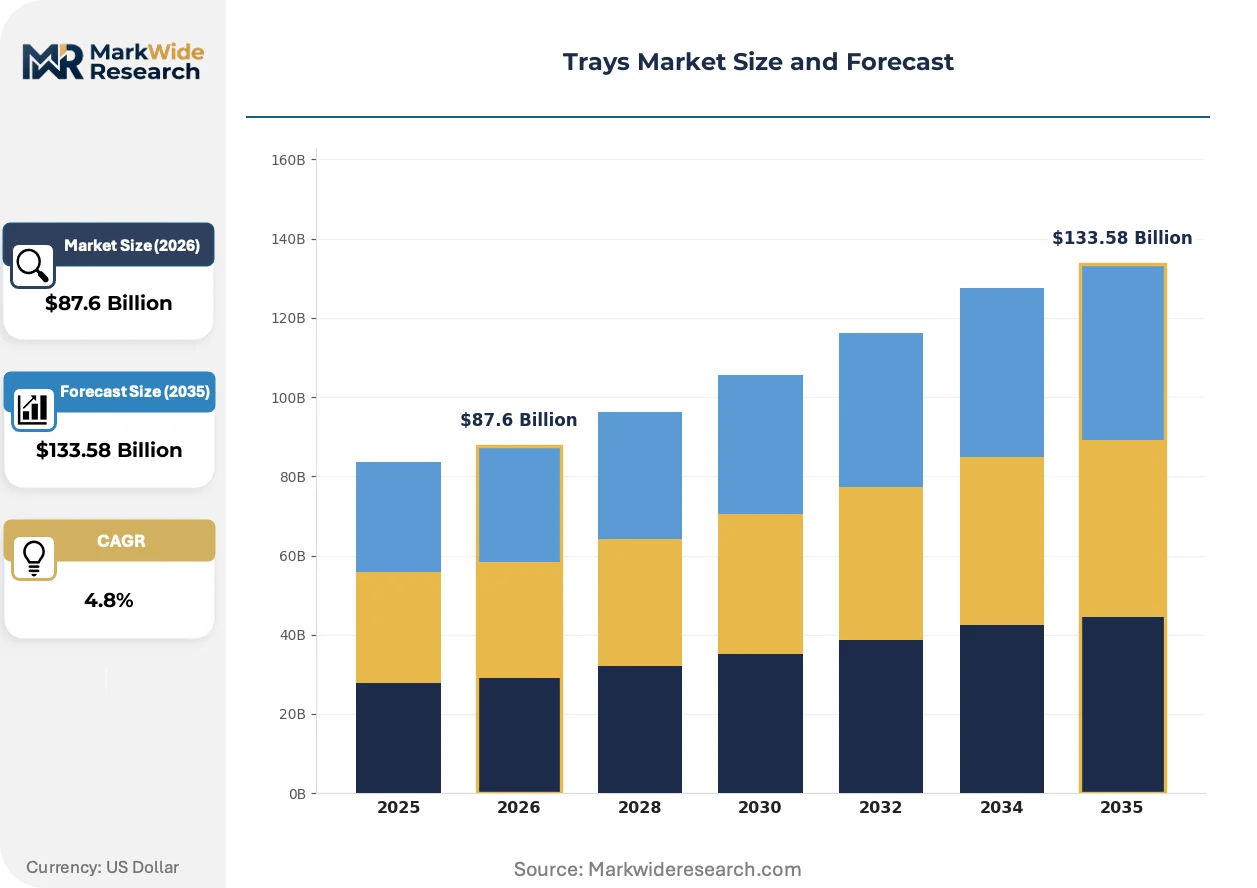
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $133.58 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serving Trays, Storage Trays, Display Trays, Food Trays Material: Plastic, Wood, Metal, Glass Application: Food Service, Household, Industrial, Hospitality Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Huhtamaki Oyj, Pactiv Evergreen Inc., Genpak LLC, Sonoco Products Company, Winpak Ltd., Amcor, Berry Global Inc., Sealed Air Corporation, Mondi Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trays Market Strategic Shifts
Material science breakthroughs in barrier coatings and forming technologies are collapsing the performance gap between fiber-based and plastic trays, while regulatory pressure accelerates commercial adoption timelines.
Advanced aqueous barrier coatings incorporating bio-based polymers are rendering obsolete conventional polyethylene-lined paperboard trays in temperature-sensitive food service applications. Quick-service chains in Nordic markets are piloting these structures for hot-protein containment. The technology is rendering obsolete legacy polyethylene extrusion equipment at mid-scale converters who cannot justify dual coating line investments.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are eliminating oil-and-grease-resistant fluorinated chemistries from food-contact paper and board across EU markets. Manufacturers are reformulating with silicone-based and clay-filled alternatives that meet migration limits. Ready-meal and airline catering segments face the steepest compliance deadlines and are consolidating supplier relationships with early-certifying mills.
Direct procurement relationships between food service operators and tray converters are displacing traditional distribution intermediaries in North American quick-service channels. Large chains are negotiating specification control and volume commitments in exchange for price transparency. This pattern is most visible in the US Southwest and Southeast where regional distribution cooperatives are losing share to captive supply arrangements with molded pulp specialists.
Trays Market Segmentation
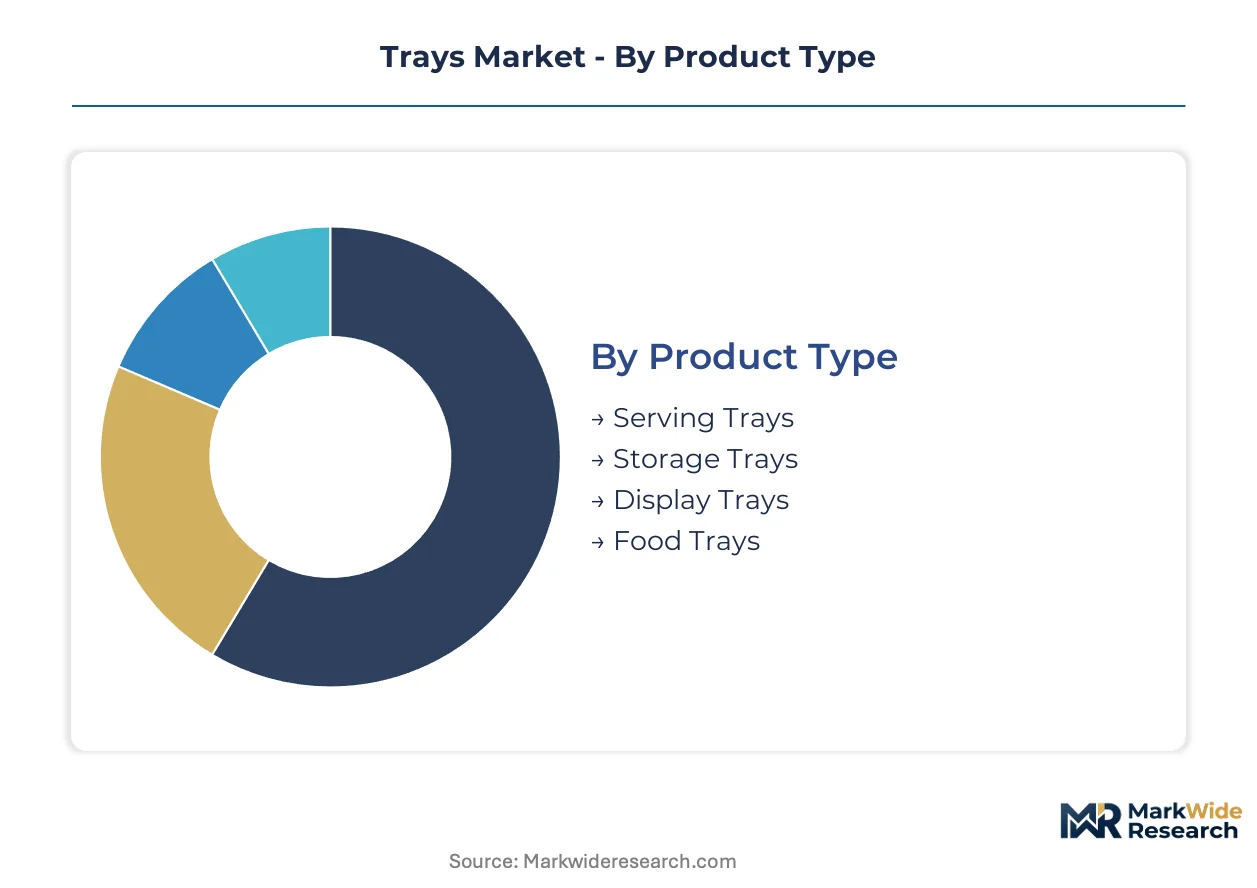
Tray specifications diverge sharply across end-use contexts, with food service operators demanding grease resistance and stackability while industrial buyers prioritize load-bearing capacity and chemical compatibility. Material selection now carries regulatory weight as single-use plastic constraints reshape procurement criteria across jurisdictions.
Product Type:
Mature formats dominate volume, though emerging geometries are capturing premium positioning in quick-service delivery channels.
- Food Trays:Engineered with raised lips and compartmentalized sections for hot-protein containment, these structures incorporate aqueous barrier coatings to meet EU fluorinated chemistry restrictions. Quick-service chains in Germany and France are consolidating supplier relationships around certified fiber-based alternatives as ECHA REACH deadlines approach.
- Display Trays:Flat-bottomed presentation structures with minimal sidewalls, optimized for retail merchandise visibility and brand printing. Demand concentrates in US big-box retail fixtures where specification control and direct converter relationships are displacing traditional distribution intermediaries.
- Serving Trays:Hospitality-grade structures with reinforced handles and non-slip surfaces for front-of-house service logistics.
- Storage Trays:Industrial-duty containers with nested or stackable geometries for component organization and warehouse density optimization.
Food Trays handles the majority of throughput; Display Trays is the fastest mover on share.
Material:
Cost tiers stratify sharply between commodity petroleum-based resins and certified fiber alternatives facing volatile OCC input markets.
- Plastic:Thermoformed polypropylene and polystyrene structures retain design flexibility and unit cost advantages across food service and industrial applications. Gulf Coast resin production clusters create geographic vulnerability for North American converters, while Middle Eastern petrochemical corridors supply Asian molding operations.
- Wood:Engineered plywood and solid timber trays serve premium hospitality presentation and temperature-sensitive catering applications. Nordic markets are piloting these structures for hot-protein containment as aqueous coating technology advances.
- Metal:Stainless steel and aluminum formats for industrial component handling and reusable food service logistics in corporate catering.
- Glass:Tempered and borosilicate structures for laboratory and high-visibility retail display contexts requiring chemical inertness.
Plastic commands the deepest volume base; fiber-based alternatives are climbing the fastest as regulatory pressure accelerates commercial adoption timelines.
Application:
Customer type determines specification rigor, with institutional buyers enforcing migration limits and temperature tolerances that exceed household requirements.
- Food Service:Quick-service restaurants, institutional catering, and airline meal operations demand grease resistance, stackability, and brand-printing capabilities. FDA 21 CFR standards govern US food-contact qualification while SAMR GB standards shape Chinese domestic and export production.
- Industrial:Manufacturing and logistics operations require load-rated structures for component organization, ESD protection, and automated handling system compatibility. Automotive and electronics assembly lines in Japan and South Korea specify JIS-standard dimensional tolerances.
- Household:Consumer-grade serving and organization products distributed through retail and online channels.
- Hospitality:Front-of-house presentation and back-of-house service logistics for hotels and event venues.
Food Service generates the steepest margin pools; Industrial applications are expanding most quickly on automation-driven specification upgrades.
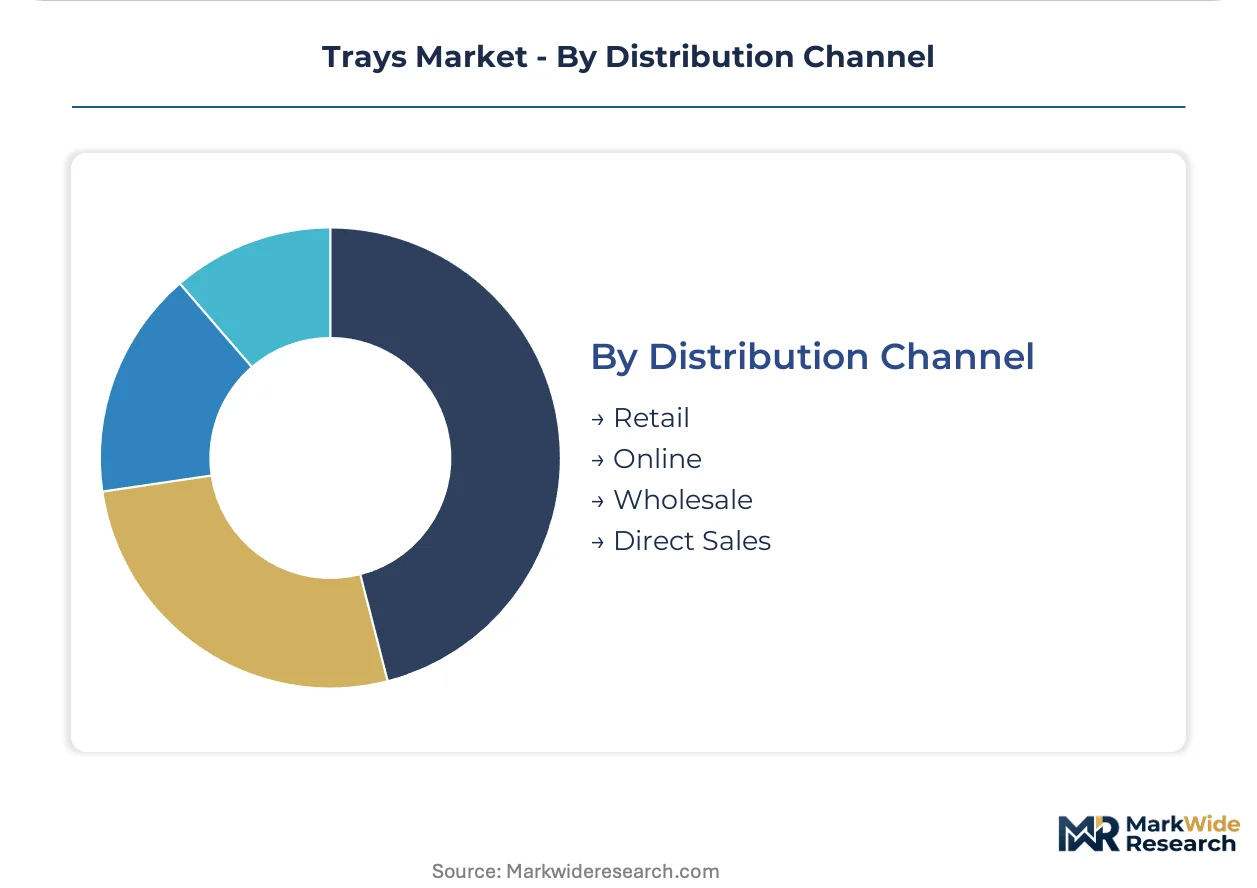
Distribution Channel:
Supply concentration varies by channel, with direct relationships capturing specification control while wholesale intermediaries retain fragmented regional coverage.
- Direct Sales:Large food service operators negotiate captive supply arrangements with molded pulp and thermoforming specialists, trading volume commitments for price transparency. This pattern is most visible in the US Southwest and Southeast where regional distribution cooperatives are losing share.
- Wholesale:Industrial distributors and foodservice broadliners aggregate fragmented demand from mid-scale operators and institutional buyers.
- Retail:Big-box and specialty store fixtures for household and hospitality-grade tray procurement.
- Online:E-commerce platforms serving fragmented household demand and small commercial accounts without direct converter relationships.
Direct Sales captures the majority of quick-service volume; Online channels are gaining share fastest among underpenetrated tier-2 city markets in India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European tray import logistics, while China's Ningbo-Zhoushan port complex anchors Asia-Pacific molded fiber export capacity. Gulf Coast petrochemical corridors supply resin feedstock for North American thermoforming operations.
United States
Quick-service restaurant chains in Texas and California are consolidating direct procurement relationships with molded pulp specialists. FDA 21 CFR standards govern food-contact material migration limits for tray structures. Houston-Galveston petrochemical clusters supply polypropylene resin to regional thermoforming converters serving Southwest distribution cooperatives.
Germany
Quick-service operators in Bavaria and North Rhine-Westphalia are certifying fiber-based tray alternatives ahead of ECHA REACH PFAS deadlines. The EU Single-Use Plastics Directive mandates expanded polystyrene phase-outs by member state timetables. Hamburg's port infrastructure handles Nordic molded pulp imports for German foodservice distribution networks.
China
Domestic food retail infrastructure expansion in tier-2 cities is scaling thermoformed plastic and molded pulp tray demand. SAMR GB standards enforce food-contact safety requirements that shape both domestic production and export qualification. Yangtze River Delta converters are adding precision molding capacity to serve quick-service delivery platform growth.
India
Organized food retail and food court infrastructure in Maharashtra and Karnataka remains underpenetrated for branded tray supply. FSSAI packaging regulations govern food-contact material safety for domestic and export-oriented production. Gujarat's chemical corridor supplies polymer feedstock to emerging thermoforming operations serving Western India quick-service chains.
Japan
Automotive and electronics assembly lines in Aichi Prefecture specify JIS-standard dimensional tolerances for industrial tray applications. METI circular economy frameworks encourage reusable container systems in corporate catering logistics. Osaka-Kobe industrial clusters maintain precision molding capacity for temperature-sensitive food service tray structures.
Trays Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on material and forming technology. The vendor base stratifies between global packaging conglomerates with integrated resin-to-tray manufacturing and regional molded pulp specialists with proprietary barrier coating formulations. Three archetypes dominate: multinational converters with captive raw material positions, mid-scale fiber specialists with certified aqueous coating platforms, and industrial distributors aggregating fragmented demand. Competitive moves concentrate on direct procurement relationship capture and molded fiber capacity expansion ahead of regulatory deadlines.
Among Finland-based packaging groups, Huhtamaki Oyj occupies a position exemplifying global fiber and molded pulp technology leverage. US-based Pactiv Evergreen Inc. and Sonoco Products Company anchor the North American foodservice supply tier. These three entities represent distinct competitive positioning vectors: European premium quick-service penetration, integrated resin-to-tray Gulf Coast manufacturing, and engineered paperboard specialization for temperature-sensitive applications.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Pactiv Evergreen Inc. |
| Genpak LLC |
| Sonoco Products Company |
| Winpak Ltd. |
| Amcor |
| Berry Global Inc. |
| Sealed Air Corporation |
| Mondi Group plc |
| Others |
Value Chain & Pricing Dynamics
Commodity resin price volatility along US Gulf Coast and Middle Eastern petrochemical corridors determines both pricing tier spreads and supply chain shape across tray manufacturing. Quick-service operators face compressed margins when polypropylene feedstock costs spike, while fiber-based alternatives track OCC pulp markets through Chinese import restriction cycles.
Pricing Analysis
Volume-discount tiering structures separate national quick-service chains from regional distribution cooperatives and fragmented independent operators. Pricing stratifies across premium certified-fiber, standard thermoformed plastic, and economy uncoated paperboard tiers, with differentiation driven by barrier coating performance and SAMR GB certification status. Cost compression in standard plastic tiers is intensifying because Gulf Coast resin production clusters face hurricane-season disruption risk. Regional distribution cooperatives exhibit highest price sensitivity due to pooled procurement volumes and limited specification control.
Supply Chain Analysis
Tariff exposure between US and Chinese molded pulp equipment suppliers dominates supply chain risk assessment for European and North American converters. Raw material sourcing draws from Chinese Yangtze River Delta fiber processing, US Gulf Coast polypropylene production, and Nordic aqueous coating chemical manufacturing. Single-source vulnerability concentrates in precision thermoforming die production, where 16-24 week procurement cycles create customer onboarding bottlenecks. Distribution runs through direct captive arrangements with quick-service chains, bypassing traditional foodservice broadliners in high-volume channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-party delivery platform interoperability requirements are reshaping tray specification standardization as food service operators demand cross-brand stackability and unified logistics handling. This platform-economics inflection rewards converters who certify early to emerging format standards.
For Market Incumbents: Pre-empt molded pulp capacity constraints by certifying aqueous barrier coating platforms ahead of ECHA REACH PFAS deadlines. Anchor Gulf Coast resin positions through long-term offtake agreements with petrochemical producers to defend against hurricane-season supply disruption. Consolidate supplier relationships with quick-service chains in Germany and France where regulatory compliance timelines are most compressed.
For New Entrants and Emerging Players: Tier-2 city markets in India offer the most penetrable geography for branded tray supply, with organized food retail infrastructure scaling faster than converter capacity expansion. Target Maharashtra and Karnataka food court developments with SAMR GB-certified export production repurposed for FSSAI-compliant domestic qualification. Pursue direct procurement relationships with emerging quick-service chains bypassing legacy distribution cooperatives.
For Investors and Strategic Acquirers: EU Single-Use Plastics Directive implementation reshapes the acquisition landscape toward fiber-based technology platforms and away from petroleum-dependent resin operations. Mid-scale molded pulp specialists with proprietary aqueous coating formulations represent the priority acquisition archetype over five-to-ten year holding periods. Monitor Chinese dual carbon policy enforcement intensity as the signal to watch for accelerated domestic capacity substitution timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Certification | ECHA REACH PFAS compliance unlocks German and French quick-service supply contracts ahead of competitor qualification. |
| Molded Pulp Capacity Expansion | Yangtze River Delta precision molding additions capture Asia-Pacific delivery platform growth and export qualification leverage. |
| Direct Procurement Relationship Capture | US Southwest and Southeast quick-service chains are displacing regional distribution cooperatives with captive supply arrangements. |
| Reusable Container-as-a-Service Pilot | Corporate catering and university food service logistics platforms test return-loop durability against single-use unit economics. |
| Dual Domestic-International Qualification | SAMR GB standards alignment enables Chinese converters to serve both domestic tier-2 city expansion and export markets. |
Study Parameters
A spread of perspectives from quick-service restaurant procurement directors, molded pulp converter operations managers, aqueous coating chemical formulators, and foodservice distribution cooperative buyers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 21 CFR filings, ECHA REACH substance restriction updates, SAMR GB standard publications, and customs trade data for OCC pulp and polypropylene resin flows. Bottom-up volume modeling from individual converter capacity announcements triangulated against top-down food service operator procurement budget disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by material substrate, end-use application, and regulatory compliance tier. CAGRs were derived from trend-line extrapolation of volume commitments disclosed in direct procurement relationships, cross-referenced against molded pulp thermoforming capacity expansion timelines and quick-service delivery platform geographic penetration rates. Industry-specific inputs included ECHA REACH PFAS restriction implementation schedules and Chinese dual carbon policy enforcement intensity assessments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated delivery logistics providers or petrochemical resin producers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Chest-Style Insulated Containers Market
Containers
Canisters Market
Containers
Dispensing Jug Market
Containers
Tin Containers Market
Containers
Multi Cavity Tray Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Compartment Trays Market
Containers
HDPE Crates Market
Containers
Bulk Containers Market
Containers
Laminated Bulk Bins Market
Containers
Lever Lid Cans Market
Containers
Algeria Container Glass Market
Containers
Flexible Water Tanks Market
Containers
Tottle Containers Market
Containers
HDPE Containers Market
Containers
Packaging Bins Market