
 Cold Chain Packaging Market | 2026-2036
Cold Chain Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Chain Packaging Market Intelligence
The gap between validated pharmaceutical-grade systems and basic food logistics packaging is repositioning how manufacturers allocate R&D budgets and production capacity. CSafe leverages aerospace-derived thermal engineering to dominate active container segments for long-haul air freight. Nordic Cold Chain Solutions anchors Nordic pharmaceutical corridors with specialized parcel shippers designed for sub-zero biologics.
Cold chain packaging comprises engineered thermal protection systems—incorporating materials such as expanded polystyrene, polyurethane foam, and vacuum insulation panels with phase-change materials—to maintain defined temperature ranges, typically 2-8°C or -20°C to -80°C, for temperature-sensitive products during storage and transit. Insulated boxes and refrigerated containers capture the largest volume share across biopharmaceutical applications, while gel packs and thermal blankets gain traction in last-mile food delivery where cost and disposability drive selection. Vacuum insulation panels command premium positioning due to superior thermal resistance per unit thickness, though corrugated fiberboard solutions expand in emerging markets where cost sensitivity shapes procurement.
FDA cold chain validation requirements and EU GDP guidelines mandate documented temperature integrity across distribution, forcing packaging suppliers to invest in sensor-integrated designs and qualification protocols. The EPA regulates refrigerant choices in active systems, while ISO 23412 provides international benchmarks for insulated shipping containers. Stakeholders must monitor how tightening pharmacopeial standards in multiple jurisdictions reshape material specifications and testing burdens for thermal packaging systems.
Market Dynamics
Cell and gene therapy commercialization is compressing development cycles for ultra-low-temperature packaging systems, forcing thermal engineers to reconcile -80°C performance requirements with air freight dimensional constraints and single-use sustainability mandates.
Growth Catalysts
- EU GDP guidelines:Tightened temperature documentation requirements are compelling pharmaceutical distributors to upgrade from basic insulated shippers to qualified thermal packaging systems with integrated data loggers.
- Biologics manufacturing concentration:Contract development and manufacturing organizations in Germany and Switzerland are expanding captive cold chain packaging operations to secure supply chain control over high-value mRNA therapies.
- Phase-change material advances:Eutectic salt formulations with tighter melting point tolerances are extending passive system duration from 72 to 120 hours, reducing active container dependency for intercontinental routes.
Market Restraints
- Polyurethane foam feedstock volatility:Isocyanate and polyol price swings are compressing margins for molded insulated container manufacturers serving generic pharmaceutical distributors.
- Active container fleet concentration:Leasing networks for refrigerated air cargo units remain concentrated among three European lessors, creating capacity bottlenecks during pandemic-response or seasonal vaccine campaigns.
- Dry ice sublimation physics:Carbon dioxide venting requirements limit payload density in -80°C parcel shippers, constraining cost-competitive positioning against liquid nitrogen dewar alternatives for cell therapy logistics.
Strategic Opportunities
- India pharmaceutical exports:CDSCO serialization mandates and expanding biosimilar production are creating demand for qualified cold chain packaging that meets EU and US import standards simultaneously.
- Reusable active container servitization:Pay-per-use leasing models with embedded IoT telemetry are displacing capital-intensive fleet ownership among mid-size biopharmaceutical distributors.
- Last-mile home infusion:Direct-to-patient delivery of temperature-sensitive biologics is opening demand for compact, patient-friendly thermal parcel designs with simplified opening protocols.
Industry Challenges
- Thermal qualification engineer scarcity:Packaging suppliers struggle to hire professionals capable of executing ISTA 7E and WHO PQS protocols within compressed product launch timelines.
- Legacy ERP integration:Sensor-integrated smart packaging generates temperature excursion data that conflicts with established pharmaceutical distribution software architectures, requiring middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Chain Packaging Market |
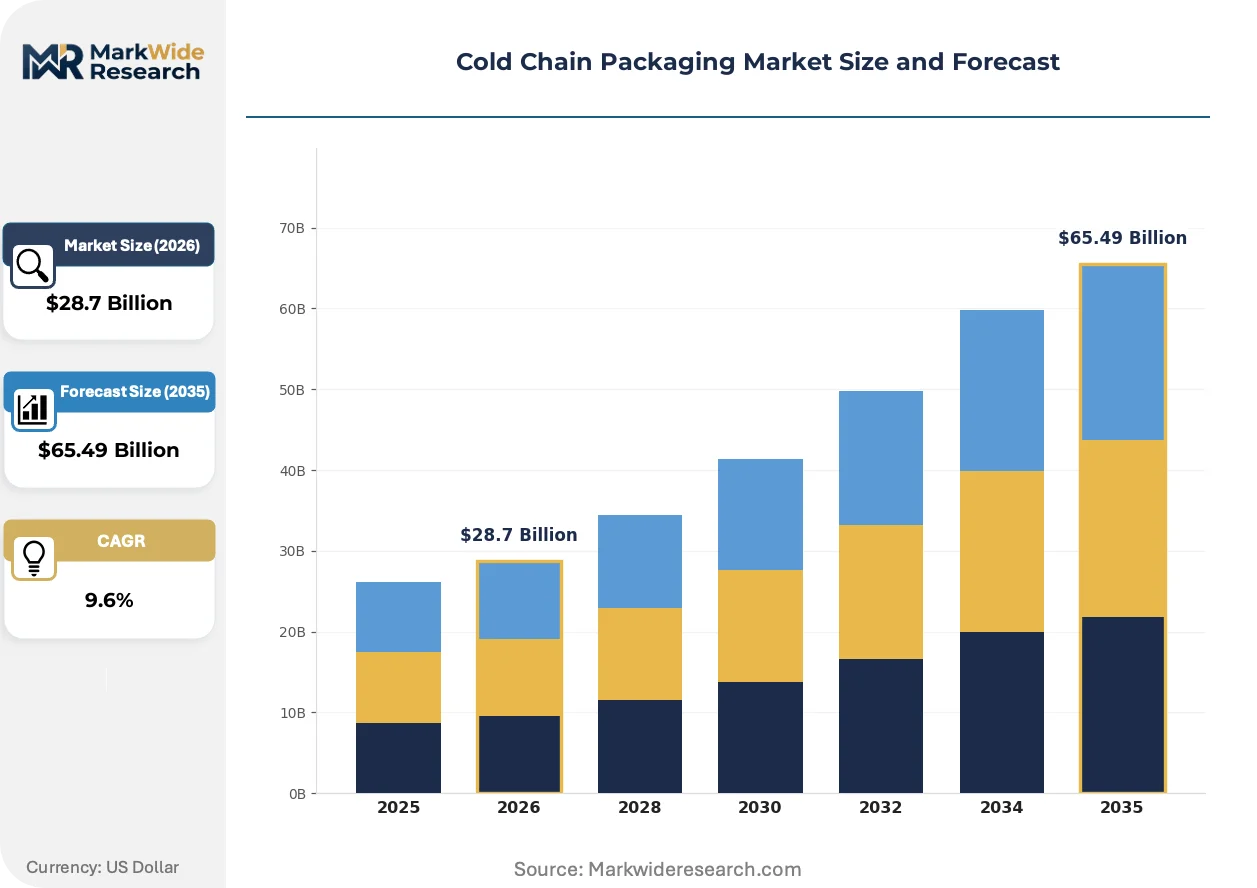
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $65.49 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Boxes, Refrigerated Containers, Gel Packs, Dry Ice, Thermal Blankets Material: Expanded Polystyrene, Polyurethane Foam, Vacuum Insulation Panels, Corrugated Fiberboard, Aluminum Application: Biopharmaceuticals, Frozen Food, Perishable Fruits, Seafood, Dairy Items End User: Logistics Providers, Pharmaceutical Distributors, Food Processors, Research Laboratories, Retailers |
| Companies Covered | CSafe, Nordic Cold Chain Solutions, Cold Chain Technologies, Sofrigam, Intelsius, Sonoco ThermoSafe, Peli BioThermal, Tower Cold Chain Solutions, Cryopak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Chain Packaging Market Strategic Shifts & Innovations
Digital thread integration across packaging design, qualification, and field performance is collapsing the feedback loop between thermal engineering and supply chain operations, compressing iteration cycles from months to weeks.
Machine learning algorithms trained on historical lane data are automating thermal packaging selection decisions that previously required manual engineering review. Third-party logistics providers deploying these tools report reduced temperature excursion rates on high-risk lanes. The technology is automating risk assessment workflows that once consumed days of analyst time.
REACH restrictions on fluorinated greenhouse gases are accelerating refrigerant transitions in active container systems from hydrofluorocarbons to hydrocarbon or carbon dioxide alternatives. Equipment manufacturers face redesign cycles to maintain cooling capacity under stricter F-Gas Regulation phase-down schedules. Cold chain operators in the EU are prioritizing lease agreements with refrigerant-compliant fleet commitments to avoid stranded asset risk.
Hospital and clinic buyers are consolidating cold chain packaging procurement through group purchasing organizations, displacing direct supplier relationships that dominated specialty pharmaceutical distribution. This concentration is compressing supplier margins while demanding extended performance guarantees and total-cost-of-ownership analytics. The shift is most visible in US oncology infusion centers managing high volumes of temperature-sensitive checkpoint inhibitors.
Cold Chain Packaging Market Segmentation
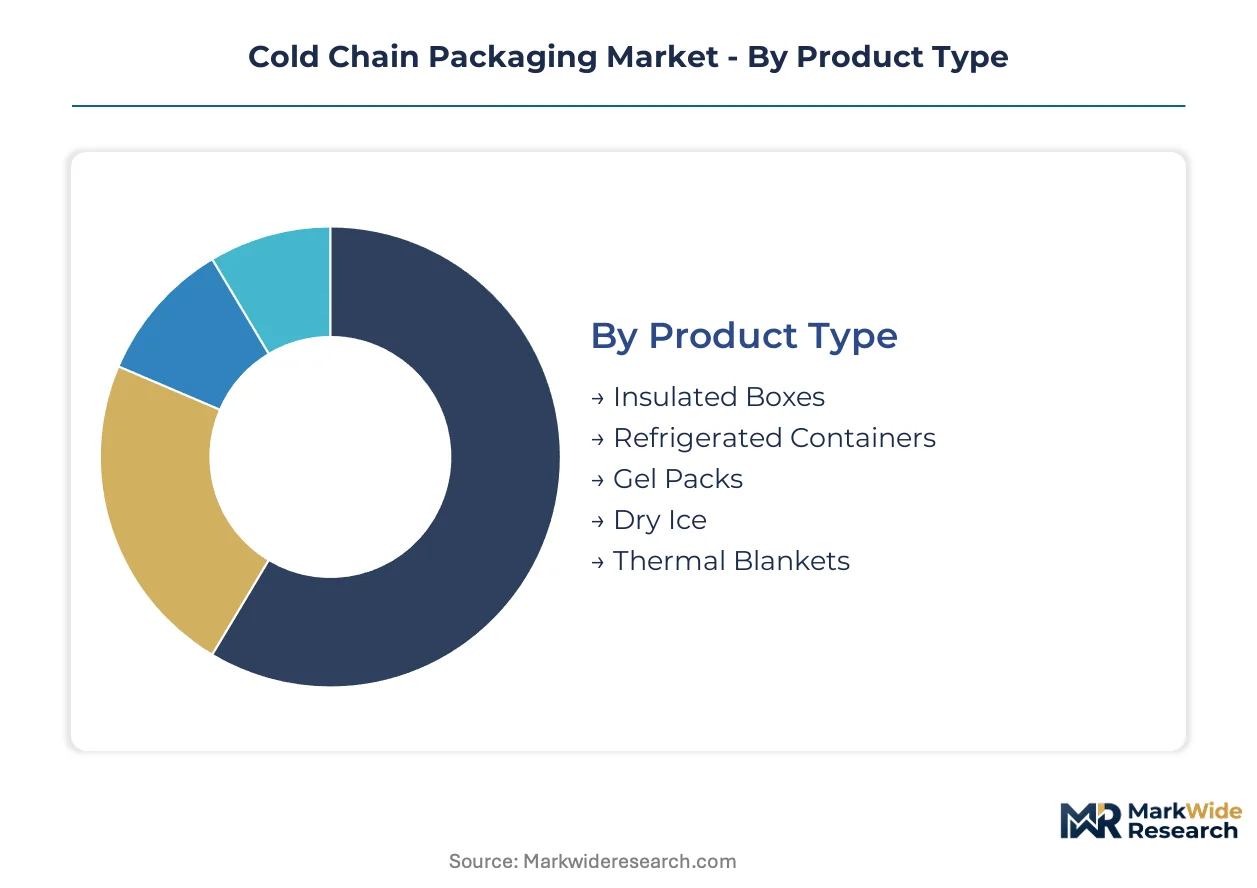
Cold chain packaging segmentation reveals how thermal protection requirements diverge across payload value, transit duration, and regulatory stringency. Material selection and product architecture decisions cascade directly into qualification protocols and total cost of ownership calculations for pharmaceutical and food logistics operators.
Product Type:
Thermal performance specifications and payload density requirements differentiate product architectures across air, road, and last-mile distribution networks.
- Insulated Boxes:Molded expanded polystyrene or polyurethane foam enclosures with phase-change material payloads dominate parcel-scale biopharmaceutical distribution. German pharmaceutical exporters deploy these for 2-8°C mRNA vaccine shipments across EU GDP-compliant lanes, balancing disposability against qualification documentation burdens.
- Refrigerated Containers:Active compressor or thermoelectric systems with integrated power management enable -20°C to -80°C holding for cell therapy logistics. Swissmedic-authorized distributors in Basel and Zurich lease these for intercontinental gene therapy shipments where passive duration limits fail.
- Gel Packs:Eutectic salt or polymer gel phase-change media provide economical thermal mass for short-duration food delivery.
- Dry Ice:Solid carbon dioxide sublimation delivers -78.5°C holding for ultra-low-temperature biologics, constrained by venting requirements and payload density limits.
- Thermal Blankets:Quilted reflective or insulated wraps protect palletized loads from ambient temperature excursions during tarmac delays or cross-docking.
Insulated boxes lead on scale; refrigerated containers lead on momentum.
Material:
Cost structures and thermal resistance coefficients position materials across premium pharmaceutical and economy food applications.
- Expanded Polystyrene:Lightweight molded foam with R-value of 5.0 per inch serves generic pharmaceutical and food logistics where single-use economics dominate. Indian pharmaceutical exporters favor EPS shippers for cost-competitive biosimilar distribution to African markets.
- Vacuum Insulation Panels:Fumed silica or fiberglass core panels with evacuated barrier films achieve R-values exceeding 30 per inch. Japanese PMDA-compliant distributors deploy VIP-based parcel shippers for 120-hour duration requirements on transpacific oncology drug lanes.
- Polyurethane Foam:Spray or molded rigid foam systems offer intermediate thermal performance with structural integrity for reusable active container insulation.
- Corrugated Fiberboard:Recyclable paper-based insulation with air-cell structures expands in emerging markets where environmental regulations and cost sensitivity align.
- Aluminum:Sheet or honeycomb structures provide conductive thermal management and electromagnetic shielding for specialized active container interiors.
Expanded polystyrene dominates volume; vacuum insulation panels command premium expansion.
Application:
Payload value and temperature tolerance windows determine packaging investment intensity across verticals.
- Biopharmaceuticals:Cell therapies, monoclonal antibodies, and mRNA vaccines demand validated 2-8°C, -20°C, or -80°C systems with continuous data logging. FDA cold chain validation requirements and EU GDP guidelines mandate documented thermal qualification for every lane and season.
- Frozen Food:Ice cream, prepared meals, and seafood require -18°C maintenance through multi-modal distribution networks with less stringent documentation than pharmaceutical applications.
- Perishable Fruits:Controlled atmosphere and temperature-managed packaging extends shelf life for berries, stone fruits, and tropical imports.
- Seafood:Fresh and frozen fish products combine ice, gel packs, and insulated containers for temperature and humidity control.
- Dairy Items:Cheese, yogurt, and milk products utilize refrigerated transport with insulated secondary packaging for last-mile delivery.
Biopharmaceuticals anchor revenue; frozen food sustains volume.
End User:
Procurement sophistication and qualification capabilities separate end-user categories.
- Pharmaceutical Distributors:McKesson, AmerisourceBergen, and regional EU operators maintain captive thermal packaging engineering teams to execute ISTA 7E and WHO PQS protocols. These organizations specify qualified systems with embedded IoT sensors and automated excursion alerting.
- Logistics Providers:DHL Supply Chain, FedEx Health Solutions, and specialized cold chain 3PLs deploy hybrid active-passive fleets with lane-specific packaging selection algorithms.
- Food Processors:Dairy cooperatives and frozen food manufacturers specify packaging through procurement teams focused on unit economics rather than qualification documentation.
- Research Laboratories:Academic and clinical trial sites require small-volume, flexible thermal solutions for specimen and investigational product transport.
- Retailers:Grocery chains and pharmacy networks consolidate cold chain packaging procurement through group purchasing organizations, demanding total-cost-of-ownership analytics.
Pharmaceutical distributors set technical standards; logistics providers scale operational deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical packaging engineers cluster in Basel, Frankfurt, and Boston, anchoring the industry's technical workforce concentration. These talent pools drive qualification protocol development and thermal system innovation across three continents.
Germany
Contract development and manufacturing organizations in Baden-Württemberg and Bavaria expand captive cold chain packaging operations for mRNA therapies. EU GDP guidelines mandate qualified thermal systems with integrated data loggers for pharmaceutical exports. Frankfurt's distribution hubs deploy advanced passive and active packaging systems for intercontinental biologics shipments.
United States
FDA cold chain validation requirements tighten thermal performance documentation for cell and gene therapy commercialization. The EPA regulates refrigerant choices in active container systems, accelerating transitions from hydrofluorocarbons. Greater Boston's biotech corridor drives demand for -80°C qualified shippers with embedded IoT telemetry.
Switzerland
Swissmedic-authorized distributors in Basel and Zurich lease active refrigerated containers for intercontinental gene therapy logistics. The country's pharmaceutical regulator enforces stringent temperature integrity standards exceeding baseline EU requirements. Zurich's centralized distribution infrastructure supports ultra-low-temperature packaging validation for European biopharmaceutical networks.
India
CDSCO serialization mandates and expanding biosimilar production create demand for qualified cold chain packaging meeting EU and US import standards. The country's national pharmaceutical regulator aligns domestic requirements with international benchmarks. Maharashtra's pharmaceutical manufacturing clusters adopt thermal packaging systems for cost-competitive biosimilar exports to African and Southeast Asian markets.
Japan
PMDA-compliant distributors deploy vacuum insulation panel-based parcel shippers for 120-hour duration requirements on transpacific oncology drug lanes. METI promotes cold chain infrastructure investment for biopharmaceutical exports. Tokyo-Yokohama's logistics networks concentrate demand for premium thermal protection systems serving domestic and regional pharmaceutical distribution.
Cold Chain Packaging Market Key Industry Players
Top-tier vendors anchor the active container segment, while specialized passive system fabricators occupy mid-market positioning. The vendor base stratifies across three tiers: aerospace-derived thermal engineering specialists, regional pharmaceutical corridor operators, and emerging market cost-optimized suppliers. Two strategic archetypes dominate: integrated lessors with captive fleet networks, and qualification-focused engineering houses. Competitive moves concentrate on reusable container servitization and sensor-embedded smart packaging development.
Within the aerospace-derived engineering tier, CSafe occupies a position exemplifying advanced active container design for long-haul air freight. Nordic Cold Chain Solutions anchors the specialized passive segment with parcel shipper systems engineered for sub-zero biologics. Cold Chain Technologies represents the diversified engineering house archetype, spanning multiple temperature ranges and transit duration requirements.
| Leading Market Players |
|---|
| CSafe |
| Nordic Cold Chain Solutions |
| Cold Chain Technologies |
| Sofrigam |
| Intelsius |
| Sonoco ThermoSafe |
| Peli BioThermal |
| Tower Cold Chain Solutions |
| Cryopak |
| Others |
Cost & Logistics Intelligence
Phase-change material formulation advances are compressing production economics for passive thermal systems while simultaneously concentrating supply among German and Swiss specialty chemical suppliers with proprietary eutectic salt expertise. This dual effect reshapes how packaging manufacturers source thermal mass components and negotiate long-term supply agreements.
Pricing Analysis
The bundled-versus-unbundled service split separates active container lessors who embed telemetry and qualification documentation from commodity passive shipper vendors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA-validated systems command substantial premiums over basic EU GDP-compliant alternatives. Pricing pressure stems from polyurethane foam feedstock volatility squeezing molded container margins. Generic pharmaceutical distributors exhibit highest price sensitivity, while cell therapy developers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers of evacuated barrier films for vacuum insulation panels, where three producers control global capacity. Raw material flows draw from German isocyanate specialists, Japanese fumed silica suppliers, and Saudi petrochemical feedstock complexes. Tariff exposure on aluminum honeycomb structures threatens active container cost structures. Distribution runs through Frankfurt and Basel pharmaceutical corridors, with Mumbai and Singapore emerging as secondary consolidation nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cold Chain Packaging Market functions as a stable compounder anchored by irreversible biopharmaceutical logistics complexity that sustains premium pricing power across economic cycles.
For Market Incumbents: Hedge refrigerant transition risk by accelerating hydrocarbon and carbon dioxide system R&D ahead of EU F-Gas Regulation phase-down deadlines. Secure captive phase-change material supply through backward integration into eutectic salt formulation or long-term offtake agreements with BASF and Clariant specialty chemical divisions. Defend against modular reusable container startups by embedding IoT telemetry as standard rather than premium feature. For New Entrants and Emerging Players: Capture last-mile home infusion packaging demand where patient-friendly thermal parcel designs remain underdeveloped against clinical site logistics saturation. Target Indian pharmaceutical exporters requiring simultaneous EU and US qualification compliance for biosimilar distribution to African markets. Lead with pay-per-use servitization models that displace capital-intensive fleet ownership among mid-size biopharmaceutical distributors lacking captive engineering teams. For Investors and Strategic Acquirers: Valuations sit cheapest among regional passive system fabricators with ISO 23412 qualification capabilities but limited active container exposure. Long-term viability centers on sensor-embedded smart packaging development and reusable container fleet networks with embedded telemetry. Watch for CDSCO enforcement actions on Indian pharmaceutical exports as signal of qualification standard tightening that benefits compliant packaging suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Qualification Protocol Harmonization | Consolidated ISTA 7E and WHO PQS documentation reduces pharmaceutical distributor vendor management burden. |
| Refrigerant Fleet Transition | EU F-Gas Regulation compliance commitments from active container lessors prevent stranded asset risk. |
| IoT Telemetry Standardization | Embedded sensor integration with automated excursion alerting meets FDA cold chain validation requirements. |
| Regional Captive Packaging Operations | CDMOs in Baden-Württemberg secure supply chain control over high-value mRNA therapies. |
| Phase-Change Material Duration Extension | Eutectic salt advances from 72 to 120 hours reduce active container dependency on intercontinental lanes. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with thermal packaging engineers, pharmaceutical distribution executives, cold chain logistics procurement managers, and regulatory affairs specialists with secondary validation. Primary fieldwork drew from FDA guidance documents, EMA GDP inspection reports, ISTA test protocols, and WHO PQS prequalification listings. Bottom-up modeling of insulated container, refrigerated unit, and phase-change material shipments triangulated against top-down pharmaceutical logistics spend estimates.
Granularity-level modeling deployed product type, material composition, temperature range specification, and end-user procurement sophistication as core segmentation dimensions across the projection horizon. CAGRs derived from historical volume trajectories adjusted for cell and gene therapy commercialization acceleration, EU GDP guideline enforcement timing, and REACH refrigerant restriction implementation schedules. Forecast inputs incorporated biopharmaceutical manufacturing capacity expansion announcements and air freight lane temperature excursion rate trends.
Regulatory enforcement delays, phase-change material supply disruptions, and active container fleet concentration bottlenecks are the dominant revision risks that could compress or extend growth trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market