
 United States and Europe Reusable Plastic Returnable Transport Packaging Market | 2026-2036
United States and Europe Reusable Plastic Returnable Transport Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States and Europe Reusable Plastic Returnable Transport Packaging Market Analytics
Food & Beverage retailers is unwinding the historical dominance of automotive buyers in pooled packaging procurement. Orbis Corporation leverages its captive North American manufacturing base to serve grocery distribution networks. Tosca Ltd anchors European fresh-produce pooling through its RPC wash-and-return infrastructure. Schoeller Allibert Services B.V. competes on modular crate standardization across multilingual supply chains.
Reusable plastic returnable transport packaging denotes closed-loop handling systems fabricated from polypropylene or high-density polyethylene, typically rated for 50–100 use cycles, designed to replace single-trip expendable packaging in repetitive logistics lanes. The primary purpose centers on reducing per-trip material cost, eliminating corrugated waste disposal, and stabilizing unit-load dimensions for automated warehouse handling. Plastic pallets and containers command the largest product volume pools, though dollies are gaining velocity in last-mile grocery replenishment. High-density polyethylene formulations lead material selection for impact resistance in cold-chain produce applications, while polypropylene dominates automotive component totes where dimensional tolerance matters. Margin pools concentrate in wash-and-lease pooling services rather than virgin equipment sales.
The EPA promotes sustainable materials management frameworks that indirectly incentivize reusable transport systems over disposable alternatives. The EU Green Deal and REACH compliance requirements restrict certain additives in virgin plastic compounds, pushing converters toward certified recyclate streams. FDA food-contact regulations in the United States govern wash-process validation for containers circulating between meat processors and retailers. Stakeholders must track how California's extended producer responsibility legislation and Germany's VerpackG amendments alter cost allocation between packaging owners and brand manufacturers.
Market Dynamics
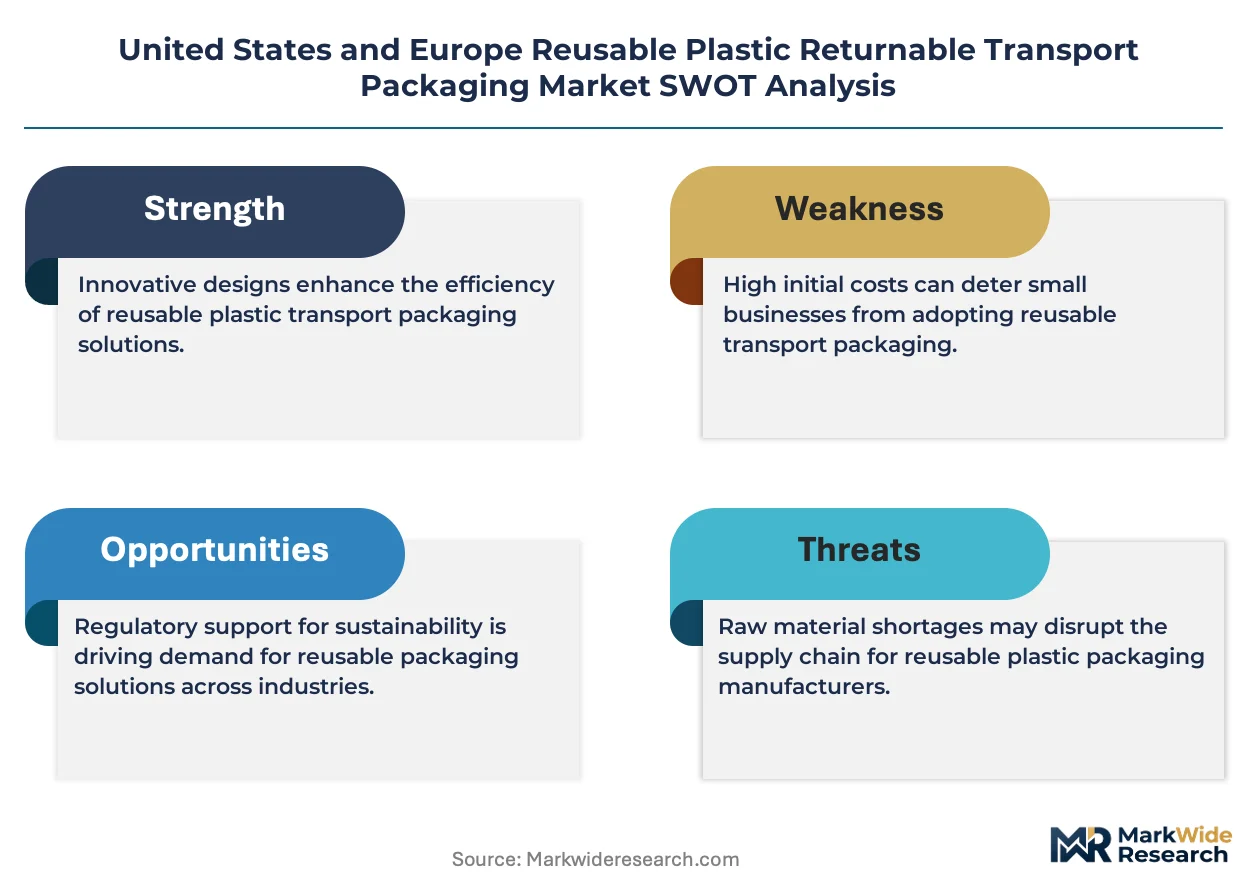
The EU Packaging and Packaging Waste Regulation is forcing Food & Beverage retailers to abandon corrugated one-way packaging in favor of pooled plastic container systems, compressing the traditional automotive dominance in procurement.
Growth Catalysts
- Reuse Mandates:The EU Green Deal tightens circular economy requirements for transport packaging, compelling brand manufacturers to adopt closed-loop systems for regulatory compliance.
- Cold-Chain Expansion:Fresh-produce distribution networks in Germany and the Upper Midwest are converting to high-density polyethylene containers for temperature stability across wash cycles.
- Automation Compatibility:Standardized polypropylene totes enable automated warehouse handling in automotive supplier corridors, reducing manual sortation labor.
Market Restraints
- Resin Price Volatility:Polypropylene and high-density polyethylene feedstock costs fluctuate with crude oil indices, compressing margin pools for wash-and-lease operators.
- Pool Concentration Risk:Equipment ownership concentrates among three major pooling service providers across the United States and Europe, limiting buyer negotiation leverage.
- Corrugated Substitution:Lightweight paper-based alternatives advance in ambient dry-goods lanes where moisture resistance matters less.
Strategic Opportunities
- Last-Mile Dollies:Grocery replenishment networks in urban European centers are deploying wheeled platforms for store-backstock efficiency, creating new equipment categories.
- Certified Recyclate Streams:REACH compliance requirements push converters toward post-consumer resin certification, differentiating premium pool offerings.
- Modular Standardization:Multilingual supply chains across Benelux and the Rhine-Ruhr corridor demand interoperable crate footprints for cross-border pooling.
Industry Challenges
- Wash-Process Validation:FDA food-contact regulations require documented sanitation protocols for containers circulating between meat processors and retailers, extending deployment timelines.
- Legacy System Integration:ERP platforms at mid-tier distributors lack real-time tracking modules for returnable asset pools, forcing manual reconciliation.
- Skill Scarcity in Pool Logistics:Fleet optimization for 50-100 use cycles demands specialized expertise in reverse logistics planning that remains underdeveloped in regional labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States and Europe Reusable Plastic Returnable Transport Packaging Market |
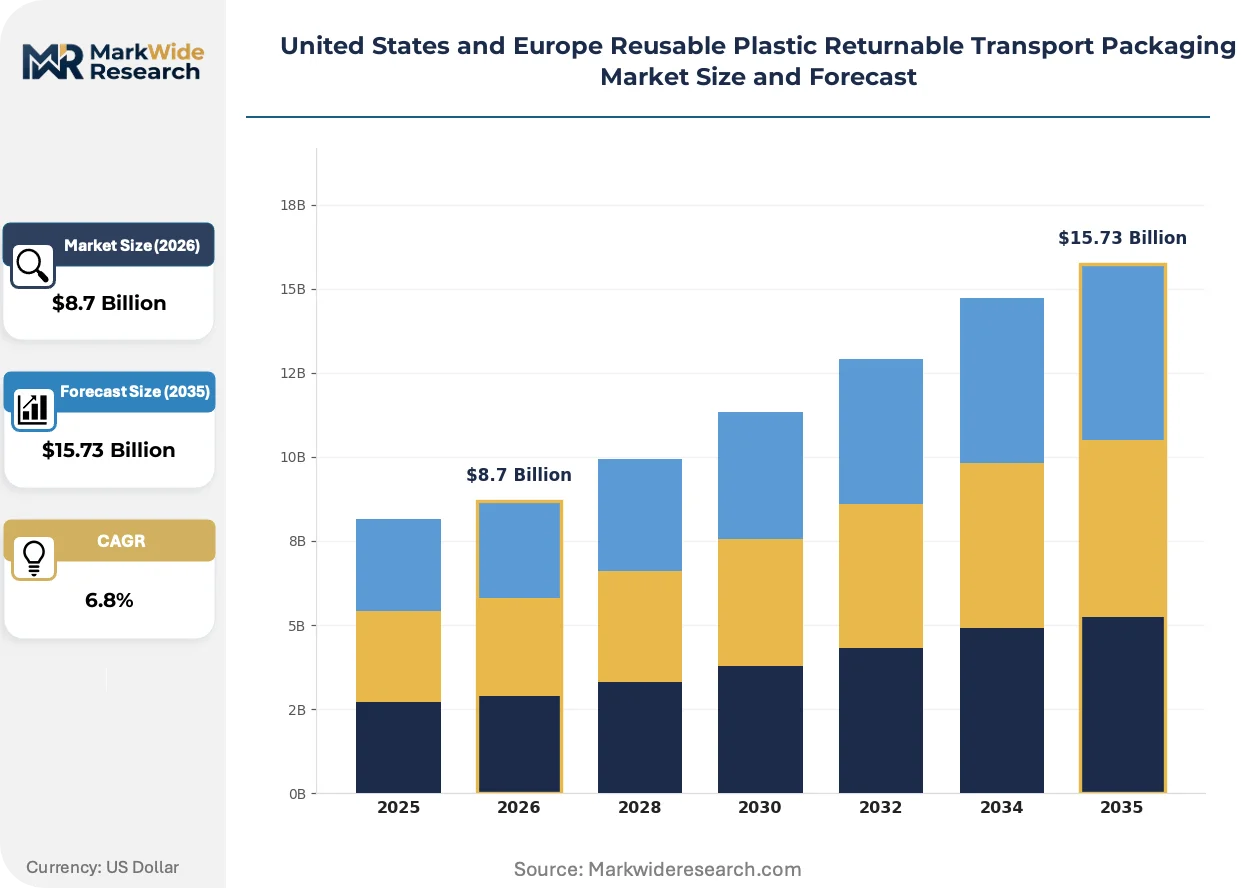
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Pallets, Containers, Crates, Dollies End User: Automotive, Food & Beverage, Pharmaceuticals, Electronics Distribution Channel: Direct Sales, Online Stores, Distributors, Manufacturers Material: Polypropylene, High-Density Polyethylene, Polyvinyl Chloride, Others |
| Companies Covered | Orbis Corporation (Menasha Corporation), Tosca Ltd, IFCO Systems N.V., Corplex Corporation, Schaefer Systems International Inc., Brambles Limited (CHEP), CABKA N.V., RPP Containers, Schoeller Allibert Services B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States and Europe Reusable Plastic Returnable Transport Packaging Market Evolving Landscape
Embedded tracking technologies and material science advances are compressing cost-per-trip economics while regulatory pressure accelerates the displacement of single-use alternatives in repetitive logistics lanes.
Radio-frequency identification tags integrated into polypropylene container bases are miniaturizing to sub-centimeter form factors. Automotive component suppliers in Germany's supplier corridors are adopting these tags for real-time location tracking. The technology is miniaturizing hardware costs sufficiently to justify deployment in lower-value produce crates.
The EU Packaging and Packaging Waste Regulation establishes mandatory reuse targets for transport packaging categories. Brand manufacturers must demonstrate measurable circularity metrics or face penalties. Fresh-produce pooling networks across the Netherlands and Belgium are restructuring lease agreements to guarantee minimum rotation frequencies.
Buyer consolidation among North American grocery distributors is compressing supplier qualification timelines. Regional pooling cooperatives are displacing single-source lease arrangements as retailers demand redundant supply. This pattern concentrates most visibly in the Upper Midwest distribution belt where three buying groups control majority volume.
United States and Europe Reusable Plastic Returnable Transport Packaging Market Segmentation
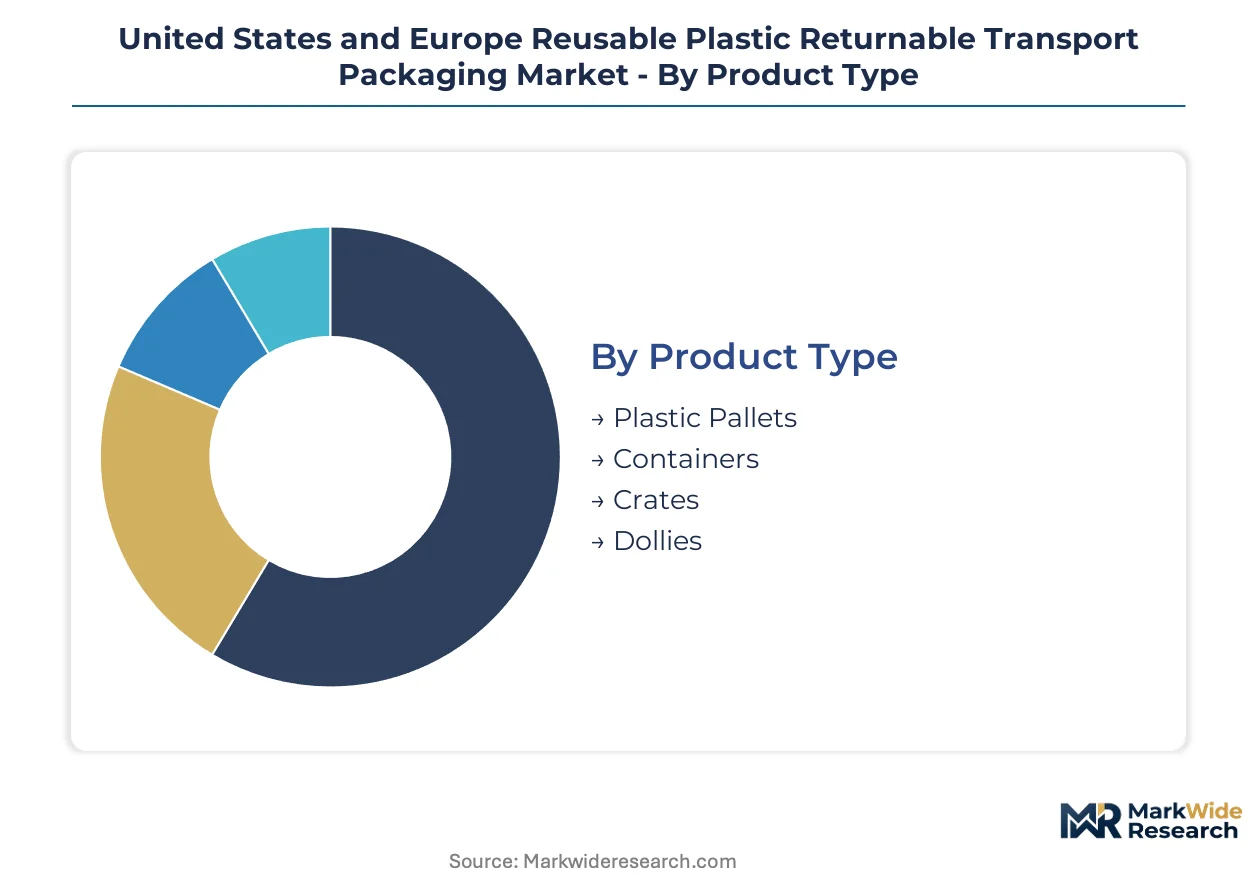
Segmentation in this market reveals how regulatory pressure and application-specific durability requirements split demand across material formulations and equipment categories. Buyers prioritize cold-chain performance in fresh produce lanes against dimensional precision in automotive supplier networks.
Product Type:
REACH compliance for polypropylene additives and FDA wash-process validation requirements differentiate equipment categories by regulatory burden and end-use eligibility.
- Plastic Pallets:Unit-load platforms fabricated from high-density polyethylene or polypropylene blends, rated for 50-100 use cycles in automated warehouse systems. Demand concentrates in Germany's automotive supplier corridors where dimensional tolerance enables robotic handling; the EU Packaging and Packaging Waste Regulation tightens reuse mandates that favor pallet pooling over expendable alternatives.
- Containers:Enclosed or lidded receptacles for component or bulk goods protection, dominant in closed-loop produce distribution. The Upper Midwest distribution belt drives volume for meat processor-to-retailer lanes where FDA food-contact regulations govern wash-process validation.
- Crates:Ventilated or solid-walled handheld containers for manual or automated sortation. Benelux fresh-produce networks demand modular standardization across multilingual supply chains.
- Dollies:Wheeled platforms for store-backstock efficiency in urban grocery replenishment. Last-mile deployment is accelerating in European city centers.
Plastic pallets handle the majority of throughput; dollies are gaining share fastest on last-mile velocity.
End User:
Procurement authority is shifting from automotive tier-one suppliers toward grocery distribution networks as reuse mandates tighten.
- Automotive:Component totes and sequencing containers for just-in-time supplier delivery. Germany's Rhine-Ruhr corridor anchors demand where polypropylene dimensional stability enables automated sortation.
- Food & Beverage:Fresh-produce pooling and protein distribution networks. The Upper Midwest buying groups and Netherlands-Belgium corridors are converting corrugated lanes to high-density polyethylene cold-chain systems.
- Pharmaceuticals:Temperature-validated containers for clinical trial logistics and API distribution. EU GDP guidelines and FDA 21 CFR Part 11 traceability requirements apply.
- Electronics:ESD-rated totes for semiconductor and component handling. Cleanroom wash protocols differentiate service tiers.
Food & Beverage commands the largest procurement volume; automotive retains the densest pool concentration per lane.
Distribution Channel:
Channel selection depends on fleet scale requirements and the buyer's internal reverse logistics capability.
- Direct Sales:Large-volume equipment purchases by national grocery distributors and automotive OEMs. Captive pool ownership suits high-frequency lanes with dedicated return infrastructure.
- Online Stores:Standardized crate and tote procurement for mid-tier distributors with intermittent replenishment needs. Digital catalogs reduce qualification timelines.
- Distributors:Regional stocking points for mixed-SKU orders and emergency replacement. Upper Midwest cooperatives leverage distributor networks for redundant supply.
- Manufacturers:Specified equipment direct from converters for custom footprints or embedded RFID integration. REACH-compliant recyclate certification drives premium tiering.
Direct sales dominate automotive procurement; distributor channels are expanding most quickly in grocery cooperative consolidation.
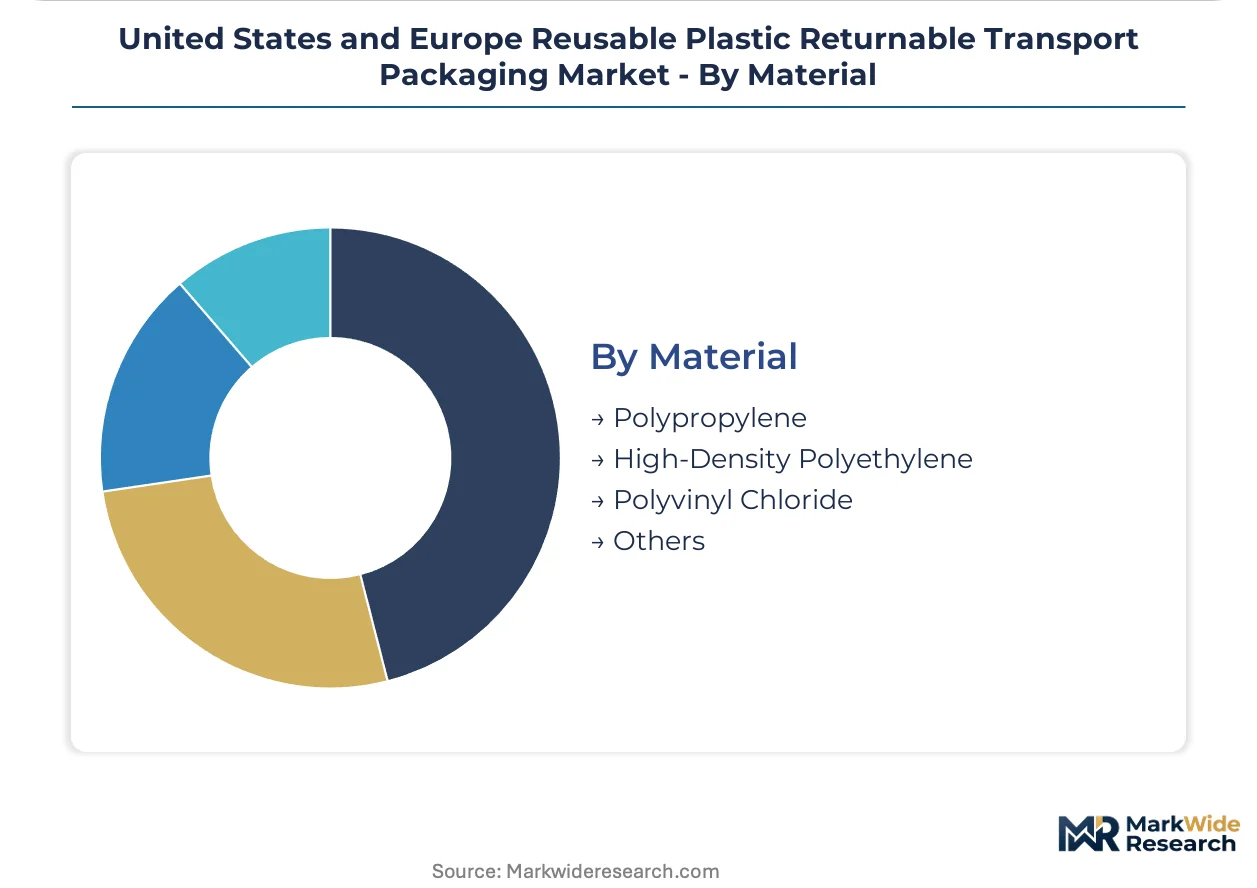
Material:
Resin selection balances impact resistance, dimensional stability, and regulatory compliance for food-contact or automotive applications.
- Polypropylene:Semi-crystalline thermoplastic with high stiffness and chemical resistance, preferred for automotive component totes where dimensional tolerance prevents jamming in automated systems. REACH restrictions on certain additives push converters toward certified recyclate streams.
- High-Density Polyethylene:Linear polymer with superior low-temperature impact resistance, dominant in cold-chain produce containers. FDA wash-process validation requirements govern its deployment between meat processors and retailers.
- Polyvinyl Chloride:Rigid formulation for chemical-resistant applications in industrial component handling. Regulatory scrutiny on plasticizer migration limits food-contact eligibility.
- Others:Engineering-grade blends and post-consumer recyclate compounds for specialized durability or sustainability credentials. EU Green Deal circularity metrics accelerate adoption.
High-density polyethylene handles the majority of fresh-produce volume; polypropylene retains the tightest specification tolerance in automotive lanes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor anchors European pooling logistics, while Union Pacific and BNSF rail spines enable Upper Midwest container circulation across the United States.
Germany
Automotive supplier corridors along the Rhine-Ruhr and Stuttgart regions drive polypropylene tote demand for just-in-time sequencing. REACH compliance requirements restrict certain additives in virgin plastic compounds, pushing converters toward certified recyclate streams. Bavaria's wash-and-return infrastructure serves as the continental hub for cross-border pooling into Austria and Switzerland.
United States
The Upper Midwest distribution belt—spanning Illinois, Wisconsin, and Michigan—concentrates fresh-produce pooling volume as grocery cooperatives displace corrugated lanes. FDA food-contact regulations govern wash-process validation for containers circulating between meat processors and retailers. Chicago's intermodal rail terminals function as the primary consolidation point for HDPE container redistribution.
Netherlands
Rotterdam's port complex enables import-export pooling for fresh-produce networks serving German and Belgian retail chains. The EU Packaging and Packaging Waste Regulation tightens reuse mandates for transport packaging categories. Benelux multilingual supply chains demand modular crate standardization across Dutch-Belgian-German border zones.
France
Île-de-France grocery distribution networks are converting ambient dry-goods lanes to pooled plastic systems under EU Green Deal circularity metrics. ECHA restrictions on certain plasticizer formulations limit PVC eligibility for food-contact applications. The Paris basin's automated warehouse density favors standardized polypropylene totes for robotic handling compatibility.
Belgium
Antwerp's port infrastructure supports transatlantic container pooling for pharmaceutical and food-grade applications requiring temperature validation. EU GDP guidelines and FDA 21 CFR Part 11 traceability requirements apply to clinical trial logistics networks. Flanders' dense road freight corridors enable high-frequency rotation cycles for 50-100 use equipment pools.
United States and Europe Reusable Plastic Returnable Transport Packaging Market Competitive Landscape
Concentration sits with integrated pooling service providers that combine captive manufacturing with wash-and-lease fleet operations. Three archetypes dominate: North American manufacturers with grocery distribution specialization, European wash-and-return infrastructure operators, and modular standardization specialists serving multilingual supply chains. Competitive moves center on backward integration into resin compounding and geographic expansion through regional cooperative partnerships.
Among North American fabricators, Orbis Corporation exemplifies the captive manufacturing archetype with dedicated production serving grocery networks. Tosca Ltd anchors European fresh-produce pooling through its RPC wash-and-return infrastructure. Schoeller Allibert Services B.V. occupies a position within the modular standardization tier for cross-border Benelux and Rhine-Ruhr corridors.
| Leading Market Players |
|---|
| Orbis Corporation (Menasha Corporation) |
| Tosca Ltd |
| IFCO Systems N.V. |
| Corplex Corporation |
| Schaefer Systems International Inc. |
| Brambles Limited (CHEP) |
| CABKA N.V. |
| RPP Containers |
| Schoeller Allibert Services B.V. |
| Others |
Value Network & Pricing Analysis
Captive wash-and-lease fleet scale in the Upper Midwest and Rhine-Ruhr corridors compresses per-trip cost floors for pooled container systems while concentrating pricing power among integrated service providers. Pool operators leverage high fixed-asset utilization to undercut virgin equipment sales, forcing converters toward certified recyclate tiering to defend margin pools.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on rotation frequency guarantees and REACH-compliant recyclate certification. Price differentiation hinges on FDA wash-process validation tier and embedded RFID integration density. Cost compression in standard-grade HDPE containers is intensifying because resin feedstock volatility compresses lease-operator margins. Mid-tier grocery cooperatives exhibit highest price sensitivity due to pooled procurement leverage, while pharmaceutical networks show lowest sensitivity given GDP temperature-validation requirements.
Supply Chain Analysis
Just-in-time container circulation dominates fresh-produce networks, while automotive supplier corridors prefer strategic stockpiles of polypropylene totes against sequencing disruption risks. Manufacturing concentration clusters in Germany, the Netherlands, and Michigan where captive compounding facilities feed wash-and-return infrastructure. Raw material dependencies center on polypropylene resin, high-density polyethylene pellets, and post-consumer recyclate streams certified under EU circularity metrics. Single-source vulnerability runs through three major pooling service providers controlling majority fleet ownership. Distribution feeds from regional rail terminals—Chicago intermodal hubs and Rotterdam port complexes—into last-mile grocery replenishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Upper Midwest grocery cooperatives and Benelux retail buying groups, compressing supplier qualification timelines and forcing redundant pool arrangements.
For Market Incumbents: Compound defensive positioning through backward integration into REACH-compliant recyclate compounding and captive expansion of wash-process capacity in Bavaria. Corrugated substitution in ambient dry-goods lanes threatens standard-grade container demand. Certification investment in FDA-validated cold-chain infrastructure represents the critical lever for pharmaceutical network capture.
For New Entrants and Emerging Players: FDA food-contact certification fast-tracks unlock meat processor-to-retailer lanes where incumbent pool concentration remains lowest. White-space targets include urban last-mile dollies for European grocery replenishment and modular crate standardization across Dutch-Belgian-German border zones. Go-to-market execution should anchor in regional distributor partnerships for redundant supply qualification.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wash-and-return infrastructure operators over virgin equipment fabricators as reuse mandates tighten. Long-term viability rests on fleet scale and geographic density in automotive supplier corridors or fresh-produce distribution belts. Acquisition targets should display embedded RFID deployment capability and cross-border pooling agreements. The signal to watch is California extended producer responsibility legislation adoption rate as inflection indicator for North American regulatory convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recyclate Compounding | REACH compliance requirements push converters toward certified post-consumer resin streams for premium tiering. |
| Wash-Process Capacity Expansion | FDA food-contact validation infrastructure in Bavaria anchors cross-border pooling into Austria and Switzerland. |
| Embedded RFID Deployment | Miniaturized tracking hardware justifies deployment in lower-value produce crates across Netherlands-Belgium corridors. |
| Regional Cooperative Partnerships | Upper Midwest buying groups demand redundant supply arrangements displacing single-source lease structures. |
| Modular Standardization Investment | Multilingual Benelux supply chains require interoperable crate footprints for cross-border rotation efficiency. |
Research Methodology
Initial hypotheses were tested against primary input from pool fleet managers, grocery distribution procurement leads, automotive Tier 1 supplier logistics directors, and wash-process validation engineers, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary triangulation across EPA sustainable materials management frameworks, EU Packaging and Packaging Waste Regulation impact assessments, FDA food-contact guidance documents, and REACH compliance databases. Bottom-up equipment deployment estimates and top-down circular economy mandate trajectories were reconciled through iterative segmentation modeling.
Variance decomposition across product type, material formulation, end-use industry, and geographic corridor dimensions structured the analytical framework over the projection horizon. CAGRs were derived from equipment pool rotation frequency assumptions and regulatory compliance timeline phasing. Industry-specific forecast inputs incorporated resin price volatility indices and automation compatibility adoption curves in automotive supplier networks.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and stable Upper Midwest grocery cooperative consolidation; material deviation would warrant model refresh. Revision becomes warranted when REACH recyclate certification cost thresholds or California extended producer responsibility implementation timelines cross critical adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market