
 Old Corrugated Containers (OCC) Market | 2026-2036
Old Corrugated Containers (OCC) Market Size, Share, and Industry Trends Forecast 2026-2036
Old Corrugated Containers (OCC) Market Analytics
Forest Stewardship Council (FSC) chain-of-custody certification is unwinding the competitive landscape, disqualifying smaller collectors who cannot trace fiber origins. Smurfit Kappa Group leverages its integrated European mill network to sustain certified pulp output at scale. WestRock Company anchors North American supply through controlled access to municipal recycling streams. International Paper competes by dominating the corrugated medium segment with thermomechanical pulping expertise.
Old corrugated containers consist of fluted paperboard layers bonded between flat linerboards, typically containing 80-100% post-consumer fiber with burst strengths ranging from 150 to 400 pounds per square inch depending on wall construction. The material serves primarily as protective packaging for goods in transit and as feedstock for recycled paper manufacturing. Double-wall OCC commands the deepest margin pools in the Food & Beverage end-user segment, where moisture resistance requirements justify premium pricing. Mechanical recycling leads volume globally, though chemical depolymerization methods are gaining traction in Electronics applications where contamination sensitivity demands cleaner fiber recovery.
The US EPA sets baseline recovery targets that shape municipal collection economics, while the EU Green Deal's packaging waste directives enforce escalating recycled-content thresholds for shipping materials entering European markets. India's BIS certification standards for recycled paperboard are tightening test protocols for burst strength and ring crush metrics, raising barriers for uncertified imports. Stakeholders must monitor how fragmented regulatory timelines across Washington, Brussels, and New Delhi reshape arbitrage opportunities for OCC traders.
Market Dynamics
The OCC market is experiencing a structural squeeze between tightening recycled-content mandates from Brussels and the scramble for certified fiber traceability that smaller collectors cannot satisfy.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Escalating recycled-content thresholds for shipping materials entering European markets force converters to lock in long-term OCC supply contracts.
- E-commerce fulfillment infrastructure:Sortation hubs operated by Amazon and Flipkart across India's Maharashtra and Gujarat corridors absorb record volumes of double-wall and reinforced OCC for protective shipping.
- Mechanical recycling advancement:Thermomechanical pulping expertise enables higher-yield fiber recovery from contaminated post-consumer streams, expanding usable feedstock pools.
Market Restraints
- Old-growth pulp price volatility:Kraft linerboard input costs swing with softwood chip availability, compressing margins for non-integrated converters.
- Collector base fragmentation:Forest Stewardship Council chain-of-custody certification requirements disqualify smaller collectors who lack fiber origin documentation.
- Plastic corrugated substitution:Reusable polypropylene containers in closed-loop automotive logistics displace single-trip OCC in select high-value circuits.
Strategic Opportunities
- Chemical depolymerization methods:Contamination-sensitive Electronics applications drive adoption of cleaner fiber recovery processes that command premium pricing.
- India BIS certification expansion:Tighter burst strength and ring crush test protocols raise barriers for uncertified imports, creating captive demand for domestic certified supply.
- Food & Beverage moisture resistance tier:Double-wall OCC with wax and polymer coatings captures deeper margin pools where spoilage risk justifies protective packaging investment.
Industry Challenges
- Fiber sorting technician shortage:Automated optical sorting systems require skilled operators who can calibrate near-infrared contamination detection, creating recruitment bottlenecks in municipal recovery facilities.
- Legacy baling equipment incompatibility:High-density OCC bales from modern single-stream facilities jam older mill pulping lines, forcing capital-intensive debaling system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Old Corrugated Containers (OCC) Market |
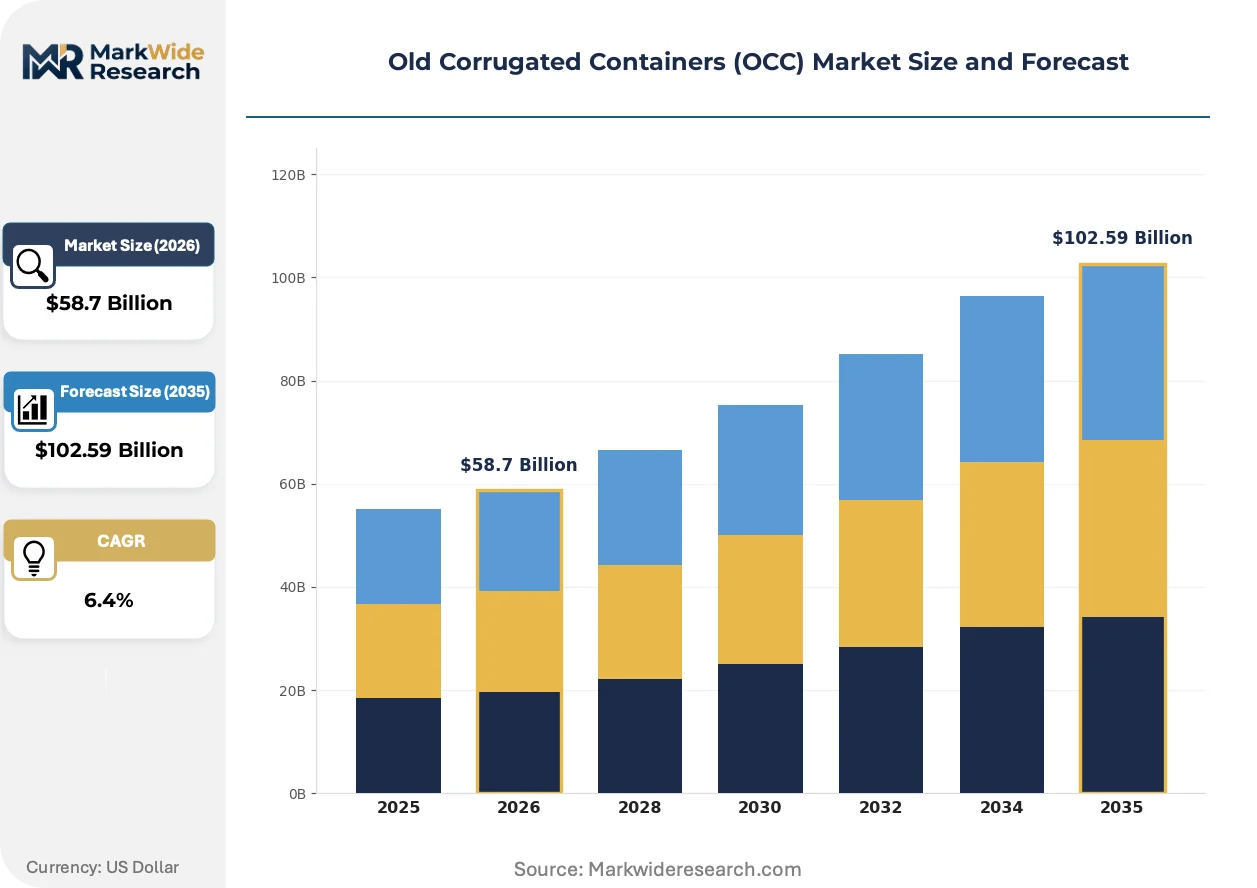
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Single Wall, Double Wall, Triple Wall, Reinforced End User: Retail, Food & Beverage, Electronics, Automotive Application: Packaging, Shipping, Storage, Waste Management Recycling Method: Mechanical, Chemical, Thermal, Pulping |
| Companies Covered | Smurfit Kappa Group, WestRock Company, International Paper, DS Smith Plc, Kruger Inc., Sonoco Products Company, Pratt Industries, Cleanaway Waste Management Limited, Royal Oak Recycling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Old Corrugated Containers (OCC) Market Evolving Landscape
Digital watermarking and blockchain traceability systems are rewiring how fiber provenance is verified across multi-tier supply chains.
Chemical depolymerization using enzymatic hydrolysis and solvent-based purification is supplanting conventional mechanical pulping in premium packaging segments. Electronics manufacturers with zero-defect surface requirements are adopting these methods fastest. The technology is enabling closed-loop fiber recovery from laminated and printed OCC streams previously routed to landfill.
REACH restrictions on persistent organic pollutants in recycled paperboard are tightening allowable thresholds for mineral oil saturated hydrocarbons. EU converters must now certify that OCC feedstock meets migration limits for food contact applications. Food & Beverage brands are responding by sourcing exclusively from mills with advanced deinking and thermal desorption capabilities.
Buyer consolidation among e-commerce platforms is compressing supplier negotiation cycles and unbundling after-sales technical support. Large fulfillment operators now demand direct mill relationships that bypass traditional distributor networks. This pattern concentrates most visibly in India's Western industrial corridor where Flipkart and Amazon have established captive packaging engineering teams.
Old Corrugated Containers (OCC) Market Segmentation

OCC market segmentation reveals how material specifications, end-use requirements, and recovery pathways create distinct commercial territories with divergent margin profiles and supply chain configurations.
Material Type:
Domestic consumption concentrates in single-wall grades for lightweight e-commerce parcels, while export demand from European converters drives double-wall and reinforced specifications.
- Single Wall:Comprises one fluted medium sandwiched between two linerboards, typically 150-200 PSI burst strength. Indian sortation hubs in Maharashtra absorb record volumes for lightweight parcel protection where shipping cost minimization overrides structural rigidity requirements.
- Double Wall:Two fluted layers bonded between three linerboards deliver 275-350 PSI burst strength with superior stackability. EU Packaging and Packaging Waste Regulation mandates force converters to secure long-term supply contracts for this grade, creating export-led demand concentration.
- Triple Wall:Heavy-duty construction with three fluted layers for industrial bulk shipments exceeding 400 PSI burst thresholds.
- Reinforced:Polymer or wax coatings added to base constructions for moisture resistance in challenging logistics environments.
Single Wall holds the largest share; momentum sits with Double Wall.
End User:
Cost tier differentiation separates premium moisture-resistant specifications from standard grades, with food safety compliance adding certification overhead.
- Food & Beverage:Moisture resistance requirements justify wax and polymer coating investments where spoilage risk commands protective packaging premiums. REACH restrictions on mineral oil saturated hydrocarbons force EU converters toward mills with advanced thermal desorption capabilities.
- Electronics:Zero-defect surface requirements drive chemical depolymerization adoption for contamination-sensitive fiber recovery, commanding steepest price premiums.
- Retail:Standard-grade OCC for display-ready packaging with moderate structural demands and shorter logistics cycles.
- Automotive:Closed-loop logistics circuits increasingly substitute reusable polypropylene containers for single-trip OCC in high-value parts movement.
Food & Beverage dominates volume; Electronics climbs the fastest.
Application:
Volume concentration in protective shipping functions contrasts with emerging waste management feedstock demand.
- Shipping:Protective transit packaging for e-commerce fulfillment absorbs the majority of double-wall and reinforced OCC output, with Amazon and Flipkart establishing direct mill relationships.
- Packaging:Primary and secondary containment for retail-ready goods, spanning standard to premium specification tiers.
- Storage:Long-duration warehousing applications requiring stack stability and moisture resistance.
- Waste Management:Feedstock recovery streams for recycled paperboard manufacturing, increasingly governed by BIS certification protocols in India.
Shipping commands the largest share; waste management feedstock applications gain share fastest.
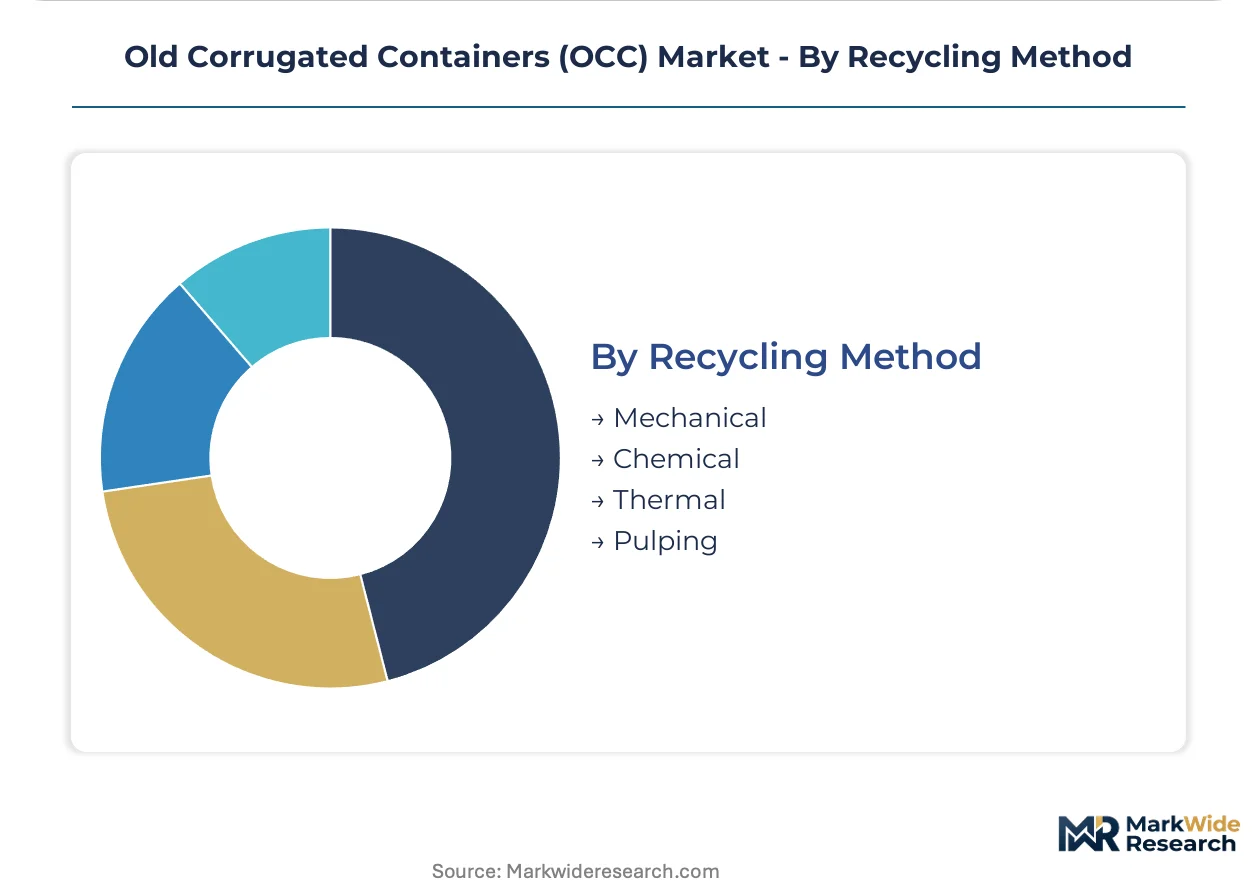
Recycling Method:
Supply concentration favors mechanical processing at scale, while chemical methods capture premium niches.
- Mechanical:Conventional pulping and screening dominates global volume, with thermomechanical expertise enabling higher-yield recovery from contaminated post-consumer streams.
- Chemical:Enzymatic hydrolysis and solvent-based purification enable closed-loop recovery from laminated and printed streams previously routed to landfill.
- Thermal:Thermal desorption systems remove mineral oil contaminants for food contact compliance under tightening EU migration limits.
- Pulping:Standard hydrapulper operations for uncontaminated post-consumer fiber with established deinking protocols.
Mechanical holds the largest share; chemical methods show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation mandates are redirecting import flows toward certified supply sources. India's BIS certification protocols are raising technical barriers for cross-border OCC trade. Collection infrastructure gaps in emerging economies are widening arbitrage windows for integrated mill operators.
United States
Municipal single-stream recycling programs generate high-density OCC bales for domestic mill consumption. EPA recovery targets shape collection economics across Midwest and Southeast population centers. Chicago and Atlanta sortation hubs feed integrated containerboard mills with post-consumer fiber streams.
Germany
REACH restrictions on mineral oil saturated hydrocarbons enforce migration limits for food contact paperboard. Dual sorting infrastructure separates commercial OCC from residential streams in the Rhine-Ruhr industrial corridor. Düsseldorf and Cologne logistics clusters demand premium double-wall specifications for automotive parts distribution.
India
Flipkart and Amazon fulfillment networks absorb reinforced OCC grades for protective e-commerce shipping. BIS burst strength and ring crush test protocols are tightening certification requirements for recycled paperboard imports. Maharashtra and Gujarat industrial corridors concentrate sortation hub capacity near Mumbai and Ahmedabad.
China
Import restrictions on contaminated post-consumer fiber are redirecting domestic collection investment toward coastal manufacturing zones. GB standards for recycled paperboard are aligning with EU technical specifications for export-oriented packaging. Yangtze River Delta mills are upgrading pulping lines to handle high-density bales from automated municipal facilities.
Brazil
E-commerce platform expansion is driving demand for single-wall OCC grades in São Paulo and Rio de Janeiro metropolitan distribution networks. National solid waste policy frameworks are formalizing extended producer responsibility for packaging recovery. Southeast industrial zones are developing integrated collection-to-mill supply chains for domestic containerboard production.
Old Corrugated Containers (OCC) Market Competitive Landscape
Player mix skews toward integrated containerboard producers with captive pulp capacity and certified fiber traceability systems. Tiered competitive structure separates multinational mill networks from regional collectors and specialized recycling operators. Strategic archetypes include integrated European producers with FSC chain-of-custody coverage, North American operators controlling municipal recycling stream access, and Asia-Pacific specialists serving e-commerce fulfillment demand. Dominant competitive moves center on backward integration into collection infrastructure and geographic expansion of certified mill capacity.
Within the integrated multinational tier, Smurfit Kappa Group and WestRock Company exemplify archetypes built on continental-scale mill networks and controlled fiber sourcing. International Paper occupies a position representing thermomechanical pulping specialization in the corrugated medium segment. These three entities anchor competitive dynamics around certification compliance, collection infrastructure control, and scale-driven cost positioning in their respective home markets.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| WestRock Company |
| International Paper |
| DS Smith Plc |
| Kruger Inc. |
| Sonoco Products Company |
| Pratt Industries |
| Cleanaway Waste Management Limited |
| Royal Oak Recycling |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with EU converters lock in both fiber access and price visibility through the analysis window, as Brussels-mandated recycled-content thresholds force converters to secure certified supply years ahead of delivery. These indexed agreements transfer old-growth pulp volatility risk from mills to brand owners while embedding FSC chain-of-custody premiums into base rates.
Pricing Analysis
Cost-plus contracts indexed to old-growth pulp futures dominate converter procurement, with base rates adjusted quarterly for kraft linerboard input swings. Price differentiation separates FSC-certified double-wall grades from uncertified single-wall commodity supply, while REACH-compliant thermal desorption capabilities command additional premiums for food-contact applications. Cost compression in standard-grade mechanical recycling is intensifying because high-density municipal bales require capital-intensive debaling retrofits. E-commerce fulfillment operators show highest price sensitivity, while Electronics manufacturers with zero-defect requirements absorb steepest premiums for chemical depolymerization fiber.
Supply Chain Analysis
Strait of Malacca transit underwrites Asia-Pacific fiber flows to EU mills, with congestion at Singapore and Port Klang creating periodic delivery windows that disrupt just-in-time converter operations. Supply concentrates in the United States, Germany, and India, with each market drawing from distinct collection infrastructure—municipal single-stream, dual commercial-residential sorting, and informal collector networks respectively. Raw material dependencies rest on post-consumer fiber bales, old-growth pulp for virgin linerboard blending, and wax or polymer coating inputs for moisture-resistant specifications. Tariff exposure on cross-border bale movements between India and Southeast Asian converters represents the dominant structural risk. Distribution runs through integrated mill-direct channels for large e-commerce platforms, with traditional distributor networks serving mid-tier converters.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against reusable polypropylene containers in closed-loop automotive logistics, where total-cost-of-ownership economics now favor plastic over single-trip OCC in high-value parts circuits.
For Market Incumbents: Consolidate collection infrastructure through backward integration into municipal single-stream contracts, securing captive fiber streams that smaller competitors cannot access. Acquire chemical depolymerization capabilities to serve Electronics manufacturers with zero-defect surface requirements, insulating margin pools from mechanical recycling commoditization. Prioritize FSC chain-of-custody certification investment to maintain EU market access as Brussels tightens traceability mandates. For New Entrants and Emerging Players: Lead with India BIS certification compliance as the primary market entry mechanism, targeting Maharashtra and Gujarat sortation hub supply gaps where Amazon and Flipkart procurement teams seek domestic alternatives to import-dependent sourcing. White-space opportunity sits with chemical depolymerization services for laminated and printed OCC streams previously routed to landfill, with Electronics applications offering fastest payback on capital deployment. For Investors and Strategic Acquirers: Regional collector networks with established municipal contracts and pending FSC certification represent the most defensible acquisition archetype, offering integrated mill operators immediate collection density without greenfield infrastructure risk. Long-term viability hinges on fiber traceability technology deployment across fragmented supplier bases. Watch for REACH enforcement actions on mineral oil saturated hydrocarbons as the inflection signal that separates compliant from non-compliant mill assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Municipal single-stream contracts in Chicago and Atlanta lock in high-density bale supply for integrated mills. |
| Chemical Depolymerization Capacity Buildout | Enzymatic hydrolysis systems capture Electronics segment premiums previously lost to landfill diversion. |
| FSC Chain-of-Custody Certification Program | EU Packaging and Packaging Waste Regulation mandates disqualify uncertified competitors from converter long-term contracts. |
| Direct Mill Relationships with E-commerce Platforms | Amazon and Flipkart procurement teams in Mumbai and Ahmedabad bypass distributor networks for volume pricing. |
| Thermal Desorption System Investment | Advanced deinking capabilities meet REACH migration limits for food-contact paperboard in European markets. |
Research Methodology
The analysis maps single-wall, double-wall, and reinforced material grades, each validated through mill procurement directors, municipal recycling facility operators, and e-commerce packaging engineers. Primary fieldwork with fiber sorting technicians and converter quality managers combined with secondary validation against EPA recovery databases, EU ECHA REACH filings, and India BIS certification registries. Bottom-up bale volume estimates from municipal recovery facilities triangulate against top-down containerboard production data from integrated mill disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models material type, end-user segment, recycling method, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from trend extrapolation of bale generation rates, pulp price index movements, and e-commerce fulfillment infrastructure deployment trajectories. Industry-specific inputs include Amazon and Flipkart sortation hub expansion schedules, EU recycled-content mandate phase-in timing, and India BIS test protocol revision calendars.
Underlying assumptions cover sustained e-commerce parcel volume growth, stable old-growth pulp price correlation, and incremental REACH enforcement stringency, with deviation risk concentrated in plastic corrugated substitution rates and chemical depolymerization technology cost curves. Practitioners should keep alternative scenarios live as EU packaging waste directive implementation timelines and India import certification protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Slide Top Tins Market
Containers
PET Hinged Containers Market
Containers
Screw Top Lids Market
Containers
Oblong Container Market
Containers
Canisters Market
Containers
Intermediate Bulk Container (IBC) Market
Containers
Reconditioned IBC Market
Containers
Aluminum Foil Containers Market
Containers
Vials Market
Containers
Flexible Water Tanks Market
Containers
Soup Containers Market
Containers
ISO Container Market
Containers
Tottle Containers Market
Containers
HDPE Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
Slotted Containers Market