
 Sanitary Cans Market | 2026-2036
Sanitary Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Cans Market Analytics
North American steel and aluminum can producers are expanding coating and lining capacity to serve pharmaceutical and food-grade applications. Ball Corporation leverages vertical integration from metal sourcing to decorated can production across multiple continents. Krones AG sustains technology leadership in high-speed filling and sealing lines for aseptic packaging environments. Syntegon Technology differentiates through barrier engineering and cleanroom-compatible handling systems.
Sanitary cans are hermetically sealed containers engineered with food-grade or medical-grade interior linings, typically manufactured through draw-and-iron or three-piece welding processes with epoxy or oleoresin coatings to prevent corrosion and contamination. Their primary purpose is to preserve sterility, extend shelf stability, and protect contents from microbial ingress across food, pharmaceutical, and chemical supply chains. Metal cans dominate volume due to established recycling infrastructure and oxygen barrier performance, while bio-based cans represent the fastest-growing structural category as brand owners face pressure to reduce petroleum-derived packaging. Plastic cans retain share in healthcare and household segments where weight reduction and shatter resistance outweigh thermal processing requirements.
FDA regulations governing food-contact substances under 21 CFR 175.300 directly determine interior coating chemistries permitted in US-sold sanitary cans. EMA and EU REACH restrictions on bisphenol-A and certain epoxy derivatives are accelerating migration toward polyester and acrylic lining systems across European supply chains. Stakeholders must monitor evolving substance authorization timelines and coordinate reformulation investments ahead of regulatory enforcement windows.
Market Dynamics
EU REACH restrictions on bisphenol-A and epoxy derivatives are forcing immediate reformulation of interior linings across European supply chains, while FDA 21 CFR 175.300 compliance costs simultaneously reshape North American coating specifications.
Growth Catalysts
- EMA migration pathways:Accelerated authorization timelines for polyester and acrylic lining systems are opening substitution opportunities for can producers serving pharmaceutical sterile-fill applications.
- Aseptic beverage processing:High-speed filling lines for shelf-stable dairy and plant-based drinks are expanding demand for hermetically sealed aluminum cans with oxygen barrier performance.
- Germany's industrial packaging corridor:Concentrated demand from chemical and food-processing clusters in North Rhine-Westphalia and Bavaria is anchoring regional capacity expansion.
Market Restraints
- Epoxy resin supply concentration:Reliance on Asian petrochemical feedstocks creates input cost volatility for traditional BPA-based coating systems still used in legacy can lines.
- Aluminum tariff exposure:Trade policy friction affecting primary metal sourcing elevates working capital requirements for three-piece can manufacturers.
- Thermal processing limitations:Plastic can structures face sterilization temperature ceilings that exclude retort applications above 121°C, constraining food-grade adoption.
Strategic Opportunities
- India PLI scheme for packaging:Production-linked incentives for food processing infrastructure are creating first-mover advantages for sanitary can suppliers establishing local coating facilities.
- Bio-based barrier convergence:Integration of polylactic acid structures with metalized films is unifying compostability claims with oxygen transmission performance in premium organic segments.
- Direct-to-brand e-commerce channels:Bypassing traditional distributor networks allows can decorators to capture value from craft beverage startups seeking short-run customized specifications.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 compliance for pharmaceutical-grade can handling systems extends facility qualification periods by 8-14 months.
- Legacy welding equipment incompatibility:Retrofitting draw-and-iron lines for laser-sealed seams requires capital outlays that mid-tier producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Cans Market |
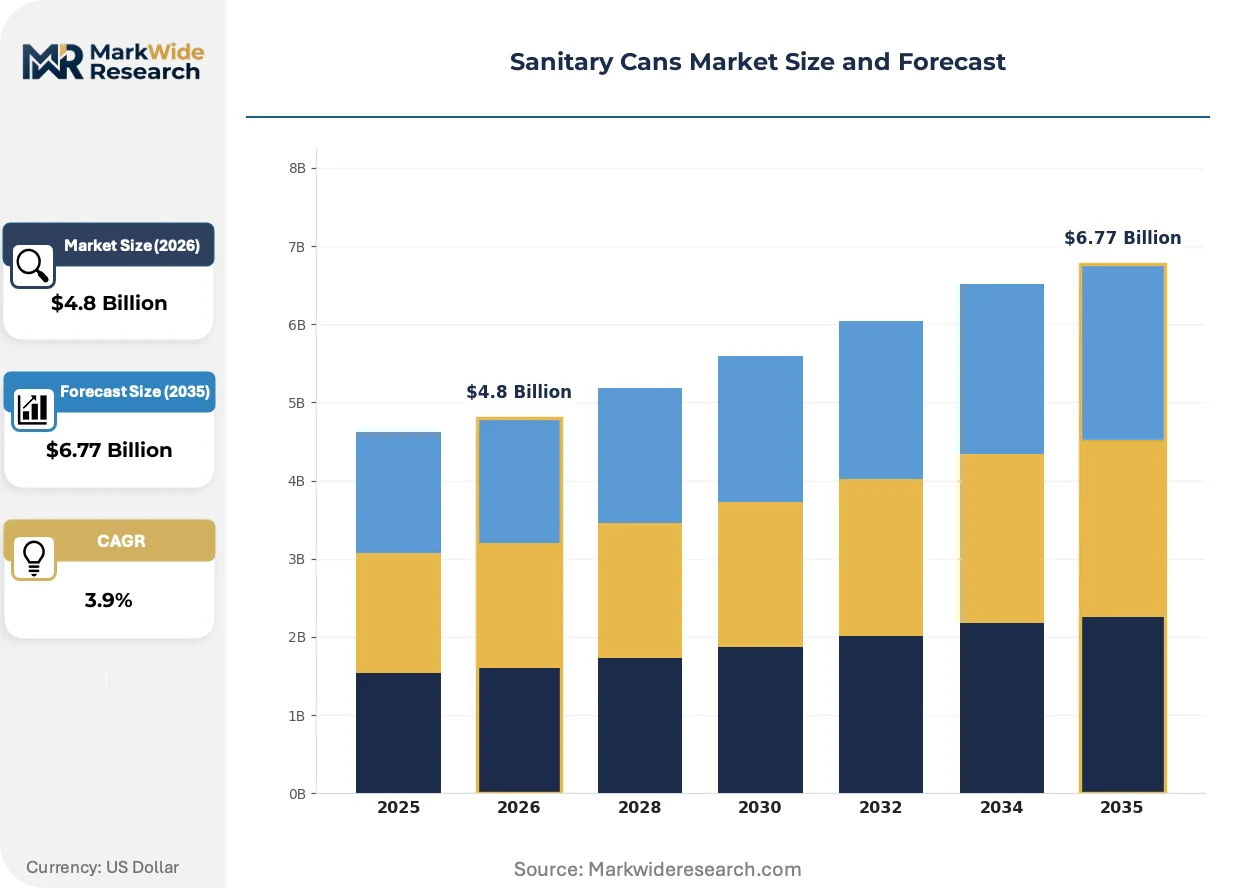
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Cans, Plastic Cans, Bio-based Cans, Composite Cans End User: Households, Healthcare Facilities, Educational Institutions, Industrial Sites Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Supermarkets, Direct Sales, Wholesale |
| Companies Covered | Freund Container & Supply, Ross Mixing Inc, Ball Corporation, Tetra Pak, Krones AG, Air Sea Container, Bennett Manufacturing Company, Syntegon Technology, Canfab Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Cans Market Evolving Landscape
Active coating chemistry migration and sterile-fill line automation are compressing the gap between food-grade and pharmaceutical-grade can specifications, forcing suppliers to serve dual-use certification requirements.
Digital printing on metal substrates is unifying short-run customization economics with aseptic barrier integrity. Craft beverage producers in Oregon and Washington are adopting UV-cured ink systems at 15-20% annual adoption velocity. This convergence is collapsing minimum order quantities from 100,000 units toward 10,000-unit batches without sacrificing FDA food-contact compliance.
FDA 21 CFR 175.300 amendments governing food-contact substances are narrowing approved epoxy chemistries for interior can coatings. Manufacturers serving US retail channels face reformulation deadlines that compress R&D cycles from 36 months toward 18 months. Acidic food categories—tomato products, citrus beverages, and pickled goods—experience the most acute substitution pressure as BPA-NI alternatives undergo accelerated extractables testing.
Hospital and clinic procurement of pre-sterilized single-use pharmaceutical cans is displacing traditional multi-dose glass vial systems in parenteral nutrition applications. Group purchasing organizations in Texas and Florida are consolidating supplier lists toward three preferred can vendors with validated gamma sterilization partnerships. This concentration is visible most acutely in oncology infusion protocols where contamination risk tolerance approaches zero.
Sanitary Cans Market Segmentation
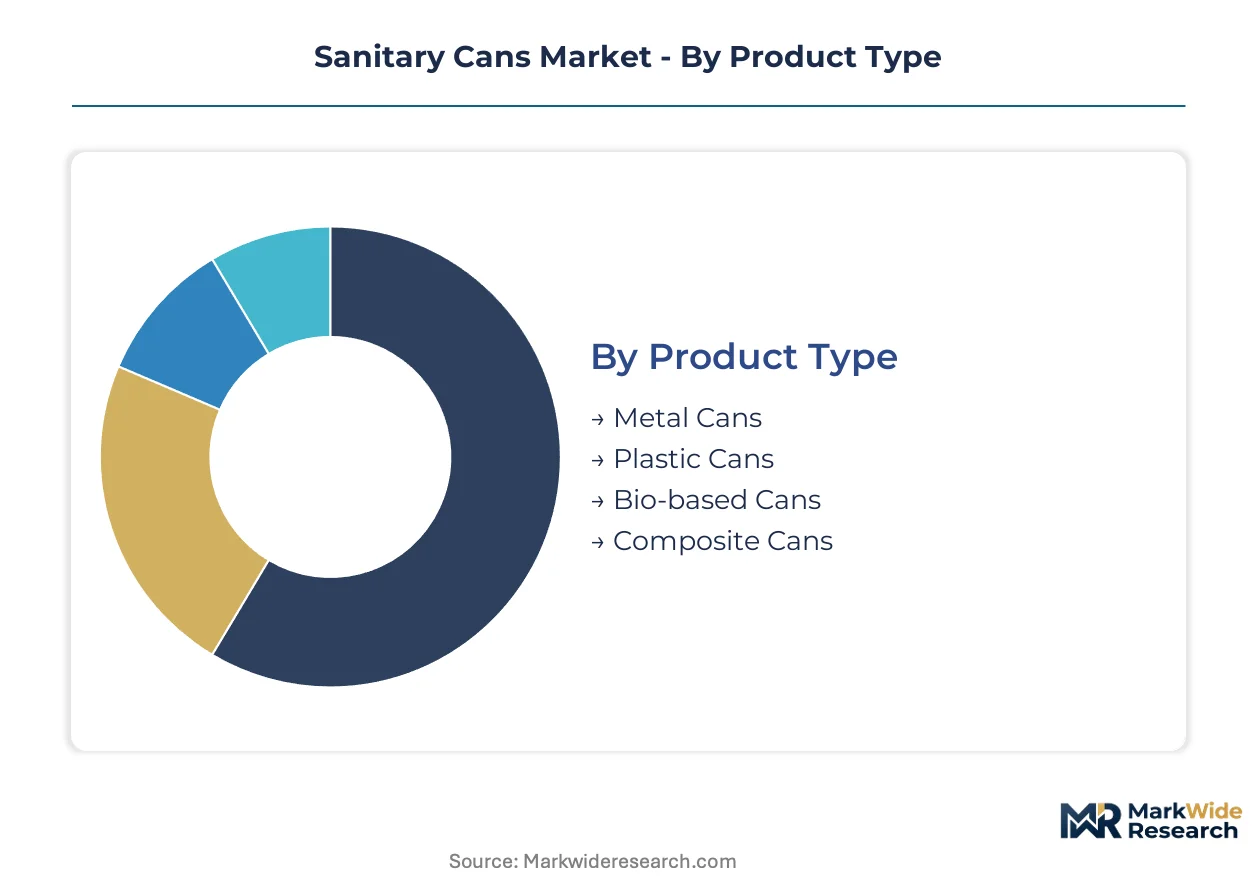
Sanitary can specifications diverge sharply across use environments, from sterile pharmaceutical filling to household chemical storage. Material selection, capacity scaling, and channel access each create distinct competitive arenas with separate certification requirements and margin structures.
Product Type:
Customization intensity spans from commodity metal stamping to engineered bio-based barriers requiring co-development with brand owners.
- Metal Cans:Draw-and-iron or three-piece welded construction with epoxy, polyester, or oleoresin interior linings delivers oxygen barrier performance and established recycling economics. Demand concentrates in Germany's North Rhine-Westphalia food-processing corridor, where retort sterilization compatibility and FDA 21 CFR 175.300 compliance anchor supplier selection.
- Plastic Cans:Injection-molded polypropylene or polyethylene structures with shatter resistance and weight advantages serve healthcare and household segments where thermal processing stays below 121°C. Texas and Florida hospital group purchasing organizations are consolidating procurement toward validated gamma-sterilization partnerships.
- Bio-based Cans:Polylactic acid structures with metalized film barriers unify compostability claims with functional performance in premium organic segments.
- Composite Cans:Paperboard-wound bodies with metal or polymer end closures balance structural rigidity with material reduction for dry goods applications.
Leading the category by volume: Metal Cans. Growing fastest: Bio-based Cans.
End User:
Volume concentration versus margin premium separates institutional procurement from fragmented consumer channels.
- Healthcare Facilities:Hospitals and clinics demand pre-sterilized single-use pharmaceutical cans with ISO 14644 cleanroom handling validation and zero contamination tolerance in oncology infusion protocols. EMA migration pathways for polyester and acrylic linings are accelerating substitution in European sterile-fill applications.
- Households:Consumer storage of cleaning chemicals and personal care products prioritizes shatter resistance and child-resistant closures over thermal processing capability.
- Educational Institutions:Laboratory and food-service procurement emphasizes chemical compatibility and portion control in medium-capacity formats.
- Industrial Sites:Chemical processing and bulk ingredient handling drives demand for large-capacity drums with UN-certified hazmat compliance.
Healthcare Facilities command the steepest expansion trajectory as parenteral nutrition protocols displace multi-dose glass vials.
Capacity:
Scale economies in tooling and shipping create distinct competitive moats across size classes.
- Small:Single-serve pharmaceutical vials and sample-size food portions require precision forming and extractables testing under FDA food-contact regulations.
- Medium:Standard retail formats for shelf-stable beverages and household chemicals dominate unit volume with established filling line compatibility.
- Large:Food-service institutional packs and industrial ingredient totes balance handling efficiency with warehouse footprint constraints.
- Extra Large:Bulk chemical and pharmaceutical ingredient storage demands specialized seam welding and pressure-rated closures with UN certification.
Medium capacity holds the largest installed base. Extra Large formats are climbing the fastest on chemical sector outsourcing trends.
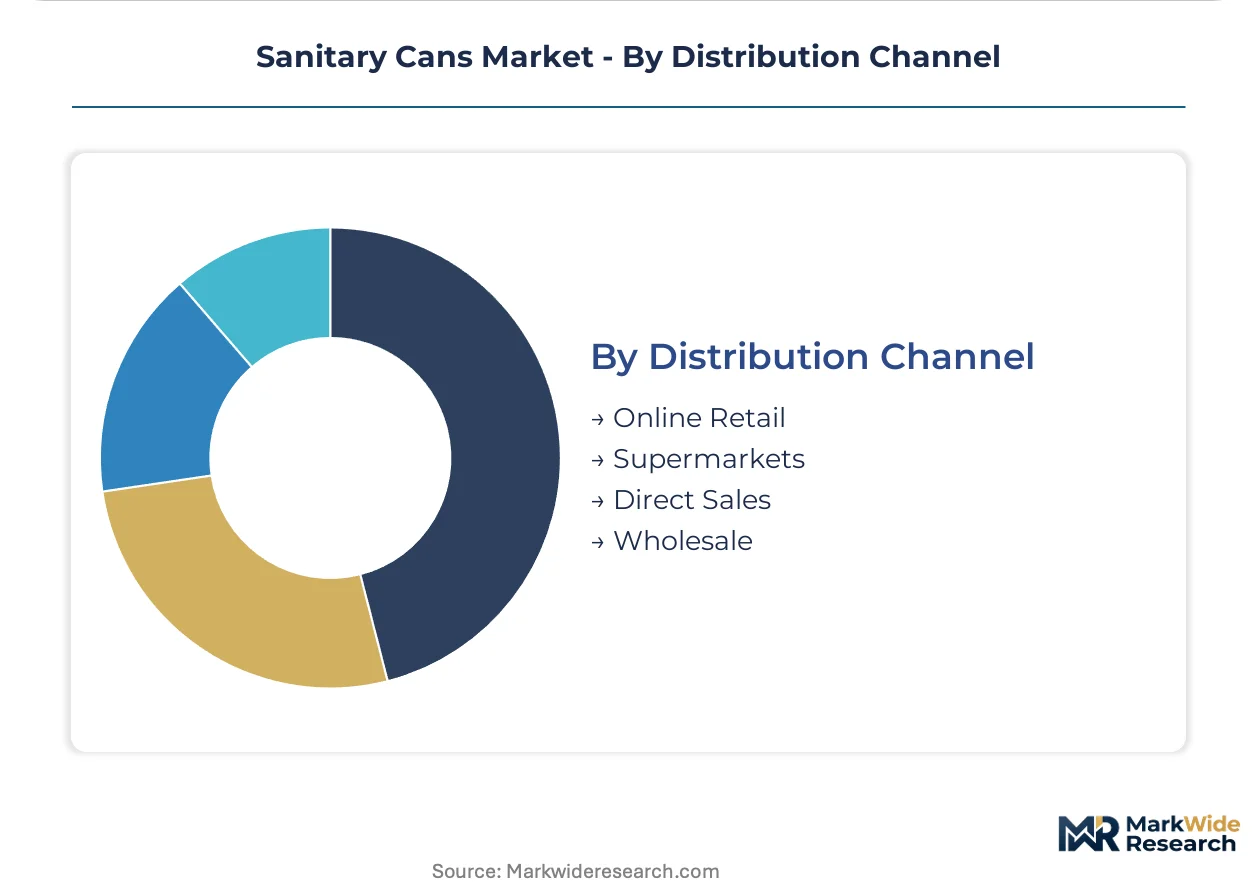
Distribution Channel:
Channel control determines pricing power and specification influence across the value chain.
- Online Retail:Direct-to-consumer fulfillment of specialized pharmaceutical and organic food cans bypasses traditional distributor markups but requires parcel-rated packaging durability.
- Supermarkets:Mass retail placement of shelf-stable food cans depends on slotting fees and promotional calendar alignment with seasonal harvest cycles.
- Direct Sales:Craft beverage producers in Oregon and Washington are adopting UV-cured digital printing for 10,000-unit short runs through direct decorator relationships.
- Wholesale:Industrial and healthcare institutional procurement flows through group purchasing organizations with consolidated supplier lists and multi-year contract structures.
Wholesale channels dominate transaction value. Direct Sales channels are gaining share fastest on craft beverage customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary aluminum smelting corridors in Canada and Norway supply feedstock for North American and European can manufacturing. Steel coil from Japanese and South Korean mills feeds Asian coating lines. Bauxite processing clusters in Australia and Guinea anchor raw-material security for beverage can sheet producers.
Germany
North Rhine-Westphalia's food-processing corridor demands retort-compatible metal cans with REACH-compliant polyester linings. ECHA restrictions on bisphenol-A derivatives are accelerating coating reformulation investments across Bavarian can plants. Munich-based filling equipment manufacturers are integrating cleanroom handling systems for pharmaceutical-grade applications.
United States
FDA 21 CFR 175.300 compliance deadlines are compressing R&D cycles for epoxy coating alternatives in acidic food categories. Oregon and Washington craft beverage producers are adopting UV-cured digital printing for short-run customized specifications. Texas hospital group purchasing organizations are consolidating procurement toward gamma-sterilization validated can suppliers.
India
FSSAI food-contact regulations and PLI scheme incentives for food processing infrastructure are creating first-mover advantages for coating facility investments. Maharashtra and Gujarat industrial corridors are attracting sanitary can suppliers establishing local production to serve domestic pharmaceutical packaging demand. CDSCO sterile-fill requirements are shaping validation protocols for parenteral nutrition can applications.
China
NMPA pharmaceutical packaging regulations and GB standards for food-contact materials are tightening interior lining specifications across Yangtze River Delta can plants. SAMR enforcement of dual carbon goals is pressuring energy-intensive coating operations toward renewable power sourcing. Pearl River Delta beverage producers are expanding aseptic aluminum can capacity for plant-based drink segments.
Japan
METI industrial standards and PMDA pharmaceutical packaging guidelines are converging food-grade and medical-grade can specifications. Kanto region can manufacturers are investing in laser-seamed welding technology to eliminate interior coating exposure points. Osaka-based suppliers are developing barrier-engineered structures for single-use oncology infusion protocols.
Sanitary Cans Market Competitive Landscape
Global majors compete with regional champions across coating technology and sterile-fill validation capabilities. The vendor base separates into three tiers: integrated metal producers with captive smelting and rolling capacity; specialized coating applicators serving third-party can makers; and equipment-technology hybrids supplying filling line integration. Strategic moves concentrate on backward integration into resin formulation and geographic expansion through distributor partnerships in emerging pharmaceutical markets.
Within the integrated metal tier, Ball Corporation and Krones AG exemplify scale-driven positioning across multiple continents. Syntegon Technology occupies a specialist position in barrier engineering and cleanroom-compatible handling systems. Among regional fabricators, Freund Container & Supply and Bennett Manufacturing Company represent mid-tier suppliers serving craft beverage and household chemical segments with customized short-run capabilities. These named entities anchor competitive archetypes rather than exhaust market coverage.
| Leading Market Players |
|---|
| Freund Container & Supply |
| Ross Mixing Inc |
| Ball Corporation |
| Tetra Pak |
| Krones AG |
| Air Sea Container |
| Bennett Manufacturing Company |
| Syntegon Technology |
| Canfab Packaging |
| Others |
Value Network & Pricing Analysis
Texas and Florida hospital group purchasing organizations concentrate procurement toward gamma-sterilization validated suppliers, anchoring a contract-based long-term offtake pricing model across pharmaceutical-grade sanitary can tiers.
Pricing Analysis
Warranty and validation bundling separates premium pharmaceutical-grade cans from unbundled commodity food-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR 175.300 certification grade and volume scale. Cost compression in standard-tier metal cans is intensifying because epoxy resin supply volatility feeds into coating reformulation expenses. Craft beverage startups in Oregon and Washington exhibit the highest price sensitivity, while oncology infusion protocol suppliers accept premium positioning.
Supply Chain Analysis
Epoxy and polyester resin supply rests on German and Japanese specialty chemical producers, with primary aluminum smelting anchored in Canada and Norway. Bauxite processing draws from Australian and Guinean extraction clusters, while steel coil feeds from Japanese and South Korean mills. Single-source vulnerability in BPA-NI coating alternatives creates qualification bottlenecks for European REACH compliance. Distribution runs through consolidated group purchasing organizations in healthcare and direct decorator relationships in craft beverage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom certification capacity constraints prop pricing power across pharmaceutical-grade tiers, as ISO 14644 validation timelines extend facility qualification by 8-14 months.
For Market Incumbents: To counter emerging bio-based barrier entrants, deepen backward integration into resin formulation and expand coating capacity in Germany's North Rhine-Westphalia corridor. Lock in multi-year gamma-sterilization partnerships with Texas and Florida hospital GPOs to secure volume commitments ahead of qualification bottlenecks. For New Entrants and Emerging Players: Laser-seamed welding technology offers a technology-first wedge into pharmaceutical sterile-fill applications where legacy equipment incompatibility blocks mid-tier incumbents. Target India's Maharashtra and Gujarat industrial corridors under PLI scheme incentives, partnering with CDSCO-registered facilities for parenteral nutrition can validation. For Investors and Strategic Acquirers: The window for entry favors coating applicators with REACH-compliant polyester and acrylic lining capabilities. Long-term viability centers on suppliers bridging food-grade and pharmaceutical-grade certification requirements. Watch EMA migration pathway acceleration for polyester lining authorizations as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captures margin from epoxy and polyester supply volatility while securing REACH-compliant coating chemistries. |
| Cleanroom Certification Investment | ISO 14644 validation opens pharmaceutical sterile-fill contracts with Texas and Florida hospital GPOs. |
| Geographic Expansion in India | PLI scheme incentives in Maharashtra and Gujarat corridors create first-mover advantages for coating facilities. |
| Digital Printing Capability Addition | UV-cured ink systems serve Oregon and Washington craft beverage demand for 10,000-unit short runs. |
| Gamma-Sterilization Partnership | Validated partnerships with oncology infusion protocol suppliers displace multi-dose glass vial systems. |
Research Methodology
Independent corroboration across coating applicator technical directors, hospital GPO procurement managers, and filling equipment engineers underwrites the qualitative findings. Primary fieldwork with FDA regulatory consultants and EMA submission specialists combined with secondary validation from FDA 21 CFR filings, ECHA restriction updates, and customs trade data. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Comparable historical periods spanning regulatory transition windows informed projection anchor points across the analysis window. Segmentation dimensions modeled include material type, end-use vertical, capacity tier, and distribution channel complexity. CAGRs derived from weighted average of capacity expansion timelines and substitution elasticity for bio-based alternatives. Forecast inputs incorporated REACH authorization timelines and PLI scheme incentive disbursement patterns.
Several conditions sit outside the modeled scope, including unannounced FDA coating chemistry amendments and abrupt aluminum tariff reconfigurations. Forecasts reflect documented assumptions regarding EMA migration pathway acceleration and cleanroom certification throughput rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Pocket Containers Market
Containers
Wet Wipes Canister Market
Containers
North America Plastic Bottles and Containers Market
Containers
HDPE Containers Market
Containers
Die Cut Display Container Market
Containers
Oblong Container Market
Containers
Composite Ibcs System Market
Containers
Shipping Container Liners Market
Containers
Tottle Containers Market
Containers
Container Fixed Fittings Market
Containers
Clear Hinged Container Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
PUR Containers Packaging Market
Containers
In-Mold Labelled Containers Market
Containers
Cylindrical Cans Market
Containers
Bulk Container Packaging Market