
 Trigger Sprayer Market | 2026-2036
Trigger Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Trigger Sprayer Market Outlook
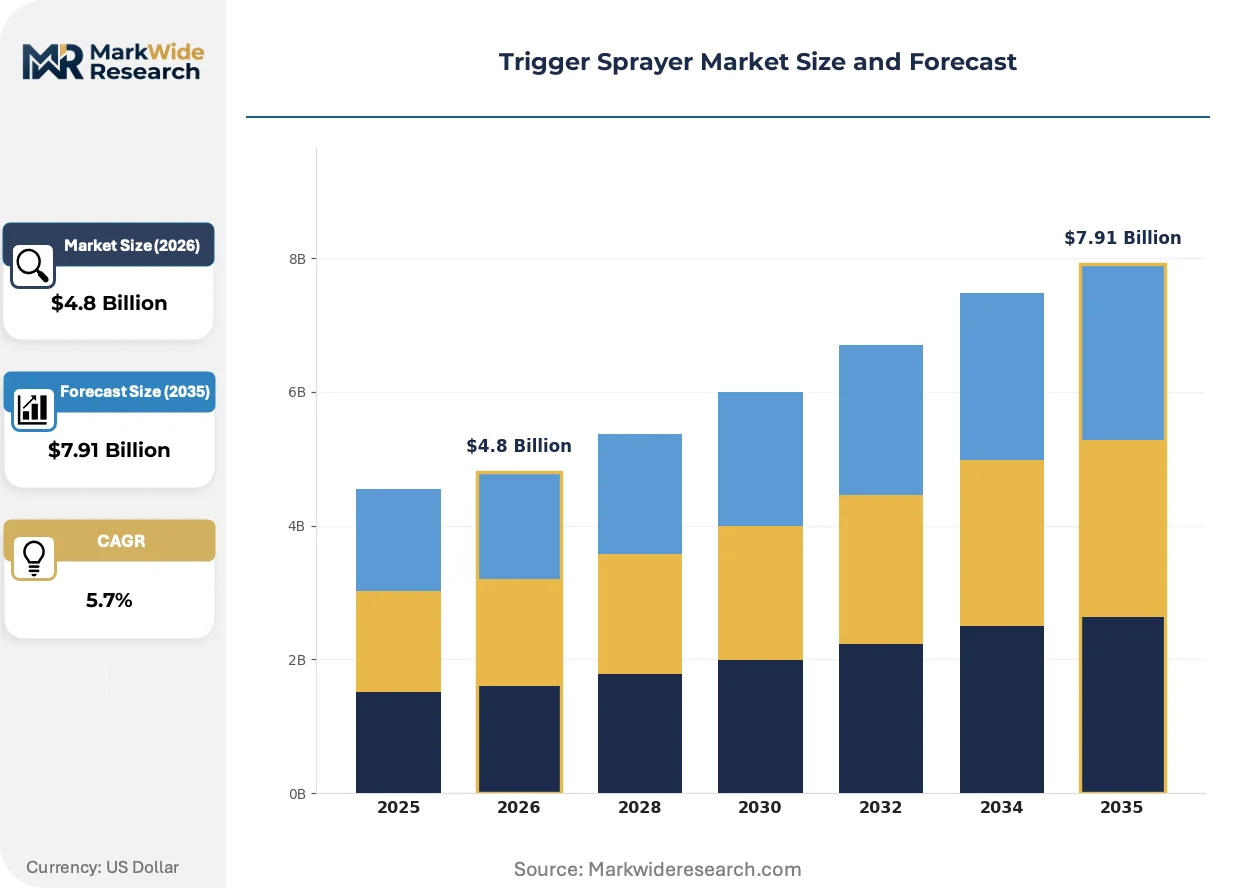
Refill subscription services for household cleaning concentrates is shifting how trigger sprayer value gets captured, bundling hardware with recurring chemical replenishment rather than one-time bottle sales. Berry Global Inc. leverages its blow-molding scale to anchor private-label programs for major retailers. Silgan Dispensing Systems sustains technology leadership through precision-engineered closure systems that reduce trigger fatigue. AptarGroup, Inc. differentiates via advanced spray-pattern modulation for premium personal care extensions.
A trigger sprayer is a manually actuated liquid dispensing device comprising a piston pump, trigger lever, dip tube, and adjustable nozzle, typically constructed from polypropylene and polyethylene components with stainless steel springs, designed to deliver metered doses of cleaning solutions, personal care formulations, or industrial chemicals through controlled spray patterns. Mist spray mechanisms dominate household applications where fine particle distribution improves surface coverage, while continuous spray formats represent the fastest-growing structural segment as consumers adopt aerosol-alternative dispensing for hair care and sun care products. Plastic material configurations occupy the largest volume share due to cost efficiency and chemical resistance, though aluminum variants command premium positioning in sustainable packaging portfolios.
The EPA regulates antimicrobial claims on cleaning products dispensed through trigger sprayers, compelling manufacturers to validate chemical compatibility and labeling accuracy. FDA oversight applies to trigger sprayers used in healthcare sanitization applications, requiring material compliance with device safety standards. California's Proposition 65 disclosure mandates further shape formulation transparency and packaging material selection for products entering that state. Stakeholders must monitor evolving state-level chemical restriction frameworks and assess whether mechanical redesign or material substitution offers the more defensible compliance pathway.
Market Dynamics
Refill subscription models are restructuring value capture in the Trigger Sprayer Market, bundling durable dispensing hardware with recurring chemical replenishment rather than transactional bottle sales. This shift concentrates margin in recurring revenue streams while commoditizing the physical sprayer unit.
Growth Catalysts
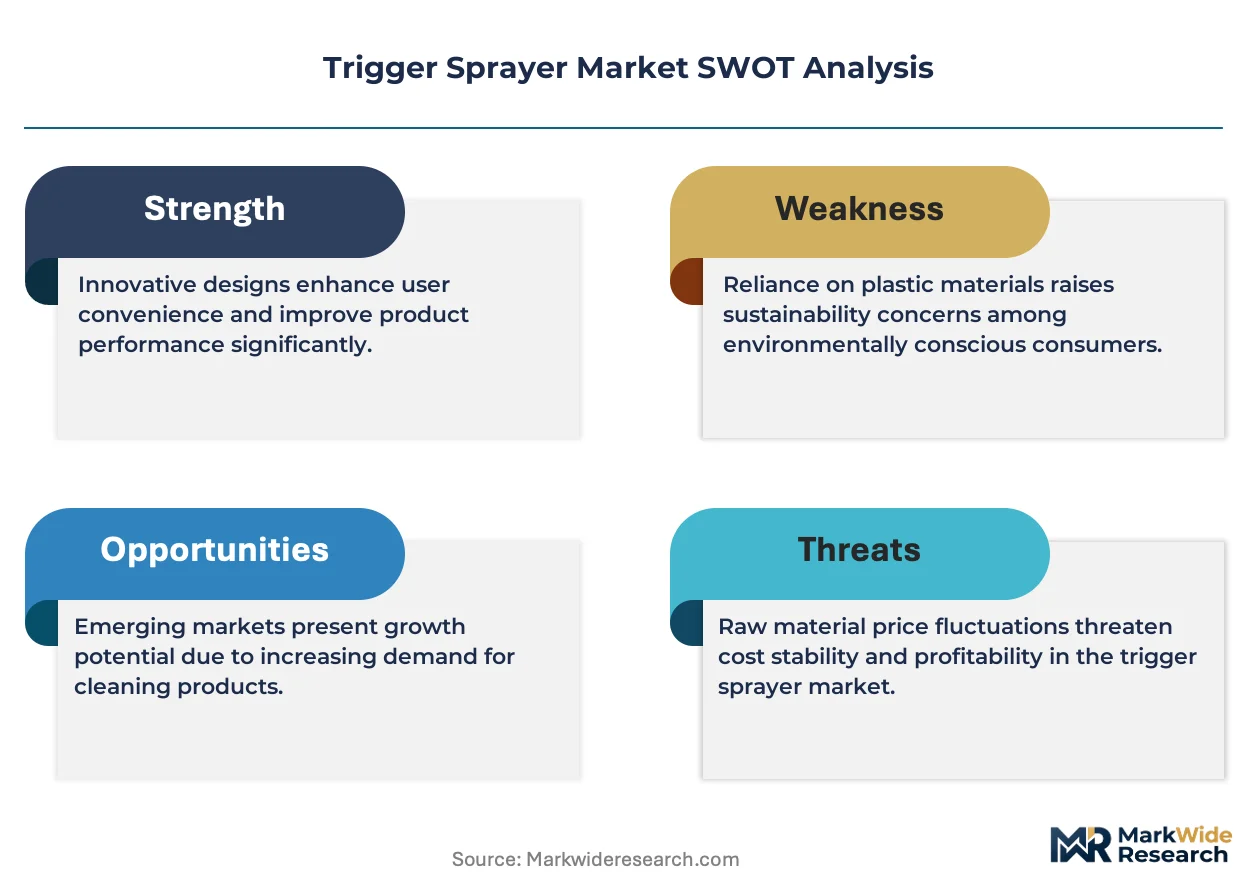
- EU REACH chemical compatibility mandates:European supply chains are accelerating material validation for polypropylene and polyethylene formulations, expanding certified component demand across home care and industrial cleaning applications.
- Continuous spray mechanism adoption:Hair care and sun care brands are replacing aerosol alternatives with pump-driven continuous formats, opening new end-use verticals beyond traditional household cleaning.
- Private-label contract manufacturing scale:United States retailers are consolidating sprayer procurement through dedicated blow-molding partnerships, reducing unit costs for home care brands.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, compressing margin predictability for injection-molded sprayer components.
- Single-source spring supply concentration:Precision stainless steel spring fabrication for trigger mechanisms concentrates in East Asian metalworking clusters, exposing buyers to geographic supply risk.
- California Proposition 65 disclosure friction:Chemical transparency mandates for products entering California create compliance overhead that discourages small-batch sprayer customization.
Strategic Opportunities
- Aluminum variant premium positioning:Sustainable packaging portfolios in Western Europe are commanding price premiums for metal-bodied sprayers as plastic-alternative credentials.
- Healthcare sanitization compliance:FDA device safety standards for hospital-grade sprayers create a defensible certification moat for manufacturers investing in material traceability systems.
- Precision-engineered closure integration:Advanced spray-pattern modulation technology from adjacent personal care dispensing is migrating into industrial chemical applications.
Industry Challenges
- Antimicrobial claim validation timelines:EPA review cycles for cleaning product efficacy testing extend go-to-market schedules for sprayer-plus-formulation bundles.
- Cross-functional material science talent scarcity:Formulation chemists with simultaneous expertise in polymer compatibility and mechanical engineering command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trigger Sprayer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Spray, Stream Spray, Mist Spray, Foam Spray Material: Plastic, Stainless Steel, Glass, Aluminum End User: Household, Industrial, Healthcare, Automotive Capacity: 30 ml, 50 ml, 100 ml, 500 ml |
| Companies Covered | Berry Global Inc., Silgan Dispensing Systems, AptarGroup, Inc., AFA Dispensing Group B.V., Guala Dispensing S.p.A., Frapak Packaging, Tolco Corporation, CL Smith Company, Mitani Valve Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trigger Sprayer Market Strategic Shifts
Mechanical dispensing architectures are fragmenting as aerosol-alternative formats gain technical parity. Three converging developments are reshaping how liquid products reach end-users.
Continuous spray pump technology is decentralizing aerosol-dependent dispensing across personal care categories. The mechanism replaces hydrocarbon propellants with mechanical pressure buildup, delivering fine particle distribution without volatile organic compound emissions. Sun care and hair styling brands in North America and Western Europe are adopting this format fastest. The technology is decentralizing category boundaries that historically separated pump sprayers from pressurized aerosol cans.
REACH substance restriction expansions are forcing material substitutions across European supply chains. ECHA evaluations of endocrine-disrupting candidates now cover plasticizer compounds common in flexible dip tubes. Manufacturers are validating bio-based polypropylene alternatives and eliminating phthalate-adjuvant formulations. Personal care extensions with premium positioning face the steepest retesting burdens.
Concentrate-to-dilute refill systems are compressing sprayer replacement cycles. Household cleaning brands are designing durable trigger hardware for multi-year use with interchangeable chemical cartridges. This pattern concentrates in direct-to-consumer subscription channels and bulk retail formats. German and French markets show the highest adoption density for refill-station retail infrastructure.
Trigger Sprayer Market Segmentation
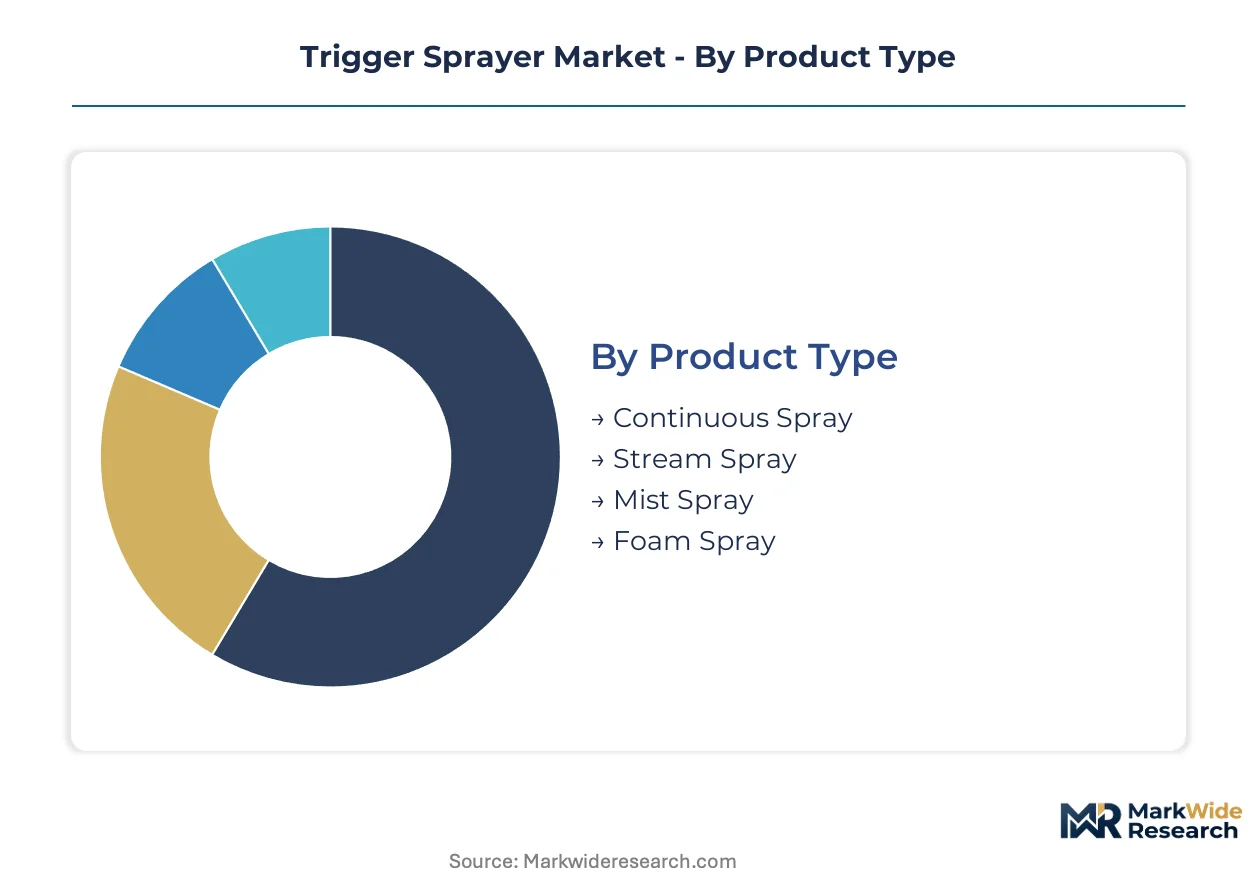
Trigger sprayer segmentation reveals divergent engineering priorities across dispensing architectures. Material selection and capacity specifications reshape procurement patterns for household versus industrial buyers.
Product Type:
Volume concentration favors established formats, while premium positioning attaches to emerging mechanical architectures.
- Mist Spray:Delivers fine particle distribution through precision-engineered nozzles with adjustable cone patterns. Household surface cleaning in the United States drives procurement scale as consumers prioritize even coverage on countertops and fixtures.
- Continuous Spray:Mechanically pressurized pump systems generate sustained aerosol-alternative output without hydrocarbon propellants. Sun care and hair styling brands in France and Germany are adopting this format fastest as regulatory pressure on volatile organic compounds intensifies.
- Stream Spray:Concentrated liquid projection for targeted application with minimal atomization. Industrial chemical dispensing and automotive detailing represent primary uptake channels.
- Foam Spray:Air-entrainment mechanisms convert liquid into clinging foam for extended surface contact. Bathroom and kitchen cleaning formulations deploy this architecture most frequently.
Mature deployment sits with Mist Spray. Newer deployment is concentrated in Continuous Spray.
Material:
Cost efficiency dominates procurement for high-volume applications, while sustainability credentials command price premiums in Western European markets.
- Plastic:Polypropylene and polyethylene configurations deliver chemical resistance at unit costs below metal alternatives. Home care brands across the United States specify plastic for disposable-format household cleaners where replacement cycles compress hardware lifespans.
- Aluminum:Metal-bodied construction targets refill-system durability and circular-economy packaging mandates. German retailers are commanding price premiums for aluminum variants in sustainable private-label portfolios.
- Stainless Steel:Precision spring mechanisms and corrosion-resistant hardware for industrial chemical compatibility. Foodservice and healthcare sanitization applications specify this material for repeated sterilization cycles.
- Glass:Inert containment for essential oil formulations and premium personal care extensions. Aromatherapy and natural cleaning concentrate brands in France favor glass dip tubes and reservoirs.
Plastic captures the highest shipment volumes. Aluminum is climbing the fastest on sustainability-driven substitution.
End User:
Application environment dictates regulatory compliance burden and mechanical durability specifications.
- Household:Consumer-grade actuation force and ergonomic trigger geometry for repetitive cleaning tasks. United States retailers are consolidating procurement through dedicated contract manufacturing partnerships.
- Industrial:Chemical-resistant seals and extended dip tubes for concentrated solvent dispensing. Manufacturing facility maintenance and commercial cleaning operations specify industrial-grade hardware.
- Healthcare:FDA device safety compliance for hospital-grade sanitization sprayers. Material traceability systems and sterilization validation create certification moats for qualified suppliers.
- Automotive:Solvent compatibility for degreasing compounds and tire dressing formulations. Professional detailing shops and consumer car care represent distinct specification tiers.
Household generates the largest absolute demand. Healthcare is expanding most quickly on post-pandemic sanitization protocols.
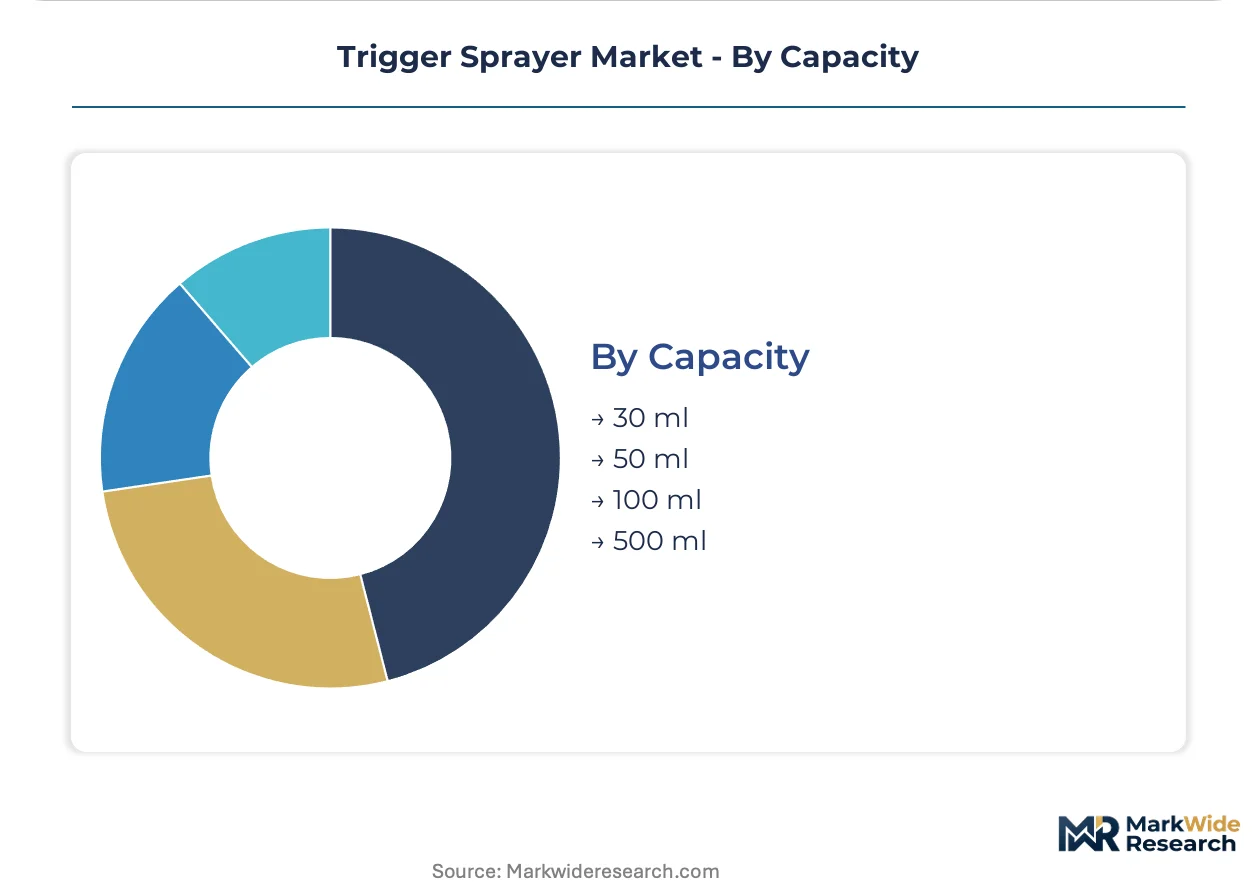
Capacity:
Usage frequency and portability requirements segment container sizing across retail and commercial channels.
- 500 ml:Standard-format household cleaners for kitchen and bathroom applications. United States mass retailers specify this capacity for mainstream private-label programs.
- 100 ml:Travel-size personal care and trial-format cleaning concentrates. Airline-compliant sizing drives adoption in sun care and hand sanitizer categories.
- 50 ml:Precision dispensing for essential oils and concentrated active formulations. Aromatherapy and natural cleaning brands favor this capacity for premium positioning.
- 30 ml:Sample formats and single-use medical applications. Pharmaceutical and diagnostic reagent dispensing specify miniaturized trigger mechanisms.
500 ml anchors mainstream retail. 100 ml is gaining share fastest on travel-format personal care expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian metalworking clusters and North American blow-molding corridors, while consumption splits between Western European refill-system adoption and United States mass retail consolidation.
United States
Private-label contract manufacturing scales through dedicated blow-molding partnerships as retailers consolidate sprayer procurement. EPA antimicrobial claim validation extends go-to-market timelines for cleaning product bundles. Chicago-area packaging corridors anchor production capacity for home care brands.
Germany
Retail refill-station infrastructure commands premium positioning for aluminum-bodied sustainable variants. ECHA evaluations of endocrine-disrupting candidates force bio-based polypropylene validation across flexible dip tube supply chains. Cologne-Düsseldorf industrial zones concentrate precision spring fabrication for trigger mechanisms.
France
Sun care and hair styling brands adopt continuous spray formats fastest as volatile organic compound regulations intensify. ANSM oversight of personal care dispensing devices shapes material traceability requirements. Lyon-based aromatherapy clusters favor glass reservoir configurations for essential oil formulations.
China
Stainless steel spring fabrication concentrates in Zhejiang and Jiangsu metalworking clusters, exposing buyers to geographic supply concentration. MIIT standards for plastic packaging recyclability reshape polypropylene specification sheets. Shanghai-Pudong logistics hubs coordinate export consolidation for North American retail programs.
India
BIS certification mandates for food-contact plastics extend to trigger sprayers used in kitchen cleaning concentrates. PLI scheme incentives for packaging machinery attract blow-molding investment into Gujarat industrial corridors. Mumbai-Pune manufacturing belts scale household-grade plastic component output for domestic FMCG brands.
Trigger Sprayer Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Trigger Sprayer Market. Blow-molding specialists with captive resin processing anchor volume tiers, while precision-engineering houses capture premium positioning through closure-system differentiation. Three archetypes dominate: integrated resin-to-sprayer manufacturers, specialized dispensing technology licensors, and private-label contract fabricators. Competitive moves concentrate in backward integration into resin compounding and geographic expansion through distributor network acquisition.
Among North American integrated packaging conglomerates, Berry Global Inc. exemplifies scale-driven private-label anchoring. Silgan Dispensing Systems and AptarGroup, Inc. represent the precision-engineering tier with technology licensing positions in spray-pattern modulation. These three occupy distinct competitive spaces without direct product overlap.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Silgan Dispensing Systems |
| AptarGroup, Inc. |
| AFA Dispensing Group B.V. |
| Guala Dispensing S.p.A. |
| Frapak Packaging |
| Tolco Corporation |
| CL Smith Company |
| Mitani Valve Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
United States mass retailers consolidating procurement through dedicated blow-molding partnerships command volume-tier pricing leverage, compressing margin capture for sprayer manufacturers while rewarding scale-efficient producers with multi-year contract stability.
Pricing Analysis
Margin tightening in the standard plastic tier reflects polypropylene resin volatility tethered to crude oil benchmarks. Three-tier pricing structure across premium aluminum, standard polypropylene, and economy recycled-content levels separates sustainability-certified variants from commodity disposable formats. Pricing pressure intensifies as private-label contract manufacturing scales concentrate procurement power among fewer retail buyers. Household cleaning brands exhibit highest price sensitivity, while healthcare sanitization applications tolerate premium positioning for FDA-compliant material traceability.
Supply Chain Analysis
Freight cost exposure from Zhejiang and Jiangsu metalworking clusters to North American retail distribution centers elevates landed costs for precision stainless steel spring components. Raw material dependencies rest on polypropylene resin from Gulf Coast petrochemical corridors, polyethylene formulations from Middle Eastern feedstock, and stainless steel spring wire from East Asian fabrication networks. Single-source concentration in Zhejiang spring manufacturing creates geographic supply vulnerability. Distribution runs through Shanghai-Pudong consolidation hubs coordinating containerized export to United States retail fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Asian metalworking cluster concentration for precision spring fabrication props pricing power among qualified suppliers, constraining capacity expansion for new entrants lacking established foundry relationships.
For Market Incumbents: Anchor defensible positioning through backward integration into polypropylene compounding and captive spring fabrication in Cologne-Düsseldorf industrial zones. Consolidate channel control via exclusive blow-molding partnerships with top-three United States retailers. Certification investment in FDA device safety standards creates switching-cost barriers against emerging Asian competitors. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route, bypassing consolidated retail procurement gatekeepers. Target aluminum-bodied sustainable variants for German refill-station infrastructure where premium positioning tolerates higher unit costs. Precision-engineered closure technology licensing from adjacent personal care dispensing segments provides differentiated go-to-market positioning. For Investors and Strategic Acquirers: The window for entry favors precision-engineering specialists with spray-pattern modulation IP and established healthcare compliance records. Long-term viability hinges on material science capabilities spanning polymer compatibility and mechanical engineering. Watch ECHA substance restriction expansions as inflection indicator for bio-based polypropylene substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply secures margin stability against petrochemical volatility. |
| Healthcare Sanitization Certification Investment | FDA device safety compliance creates defensible moat in hospital-grade applications. |
| Continuous Spray Technology Licensing | Aerosol-alternative formats open sun care and hair styling verticals beyond household cleaning. |
| Aluminum Variant Manufacturing Scale-Up | Sustainable packaging mandates in Western Europe command price premiums for metal alternatives. |
| Direct-to-Consumer Refill Subscription Launch | Recurring revenue capture shifts value from transactional hardware to chemical replenishment. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with blow-molding plant managers, retail category buyers, formulation chemists, and precision spring fabrication engineers. Bottom-up sprayer shipment tallies triangulated against top-down household cleaning product consumption estimates from EPA antimicrobial registration databases and EU REACH substance volume declarations.
Segment-level granularity modeled product type, material composition, end-use vertical, and capacity tier across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating petrochemical input cost trajectories and regulatory compliance burden indices. Forecast inputs included ECHA endocrine-disrupting candidate evaluation timelines and United States private-label contract manufacturing expansion patterns.
The model holds under stable resin pricing and continued REACH substance restriction enforcement; deviation in crude oil volatility or accelerated aluminum substitution mandates would shift volume-value trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Slide Top Tins Market
Containers
PS Containers Market
Containers
Collapsible Food Packaging Containers Market
Containers
Chest-Style Insulated Containers Market
Containers
Algeria Container Glass Market
Containers
Shipping Container Liners Market
Containers
Oblong Container Market
Containers
Flexible Water Tanks Market
Containers
ISO Ocean Containers Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
EMEA Container Technology Market
Containers
PET Hinged Containers Market
Containers
Essential Oil Containers Market
Containers
Tottle Containers Market
Containers
Composite Ibcs System Market
Containers
High Density Polyethylene (HDPE) Bottles Market