
 Wire Containers Market | 2026-2036
Wire Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Containers Market Analytics
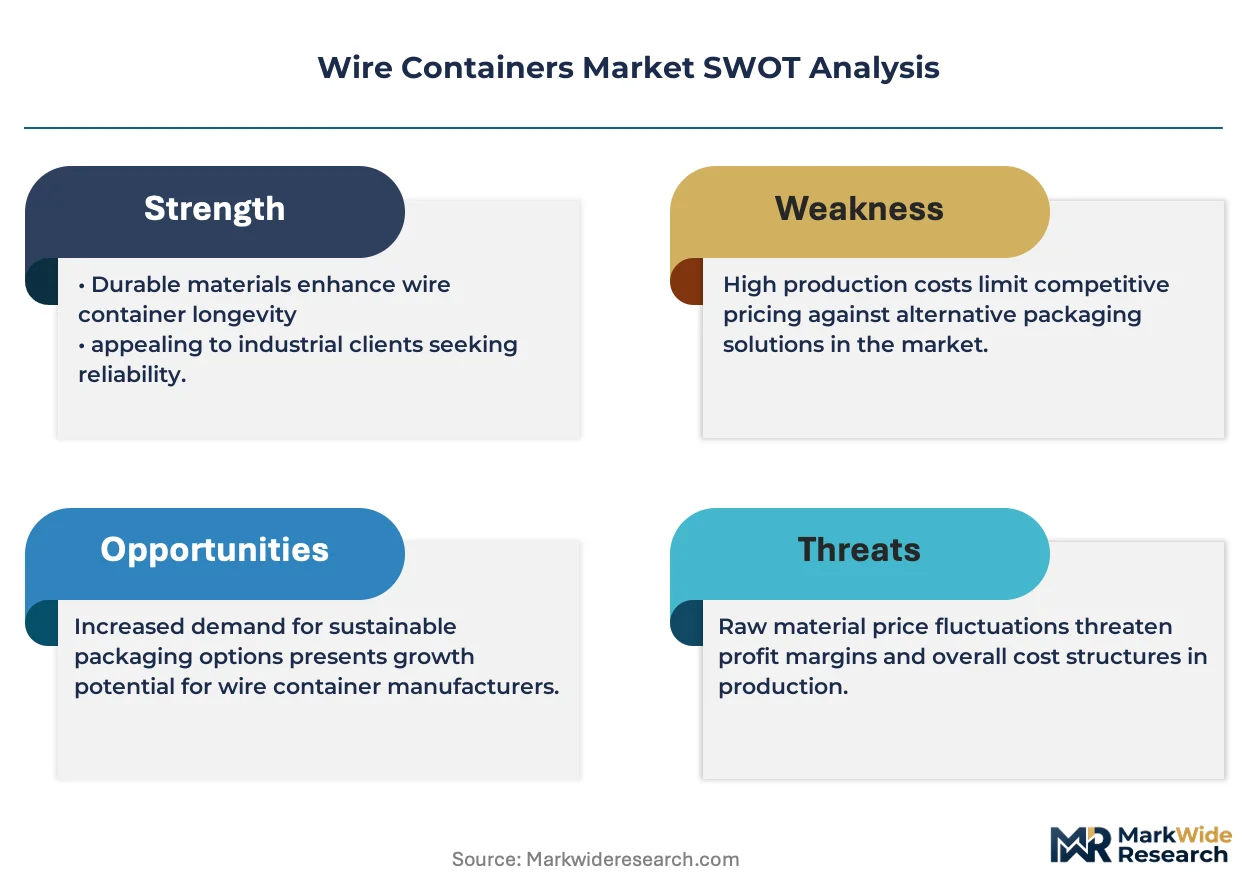
Automation-compatible mesh geometry is narrowing the design gap between standard wire baskets and engineered storage systems. Vestil Manufacturing Corp. leverages its North American fabrication network to serve regional distribution hubs. KW Materials Handling anchors its position through specialized wire trolleys for automotive assembly lines. Massey Rack competes on custom capacity configurations for cold-storage logistics.
Wire containers are fabricated metal enclosures constructed from welded wire mesh, typically with base dimensions ranging from 20 inches to 48 inches and load ratings from 500 to 4,000 pounds, designed for unitized material handling, inventory storage, and transport pooling across supply chains. Stainless steel variants command premium positioning due to corrosion resistance requirements in food processing environments governed by FDA and EFSA hygiene protocols. Carbon steel wire cages dominate manufacturing end-use where cost efficiency outweighs chemical exposure risks. Small and medium capacity segments lead volume while custom configurations capture disproportionate margin pools in pharmaceutical and aerospace verticals.
OSHA walking-working surface standards, ISO 9001 quality management protocols, and EU machinery safety directives collectively mandate load-testing documentation and traceable weld certification for commercial wire container deployments. The EPA's emerging focus on steel recycling content reporting will reshape raw material sourcing decisions for galvanized and carbon steel product lines. Stakeholders must evaluate mesh gauge standardization against robotic gripping interfaces as warehouse automation penetrates mid-tier logistics operations.
Market Dynamics
Automation penetration in warehouse fulfillment is compressing design cycles for wire containers, forcing mesh geometry standardization to align with robotic gripping interfaces and AGV compatibility requirements.
Growth Catalysts
- OSHA Walking-Working Surface Standards:Mandated load-testing documentation for material handling equipment drives replacement demand across US distribution networks. Facilities must upgrade legacy cages to certified welded units.
- E-commerce Fulfillment Density:Amazon, Walmart, and regional 3PL operators in Germany and the United States deploy collapsible wire containers for returns processing and seasonal inventory surges.
- Stainless Steel Hygiene Protocols:FDA and EFSA food-contact regulations require corrosion-resistant wire enclosures in meat processing and dairy operations, expanding premium product adoption.
Market Restraints
- Galvanized Steel Input Volatility:Zinc price fluctuations and scrap steel availability constrain margin stability for carbon steel wire cage producers in China and India.
- Welding Certification Bottlenecks:ISO 3834 compliance requirements for traceable weld documentation extend production lead times and exclude uncertified fabricators from commercial contracts.
- Plastic Pallet Box Substitution:Injection-molded bulk containers from Macro Plastics and Schoeller Allibert capture pharmaceutical and electronics verticals seeking lighter tare weights.
Strategic Opportunities
- India Cold-Chain Expansion:FSSAI-mandated food safety infrastructure investments create demand for stackable wire containers in temperature-controlled logistics hubs around Mumbai and Delhi.
- RFID-Integrated Mesh Tracking:Convergence of welded wire fabrication with passive RFID tagging enables real-time inventory visibility for automotive just-in-sequence delivery systems.
- EU Green Deal Steel Sourcing:CSRD reporting requirements on recycled content percentage incentivize procurement shifts toward electric-arc-furnace steel suppliers in European wire container manufacturing.
Industry Challenges
- Robotic Interface Standardization Delays:Absence of unified mesh pitch and gauge specifications complicates integration with warehouse automation systems from KUKA and Fanuc.
- Weld Inspector Certification Scarcity:Shortage of EN ISO 9712-qualified non-destructive testing personnel extends quality assurance timelines for export-bound container orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Containers Market |
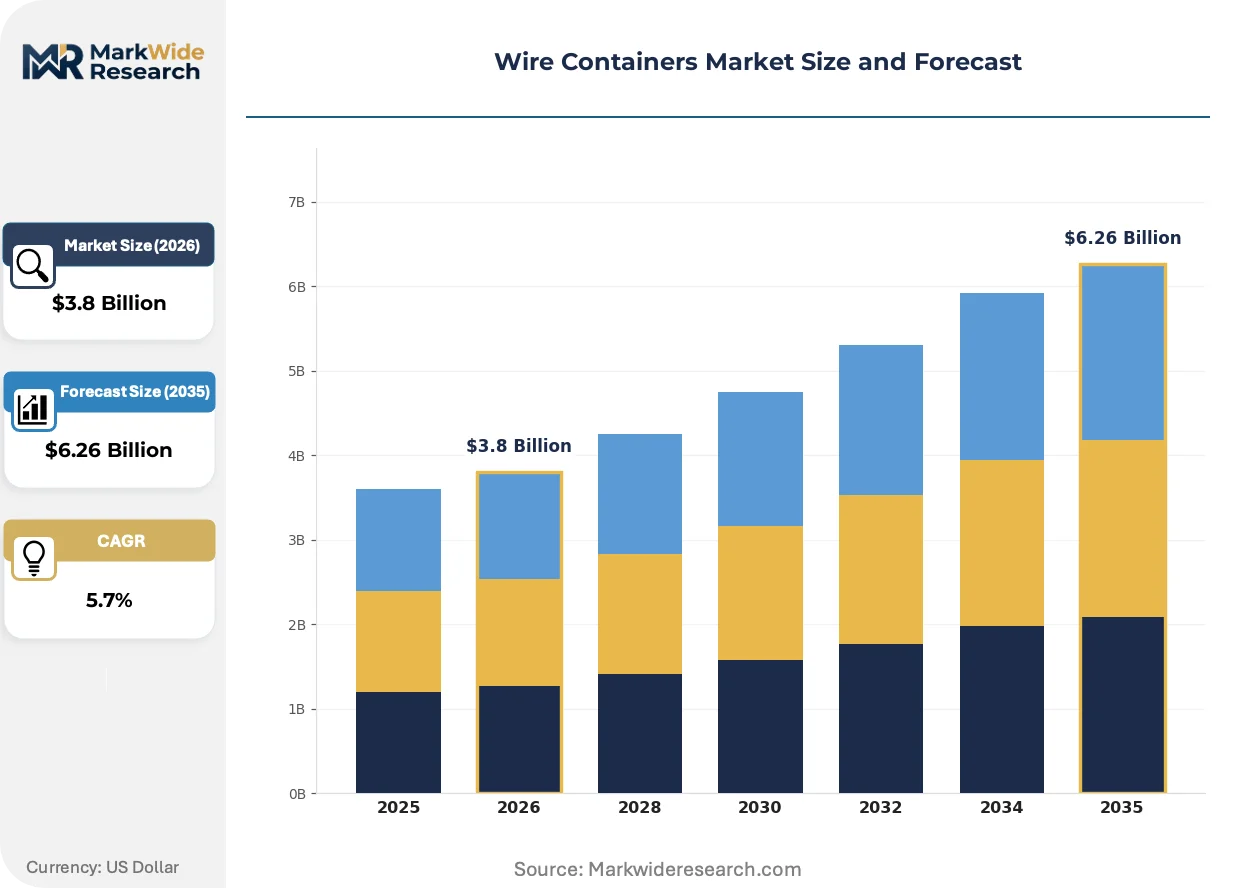
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Baskets, Wire Cages, Wire Trolleys, Wire Racks Material: Stainless Steel, Carbon Steel, Galvanized Steel, Aluminum End User: Retail, Manufacturing, Food Industry, Logistics Capacity: Small, Medium, Large, Custom |
| Companies Covered | Massey Rack, Vestil Manufacturing Corp., KW Materials Handling, Worldwide Material Handling, Warehouse Rack & Shelf, Lafayette Wire Products, Nefab Packaging, Troax Group, Nashville Wire Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Containers Market Evolving Landscape
Digital twin technology and predictive maintenance platforms are rewiring how wire container fleets are managed across multi-site distribution networks, compressing asset utilization metrics and reshaping procurement evaluation criteria.
Modular mesh virtualization is enabling rapid reconfiguration of container dimensions through standardized connection nodes. Tier-one automotive suppliers in Stuttgart and Detroit deploy these systems for powertrain component sequencing. The technology is virtualizing traditional fixed-capacity cage procurement into flexible pool management.
EPA's emerging steel recycling content reporting rules will require documented supply chain provenance for galvanized wire inputs. Fabricators must implement batch-level tracking systems to satisfy disclosure mandates. Carbon steel product lines face the steepest compliance adaptation burden.
Leasing models displace outright purchase for seasonal retail operations. Third-party pool managers in the Netherlands and Ohio now offer per-trip pricing with maintenance inclusion. Apparel and consumer electronics verticals drive adoption where demand fluctuates sharply.
Wire Containers Market Segmentation
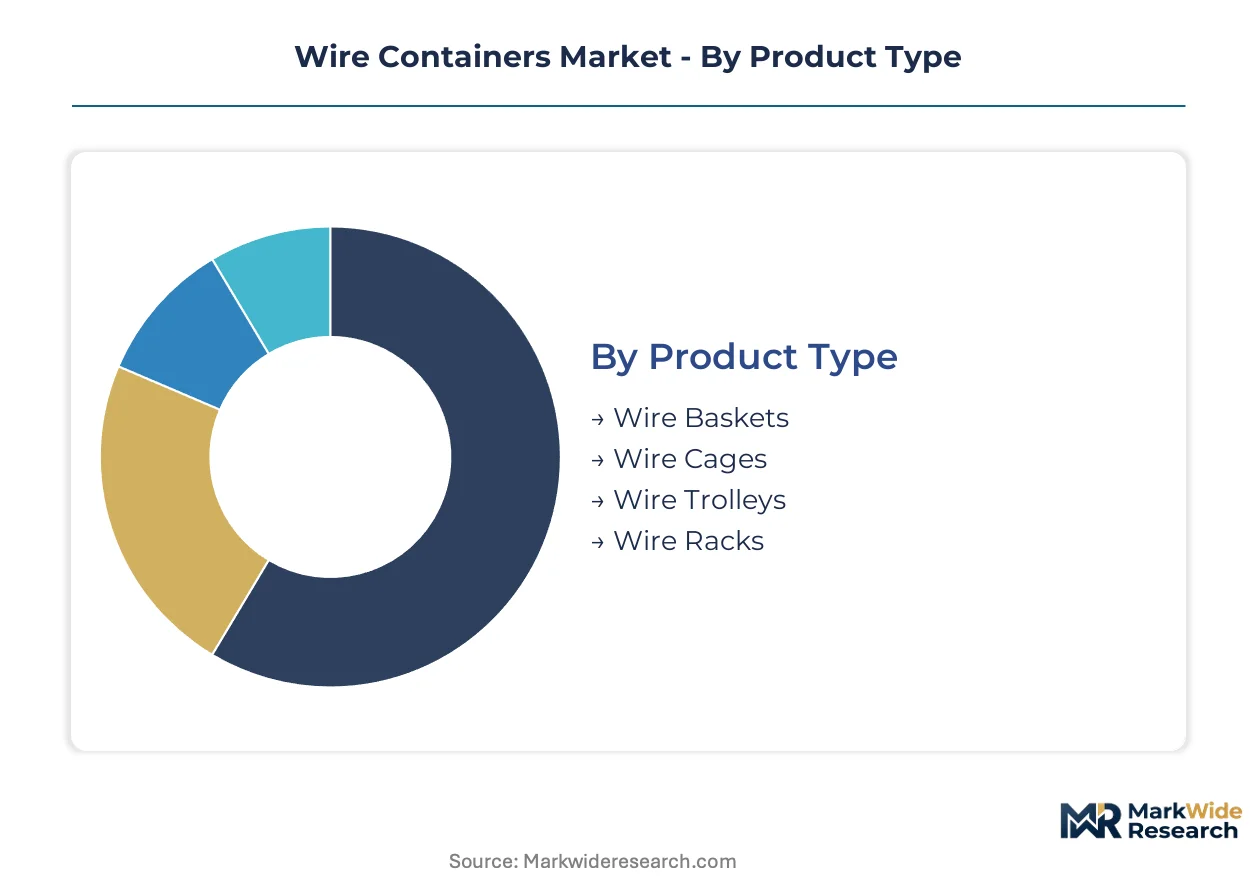
Wire container procurement patterns diverge sharply across material grades and load specifications. Buyers segment purchases by corrosion exposure, automation compatibility, and regulatory compliance burdens rather than unit geometry alone.
Product Type:
Application context determines which enclosure geometry delivers optimal unit economics for material handling workflows.
- Wire Baskets:Open-top mesh containers with drop-gate access suit high-velocity picking operations. Amazon fulfillment centers in Germany and the United States standardize on 24-inch base variants for apparel returns processing.
- Wire Cages:Fully enclosed welded structures with hinged doors dominate automotive component sequencing. Load ratings from 1,500 to 4,000 pounds accommodate powertrain modules for just-in-time delivery to Stuttgart and Detroit assembly plants.
- Wire Trolleys:Caster-mounted mobile units serve maintenance operations and tool cribs. KW Materials Handling anchors market position through specialized trolleys for automotive assembly line replenishment.
- Wire Racks:Vertical shelving configurations maximize cube utilization in cold-storage environments. Massey Rack competes on custom capacity configurations for temperature-controlled logistics.
Wire cages command the established base. The steepest expansion runs through wire trolleys.
Material:
Corrosion resistance requirements and input cost volatility split procurement between premium alloys and commodity grades.
- Stainless Steel:AISI 304 and 316 grades resist chemical exposure in meat processing and dairy operations. FDA and EFSA food-contact regulations mandate these alloys for direct product contact surfaces, expanding premium positioning despite 40-60% cost premiums over carbon alternatives.
- Carbon Steel:Plain welded wire dominates manufacturing end-use where ambient conditions permit surface oxidation. Cost efficiency outweighs chemical exposure risks in general industrial storage and transport pooling applications.
- Galvanized Steel:Zinc-coated wire balances corrosion protection against cost constraints. EPA recycling content reporting requirements are reshaping sourcing decisions for this intermediate grade.
- Aluminum:Lightweight extrusions serve aerospace component handling where tare weight reduction justifies material premiums. Limited penetration outside aviation and precision electronics verticals.
Carbon steel commands the established base. The steepest expansion runs through stainless steel.
End User:
Regulatory exposure and throughput velocity shape specification requirements across downstream verticals.
- Retail:Seasonal demand surges drive collapsible container adoption for returns processing and inventory staging. E-commerce fulfillment density concentrates procurement among Amazon, Walmart, and regional 3PL operators.
- Manufacturing:Heavy-duty welded cages with certified load ratings support work-in-process storage and line-side delivery. OSHA walking-working surface standards mandate documented testing for US facilities.
- Food Industry:Hygiene protocols require corrosion-resistant enclosures with smooth weld finishes. FSSAI-mandated infrastructure investments in India are expanding addressable market for stackable temperature-compatible units.
- Logistics:Pool management operators deploy RFID-integrated mesh for asset tracking across multi-site networks. Third-party pool managers in the Netherlands and Ohio now offer per-trip pricing with maintenance inclusion.
Manufacturing commands the established base. The steepest expansion runs through logistics.
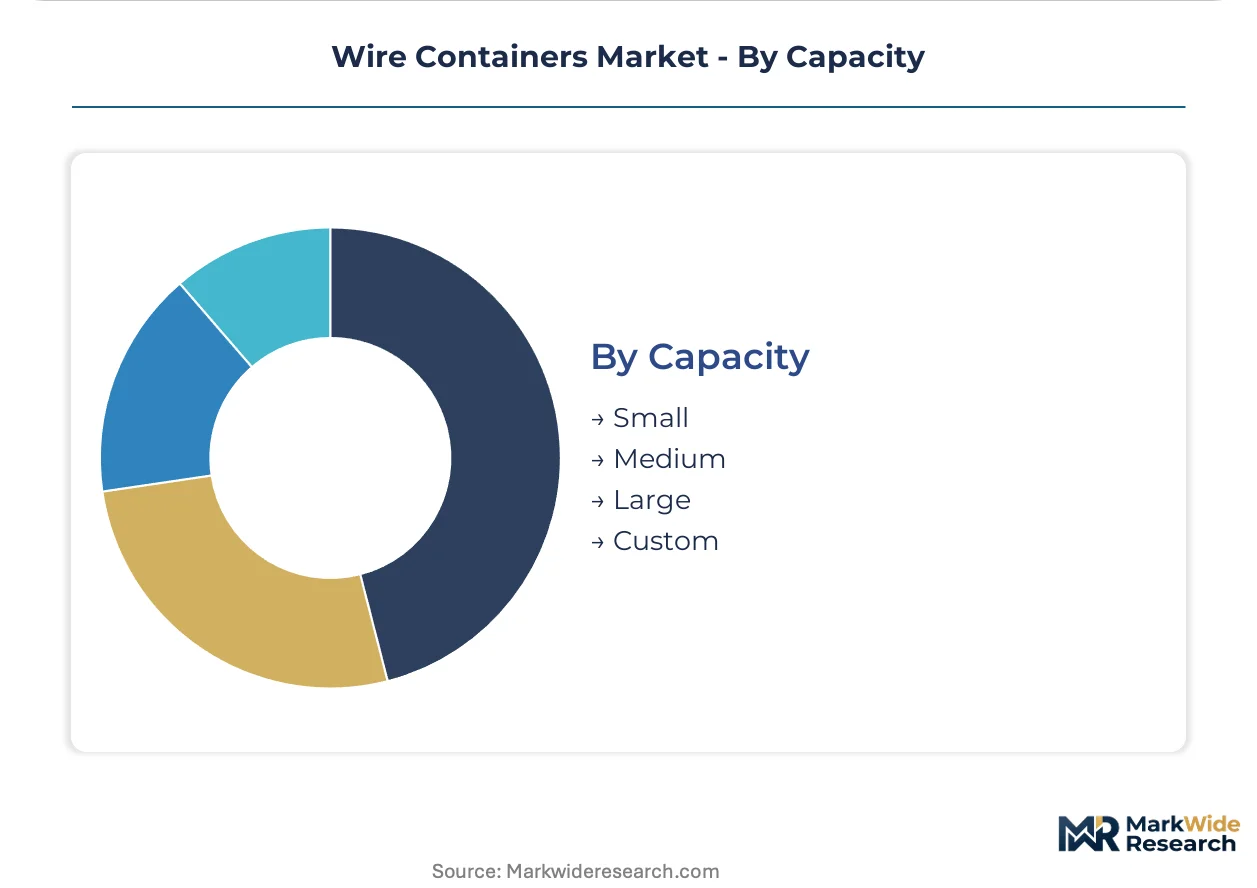
Capacity:
Load rating and dimensional flexibility segment procurement between standardized pooling assets and engineered custom configurations.
- Small:Sub-500 pound ratings serve electronics component handling and pharmaceutical batch operations. Custom configurations capture disproportionate margin pools in these regulated verticals.
- Medium:500-2,000 pound ratings balance cube efficiency against manual handling constraints. This segment leads unit volume across general distribution applications.
- Large:2,000-4,000 pound ratings accommodate bulk raw materials and subassemblies. Automated guided vehicle compatibility requirements are compressing design cycles for mesh geometry standardization.
- Custom:Non-standard dimensions and specialized fittings serve automotive sequencing and aerospace component racking. Modular mesh virtualization is enabling rapid reconfiguration through standardized connection nodes.
Medium capacity commands the established base. The steepest expansion runs through custom configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive assembly plants and e-commerce fulfillment centers drive procurement concentration across Germany, the United States, and China. Cold-chain logistics investments in India and regulatory compliance requirements in the European Union reshape regional demand patterns.
United States
OSHA walking-working surface standards mandate documented load-testing for material handling equipment across distribution networks. Amazon and Walmart fulfillment centers in Ohio and Pennsylvania deploy collapsible wire containers for returns processing. Third-party pool managers in the Midwest now offer per-trip pricing with maintenance inclusion.
Germany
Automotive just-in-sequence delivery systems in Stuttgart and Munich require heavy-duty welded cages with certified load ratings. EU machinery safety directives and CSRD reporting requirements on recycled steel content reshape procurement decisions. Fabricators in Bavaria and North Rhine-Westphalia concentrate production for European automotive tier-one suppliers.
China
Dual carbon goals and steel recycling mandates from the Ministry of Ecology and Environment constrain raw material sourcing for galvanized wire producers. Manufacturing clusters in Guangdong and Jiangsu provinces drive volume demand for carbon steel cages in general industrial applications. Scrap steel availability fluctuations compress margin stability for mid-tier fabricators.
India
FSSAI-mandated food safety infrastructure investments create demand for stackable wire containers in temperature-controlled logistics hubs around Mumbai and Delhi. Cold-chain expansion for dairy and meat processing requires corrosion-resistant enclosures with smooth weld finishes. Logistics operators in Maharashtra and Gujarat prioritize RFID-integrated mesh for real-time asset tracking.
Japan
METI industrial standards and JIS certification requirements govern weld quality documentation for export-bound container orders. Automotive component suppliers in the Nagoya and Osaka regions deploy automation-compatible mesh geometry for robotic gripping interfaces. Precision electronics manufacturers in Kanto drive demand for small-capacity custom configurations.
Wire Containers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where regional fabrication networks and certification capabilities determine contract access. The market structures around three tiers: multinational material handling conglomerates with broad distribution reach, mid-cap regional fabricators holding ISO-certified weld documentation, and specialized custom shops serving pharmaceutical and aerospace verticals. M&A activity concentrates among North American and European players seeking geographic coverage expansion, while technology licensing agreements proliferate for RFID-integrated mesh tracking systems.
Among North American fabricators, Vestil Manufacturing Corp. and Massey Rack exemplify the regional-specialist archetype, with the former leveraging fabrication network density and the latter competing on custom capacity configurations. KW Materials Handling anchors a position through specialized mobility solutions. These three represent distinct competitive vectors: scale-driven distribution, application-engineered customization, and vertical-specific mobility integration.
| Leading Market Players |
|---|
| Massey Rack |
| Vestil Manufacturing Corp. |
| KW Materials Handling |
| Worldwide Material Handling |
| Warehouse Rack & Shelf |
| Lafayette Wire Products |
| Nefab Packaging |
| Troax Group |
| Nashville Wire Products |
| Others |
Value Network & Pricing Analysis
Guangdong and Jiangsu manufacturing clusters anchor galvanized wire supply, with their capacity utilization rates directly transmitting into downstream pricing leverage for carbon steel cage producers serving automotive sequencing contracts.
Pricing Analysis
Cost-plus contracts with London Metal Exchange zinc indexation dominate galvanized steel wire procurement, insulating fabricators from raw material volatility while compressing margins during LME price spikes. Price differentiation hinges on ISO 3834 weld certification tier and automation-compatible mesh geometry. Pricing pressure intensifies in carbon steel segments as Indian scrap steel availability fluctuates. Small electronics handlers exhibit acute price sensitivity; pharmaceutical and aerospace buyers prioritize certification grade over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among ISO-certified weld shops in Bavaria, Ohio, and Guangdong provinces, with certified fabricators holding priority access to automotive tier-one supplier contracts. Raw material flows draw from electric-arc-furnace steel mills in Germany, induction furnaces in India, and integrated blast furnace operations in China. Single-source vulnerability runs through EN ISO 9712-qualified weld inspector pools, where certification scarcity extends quality assurance timelines. Distribution runs through regional material handling distributors and third-party pool managers offering per-trip pricing with maintenance inclusion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified weld documentation scarcity constrains contract access, with EN ISO 9712-qualified inspector availability representing the binding capacity bottleneck for export-bound orders.
For Market Incumbents: Build certification moats by deepening inspector training pipelines and securing captive EN ISO 9712-qualified personnel pools. Expand backward integration into electric-arc-furnace steel sourcing to satisfy EU Green Deal recycled content mandates. Defend against plastic pallet box substitution in pharmaceutical verticals by emphasizing FDA-compliant stainless steel traceability. For New Entrants and Emerging Players: Pursue India cold-chain logistics hubs around Mumbai and Delhi, where FSSAI-mandated infrastructure investments outstrip certified local fabrication capacity. Target RFID-integrated mesh tracking as a technology licensing entry point with lower capital barriers than heavy-gauge welding certification. Lead with per-trip leasing models to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regional ISO-certified fabricators in North America and Europe remain fragmented and acquisition-ready at reasonable multiples. Target mid-cap specialists with established automotive tier-one relationships and documented weld certification. Monitor warehouse automation penetration rates in mid-tier logistics operations as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | EN ISO 9712 weld inspector training secures automotive tier-one contract access against uncertified competitors. |
| Backward Integration | Captive electric-arc-furnace steel sourcing satisfies CSRD recycled content reporting for EU automotive customers. |
| Technology Licensing | RFID-integrated mesh tracking partnerships enable real-time inventory visibility without full R&D capital deployment. |
| Geographic Expansion | FSSAI-mandated cold-chain investments in Maharashtra and Gujarat create addressable demand for corrosion-resistant enclosures. |
| Service Model Pivot | Per-trip leasing with maintenance inclusion captures seasonal retail demand without capital-intensive fleet ownership. |
Research Methodology
A standing panel of automotive tier-one procurement managers, cold-chain logistics operators, ISO-certified weld shop supervisors, and material handling distributors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through OSHA enforcement databases, EU machinery safety directive compliance registries, and customs trade flow records for galvanized steel wire. Bottom-up volume modeling triangulated against top-down market sizing from e-commerce fulfillment center deployment data.
Scenario bracketing around automation penetration rates and zinc price volatility informed projection boundaries across the analysis window. Segmentation dimensions modeled include product type, material grade, end-use vertical, and capacity tier, with robotic interface compatibility treated as a cross-cutting attribute. CAGRs derived from historical shipment correlations with automotive production indices and e-commerce warehouse square footage expansion.
Sensitivities concentrate around warehouse automation standardization timelines and EN ISO 9712 inspector certification throughput. Forecasts reflect assumptions on galvanized steel input cost trajectories and regulatory enforcement consistency for FDA and EFSA hygiene protocols. Quarterly review of automotive just-in-sequence contract awards and 3PL pool manager fleet expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Injection Molding Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
Popcorn Containers Market
Containers
Disposable Lids Market
Containers
LDPE Containers Market
Containers
Screw Top Jar Market
Containers
North America Plastic Bottles and Containers Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Club Store Packaging Tray Market
Containers
Kuwait Container Glass Market
Containers
Screw Top Lids Market
Containers
Vials Market
Containers
Container Coating Market
Containers
PET Hinged Containers Market
Containers
Global Flexitanks Market
Containers
Trigger Sprayer Market