
 Cups and Lids Market | 2026-2036
Cups and Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Cups and Lids Market Analysis
Multi-source resin procurement is pivoting toward captive polymer supply as converters seek margin protection against petrochemical volatility. Berry Global Inc. leverages its North American resin compounding network to stabilize input costs for injection-molded lids. Huhtamäki Oyj anchors its position through integrated fiber sourcing and molded-fiber manufacturing in European quick-service supply chains. Dart Container Corporation dominates the US foam cup segment through vertical control of expandable polystyrene bead production and regional distribution density.
Cups and lids comprise engineered containment systems for liquid and semi-liquid food service products, typically manufactured through thermoforming, injection molding, or fiber-molding processes with wall thicknesses calibrated for thermal insulation and stackability. Their primary commercial purpose is to enable safe, branded beverage and food distribution across away-from-home consumption channels. Disposable cups remain the volume anchor, though biodegradable materials represent the fastest-expanding material category as food service operators face compliance deadlines under extended producer responsibility frameworks. Lids command disproportionate margin contribution due to precision-fit engineering requirements and proprietary aperture designs for strawless consumption.
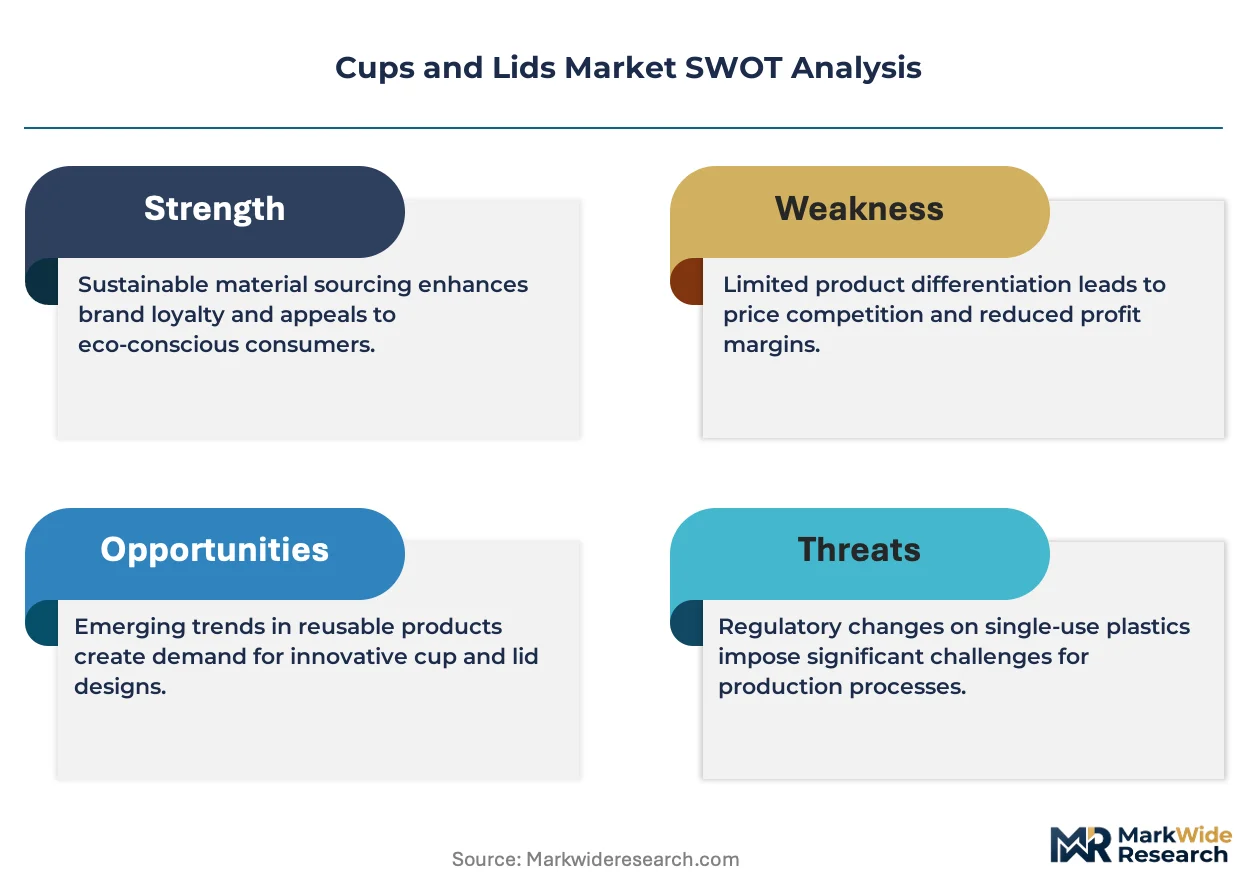
The US Food and Drug Administration governs food-contact substance compliance under 21 CFR, while the EU F-Gas Regulation and REACH restrict certain polymer additives and blowing agents used in insulated cup production. These frameworks elevate compliance costs for imported stock and favor regional manufacturers with certified material streams and testing infrastructure. Stakeholders must monitor evolving state-level extended producer responsibility legislation in the United States, where fragmented policy development between California, Maine, and Oregon threatens to fragment national product specifications and distribution economics.
Market Dynamics
The EU Single-Use Plastics Directive is forcing material transitions across European food service packaging, while quick-service restaurant chains in the United States expand cold-beverage programs that pull specialized cup and lid combinations. These dual pressures are restructuring converter procurement and resin sourcing strategies simultaneously.
Growth Catalysts
- Regulatory mandates:The EU Single-Use Plastics Directive bans specific single-use items and mandates recycled content thresholds, creating compliance-driven replacement cycles across European food service packaging.
- Quick-service beverage expansion:Cold-beverage program growth at major quick-service restaurant chains sustains high-volume procurement of specialized cup and lid combinations with precision-fit engineering.
- Stadium and venue concessions:Drive-through consumption patterns and large-format event catering in the United States concentrate demand for durable, branded containment systems.
Market Restraints
- Petrochemical input volatility:Expandable polystyrene bead and polypropylene resin prices fluctuate with crude oil indices, compressing converter margins on fixed-price annual contracts.
- Regional supply concentration:Expandable polystyrene bead production clusters in the US Gulf Coast and select European petrochemical corridors, exposing buyers to localized disruption risks.
- Material performance gaps:Molded-fiber alternatives to plastic insulated cups exhibit inferior thermal retention and liquid barrier properties, limiting substitution in extended-hold applications.
Strategic Opportunities
- Extended producer responsibility frameworks:State-level EPR legislation in California, Maine, and Oregon creates certified material stream premiums for converters with testing infrastructure and verified recycling partnerships.
- Strawless lid engineering:Proprietary aperture designs for direct consumption are displacing standard flat lids, enabling patent-protected margin capture in quick-service supply chains.
- Captive resin compounding:Backward integration into polymer supply stabilizes input costs and insulates against petrochemical volatility for injection-molded lid manufacturers.
Industry Challenges
- Fragmented EPR compliance:Divergent state-level extended producer responsibility requirements across California, Maine, and Oregon threaten to fragment national product specifications and distribution economics.
- Biodegradable certification timelines:Industrial composting and marine biodegradability testing protocols under ASTM and TÜV standards extend product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cups and Lids Market |
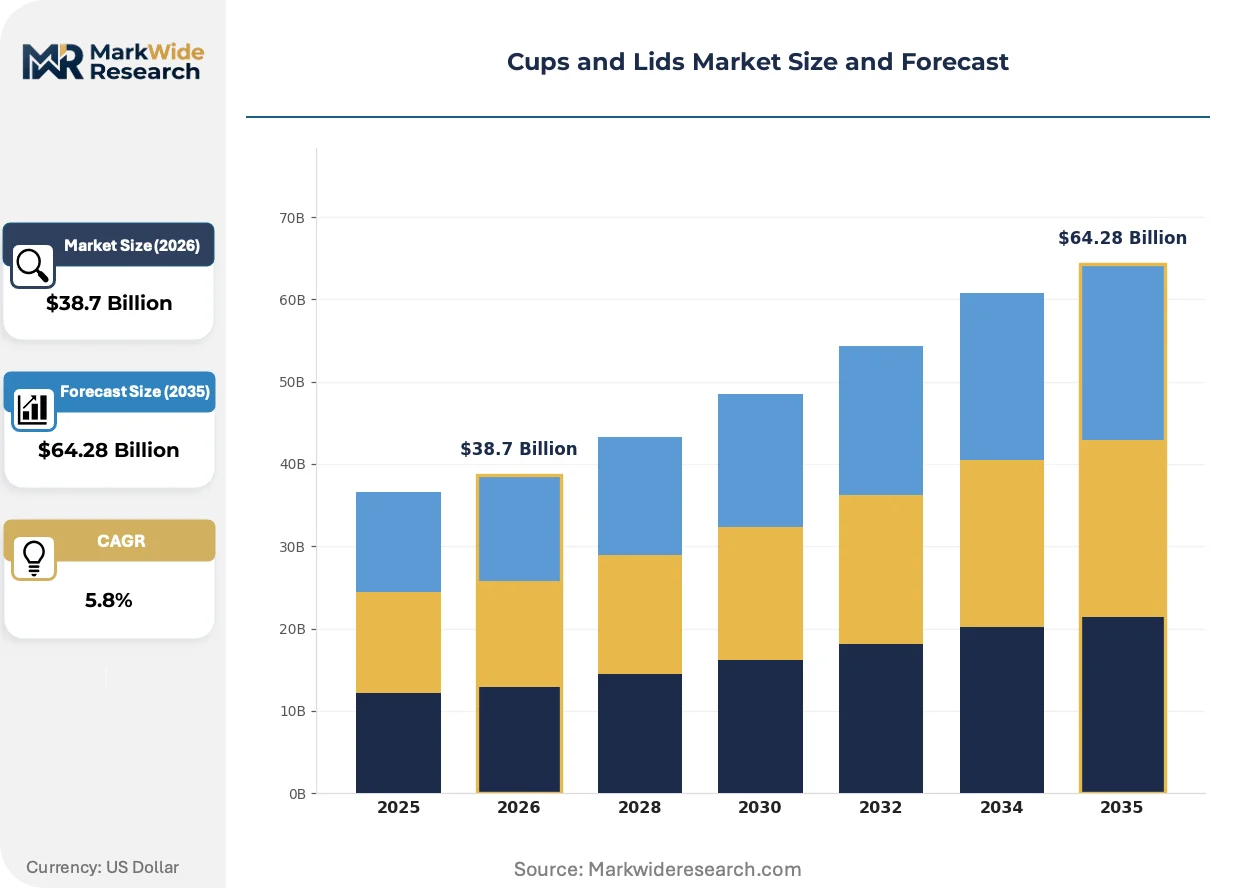
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Cups, Reusable Cups, Lids, Sleeves Material: Plastic, Paper, Foam, Biodegradable End User: Food Service, Retail, Industrial, Home Use Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Berry Global Inc., Huhtamäki Oyj, Dart Container Corporation, Greiner AG, Graphic Packaging International Inc., WinCup Inc., Solo Cup Operating Corporation, Reynolds Consumer Products, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cups and Lids Market Emerging Trajectories
Automation and material science are converging to reshape cup and lid manufacturing economics, while regulatory compliance requirements accelerate capital deployment toward certified production lines.
Robotic pick-and-place systems integrated with thermoforming lines are automating lid-to-cup assembly and sleeve application at quick-service restaurant packaging facilities. Major US fast-food chains are adopting these systems at greenfield distribution centers to reduce labor dependency and improve stackability consistency. This automation is compressing unit economics for high-volume converters while raising barriers for smaller regional competitors.
The EU F-Gas Regulation restricts hydrofluorocarbon blowing agents used in insulated cup production, forcing converters to qualify alternative thermal insulation chemistries. European manufacturers are accelerating adoption of carbon dioxide and hydrocarbon blowing agent systems to maintain thermal performance compliance. Molded-fiber insulated cup categories are capturing share in Nordic markets where regulatory enforcement timelines are shortest.
Consolidated procurement at quick-service restaurant headquarters is displacing distributed purchasing through regional distributors, centralizing specification authority with sustainability and packaging engineering teams. Direct converter relationships now govern 60-70 percent of cup and lid volume for top ten US fast-food chains. This concentration is most visible in the US Southeast, where several quick-service headquarters clusters negotiate multi-year supply agreements with integrated packaging suppliers.
Cups and Lids Market Segmentation
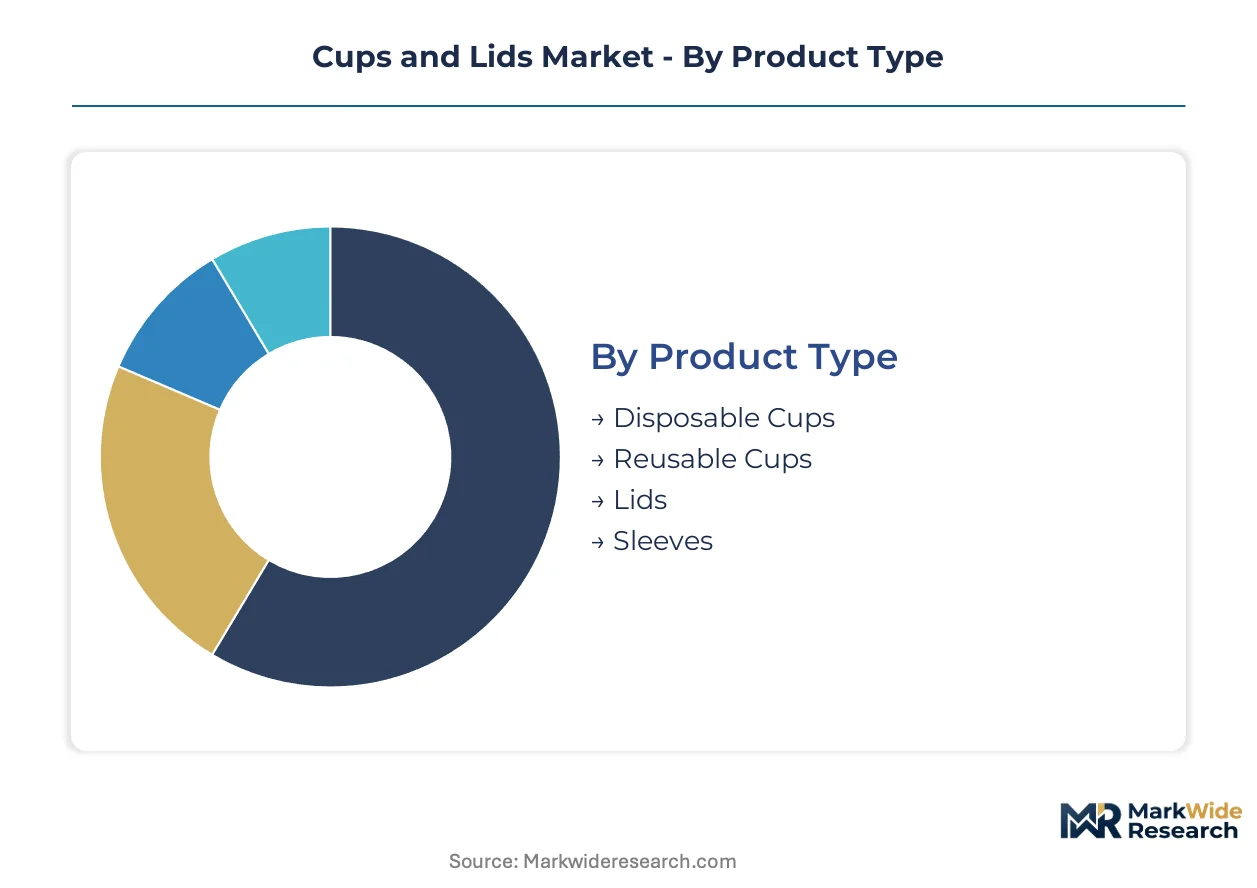
Cup and lid procurement decisions cascade through material specifications, capacity requirements, and end-use durability demands. Each segmentation dimension carries distinct capital requirements and margin profiles that reshape converter investment priorities.
Product Type:
Capital intensity peaks in lid manufacturing, where precision-fit engineering demands injection molding infrastructure with tight tolerance controls.
- Disposable Cups:Thermoformed or fiber-molded single-use vessels dominate quick-service restaurant procurement. Stadium concessions and drive-through beverage programs in the United States sustain the highest-volume demand clusters for this segment.
- Reusable Cups:Durable polypropylene or stainless steel vessels engineered for 500+ wash cycles. Corporate sustainability mandates at major coffee chains are accelerating procurement shifts toward deposit-return schemes in Nordic markets.
- Lids:Injection-molded containment systems with proprietary aperture geometries for strawless consumption. Precision engineering requirements command disproportionate margin contribution relative to material weight.
- Sleeves:Corrugated paper or molded-fiber thermal barriers that reduce wall thickness requirements in cup substrates. Demand concentrates in specialty coffee retail where extended hold times matter.
Most installed capacity flows through Disposable Cups. Expansion is steepest in Lids.
Material:
Raw material sourcing strategies diverge sharply between petrochemical-based substrates and certified biodegradable alternatives.
- Plastic:Polypropylene and PET formulations dominate cold-beverage applications through thermoforming and injection molding. FDA 21 CFR compliance requirements favor domestic converters with certified material streams in the United States.
- Paper:Polyethylene-lined or aqueous-barrier-coated fiber vessels for hot-fill applications. EU Single-Use Plastics Directive enforcement is redirecting procurement toward plastic-free barrier chemistries in Germany and France.
- Foam:Expandable polystyrene bead systems for insulated cup production. REACH restrictions on hydrofluorocarbon blowing agents are forcing qualification of carbon dioxide alternatives in European manufacturing.
- Biodegradable:PLA, PHA, and molded-fiber substrates certified to ASTM or TÜV composting standards. Industrial composting infrastructure gaps limit deployment to regions with verified collection and processing partnerships.
Plastic retains the largest production base. Biodegradable alternatives are climbing the fastest.
End User:
Customer procurement authority is consolidating at headquarters level for the largest volume accounts.
- Food Service:Quick-service restaurant chains and contract caterers sourcing through centralized specifications. Direct converter relationships now govern the majority of cup and lid volume for top ten US fast-food chains.
- Retail:Grocery chains and convenience stores with private-label beverage programs. Shelf-stable packaging requirements differ from food service durability standards.
- Industrial:Vending machine operators and institutional food service contractors. Procurement emphasizes stackability and dispensing compatibility over branding.
- Home Use:Consumer-packaged goods sold through mass retail channels. Seasonal demand spikes around sporting events and holiday entertaining patterns.
Food Service channels deploy the most capital. Home Use is gaining share fastest.
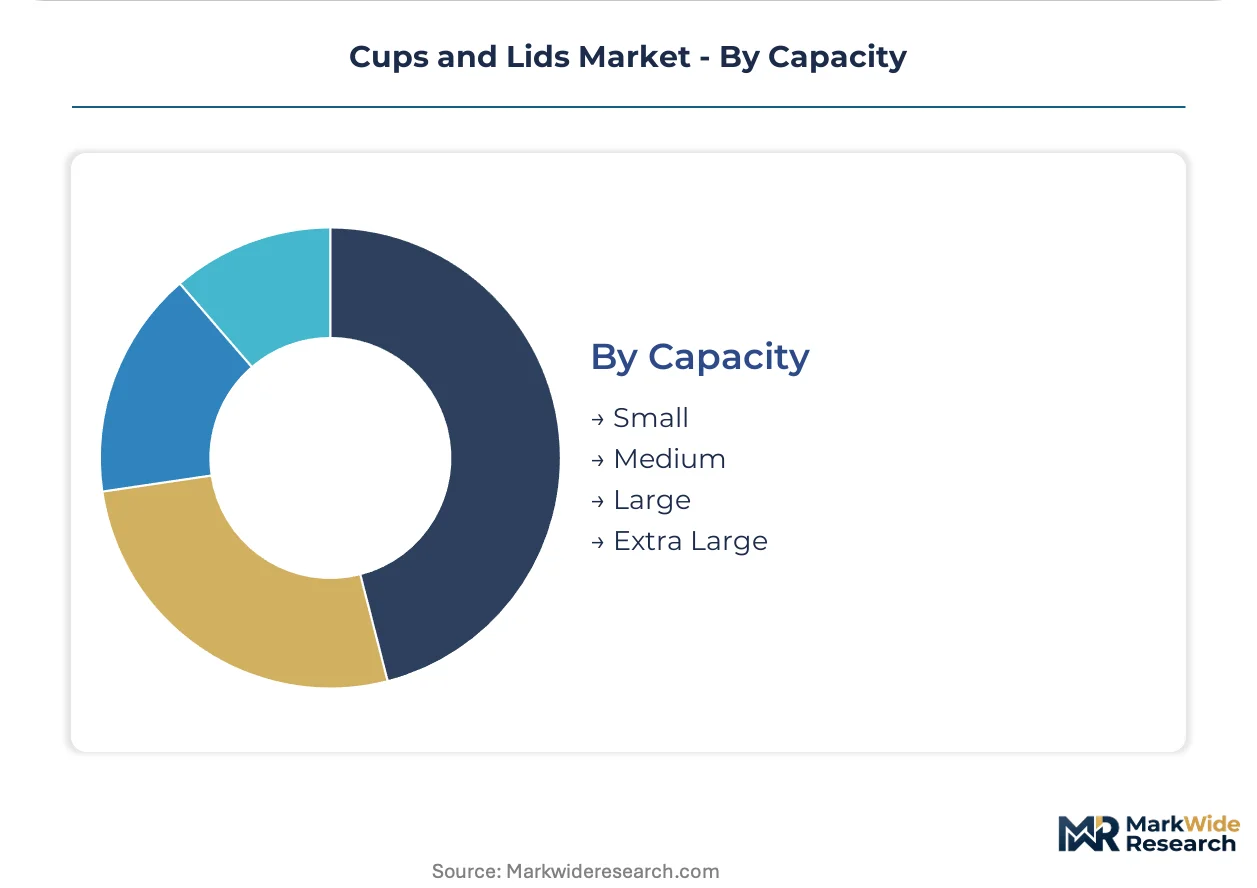
Capacity:
Equipment scale economies favor dedicated lines for high-volume formats over flexible short-run production.
- Small:Espresso and sampling vessels under 8 ounces. Specialty coffee chains drive specification innovation for this format.
- Medium:Standard 12-16 ounce vessels for core beverage menus. This format captures the highest absolute volume across quick-service and specialty coffee segments.
- Large:20-24 ounce vessels for value-oriented beverage programs. Drive-through consumption patterns in the United States sustain disproportionate demand for this capacity tier.
- Extra Large:32+ ounce vessels for shared and extended-consumption occasions. Stadium and cinema concessions concentrate procurement for this format.
Medium capacity absorbs the most installed equipment. Extra Large formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US quick-service restaurant headquarters clusters in Atlanta and Dallas-Fort Worth anchor procurement authority for the cups and lids industry. These metropolitan areas concentrate specification negotiations for multi-year supply agreements. Regulatory divergence between jurisdictions is fragmenting product standards.
United States
Drive-through beverage consumption and stadium concessions in the US Southeast sustain high-volume procurement of large-format cups. FDA 21 CFR compliance requirements favor domestic converters with certified material streams. The Atlanta metropolitan area hosts several quick-service headquarters that centralize national purchasing decisions.
Germany
Industrial composting infrastructure in Bavaria and Baden-Württemberg supports deployment of biodegradable cup categories. REACH restrictions on hydrofluorocarbon blowing agents are accelerating carbon dioxide alternative qualification. The Rhine-Ruhr corridor concentrates molded-fiber manufacturing capacity for European quick-service supply chains.
China
Export-oriented thermoforming operations in Guangdong and Zhejiang provinces supply global food service distributors. SAMR food-contact substance regulations elevate testing costs for international shipment compliance. The Yangtze River Delta cluster dominates injection-molded lid production for Asian quick-service markets.
France
Plastic-free barrier chemistry adoption concentrates in Île-de-France quick-service operations under EU Single-Use Plastics Directive enforcement. ANSM food-contact oversight intersects with national extended producer responsibility implementation. The Lyon-Auvergne-Rhône-Alpes region hosts specialized fiber-molding facilities serving pan-European retail.
India
Quick-service expansion in Maharashtra and Karnataka drives medium-capacity cup demand from domestic thermoformers. FSSAI packaging regulations are tightening migration testing requirements for polyethylene-lined paper vessels. The Delhi-NCR corridor concentrates import distribution for premium injection-molded lid categories.
Cups and Lids Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable certification and strawless aperture engineering. The cups and lids market exhibits tiered concentration, with integrated resin compounders and fiber molders commanding margin premiums over pure-play distributors. Three archetypes dominate: petrochemical-integrated converters with captive resin supply, fiber-specialist molders with European regulatory alignment, and regional thermoformers serving distributed food service accounts. Competitive moves center on backward integration into polymer compounding and multi-year procurement lock-ins with quick-service headquarters.
Among North American resin-integrated converters, Berry Global Inc. and Dart Container Corporation exemplify the captive-supply archetype, while Huhtamäki Oyj represents European fiber-integration positioning. These three entities anchor distinct strategic vectors: petrochemical cost stabilization, molded-fiber regulatory compliance, and quick-service direct contracting relationships.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Huhtamäki Oyj |
| Dart Container Corporation |
| Greiner AG |
| Graphic Packaging International Inc. |
| WinCup Inc. |
| Solo Cup Operating Corporation |
| Reynolds Consumer Products |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
The EU Single-Use Plastics Directive gates both qualified supply and premium-tier pricing access by mandating recycled content thresholds and banning specific single-use items. Converters with certified material streams command pricing premiums while uncertified competitors face exclusion from quick-service restaurant procurement channels.
Pricing Analysis
Input-cost pass-through from expandable polystyrene bead and polypropylene resin volatility shapes contract structures across the cups and lids market. Three-tier pricing structure across premium, standard, and economy levels separates biodegradable-certified suppliers from conventional plastic converters from foam-based producers. Cost compression in the economy tier is intensifying because quick-service chains consolidate procurement at headquarters level. Small regional thermoformers exhibit highest price sensitivity while integrated resin compounders with captive supply demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates under FDA 21 CFR and EU REACH restrictions are reshaping sourcing toward regional manufacturers with certified testing infrastructure. Raw material supply draws from expandable polystyrene bead production concentrated on the US Gulf Coast, polypropylene resin compounding in Germany and Belgium, and molded-fiber pulp sourcing across Nordic forest products corridors. Single-source vulnerability in petrochemical corridors exposes converters to localized disruption risks. Distribution runs through direct converter relationships with quick-service headquarters clusters in Atlanta and Dallas-Fort Worth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cups and lids market represents a late-cycle quality story as quick-service restaurant chains pivot procurement toward biodegradable-certified suppliers with verified recycling partnerships.
For Market Incumbents: Hedge against margin compression by accelerating backward integration into polymer compounding and securing multi-year supply agreements with top-ten fast-food headquarters before state-level EPR legislation fragments national specifications. Biodegradable certification timelines and emerging fiber-molding competitors threaten established foam-cup positions. For New Entrants and Emerging Players: Begin with industrial composting infrastructure partnerships in Bavaria and Baden-Württemberg, where regulatory enforcement timelines create immediate demand for certified biodegradable alternatives. Strawless lid engineering with proprietary aperture geometries offers the most penetrable white-space target against incumbent patent portfolios. For Investors and Strategic Acquirers: Roll-up economics work for regional thermoformers with quick-service direct contracts because procurement consolidation at headquarters level is displacing distributed purchasing through distributors. The signal to watch as inflection indicator is state-level EPR adoption velocity beyond California, Maine, and Oregon.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Certification Investment | ASTM and TÜV composting standards unlock premium-tier pricing in EU-regulated channels. |
| Captive Resin Compounding Expansion | Backward integration insulates margin stability against crude oil-indexed petrochemical volatility. |
| Strawless Lid Patent Development | Proprietary aperture geometries enable patent-protected positioning in quick-service supply chains. |
| Multi-Year Headquarters Procurement Lock-In | Direct relationships with Atlanta and Dallas-Fort Worth clusters secure volume commitments. |
| Industrial Composting Infrastructure Partnership | Verified collection and processing partnerships overcome deployment barriers in biodegradable categories. |
Methodological Framework
Multiple input streams — primary interviews with quick-service procurement directors, thermoforming plant managers, and sustainability compliance officers; secondary validation through FDA 21 CFR filings, EU REACH substance restrictions, and SEC disclosures from resin-integrated converters; plus customs data on expandable polystyrene bead trade flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, material substrate, capacity tier, and end-use channel dimensions produced volume and value estimates throughout the forecast period. CAGRs were derived from segment-level growth trajectories weighted by installed equipment capacity and quick-service expansion pipelines.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration in US state-level EPR implementation and breakthroughs in marine biodegradability chemistry that could compress certification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Metal Crates Market
Containers
Spout Containers Market
Containers
Essential Oil Containers Market
Containers
LDPE Containers Market
Containers
Stack and Nest Containers Market
Containers
Container Fixed Fittings Market
Containers
Multi Cavity Tray Market
Containers
Laminated Bulk Bins Market
Containers
Cylindrical Cans Market
Containers
Screw Top Lids Market
Containers
Child-Resistant Containers Market
Containers
Container Stacking Machine Market
Containers
North America Plastic Bottles and Containers Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
Screw Top Jar Market
Containers
Soup Containers Market