
 Humidity Indicator Cards (HIC) Market | 2026-2036
Humidity Indicator Cards (HIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Humidity Indicator Cards (HIC) Market Analytics
Cobalt chloride is realigning product economics as manufacturers shift toward cobalt-free indicator chemistry amid tightening toxic substance controls. 3M Company leverages its materials science heritage to dominate high-reliability electronics applications. Clariant International Ltd. differentiates through specialty chemical expertise in humidity-sensitive coatings. AGM Container competes on geographic proximity to North American aerospace and defense contractors.
Humidity Indicator Cards are paper or polymer substrates impregnated with moisture-sensitive chemicals that undergo visible color transitions at defined relative humidity thresholds, typically manufactured through precision coating processes to ensure batch consistency in threshold accuracy. Their primary purpose is to provide immediate visual verification of moisture exposure during storage, transport, and handling of moisture-sensitive goods. Color Changing products occupy the largest volume share due to their simplicity and universal applicability across pharmaceutical and electronics supply chains. Digital technology represents the fastest-expanding segment, driven by integration demands in automated warehouse management and IoT-enabled cold-chain monitoring systems.
The FDA enforces humidity control standards through stability testing requirements for drug packaging under Current Good Manufacturing Practice regulations. The EPA restricts cobalt chloride use under toxic substance reporting rules, compelling reformulation investments. REACH in Europe mandates chemical safety documentation for indicator card components exported into EU pharmaceutical supply chains. Stakeholders must monitor regulatory divergence between cobalt-free transition timelines in North America and Europe to align product portfolios with diverging compliance deadlines.
Market Dynamics
The cobalt chloride phase-out is compressing product economics as manufacturers absorb reformulation costs while competing on threshold accuracy. This chemistry transition intersects with FDA stability testing mandates to create dual compliance pressure on suppliers serving pharmaceutical and electronics end-uses.
Growth Catalysts
- Biologics cold-chain expansion:Moisture-sensitive monoclonal antibodies and cell therapies multiply humidity monitoring points across pharmaceutical distribution networks. The FDA's evolving stability testing guidelines tighten packaging validation requirements.
- REACH chemical safety mandates:European pharmaceutical supply chains demand documented cobalt-free indicator chemistry. Exporters into EU markets must align product portfolios with ECHA substance restrictions.
- Defense supply chain protocols:United States aerospace contractors require stringent moisture documentation for mission-critical electronics. MIL-STD-3010 specifications institutionalize HIC deployment in military packaging.
Market Restraints
- Cobalt-free chemistry cost premium:Reformulated indicator compounds require specialized synthesis and batch calibration. Raw material substitution elevates unit production costs versus legacy cobalt chloride substrates.
- Threshold accuracy variance:Cobalt-free alternatives exhibit wider color-transition bands at critical humidity setpoints. Precision electronics manufacturers demand tighter tolerance windows than current substitutes reliably deliver.
- Specialty coating capacity concentration:Precision impregnation equipment for consistent indicator distribution concentrates among limited North American and European coating houses.
Strategic Opportunities
- IoT cold-chain convergence:Digital humidity sensors integrating with warehouse management systems create hybrid monitoring architectures. Automated pharmaceutical distribution centers in Germany and Switzerland pilot combined visual-digital verification.
- India pharmaceutical manufacturing:CDSCO packaging guidelines for export-oriented drug production create compliance-driven HIC demand. Domestic generic API producers upgrade moisture control infrastructure.
- Reusable indicator substrates:Polymer-based cards with reversible color chemistry reduce per-shipment consumable costs. Circular economy packaging mandates in France and the Netherlands accelerate pilot programs.
Industry Challenges
- Colorimetric calibration expertise scarcity:Reformulation chemists with humidity-sensitive dye experience command premium compensation. Manufacturers compete for talent capable of maintaining batch-to-batch threshold consistency.
- Dual certification timeline compression:Suppliers must simultaneously secure FDA drug packaging acceptability and EPA toxic substance compliance. Parallel regulatory pathways strain quality assurance bandwidth.
- Legacy inventory obsolescence:Cobalt chloride card stocks face accelerated write-downs as customer specifications shift. Distributors absorb margin compression from stranded product.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humidity Indicator Cards (HIC) Market |
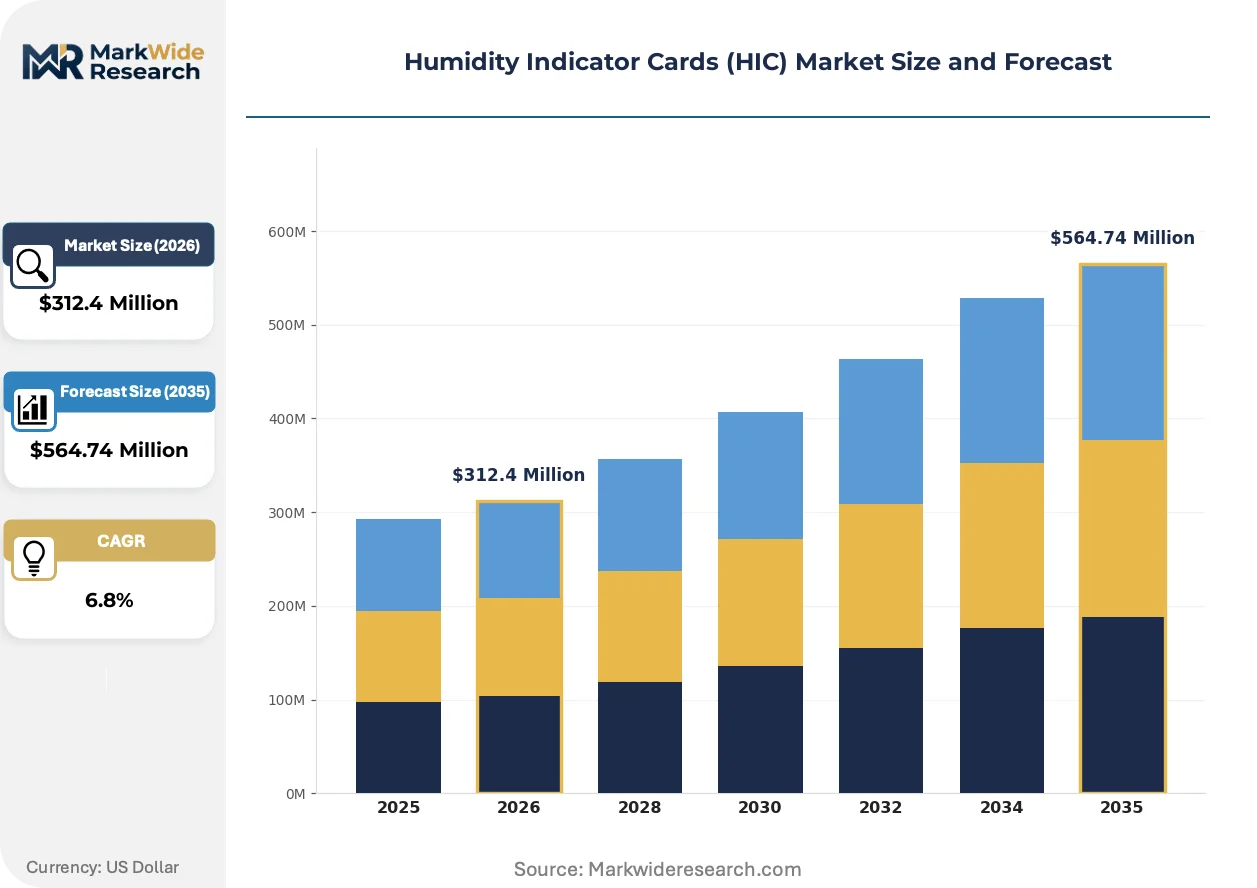
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Color Changing, Reusable, Disposable, Digital End User: Pharmaceuticals, Food Packaging, Electronics, Museums Technology: Chemical, Electrochemical, Microbial, Polymer Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | 3M Company, Clariant International Ltd., Desiccare Inc., AGM Container, IMPAK Corporation, Advantek, Telatemp, Sanner GmbH, Desco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humidity Indicator Cards (HIC) Market Evolving Landscape
Digital sensing architectures are penetrating humidity monitoring as warehouse automation demands real-time data streams. This convergence compresses the traditional visual-indicator value proposition toward specialized applications.
Near-field communication chips embedded in indicator substrates enable smartphone-readable humidity exposure logs. Pharmaceutical 3PL providers in the Netherlands and Belgium deploy these hybrid cards for automated chain-of-custody documentation. The technology is integrating with existing warehouse management infrastructure without requiring dedicated scanner hardware.
EPA toxic substance reporting rules tighten cobalt chloride thresholds under Section 313 of the Emergency Planning and Community Right-to-Know Act. Electronics manufacturers serving US government contracts face procurement specifications prohibiting cobalt-containing indicators. Defense supply chains accelerate qualification of copper halide and organic dye alternatives.
Consolidated buying by pharmaceutical distributors compresses supplier margins while demanding extended validation documentation. Large 3PL operators in the United States unbundle humidity monitoring from broader packaging services. Direct procurement relationships between generic drug manufacturers and indicator card producers displace traditional distribution intermediaries.
Humidity Indicator Cards (HIC) Market Segmentation
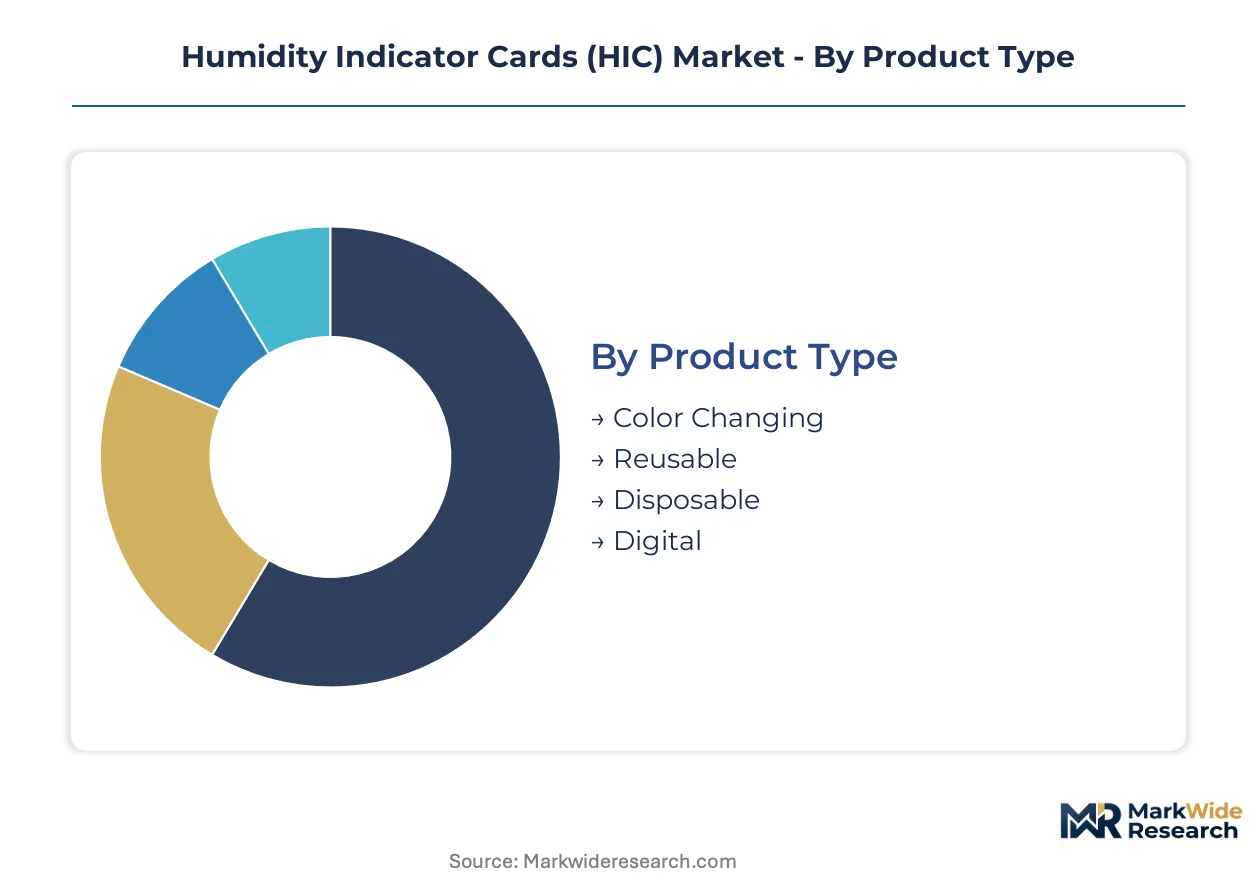
Segmentation in the Humidity Indicator Cards market reflects divergent compliance pressures and technology substitution cycles. Pharmaceutical and electronics end-users drive specification fragmentation as cobalt-free chemistry mandates reshape product portfolios across all categories.
Product Type:
Replacement cycles accelerate as cobalt chloride phase-outs force inventory turnover and qualification of alternative indicator chemistries.
- Color Changing:Paper or polymer substrates impregnated with moisture-sensitive dyes undergo visible transitions at defined relative humidity thresholds. Pharmaceutical cold-chain networks in the United States and Germany standardize these cards for immediate visual verification of moisture exposure during monoclonal antibody distribution.
- Digital:Sensor-equipped cards with NFC or RFID chips transmit real-time humidity data to warehouse management systems. Automated pharmaceutical distribution centers in Switzerland and the Netherlands pilot hybrid visual-digital architectures for automated chain-of-custody documentation.
- Reusable:Polymer-based substrates with reversible color chemistry reduce per-shipment consumable costs under circular economy packaging mandates in France.
- Disposable:Single-use paper cards dominate high-volume electronics and food packaging applications where cost minimization overrides sustainability considerations.
Color Changing sits at the top of the volume ranking, with Digital climbing the fastest.
End User:
Application-specific validation requirements create tiered pricing structures across regulated and non-regulated sectors.
- Pharmaceuticals:FDA stability testing mandates under Current Good Manufacturing Practice regulations institutionalize humidity monitoring for moisture-sensitive biologics. CDSCO packaging guidelines for export-oriented Indian generic drug production expand compliance-driven procurement.
- Electronics:MIL-STD-3010 specifications govern moisture documentation for mission-critical aerospace and defense components. Precision manufacturers demand tighter threshold tolerance windows than cobalt-free alternatives reliably deliver.
- Food Packaging:Moisture-sensitive specialty foods and dehydrated meal kits deploy indicator cards to verify barrier integrity during extended shelf-life storage.
- Museums:Climate-controlled artifact storage facilities utilize low-cost color-changing cards for routine environmental monitoring without digital infrastructure investment.
Pharmaceuticals commands the largest revenue share, though Electronics exhibits the steepest expansion trajectory as defense procurement specifications tighten.
Technology:
Raw material substitution costs concentrate margin pressure on reformulation chemistry capabilities.
- Chemical:Cobalt chloride and copper halide indicator systems dominate legacy installed bases. EPA Section 313 toxic substance reporting rules accelerate phase-out timelines for cobalt-containing formulations in US government contracts.
- Polymer:Advanced moisture-sensitive coatings enable reversible color transitions and extended calibration stability. Specialty coating capacity concentrates among limited North American and European precision impregnation houses.
- Electrochemical:Sensor-based architectures integrate with IoT cold-chain platforms for continuous data logging in automated warehouse environments.
- Microbial:Experimental biologically-derived indicators remain confined to research applications pending validation for pharmaceutical packaging acceptability.
Chemical technology retains dominant volume position, while Polymer formulations gain share fastest as reversible substrates penetrate circular economy mandates.
Distribution Channel:
Channel consolidation by pharmaceutical distributors compresses supplier margins while fragmenting procurement relationships.
- Distributors:Traditional packaging supply intermediaries face margin compression from stranded cobalt chloride inventory as customer specifications shift. Large 3PL operators unbundle humidity monitoring from broader packaging service portfolios.
- Direct Sales:Generic drug manufacturers establish direct procurement relationships with indicator card producers to secure extended validation documentation and volume pricing.
- Online:E-commerce platforms serve small-batch electronics manufacturers and museum facilities with standardized off-the-shelf indicator specifications.
- Retail:Limited penetration through industrial supply stores targets maintenance and repair operations with immediate-need procurement patterns.
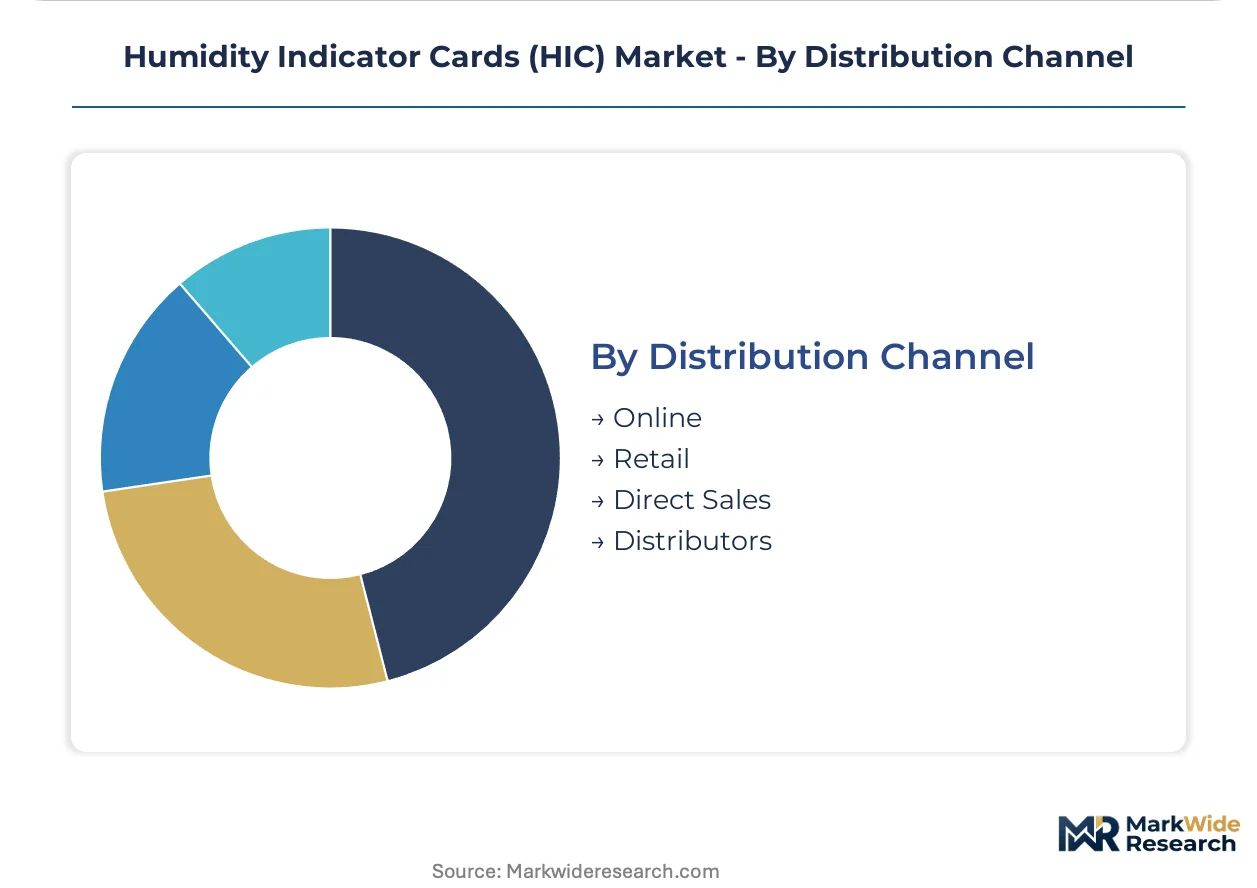
Distributors maintain volume leadership, with Direct Sales expanding most quickly as pharmaceutical procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States precision electronics manufacturing and defense supply chains anchor global demand for humidity indicator cards, with pharmaceutical cold-chain logistics expanding adoption across Germany, Switzerland, India, and Japan.
United States
FDA stability testing mandates under Current Good Manufacturing Practice regulations institutionalize humidity monitoring for moisture-sensitive biologics. EPA Section 313 toxic substance reporting rules accelerate cobalt chloride phase-outs in government contracts. Boston-Cambridge biologics clusters and Silicon Valley electronics fabs drive specification tightening for threshold accuracy.
Germany
REACH chemical safety documentation requirements reshape indicator card portfolios for EU pharmaceutical supply chains. ECHA substance restrictions compel reformulation investments ahead of North American timelines. Stuttgart precision electronics manufacturers and Frankfurt pharmaceutical 3PL operators pilot hybrid visual-digital monitoring architectures.
Switzerland
Swissmedic packaging validation guidelines for high-value biologics institutionalize stringent moisture control protocols. Automated pharmaceutical distribution centers in Basel and Zurich integrate NFC-enabled indicator cards with warehouse management systems. Geneva-based generics exporters align procurement with CDSCO requirements for Indian market access.
India
CDSCO packaging guidelines for export-oriented drug production create compliance-driven HIC demand from domestic API manufacturers. Hyderabad and Ahmedabad generic drug clusters upgrade moisture control infrastructure for EU and US market access. Maharashtra pharmaceutical exporters absorb cobalt-free chemistry cost premiums to maintain contract manufacturing relationships.
Japan
PMDA stability testing requirements for moisture-sensitive drug packaging tighten humidity control mandates across domestic distribution networks. METI industrial standards for precision electronics manufacturing institutionalize MIL-STD-3010 equivalent protocols. Osaka-Kobe pharmaceutical manufacturing corridors and Nagoya aerospace clusters concentrate specification development.
Humidity Indicator Cards (HIC) Market Competitive Landscape
Global majors compete with regional champions across reformulation chemistry capabilities and specialty coating capacity. The vendor base concentrates among North American and European precision impregnation houses with limited qualified alternatives. Three archetypes dominate: diversified materials science conglomerates, specialty chemical coating specialists, and geographic-proximity packaging suppliers. Competitive moves center on cobalt-free chemistry qualification and direct procurement relationships with pharmaceutical manufacturers.
Within the materials science tier, 3M Company exemplifies diversified conglomerate positioning through heritage coating technologies. Clariant International Ltd. represents specialty chemical expertise anchored in humidity-sensitive formulation capabilities. AGM Container occupies geographic-proximity positioning for North American aerospace and defense contractor access.
| Leading Market Players |
|---|
| 3M Company |
| Clariant International Ltd. |
| Desiccare Inc. |
| AGM Container |
| IMPAK Corporation |
| Advantek |
| Telatemp |
| Sanner GmbH |
| Desco |
| Others |
Value Network & Pricing Analysis
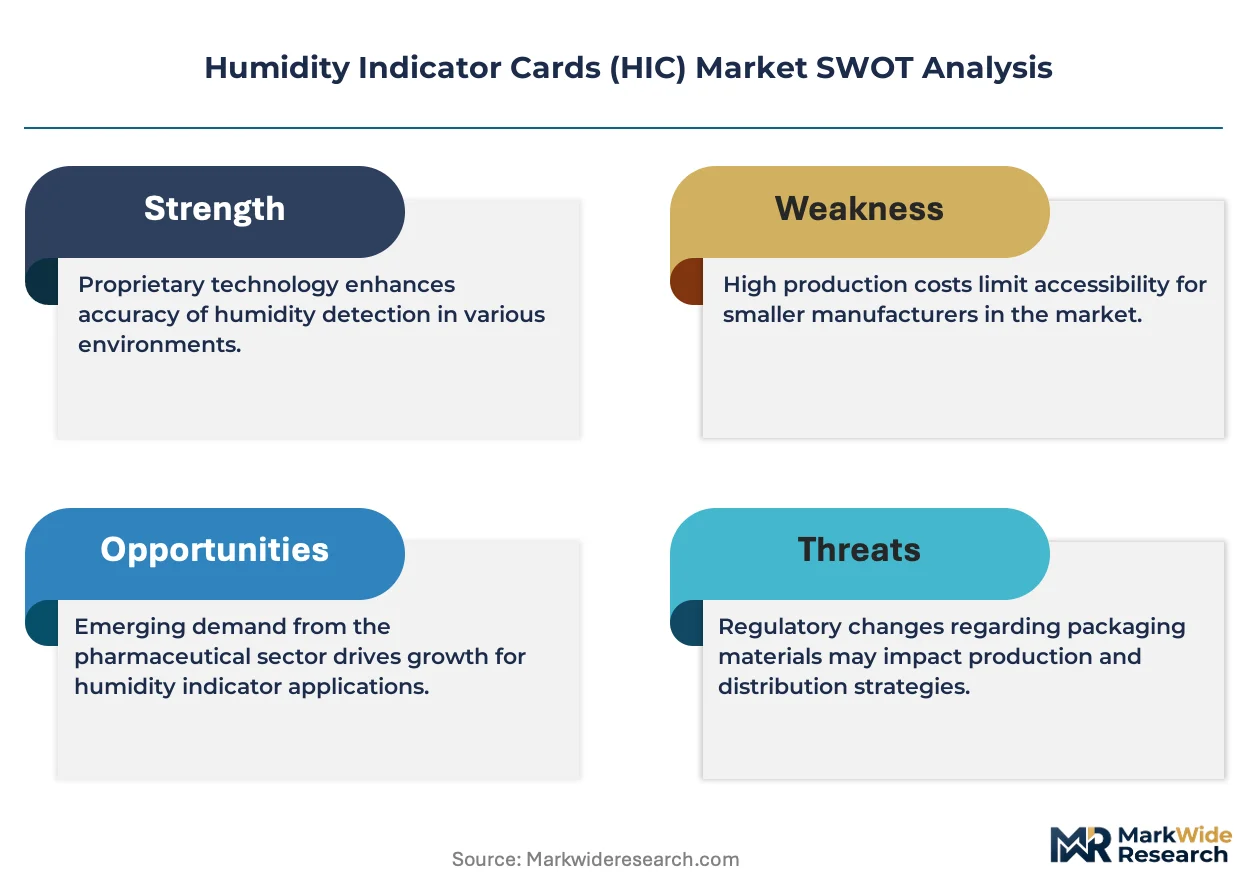
Cobalt-free chemistry reformulation simultaneously elevates raw material costs and concentrates production capacity among North American and European coating houses with precision impregnation expertise. This dual compression reshapes pricing power dynamics as buyers absorb reformulation premiums while suppliers compete on threshold accuracy capabilities.
Pricing Analysis
Input-cost pass-through from cobalt chloride substitution drives three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA validation documentation and MIL-STD-3010 certification tier, with pharmaceutical-grade cards commanding substantial premiums over electronics applications. Pricing pressure stems from consolidated pharmaceutical distributor procurement squeezing supplier margins. Generic drug manufacturers exhibit highest price sensitivity, while defense contractors prioritize threshold reliability over unit cost.
Supply Chain Analysis
Workforce availability for colorimetric calibration chemists constrains expansion in Massachusetts, Bavaria, and Basel precision coating clusters. Specialty coating capacity draws from Germany, the United States, and Switzerland, with raw material dependencies spanning copper halide compounds, moisture-sensitive polymer substrates, and NFC chip components. Single-source vulnerability concentrates among qualified reformulation chemists. Distribution runs through pharmaceutical 3PL operators and direct procurement relationships with generic drug manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Humidity Indicator Cards market functions as a regulatory compounder where EPA Section 313 toxic substance reporting milestones and FDA stability testing mandates continuously tighten compliance thresholds and expand monitoring point requirements.
For Market Incumbents: Anticipate accelerated cobalt-free qualification timelines by securing ECHA substance restriction documentation ahead of customer mandates. Invest in backward integration into specialty polymer substrate production to capture margin from coating capacity scarcity. Defend against digital sensor substitution by embedding NFC capabilities into visual-indicator substrates for hybrid architectures.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical-grade HICs creates entry opportunity for mid-tier suppliers with CDSCO validation capabilities. Target export-oriented Indian generic drug manufacturers upgrading moisture control infrastructure for EU market access. Pursue geographic proximity positioning to Maharashtra and Gujarat pharmaceutical clusters with localized coating operations.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional coating specialists with cobalt-free chemistry portfolios and dormant FDA master files. Long-term viability hinges on qualification runway for reversible polymer substrates under circular economy mandates. Monitor ECHA substance restriction timeline acceleration as inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Cobalt-Free Chemistry Qualification | EPA Section 313 compliance secures eligibility for US government contract procurement. |
| NFC-Enabled Substrate Development | Swissmedic validation requirements drive hybrid visual-digital monitoring adoption in Basel. |
| Backward Integration into Polymer Production | Captive substrate supply insulates margin from specialty coating capacity concentration. |
| Direct Procurement Relationship Building | Bypassing distributor intermediaries captures margin from pharmaceutical procurement consolidation. |
| CDSCO Validation Investment | Hyderabad and Ahmedabad generic drug clusters demand compliant moisture control infrastructure. |
Research Methodology
Direct dialogue with pharmaceutical packaging engineers, regulatory affairs specialists at FDA-registered facilities, precision electronics procurement managers, and specialty coating house operations directors grounded qualitative insights. Secondary validation drew from EPA Section 313 filings, ECHA substance restriction databases, FDA Current Good Manufacturing Practice guidance documents, and MIL-STD-3010 specifications. Bottom-up demand modeling across pharmaceutical, electronics, and defense end-uses triangulated with top-down market sizing from coating capacity assessments.
Bottom-up segmentation analysis modeled product type, end-user industry, technology chemistry, and distribution channel dynamics across the projection horizon. CAGRs derived from regression analysis against pharmaceutical cold-chain expansion rates and defense procurement specification adoption curves. Forecast inputs incorporated cobalt chloride phase-out timelines, REACH chemical safety documentation requirements, and IoT cold-chain integration penetration assumptions.
Caveats apply where EPA toxic substance reporting threshold revisions or FDA stability testing guideline updates could materially shift the outlook. Forecasts reflect assumptions around reformulation chemistry qualification timelines and specialty coating capacity expansion rates. Material deviation in ECHA substance restriction acceleration or digital sensor substitution velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Global Bowie Dick Test Pack Market
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Global Package Testing Market
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Packaging Testing Market
Packaging Testing
North America Package Testing Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Bottle Perpendicularity Tester Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Pack Testing Machines Market