
 Kuwait Container Glass Market | 2026-2036
Kuwait Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Container Glass Market Insights
Modular sizing of pharmaceutical and cosmetic containers is broadening procurement flexibility for Kuwaiti brand owners. Kuwait Glass Company leverages vertical integration from silica sourcing to finished vial output, sustaining cost advantages across prescription drug contracts. Gulf Glass Manufacturing Co. anchors its position in food-grade bottle supply for dairy and beverage processors. Al-Ahlia Glass Manufacturing Co. differentiates through handcrafted specialty designs targeting premium cosmetic houses in Salmiya and Kuwait City retail corridors.
Container glass denotes chemically inert packaging formed from silica sand, soda ash, and limestone melted above 1500°C, then shaped by blow-molding or press-forming into hollow vessels with wall thickness typically 3-8 mm, engineered to preserve product integrity against oxygen ingress and UV degradation. Bottles dominate volume throughput due to entrenched dairy and soft-drink filling infrastructure across Kuwait's Agro-Food sector. Jars capture expanding margin pools in halal-certified cosmetic creams and pharmaceutical ointments. Blow-molding technology leads unit economics for standardized pharmaceutical vials, while press-forming retains niche premium positioning in heavier cosmetic and household configurations.
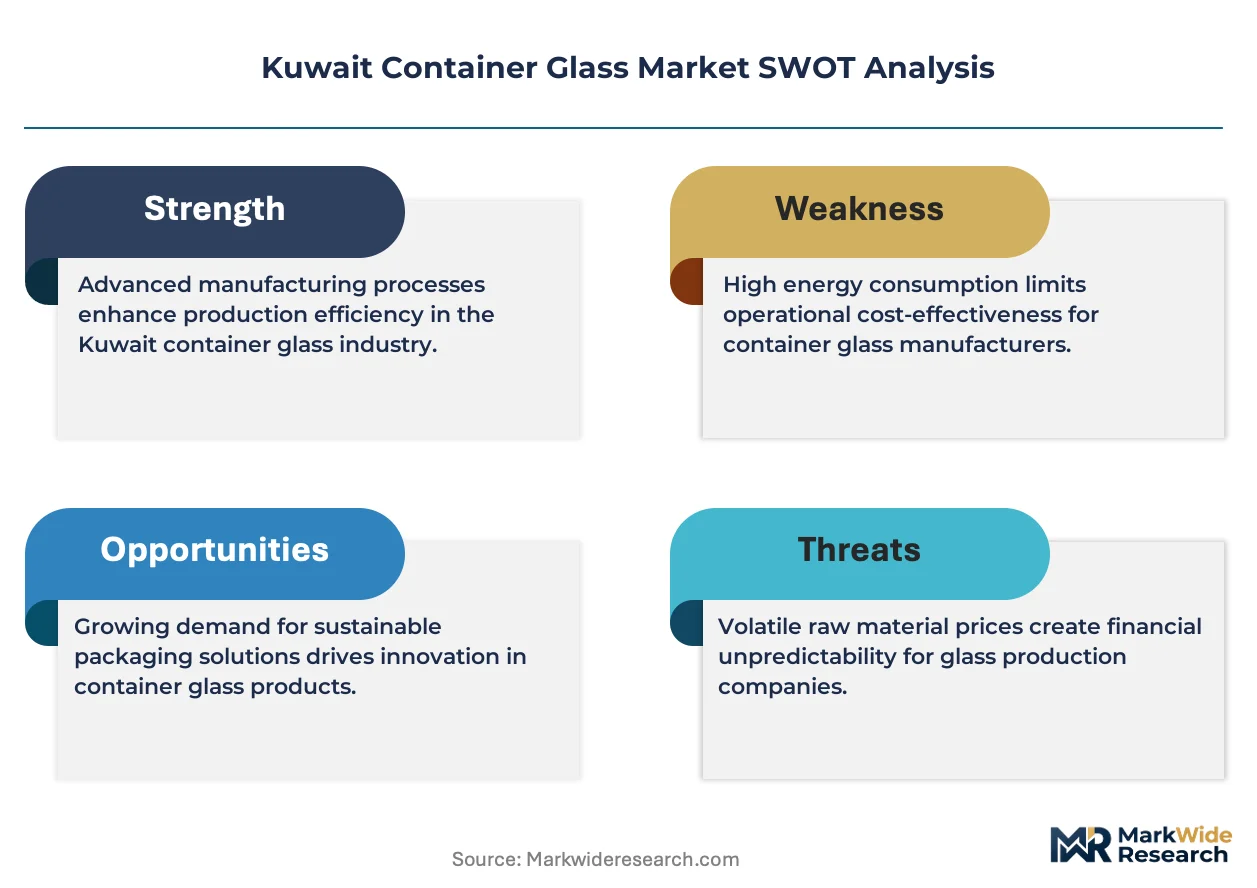
Kuwait's Environment Public Authority enforces post-consumer glass recovery mandates under integrated waste management frameworks, while the Public Authority for Industry administers KOSHA-aligned manufacturing safety standards and quality certification for food-contact materials. These dual compliance layers elevate capital requirements for new entrants and incentivize incumbent investment in cullet preprocessing and emissions control systems. Stakeholders must monitor regulatory calibration between circular-economy targets and energy-intensive melting constraints to align capacity planning with enforceable operating permits.
Market Dynamics
Kuwait's Environment Public Authority mandates on post-consumer glass recovery are compressing operational margins while simultaneously locking in incumbent capacity advantages through elevated compliance capital requirements.
Growth Catalysts
- Pharmaceutical packaging expansion:Prescription drug vial demand from Kuwait's expanding healthcare infrastructure is pulling dedicated pharmaceutical-grade melting capacity online at Shuaiba Industrial Area facilities.
- KOSHA-aligned manufacturing standards:The Public Authority for Industry's enforcement of workplace safety and food-contact quality certifications is filtering out subscale competitors and concentrating volume among certified producers.
- Cullet preprocessing investment:Advanced optical sorting and washing systems are lowering effective raw material costs for integrated operators with captive recycling streams.
Market Restraints
- Natural gas price volatility:Melting furnaces consume substantial energy inputs, and feedstock cost swings directly compress unit economics for non-integrated producers lacking long-term fuel supply agreements.
- Import dependency for high-purity silica:Domestic silica sand deposits require supplemental beneficiation, creating supply concentration risk tied to maritime freight corridors from regional bulk terminals.
- Polymer substitution in lightweight applications:PET and HDPE bottles are capturing share in non-barrier-sensitive beverage categories where weight-based logistics savings outweigh glass's oxygen-blocking advantages.
Strategic Opportunities
- Halal-certified cosmetic packaging:Premium skincare and fragrance houses in Salmiya retail corridors are sourcing decorated glass jars with certified supply chain documentation, opening margin pools above commodity food-grade pricing.
- Integrated waste management framework expansion:The Environment Public Authority's planned deposit-return scheme for beverage containers would structurally increase cullet availability and lower raw material input costs for participating recyclers.
- Press-forming technology for household chemicals:Heavier-walled containers for cleaning products and industrial solvents represent an underpenetrated application where glass's chemical inertness commands durable specification locks.
Industry Challenges
- Furnace rebuild cycle compression:Refractory-lined melting vessels require decade-interval cold repairs, and scheduling downtime without disrupting pharmaceutical contract deliveries demands sophisticated production planning.
- Food-contact certification timelines:Migration testing and regulatory approval for new colorant formulations or surface treatments can extend twelve to eighteen months, delaying product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Container Glass Market |
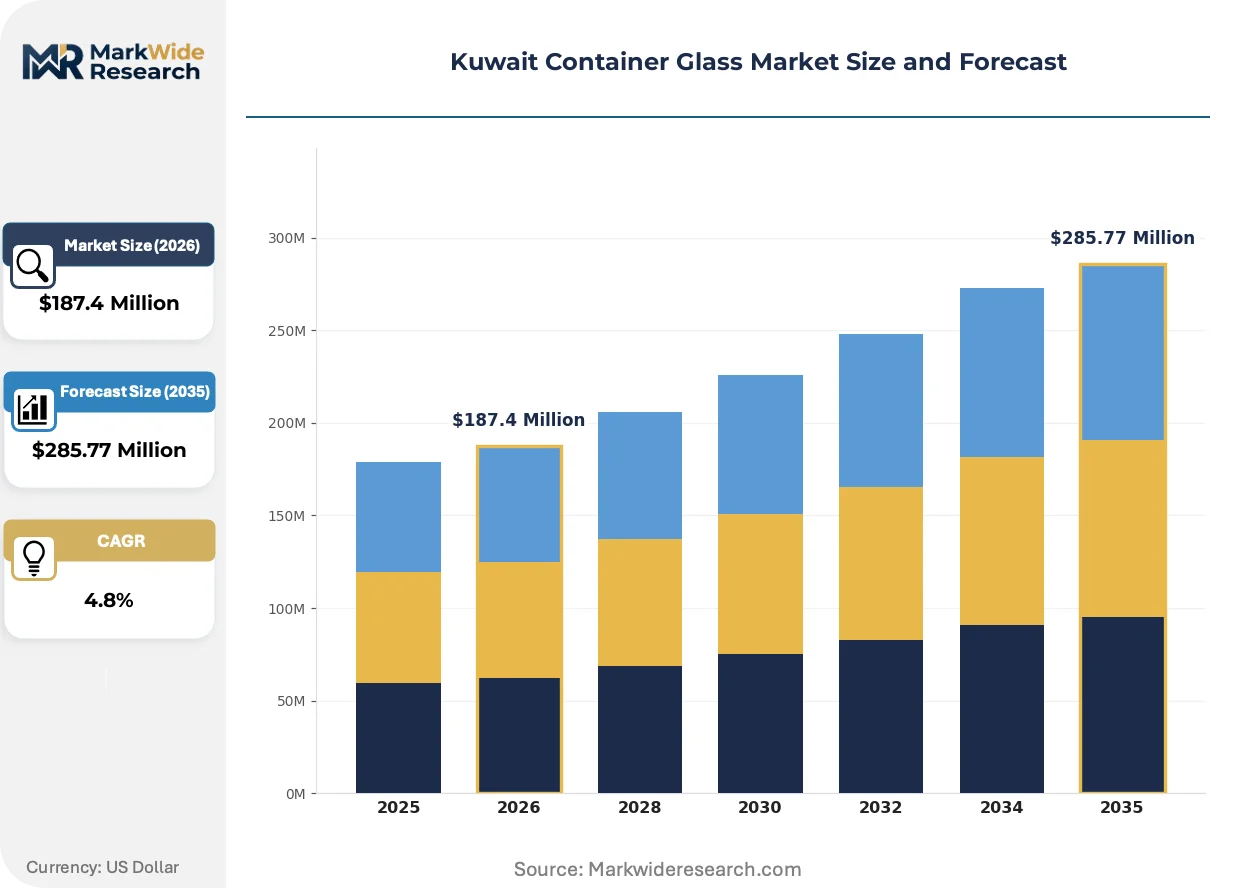
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Material: Recycled Glass, Float Glass, Specialty Glass, High-Temperature Glass Technology: Blow-Molding, Press-Forming, Automatic Production, Handcrafted |
| Companies Covered | Feemio Group Co., Ltd., Kuwait Glass Company, Gulf Glass Manufacturing Co., Al Khorayef Group, Al-Ahlia Glass Manufacturing Co., Mexim Company W.L.L., Pragati Glass Pvt. Ltd., Al-Fahad Glass Factory, Coming Century Company WLL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Container Glass Market Trends and Innovations
Container glass production in Kuwait is pivoting toward modular furnace configurations and digital quality systems that accommodate shorter pharmaceutical production runs without sacrificing melting efficiency.
Electrical boosting and oxy-fuel combustion retrofits are modularizing furnace operations across Shuaiba Industrial Area facilities. Pharmaceutical contract manufacturers are specifying these upgraded lines for vial production requiring tighter thermal uniformity. The technology is modularizing batch size flexibility, enabling economical production runs below traditional minimum efficient scale thresholds.
Kuwait's Environment Public Authority is tightening integrated waste management enforcement with mandatory post-consumer recovery targets for packaging producers. Glass container manufacturers face direct accountability for end-of-life material flows under extended producer responsibility frameworks. Food-grade bottle suppliers are responding by embedding closed-loop cullet systems within their Shuaiba operations to demonstrate compliance.
Brand owners in dairy and beverage categories are consolidating procurement around fewer suppliers with demonstrated KOSHA certification and Environment Public Authority waste compliance records. This concentration is displacing fragmented spot-market purchasing that historically characterized smaller Agro-Food processors. The shift is most visible among Kuwait's integrated dairy cooperatives, which now require documented chain-of-custody from silica sourcing through finished container delivery.
Kuwait Container Glass Market Segmentation
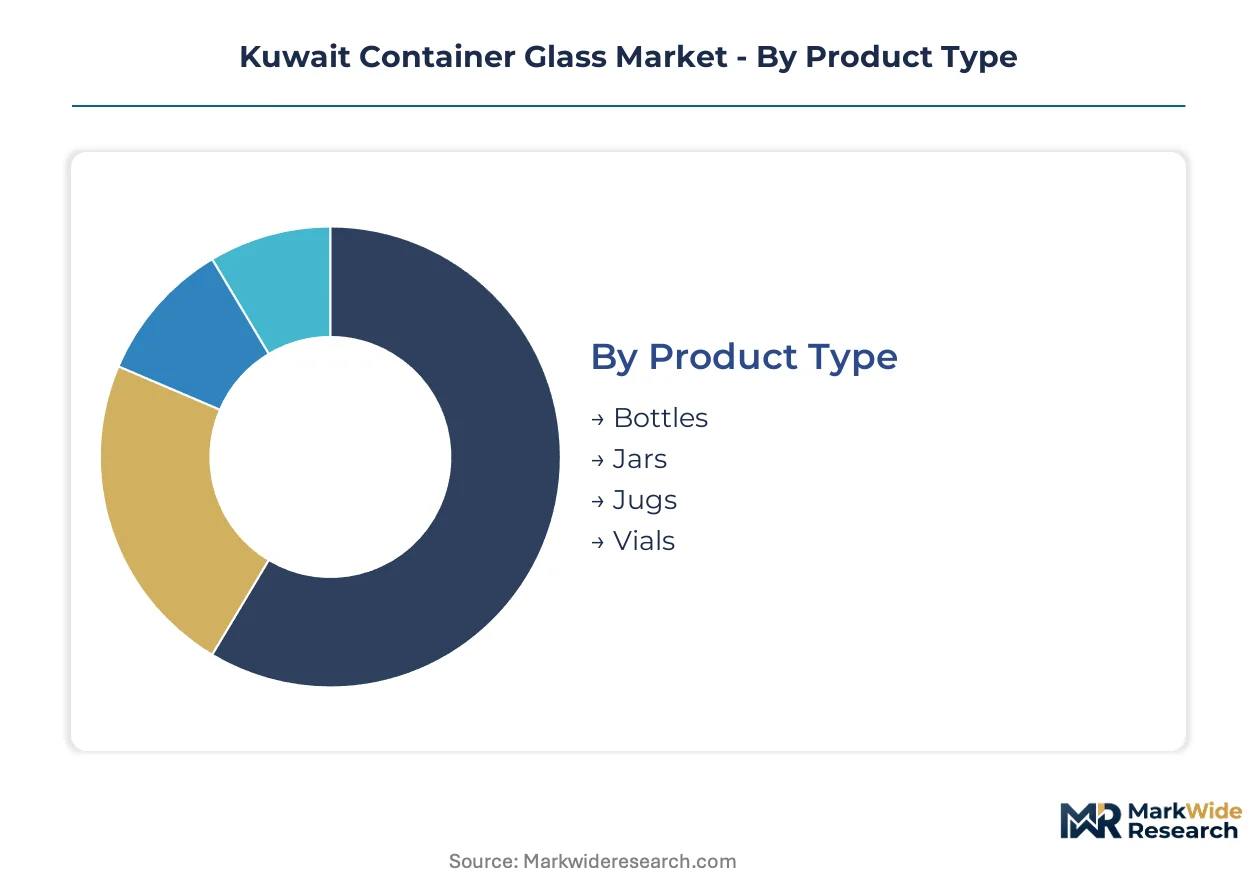
Segmentation in Kuwait's container glass market reveals how furnace technology and compliance requirements reshape procurement patterns across distinct product categories. Understanding these divisions helps stakeholders align capacity investments with specific end-use certification demands.
Product Type:
Replacement cycles for filling line equipment drive differential demand patterns across container formats, with dairy and beverage infrastructure favoring standardized geometries while pharmaceutical lines accommodate modular vial sizing.
- Bottles:Cylindrical or shaped hollow vessels with 3-8 mm wall thickness, engineered for oxygen and UV barrier protection. Agro-Food processors across Kuwait's dairy cooperatives specify these for pasteurized milk and soft-drink filling lines, where entrenched conveyor infrastructure locks in procurement volumes.
- Jars:Wide-mouth containers with threaded or lug finishes, optimized for viscous product access. Halal-certified cosmetic cream manufacturers in Salmiya retail corridors source decorated jar formats, commanding margin premiums above commodity food-grade pricing through certified supply chain documentation.
- Jugs:Large-format vessels with handle attachments for household-scale liquid dispensing. Domestic water and cooking oil distributors favor these for direct-to-consumer refill programs.
- Vials:Small-diameter pharmaceutical containers with precise neck finishes for rubber stopper and aluminum crimp seals. Prescription drug contract manufacturers at Shuaiba Industrial Area pull dedicated pharmaceutical-grade melting capacity for these formats.
Bottles sit at the top of the volume ranking, with vials climbing the fastest.
End User:
Customer concentration around integrated industrial zones creates distinct margin tiers, with pharmaceutical and cosmetic buyers demanding documentation depth that food processors rarely require.
- Food & Beverage:Dairy cooperatives and soft-drink bottlers constitute the foundational demand base. These buyers prioritize KOSHA certification and Environment Public Authority waste compliance records over decorative specifications.
- Cosmetics:Premium skincare and fragrance houses in Kuwait City and Salmiya retail corridors. Handcrafted specialty designs with halal-certified supply chains open margin pools above standard pricing tiers.
- Pharmaceuticals:Prescription drug manufacturers requiring chemically inert packaging with documented migration testing. Extended certification timelines for new colorant formulations filter supplier pools to established incumbents.
- Household:Cleaning product and industrial solvent distributors. Heavier-walled press-formed containers represent underpenetrated applications where chemical inertness commands durable specification locks.
Food & Beverage anchors absolute volume, though Pharmaceuticals delivers the steepest expansion trajectory.
Material:
Raw material sourcing strategies differentiate integrated operators from merchant buyers, with captive cullet streams lowering effective input costs under tightening recovery mandates.
- Recycled Glass:Post-consumer cullet processed through optical sorting and washing systems. Environment Public Authority recovery mandates elevate this feedstock's strategic importance for compliance demonstration.
- Float Glass:High-clarity sheet glass adapted through secondary forming for premium cosmetic applications. Limited local production creates import dependency for specialized grades.
- Specialty Glass:Borosilicate and other chemically resistant formulations. Pharmaceutical vial specifications require these materials for thermal shock resistance and low extractable profiles.
- High-Temperature Glass:Alumina-silicate compositions for industrial solvent containment. Niche applications in cleaning product distribution favor this material's durability.
Recycled Glass dominates input volumes, with Specialty Glass gaining share fastest on pharmaceutical contract expansion.
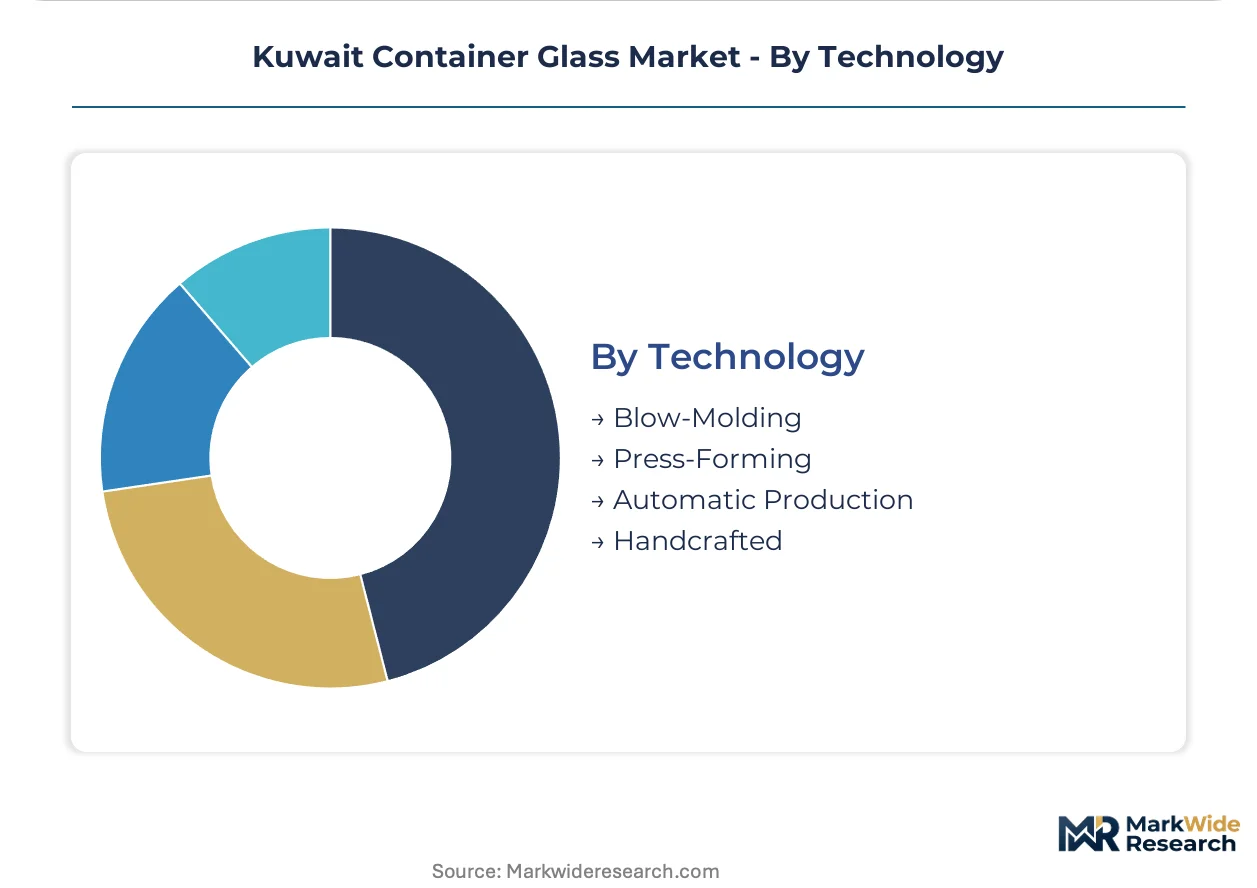
Technology:
Equipment selection locks in production economics and batch size flexibility, with modular furnace configurations now accommodating shorter pharmaceutical runs without sacrificing melting efficiency.
- Blow-Molding:Compressed air expansion of molten glass parisons within metal molds. Standardized pharmaceutical vial production leverages this method for unit economic advantages at scale.
- Press-Forming:Mechanical pressing of glass gobs between mold halves. Heavier cosmetic and household configurations retain premium positioning through this technology's thicker wall capabilities.
- Automatic Production:Continuous IS machine operation with robotic handling. Shuaiba Industrial Area facilities deploy these lines for dairy and beverage bottle throughput.
- Handcrafted:Manual gathering and shaping for limited decorative editions. Al-Ahlia Glass Manufacturing Co. differentiates through this approach for premium cosmetic houses.
Automatic Production leads absolute output, while Blow-Molding expands most quickly on pharmaceutical packaging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container glass production in Kuwait traces its industrial lineage to the 1960s oil-era infrastructure buildout, when state-led industrialization established Shuaiba as the primary manufacturing corridor. Today, domestic capacity serves Gulf Cooperation Council markets while navigating energy cost pressures and import competition from regional suppliers.
Saudi Arabia
Pharmaceutical packaging demand from Riyadh's expanding healthcare infrastructure pulls specialized container imports from Kuwaiti suppliers. The Saudi Food and Drug Authority enforces stringent migration testing standards for food-contact materials, elevating compliance requirements for cross-border shipments. Jeddah's Red Sea industrial zone hosts competing glass melting capacity that pressures Kuwaiti exporters on freight-adjusted pricing.
United Arab Emirates
Dubai's premium cosmetics retail sector sources decorated glass jars with halal-certified supply chain documentation, opening margin opportunities for Kuwaiti specialty producers. The Emirates Authority for Standardization and Metrology administers product safety certifications that Kuwaiti exporters must obtain for market access. Sharjah's Hamriyah Free Zone concentrates competing container glass capacity that vies for Gulf market share.
Qatar
Liquefied natural gas revenues fund healthcare infrastructure expansion in Doha, generating pharmaceutical vial demand that Kuwaiti suppliers partially serve. The Ministry of Public Health regulates medical device packaging standards, including glass primary containers for sterile formulations. Ras Laffan Industrial City's energy-intensive industries cluster creates regional competition for natural gas feedstock access.
Bahrain
Aluminum smelting and downstream fabrication dominate Bahrain's industrial base, leaving container glass as a net import category served by regional suppliers including Kuwait. The Bahrain Standards and Metrology Directorate enforces Gulf Technical Regulation conformity for packaging materials. Sitra's industrial area lacks indigenous glass melting capacity, creating dependency on cross-Gulf supply chains.
Iraq
Reconstruction-driven demand for food-grade packaging in Baghdad and Basra presents long-term market development potential for Kuwaiti producers with logistics proximity. The Central Organization for Standardization and Quality Control maintains evolving import standards that regional exporters must navigate. Basra's port infrastructure limitations currently constrain reliable containerized glass shipments from Kuwaiti manufacturing bases.
Kuwait Container Glass Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and furnace technology tiers, with pharmaceutical-grade melting capacity commanding structural advantages over standard food-grade operations. The vendor base clusters around three archetypes: integrated silica-to-container operators with captive recycling streams, specialized cosmetic jar fabricators emphasizing decorative craftsmanship, and regional trading houses sourcing standardized bottles from low-cost origins. Dominant competitive moves include backward integration into cullet preprocessing assets and strategic positioning for Environment Public Authority compliance documentation.
Among Kuwait-based manufacturers, Kuwait Glass Company and Gulf Glass Manufacturing Co. represent the integrated production archetype with Shuaiba Industrial Area presence, while Al-Ahlia Glass Manufacturing Co. occupies a position within specialty decorative fabrication for premium cosmetic applications. Feemio Group Co., Ltd. anchors the import-supply tier serving standardized volume requirements. These named entities exemplify how competitive positioning stratifies across certification capability, furnace scale, and end-use specialization rather than geographic coverage alone.
| Leading Market Players |
|---|
| Feemio Group Co., Ltd. |
| Kuwait Glass Company |
| Gulf Glass Manufacturing Co. |
| Al Khorayef Group |
| Al-Ahlia Glass Manufacturing Co. |
| Mexim Company W.L.L. |
| Pragati Glass Pvt. Ltd. |
| Al-Fahad Glass Factory |
| Coming Century Company WLL |
| Others |
Pricing and Supply Chain Analysis
Skilled furnace operators concentrated in Shuaiba Industrial Area command wage premiums that compress margins at commodity-grade producers while widening spreads between pharmaceutical-certified and standard food-grade container tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Kuwait's container glass procurement. Price differentiation centers on KOSHA certification grade and Environment Public Authority compliance documentation depth. Pricing pressure stems from natural gas cost volatility feeding into melting furnace economics. Food & Beverage processors exhibit highest price sensitivity, while pharmaceutical contract manufacturers absorb premiums for migration-tested vial supply.
Supply Chain Analysis
Workforce availability constraints in Shuaiba Industrial Area and adjacent manufacturing zones tether production scheduling to skilled labor pools. Supply concentrates in Kuwait, Saudi Arabia, and United Arab Emirates for regional pharmaceutical and cosmetic demand. Raw material dependencies include high-purity silica from maritime bulk terminals, soda ash imports, and post-consumer cullet streams. Single-source vulnerability runs through maritime freight corridors for silica beneficiation. Distribution runs through integrated dairy cooperatives and pharmaceutical contract manufacturers with documented chain-of-custody requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's container glass market represents a late-cycle quality story as pharmaceutical packaging specifications tighten and halal-certified cosmetic demand shifts toward premium decorated formats.
For Market Incumbents: To counter polymer substitution in lightweight beverage applications, Kuwait Glass Company and Gulf Glass Manufacturing Co. should deepen captive cullet preprocessing assets and lock in long-term natural gas supply agreements. Backward integration into optical sorting systems preserves margin position against import competition from Sharjah's Hamriyah Free Zone. For New Entrants and Emerging Players: Environment Public Authority's planned deposit-return scheme in Kuwait opens a window for specialized cullet collection and preprocessing ventures. Household chemicals packaging presents the most penetrable white-space segment, with press-formed heavier-walled containers for cleaning products offering specification locks through chemical inertness advantages. For Investors and Strategic Acquirers: Integrated industrial conglomerates with energy sector exposure are the most active acquirer in this space, seeking captive packaging supply for downstream chemical and food operations. Targets with pharmaceutical-grade melting capacity and Environment Public Authority compliance documentation offer superior long-term viability. Watch for calibration between circular-economy recovery mandates and furnace energy intensity as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cullet Preprocessing Investment | Advanced optical sorting at Shuaiba facilities satisfies Environment Public Authority recovery mandates while lowering silica input costs. |
| Pharmaceutical-Grade Melting Capacity | Dedicated furnace lines with electrical boosting serve prescription drug vial contracts requiring tighter thermal uniformity specifications. |
| Halal Certification Integration | Documented supply chain credentials unlock premium cosmetic jar demand from Salmiya retail corridor skincare houses. |
| Natural Gas Supply Hedging | Long-term fuel agreements insulate melting economics against regional LNG price volatility affecting unit costs. |
| Press-Forming Technology Deployment | Heavier-walled container capabilities target underpenetrated household chemicals segment with durable specification locks. |
Research Methodology
Bottom-up pharmaceutical and cosmetic packaging modeling reconciled against top-down furnace capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Shuaiba Industrial Area facilities, procurement leads at Kuwaiti dairy cooperatives, regulatory affairs specialists at the Public Authority for Industry, and pharmaceutical contract manufacturing executives combined with secondary validation from Environment Public Authority waste management filings, KOSHA certification databases, and Gulf Cooperation Council customs records. Triangulation against installed melting capacity and cullet recovery rates cross-checks demand-side estimates.
Historical trendline analysis of pharmaceutical vial production runs and food-grade bottle throughput established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, end-user industry, material grade, and furnace technology dimensions. CAGRs were derived from capacity utilization trajectories and prescription drug packaging contract visibility. Forecast inputs included natural gas price scenarios and Environment Public Authority enforcement intensity for post-consumer recovery targets.
Revisions become necessary when Environment Public Authority regulatory calibration shifts, pharmaceutical migration testing timelines extend, or polymer substitution accelerates in non-barrier-sensitive beverage categories. Material deviation in these triggers warrants pause and re-evaluation of capacity expansion assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Wooden Crates Market
Containers
Global Multi Pack Carriers Market
Containers
Takeout Containers Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Thermoformed Containers Market
Containers
Thermoformed Shallow Trays Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Collapsible Sleeve Containers Market
Containers
Dispensing Jug Market
Containers
Global Food Containers Market
Containers
Snap-Lock Container Market
Containers
Injection Molding Containers Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Single Wall Jars Market
Containers
Thin Wall Plastic Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market