
 Jars Market | 2026-2036
Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Jars Market Outlook
European glass furnace operations is shifting toward oxy-fuel and electric melting technologies to curb carbon intensity in jar production. Ball Corporation leverages vertical integration from metal packaging into glass jar manufacturing to sustain supply chain control across North American beverage and food accounts. O-I Glass anchors its position through R&D intensity in lightweighting technologies, while Ardagh Group competes via geographic dominance across Western European packaging markets.
A jar is a rigid cylindrical container with a wide mouth and threaded neck, typically manufactured from soda-lime glass, polyethylene terephthalate, or tinplate steel, with wall thicknesses ranging from 2mm to 6mm depending on material and pressure requirements, designed primarily for hermetic food preservation, pharmaceutical storage, and consumer goods containment. Glass jars dominate premium food and pharmaceutical applications due to inertness and barrier properties, while plastic jars lead in mass-market household segments where cost and shatter resistance outweigh shelf aesthetics. Metal jars occupy niche positions in industrial and high-acid food categories where oxygen exclusion is critical.
The FDA enforces 21 CFR standards for food-contact glass and plastic jar safety, while the EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that reshape material sourcing decisions for jar producers. ISO 9001 and BRCGS certification frameworks govern quality assurance protocols for pharmaceutical and food-grade jar manufacturing facilities. Stakeholders must monitor evolving extended producer responsibility schemes and carbon border adjustments that will redefine competitive positioning in jar procurement across European and North American supply chains.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material transition timelines, forcing jar manufacturers to reconfigure furnace operations and recycled content sourcing before compliance deadlines crystallize.
Growth Catalysts
- EU recycled content mandates:The Packaging and Packaging Waste Regulation mandates minimum recycled glass thresholds, pulling capital into cullet processing infrastructure across Germany, France, and Italy.
- Pharmaceutical cold-chain expansion:Biologics storage requirements are amplifying demand for borosilicate glass jars with thermal shock resistance in temperature-controlled distribution networks.
- Oxy-fuel furnace conversion:Glass manufacturers are retrofitting melting operations to cut carbon intensity per ton, aligning jar production with EU Green Deal emission benchmarks.
Market Restraints
- Natural gas price volatility:Glass furnace operations remain tethered to natural gas feedstock, exposing margin structures to energy market swings across European production zones.
- Cullet supply concentration:High-quality recycled glass sourcing clusters in Germany and the Netherlands, creating bottleneck risk for jar producers outside these collection hubs.
- Plastic jar substitution in mass retail:Polypropylene and PET jars continue displacing glass in price-sensitive household segments where shelf aesthetics matter less than freight cost.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO regulatory alignment with ICH standards is opening export-grade glass jar demand for sterile formulations from domestic manufacturers.
- Smart packaging integration:Near-field communication tags and temperature-sensitive inks are converging with jar closures to enable supply chain traceability in premium food segments.
- Extended producer responsibility schemes:France's Citeo and Germany's Duales System are creating reverse-logistics revenue streams for jar producers who capture post-consumer material.
Industry Challenges
- Electric melting engineering talent:The shift from combustion to electric furnace architectures demands glass technologists with plasma and induction heating expertise that remains scarce in traditional manufacturing regions.
- BRCGS certification timelines:Food-grade jar facilities face 12-18 month audit cycles to achieve Grade A status, compressing speed-to-market for new production lines.
- Legacy mold inventory incompatibility:Lightweighting programs require complete die replacement, stranding capital in thick-wall jar tooling that cannot produce next-generation specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jars Market |
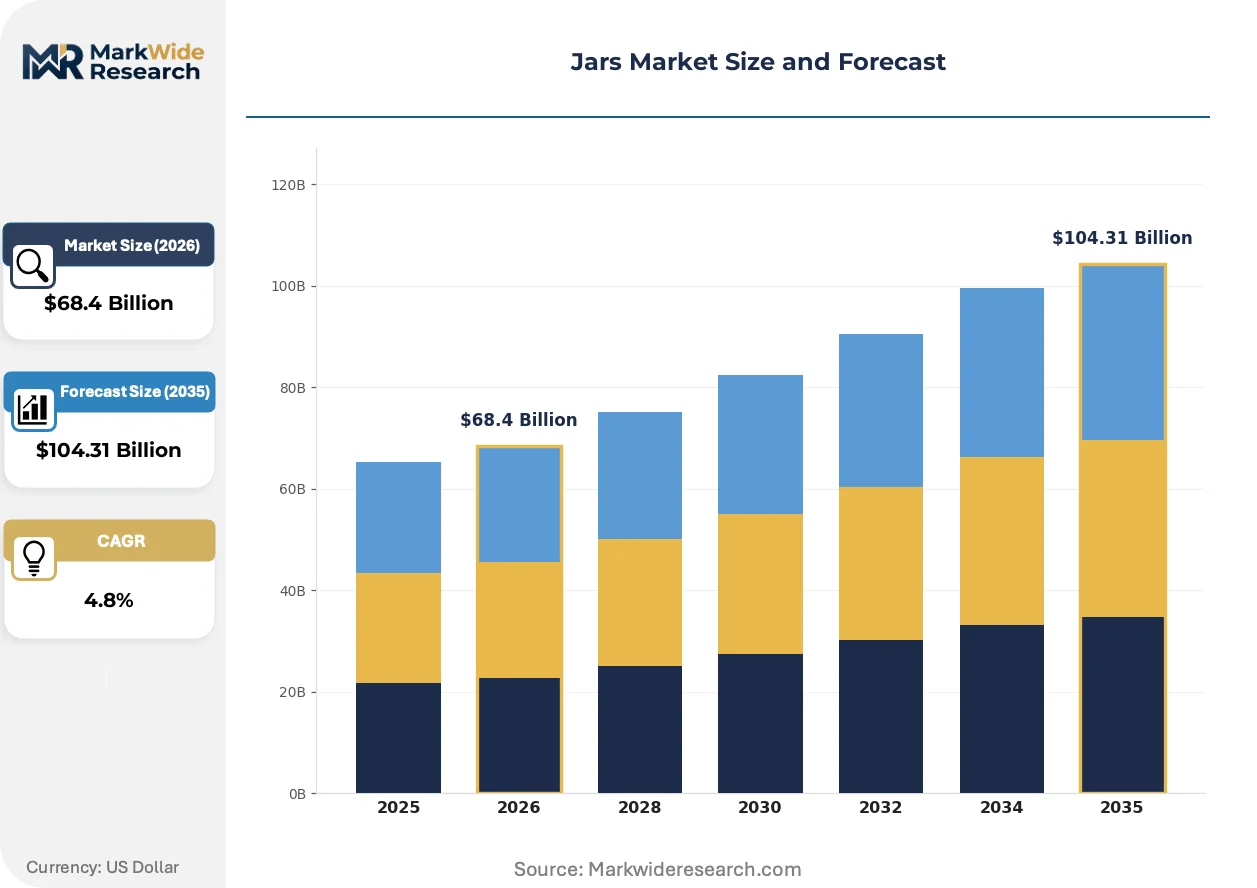
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Metal, Ceramic Capacity: 100ml, 250ml, 500ml, 1L End User: Households, Restaurants, Food Manufacturers, Pharmacies Closure Type: Screw Cap, Snap Lid, Rubber Seal, Metal Lid |
| Companies Covered | Ball Corporation, O-I Glass, Inc., Ardagh Group, Libbey, Anchor Hocking, Verallia, Saverglass, Heinz-Glas, Stölzle Glass Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jars Market Strategic Shifts
Active redesign of jar manufacturing is compressing energy intensity while embedding intelligence into packaging systems. Three developments are restructuring competitive capability requirements.
Thin-wall glass forming is unifying structural integrity with material reduction. Pharmaceutical and premium food packagers in Germany and Switzerland are adopting 2.2mm base specifications that cut silica consumption 15% without sacrificing stack strength. This technology is unifying sustainability metrics with logistics efficiency, collapsing the trade-off between carbon footprint and breakage rates that previously segmented glass jar tiers.
REACH restrictions on heavy metals in glass colorants are forcing reformulation of amber and cobalt jar stocks. Cadmium and lead elimination from UV-blocking additives has triggered R&D intensity in cerium and titanium oxide alternatives across European furnace operations. Cosmetic and pharmaceutical segments are absorbing higher pigment costs to maintain regulatory clearance for EU and Swissmedic markets.
Direct-to-brand procurement is consolidating buyer power among mid-sized food manufacturers. Regional specialty producers in Italy and Spain are bypassing distributor networks to negotiate volume commitments directly with Ardagh and O-I Glass facilities. This channel compression is visible most acutely in organic preserves and craft condiment verticals where lot traceability and custom mold access outweigh distributor service bundling.
Jars Market Segmentation
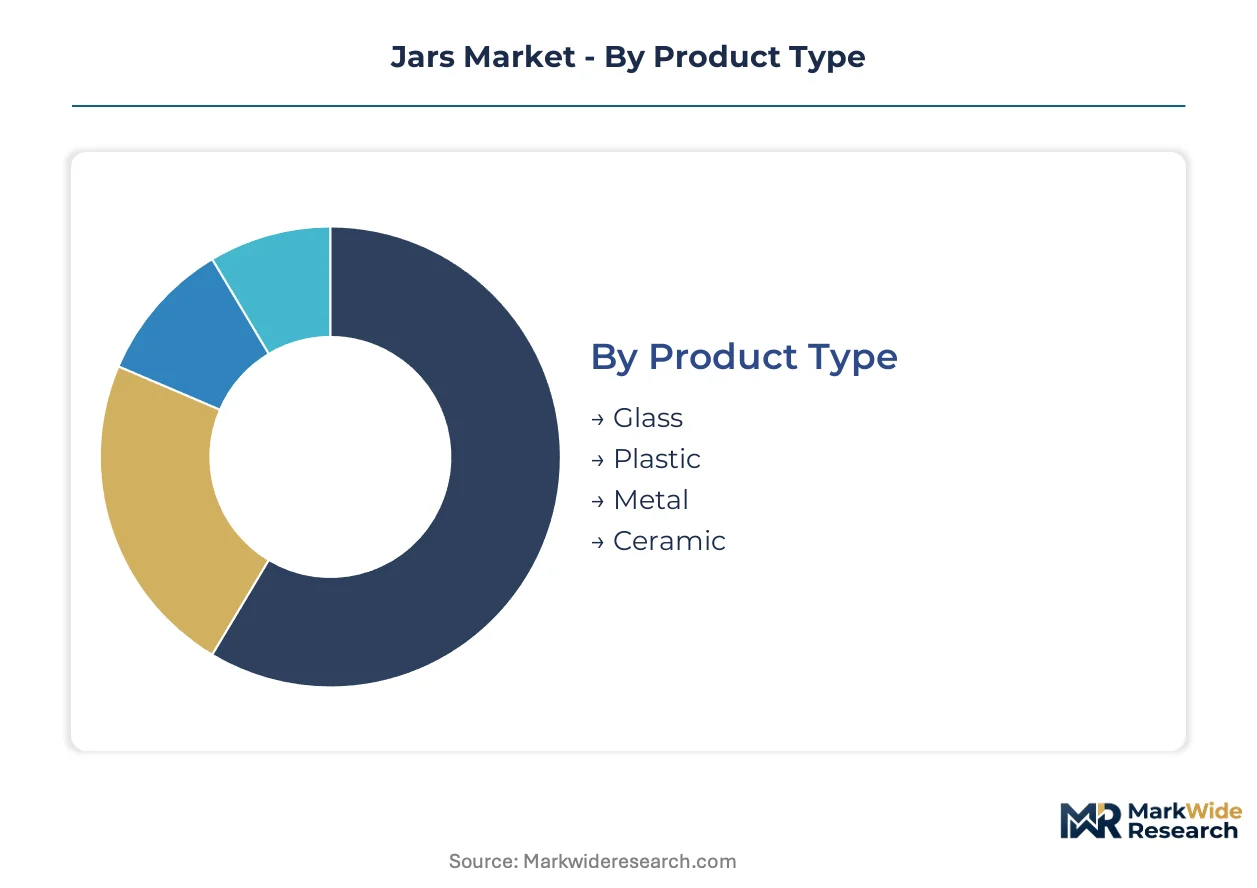
Jars manufacturers configure production lines around four intersecting dimensions that determine furnace specifications, mold investments, and customer targeting. Each segmentation axis carries distinct margin profiles and regulatory compliance burdens that reshape procurement negotiations across food, pharmaceutical, and household channels.
Product Type:
Upgrade cycles in jar manufacturing track material transitions driven by sustainability mandates and end-use performance requirements. Glass furnace retrofits and plastic resin reformulations are compressing replacement timelines as producers reposition for recycled content thresholds.
- Glass:Soda-lime and borosilicate compositions dominate premium food preservation and pharmaceutical storage where inertness and UV barrier properties are non-negotiable. German and French food processors are expanding glass jar procurement to meet EU Packaging and Packaging Waste Regulation mandates, pulling investment into oxy-fuel furnace conversions that cut carbon intensity per ton.
- Plastic:Polyethylene terephthalate and polypropylene variants lead mass-market household segments where freight cost and shatter resistance outweigh shelf aesthetics. PET jar demand is concentrating in North American big-box retail where lightweighting reduces per-unit logistics spend.
- Metal:Tinplate steel construction serves high-acid food categories and industrial applications requiring absolute oxygen exclusion. Metal jar procurement clusters in Italian tomato processing and Spanish olive packaging where hermetic integrity extends shelf life.
- Ceramic:Stoneware and porcelain formulations occupy artisan food and cosmetic niches where tactile differentiation commands premium positioning. Japanese and Korean cosmetic brands are driving specialized ceramic jar sourcing for K-beauty export lines.
Glass sits at the top of the volume ranking, with ceramic climbing the fastest as premium cosmetic brands seek material differentiation.
Capacity:
Volume tiering in jar procurement aligns with end-use consumption patterns and distribution economics, with smaller formats capturing pharmaceutical precision and larger formats optimizing food processing throughput.
- 100ml:Compact borosilicate glass specifications serve pharmaceutical single-dose and travel-size cosmetic applications. Swissmedic and EMA compliance requirements are concentrating 100ml glass jar demand in German and Swiss pharmaceutical packaging hubs.
- 250ml:Mid-range capacity dominates specialty food preserves and condiment positioning where portion control meets shelf presence. Italian organic preserves producers are standardizing on 250ml glass for direct-to-retail distribution.
- 500ml:Standard household format balancing kitchen storage efficiency with retail case pack economics. 500ml PET jars are displacing glass in North American mass-market peanut butter and spreads where cost sensitivity dominates.
- 1L:Bulk format capturing food service and institutional procurement where volume throughput reduces per-ounce packaging cost. German food manufacturers are expanding 1L glass lines for export-grade sauerkraut and pickled vegetable shipments.
500ml maintains the highest shipment volumes, with 100ml gaining share fastest as pharmaceutical cold-chain requirements multiply.
End User:
Customer-type segmentation reveals divergent procurement logics, from household price sensitivity to pharmaceutical regulatory stringency.
- Households:Mass retail consumers prioritize cost and convenience, driving PET and polypropylene jar dominance in supermarket channels. Private label expansion is compressing branded glass jar penetration in European household segments.
- Restaurants:Food service operators balance durability with back-of-house storage efficiency, favoring wide-mouth plastic and metal jars for ingredient access. Independent restaurant procurement is consolidating through broadline distributors.
- Food Manufacturers:Industrial processors specify jars around line speed compatibility and label adhesion properties. BRCGS certification requirements are extending supplier qualification timelines for food-grade jar facilities.
- Pharmacies:Pharmaceutical packagers demand borosilicate thermal shock resistance and USP compliance for sterile formulations. CDSCO alignment with ICH standards is opening Indian pharmaceutical jar export opportunities.
Food Manufacturers represent the largest procurement volume, with Pharmacies expanding most quickly on biologics storage requirements.
Closure Type:
Sealing mechanism selection determines hermetic integrity, consumer convenience, and regulatory compliance across food and pharmaceutical applications.
- Screw Cap:Threaded polypropylene or metal closures dominate reusable applications where consumer resealing is frequent. Child-resistant screw cap specifications are mandatory for pharmaceutical jar lines.
- Snap Lid:Press-fit plastic closures serve single-serve dairy and dessert applications where opening ease drives purchase intent. Snap lid jar demand concentrates in European fresh dairy segments.
- Rubber Seal:Compression gaskets in wire-bail or clamp closures enable vacuum preservation for artisan food producers. Rubber seal specifications face REACH scrutiny on nitrosamine content.
- Metal Lid:Tinplate or aluminum closures with plastisol linings secure high-acid foods and thermal-processed preserves. Metal lid sourcing is concentrating in Spanish and Portuguese cannery supply chains.
Screw Cap leads absolute volume, with Rubber Seal gaining fastest among premium artisan food channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specialized jar procurement through pharmaceutical and food processing clusters, while India scales pharmaceutical packaging capacity to meet export-grade demand under evolving regulatory alignment.
Germany
Food manufacturers in Baden-Württemberg and Bavaria are expanding glass jar adoption for premium preserves and sauerkraut exports. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that pull capital into cullet processing infrastructure. Oxy-fuel furnace conversions in the Rhine-Ruhr industrial corridor are cutting carbon intensity per ton of jar production.
United States
Mass-market retail channels are driving PET jar penetration in peanut butter and spreads segments where freight cost dominates procurement decisions. FDA 21 CFR standards govern food-contact safety requirements for glass and plastic jar imports. Ball Corporation leverages backward integration from metal packaging into glass manufacturing to sustain supply chain control across North American beverage accounts.
India
Domestic pharmaceutical packagers are scaling borosilicate glass jar output for sterile biologics formulations targeting export markets. CDSCO alignment with ICH standards is opening compliance pathways for EU and US pharmaceutical regulators. Gujarat and Maharashtra host expanding pharmaceutical packaging hubs where Grade A BRCGS certification timelines compress speed-to-market for new jar production lines.
France
Organic preserves producers in Provence-Alpes-Côte d'Azur are standardizing on 250ml glass formats for direct-to-retail distribution bypassing traditional distributor networks. Citeo extended producer responsibility schemes create reverse-logistics revenue streams for jar producers capturing post-consumer material. Verallia anchors furnace operations in the Champagne-Ardenne region serving wine and condiment packaging demand.
Italy
Tomato processing clusters in Emilia-Romagna and Campania concentrate metal jar procurement for high-acid food categories requiring absolute oxygen exclusion. Metal lid sourcing is consolidating through Spanish and Portuguese cannery supply chains feeding Italian processors. REACH restrictions on heavy metals in glass colorants are forcing reformulation of amber jar stocks for cosmetic and pharmaceutical applications.
Jars Market Competitive Environment
North American producers anchor one tier; Western European specialists hold differentiated positions in premium pharmaceutical and food-grade segments. The vendor base splits between scale-driven container glass conglomerates and mid-cap specialists focused on cosmetic and artisan food niches. Three archetypes dominate: furnace-integrated giants with cullet processing networks, mold-specialist boutiques serving custom short-run orders, and diversified packaging conglomerates leveraging cross-material synergies. Capacity expansion and oxy-fuel retrofit investments constitute the dominant competitive moves across both tiers.
Within the furnace-integrated tier, Ball Corporation and O-I Glass exemplify scale-driven positioning through captive supply chain control and lightweighting R&D intensity. Ardagh Group occupies a position among Western European fabricators leveraging geographic dominance across packaging markets. These three entities represent the consolidation logic that is compressing mid-tier jar manufacturing capacity in both North American and European production zones.
| Leading Market Players |
|---|
| Ball Corporation |
| O-I Glass, Inc. |
| Ardagh Group |
| Libbey |
| Anchor Hocking |
| Verallia |
| Saverglass |
| Heinz-Glas |
| Stölzle Glass Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between BRCGS Grade A pharmaceutical jar facilities and uncertified commodity glass operations manifests in both pricing power and supply chain configuration. Premium borosilicate glass commands substantial markups from German and Swiss pharmaceutical packagers, while mass-market PET jar procurement in North American retail channels operates on thin distributor margins and volume-based contract structures.
Pricing Analysis
Distributor margin layers in European glass jar distribution typically capture 15-25 points between furnace gate and pharmaceutical end-user, while direct-to-brand procurement in Italian organic preserves compresses this spread through volume commitments. Three-tier pricing structure across premium pharmaceutical-grade, standard food-grade, and economy household-grade specifications reflects certification burden and thermal performance differentiation. Cost compression in commodity PET segments is intensifying because of resin price volatility and freight optimization demands from big-box retailers. Food manufacturers exhibit highest price sensitivity, while pharmaceutical packagers prioritize USP compliance and thermal shock resistance over unit cost.
Supply Chain Analysis
High-quality cullet supply rests on German and Dutch collection infrastructure, with furnace operations in France and Italy drawing from these processing hubs. Soda-lime silica sand sources from Belgium and France, while borosilicate raw materials concentrate in specialty chemical producers across Germany and the United States. Single-source vulnerability in pharmaceutical-grade borosilicate glass creates bottleneck exposure for sterile formulation packagers outside established supply corridors. Distribution runs through regional packaging distributors serving food manufacturers, with direct mill relationships dominating pharmaceutical and premium cosmetic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation functions as a regulatory compounder, mandating recycled content thresholds that restructure procurement economics and furnace investment decisions across European production zones.
For Market Incumbents: Lock in cullet processing capacity through offtake agreements with German and Dutch collection networks before compliance deadlines crystallize. Retrofit Rhine-Ruhr furnace operations to oxy-fuel architectures to defend margin position against carbon border adjustments. Vertical integration into lightweighting R&D preserves pricing power as thin-wall specifications become mandatory for export-grade pharmaceutical accounts.
For New Entrants and Emerging Players: Smart packaging integration with NFC-enabled closures offers a technology-first wedge into premium food segments where traceability commands price premiums. Indian pharmaceutical packaging under CDSCO-ICH alignment presents the most penetrable geography for export-grade borosilicate glass jar production. Direct-to-brand sales models bypassing distributor networks capture margin in Italian organic preserves and Spanish craft condiment verticals.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier jar manufacturers lack BRCGS certification and electric furnace engineering talent to meet EU Green Deal benchmarks. Acquisition targets with captive cullet processing and Grade A pharmaceutical certification offer longest-term viability through the energy transition. Watch electric melting engineering talent scarcity as the inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Conversion | Rhine-Ruhr retrofit investments align jar production with EU Green Deal emission benchmarks. |
| Cullet Processing Infrastructure Expansion | German and French capital deployment secures recycled glass supply for regulatory compliance. |
| Lightweighting R&D Intensity | 2.2mm base specifications cut silica consumption without sacrificing pharmaceutical stack strength. |
| Direct-to-Brand Procurement Channels | Italian organic preserves producers bypass distributors to negotiate custom mold access directly. |
| Smart Packaging Integration | NFC tags and temperature-sensitive inks enable supply chain traceability in premium food segments. |
Study Parameters
Coverage spans Germany, France, Italy, the United States, and India, with primary inputs from each market informing demand calibration. Glass furnace operators, pharmaceutical packaging procurement leads, food manufacturer supply planners, and distributor channel managers contributed structured interviews. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, FDA 21 CFR standards documentation, CDSCO alignment announcements, and customs trade data. Bottom-up volume modeling triangulated against top-down industry association aggregates.
Granularity-level modeling tracked material composition, capacity tier, end-user segment, and closure type across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by pricing tier and regional regulatory intensity. Pharmaceutical cold-chain expansion rates, oxy-fuel conversion capex cycles, and cullet supply concentration patterns served as industry-specific forecast inputs.
The model holds under stable EU regulatory implementation timelines; deviation in natural gas price volatility or electric furnace engineering talent availability would shift capacity expansion trajectories. Forecasts reflect documented assumptions on recycled content mandate enforcement and carbon border adjustment mechanisms. A small set of named triggers—cullet supply disruption, REACH reformulation deadlines, and BRCGS audit backlogs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
HDPE Bottles Market
Containers
Container Fixed Fittings Market
Containers
Reconditioned IBC Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Laboratory Sample Container Market
Containers
Takeout Containers Market
Containers
Stock Clamshell Packaging Market
Containers
Collapsible Crate Market
Containers
Belgium Container Glass Market
Containers
ISO Ocean Containers Market
Containers
Kuwait Container Glass Market
Containers
Global Cardboard Box and Container Market
Containers
Global Multi Pack Carriers Market
Containers
In-Mold Labelled Containers Market
Containers
Snap-Lock Container Market
Containers
Slip Lid Can Market