
 Mexico Container Glass Market | 2026-2036
Mexico Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Container Glass Market Insights
The premium-commodity split in Mexican container glass is repositioning around decoration intensity, batch customization, and lead-time flexibility rather than volume scale alone. Vitro, S.A.B. de C.V. leverages its integrated flat and container glass operations to sustain cost advantages across high-volume beer and soft-drink contracts. Fevisa anchors specialty pharmaceutical and cosmetics vial production with dedicated furnace lines that competitors cannot easily replicate. Grupo Pavisa competes through decorative capabilities, occupying the premium spirits segment where embossed and painted finishes command sustained margin premiums.
Container glass denotes silica-based packaging formed through controlled thermal processing, typically comprising soda ash, limestone, and cullet in proportions yielding chemically inert, impermeable vessels with wall thicknesses calibrated for internal pressure or vacuum stability. Its primary commercial purpose centers on preserving organoleptic properties, extending shelf life, and supporting brand differentiation through form and surface treatment in liquid and semi-solid product distribution. Glass bottles dominate volume throughput across Mexican production lines, while vials capture concentrated margin pools in pharmaceutical serialization and cosmetics sampling applications. The blown manufacturing stage leads installed capacity, though moulded formats gain traction in standard spirits and food jar segments where dimensional repeatability reduces downstream filling-line adjustments.
SEMARNAT enforces Extended Producer Responsibility frameworks that obligate container glass producers to document recycled content thresholds and end-of-life collection participation, directly shaping batch composition decisions and cullet sourcing strategies. NOM-252-SSA1-2011, administered by COFEPRIS, specifies chemical migration limits and surface integrity standards for pharmaceutical and food-contact glass, filtering market access for non-compliant imports and sub-scale domestic operations. BIS-referenced ISO 15378 alignment, increasingly demanded by multinational pharmaceutical clients operating in Mexico, adds a certification layer that concentrates supply relationships toward audited manufacturers. Stakeholders must monitor how SEMARNAT's pending packaging waste decree modifies cullet recovery obligations and whether COFEPRIS harmonizes further with US FDA glass quality guidance, as these regulatory trajectories will determine which furnace investments retain competitive validity.
Market Dynamics
SEMARNAT's Extended Producer Responsibility framework is compressing batch composition decisions across Mexican furnace operations, forcing producers to restructure cullet sourcing networks and renegotiate supplier terms before pending decree implementation.
Growth Catalysts
- Spirits packaging premiumization:Jalisco and Guanajuato craft distillers are specifying heavier base weights and embossed finishes that displace standard commodity formats.
- SEMARNAT recycled content mandates:Documented cullet thresholds in updated packaging waste regulations are redirecting capital toward closed-loop collection infrastructure.
- Bajío food processing concentration:Clustered tomato paste, salsa, and sauce operations in Querétaro and Guanajuato generate sustained jar and bottle offtake with minimal logistics friction.
Market Restraints
- Natural gas input volatility:Furnace energy costs fluctuate with Pemex pipeline supply interruptions and spot LNG pricing, compressing margin predictability for continuous-melt operations.
- High-purity silica concentration:Domestic sand deposits meeting pharmaceutical and cosmetics glass specifications concentrate in limited Sonora and Coahuara quarries, creating single-source exposure.
- Aluminum can substitution:Beer and soft-drink brands are piloting lightweight metal formats for export markets where shipping weight dominates packaging selection.
Strategic Opportunities
- Pharmaceutical serialization compliance:COFEPRIS alignment with FDA glass quality guidance is opening dedicated vial furnace capacity for contract manufacturing organizations serving US generics.
- Decorative capability convergence:Digital printing integration with traditional mould embossing enables batch-size-one customization for limited-edition spirits releases.
- Yucatán Peninsula underpenetration:Mérida and Cancún beverage production clusters currently import from Veracruz, creating logistics arbitrage for regional furnace investment.
Industry Challenges
- ISO 15378 audit compression:Pharmaceutical clients are demanding 12-month certification cycles rather than 24-month intervals, straining quality documentation staffing.
- Legacy furnace rebuild sequencing:Regenerative chamber upgrades require 45-day cold shutdowns that conflict with just-in-time contract delivery obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Container Glass Market |
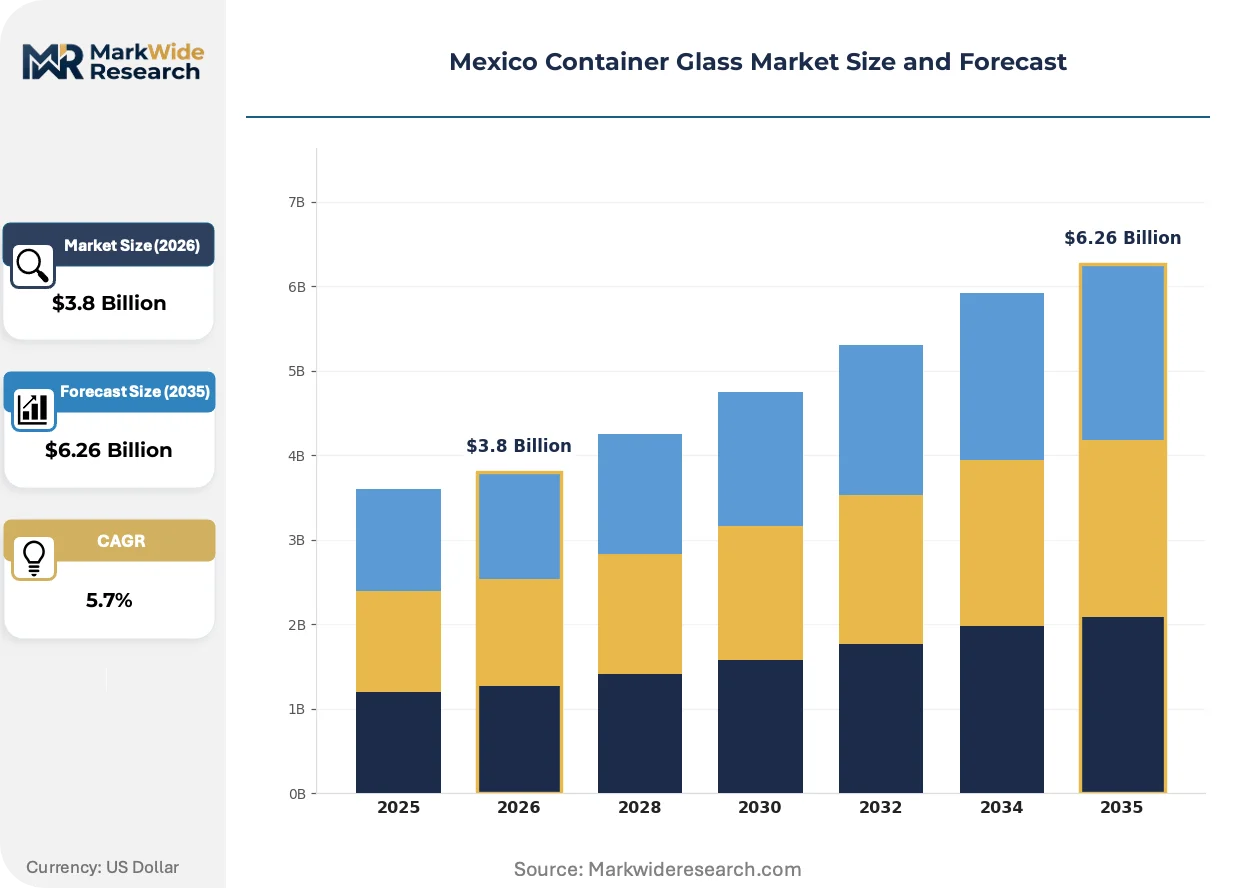
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Bottles, Jars, Vials, Tumblers Manufacturing Stage: Blown, Pressed, Moulded, Coated End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Packaging Type: Recyclable, Single-use, Durable, Premium |
| Companies Covered | Fevisa, Gerresheimer AG, Vitro, S.A.B. de C.V., Glasser S.A. de C.V., Grupo Pavisa, O-I Glass, Inc., Saverglass SAS, Inova Glass SA DE CV, BA Glass-Vidrio Formas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Container Glass Market Trends and Innovations
Electrification of melting operations and digital decoration integration are converging to alter capital deployment patterns across Mexican production assets, with regulatory compliance timelines compressing technology adoption windows.
Hybrid oxy-fuel furnace architecture is rewriting energy intensity benchmarks for container glass melting. Grupo Modelo and Constellation Brands procurement specifications now prioritize suppliers demonstrating 20% thermal efficiency gains over regenerative designs. This technology is compressing the payback period for furnace rebuild investments from seven years toward four, reallocating capital toward decoration downstream.
COFEPRIS harmonization with US FDA glass quality guidance is tightening migration limit enforcement for pharmaceutical-contact surfaces. Domestic manufacturers lacking dedicated borosilicate furnace lines face exclusion from multinational generics contracts. Specialty vial producers with NOM-252-SSA1-2011 compliance documentation are capturing preference share in insulin and biologics packaging.
Direct-to-distillery design services are displacing traditional distributor-mediated specification processes. Premium tequila houses in Atotonilco and Arandas now retain glass designers in-house, forwarding technical drawings straight to furnace operators. This pattern concentrates most visibly in the Tequila Valley, where brand identity investments exceed packaging material costs by three-to-one ratios.
Mexico Container Glass Market Segmentation
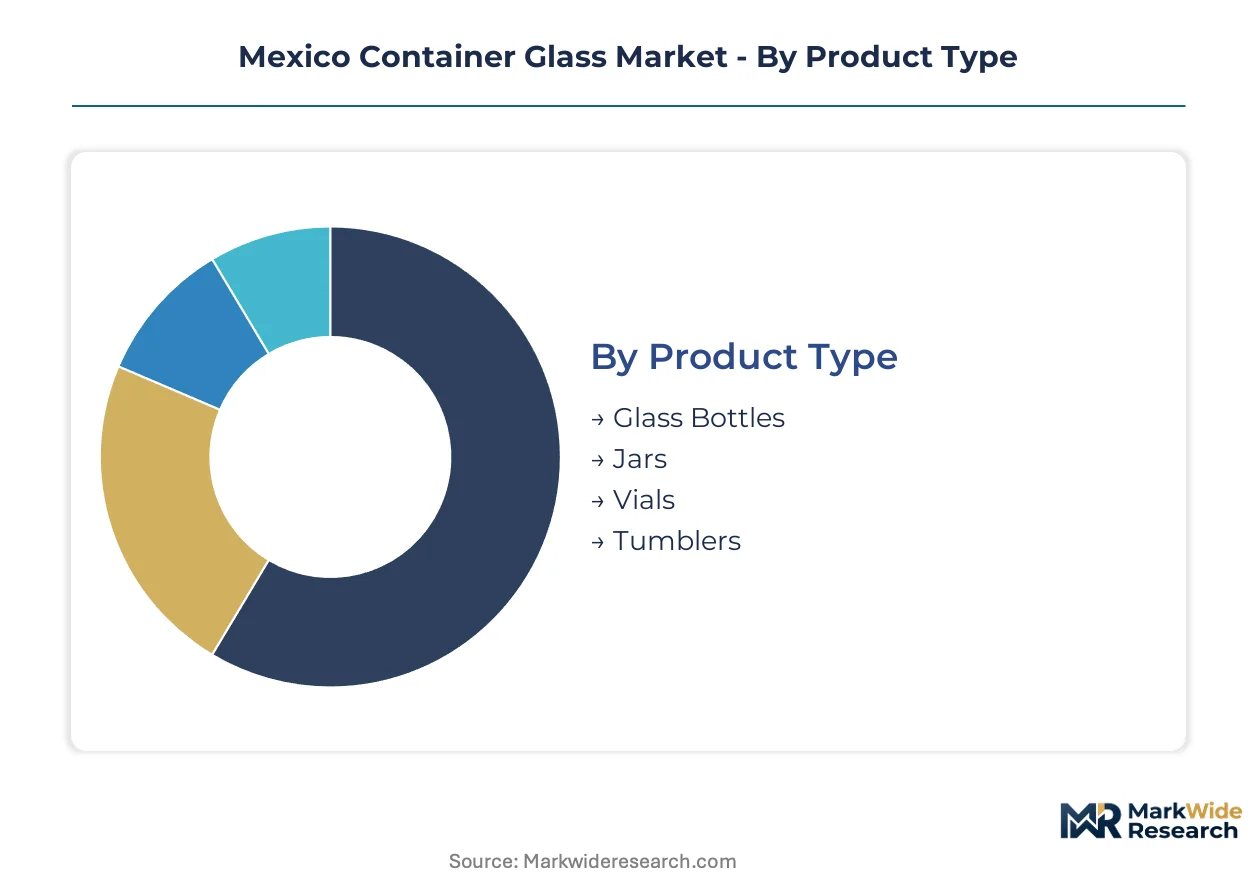
Mexican container glass segmentation reveals how furnace operators must configure batch chemistry and mould capabilities around divergent buyer requirements. Distinct technical specifications across product types, manufacturing stages, and end-user verticals determine which producers capture margin premiums versus commodity volume.
Product Type:
Bottle weight, wall thickness, and finish complexity separate premium spirits buyers from mass-market beverage procurement.
- Glass Bottles:Soda-lime silica construction dominates beer and soft-drink filling lines across Jalisco and Nuevo León. Constellation Brands and Grupo Modelo procurement contracts anchor capacity utilization at Bajío corridor furnaces.
- Jars:Wide-mouth configurations with vacuum-stable sealing surfaces concentrate demand in Querétaro tomato paste and salsa processing clusters. Food safety compliance with NOM-252-SSA1-2011 filters supplier qualification.
- Vials:Borosilicate and neutral glass formats for pharmaceutical serialization.
- Tumblers:Direct-to-consumer drinkware with decorative surface treatments.
Volume sits with bottles; growth tilts toward vials.
Manufacturing Stage:
Energy intensity and capital recovery timelines vary sharply across thermal processing methods.
- Blown:Compressed air forming of molten glass parisons enables thin-wall construction for lightweight beverage containers. Hybrid oxy-fuel furnace retrofits are compressing energy costs per ton at Monterrey and Toluca production sites.
- Moulded:Mechanical pressing delivers dimensional repeatability for standard spirits and food jar formats. Bajío filling-line operators prefer moulded supply to minimize downstream adjustment downtime.
- Pressed:Direct mechanical forming for heavier-walled specialty containers.
- Coated:Surface treatment applications for UV protection and scratch resistance.
Blown capacity commands the installed base; moulded lines are expanding most quickly.
End User:
Regulatory stringency and brand differentiation budgets determine margin capture potential.
- Food & Beverage:Volume concentration in beer, soft drinks, and processed foods. SEMARNAT recycled content mandates are redirecting procurement toward suppliers with documented cullet recovery networks.
- Pharmaceuticals:COFEPRIS alignment with FDA glass quality guidance is tightening migration limit enforcement. Dedicated borosilicate furnace lines at Fevisa and Grupo Pavisa capture insulin and biologics packaging contracts.
- Cosmetics:Sampling and premium fragrance applications.
- Household:Storage and decorative consumer goods.
Food and beverage anchors throughput; pharmaceuticals deliver the steepest expansion trajectory.
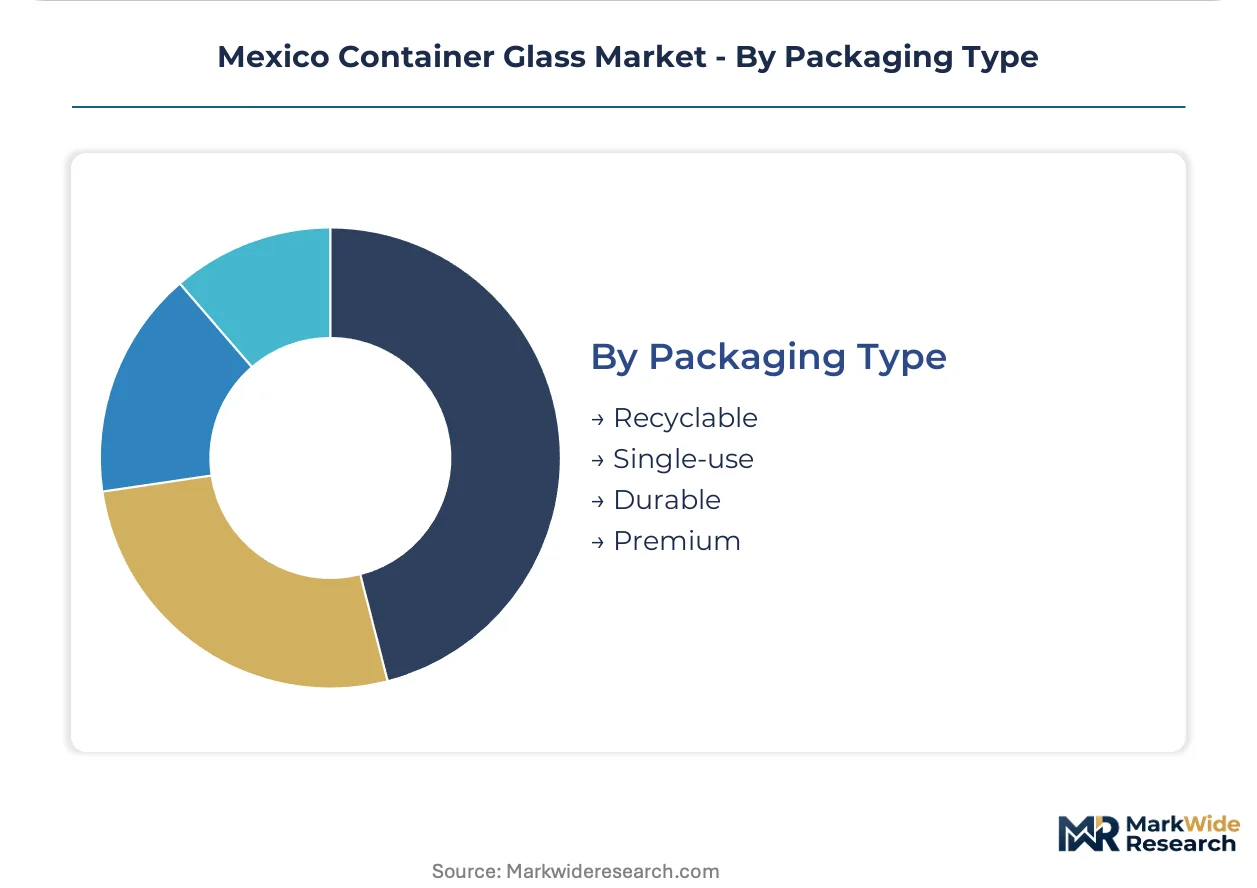
Packaging Type:
Circular economy compliance and brand positioning separate procurement tiers.
- Recyclable:Documented cullet content and end-of-life collection participation required under SEMARNAT Extended Producer Responsibility frameworks. Furnace operators are restructuring supplier terms to secure post-consumer glass feedstock.
- Premium:Embossed, painted, and digitally printed finishes for craft spirits and limited releases. Tequila Valley distillers specify decoration intensity exceeding material costs by substantial margins.
- Single-use:Standard beverage and food service applications.
- Durable:Reusable container formats with enhanced mechanical strength.
Recyclable formats dominate regulatory attention; premium finishes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bajío industrial corridor anchors Mexican container glass demand, with Querétaro and Guanajuato hosting dense food processing clusters that consume jar and bottle formats at scale.
Bajío Region
Tomato paste, salsa, and sauce operations in Querétaro and Guanajuato generate sustained jar offtake with minimal logistics friction. SEMARNAT's Extended Producer Responsibility framework obligates producers here to document recycled content thresholds. Irapuato and Celaya anchor regional consumption through clustered agro-industrial filling lines.
Jalisco
Craft tequila and spirits distillers in Atotonilco and Arandas specify heavier base weights and embossed finishes that displace commodity formats. COFEPRIS enforces NOM-252-SSA1-2011 chemical migration limits for food-contact glass. The Tequila Valley concentrates premium packaging specification activity where brand identity investments exceed material costs.
Nuevo León
Monterrey-based beverage producers anchor high-volume beer and soft-drink contract demand. Hybrid oxy-fuel furnace retrofits are compressing energy costs per ton at local production sites. Apodaca and García host filling-line clusters that prefer moulded glass supply to minimize downstream adjustment downtime.
Mexico City Metro
Pharmaceutical and cosmetics packaging demand concentrates in the capital's contract manufacturing ecosystem. COFEPRIS alignment with FDA glass quality guidance tightens migration limit enforcement for serialization-ready vials. Toluca production sites serve multinational generics clients with dedicated borosilicate furnace capacity.
Yucatán Peninsula
Mérida and Cancún beverage production clusters currently import container glass from Veracruz, creating logistics arbitrage opportunities. Pending SEMARNAT packaging waste decree modifications may alter cullet recovery obligations for regional entrants. Progreso port infrastructure supports potential furnace investment serving underpenetrated southeastern markets.
Mexico Container Glass Market Competitive Landscape
Capital-heavy furnace operators compete with asset-light decoration specialists across tiered procurement channels. The market structure concentrates around integrated flat-and-container glass conglomerates, dedicated pharmaceutical vial producers, and premium spirits decoration houses. Three archetypes dominate: scale-driven commodity suppliers, compliance-focused pharmaceutical specialists, and design-forward premium finishers. Competitive moves center on furnace electrification retrofits and direct-to-distillery design service contracts.
Among Mexico-based producers, Vitro, S.A.B. de C.V. and Grupo Pavisa occupy distinct positioning archetypes, while Fevisa anchors specialty pharmaceutical production. Gerresheimer AG represents European multinational participation in compliance-intensive segments. These named entities exemplify how geographic origin and corporate structure map to strategic specialization without converging on identical capability profiles.
| Leading Market Players |
|---|
| Fevisa |
| Gerresheimer AG |
| Vitro, S.A.B. de C.V. |
| Glasser S.A. de C.V. |
| Grupo Pavisa |
| O-I Glass, Inc. |
| Saverglass SAS |
| Inova Glass SA DE CV |
| BA Glass-Vidrio Formas |
| Others |
Pricing and Supply Chain Analysis
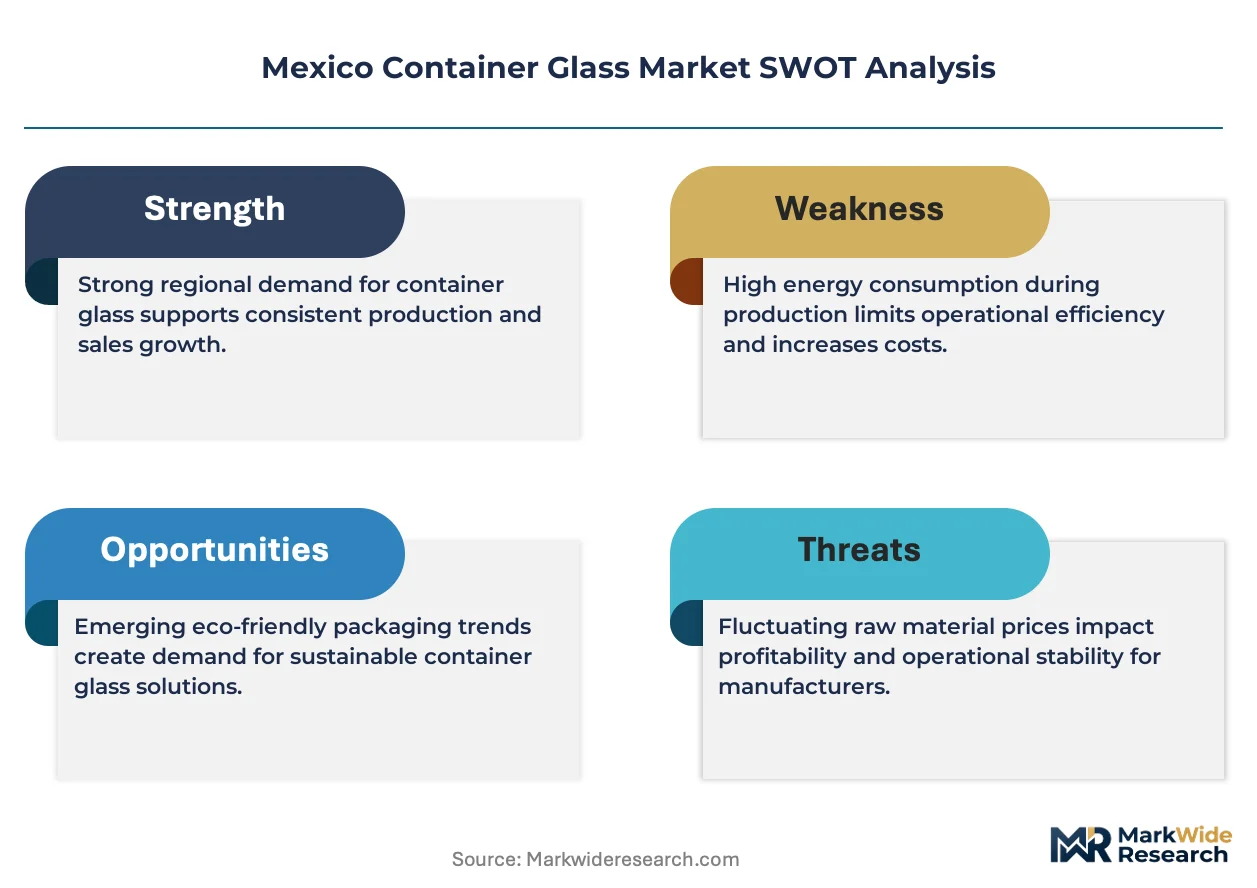
Pemex natural gas spot pricing cascades through Mexican furnace operations into three distinct procurement tiers, with energy-intensive continuous-melt producers passing volatility premiums to beverage contract buyers while specialty vial manufacturers absorb costs through pharmaceutical-grade certification markups.
Pricing Analysis
Yield-guaranteed furnace uptime anchors value-based pricing for pharmaceutical serialization contracts, where COFEPRIS-compliant borosilicate batches command substantial premiums over standard soda-lime formats. Price differentiation stratifies across ISO 15378 certification tier, volume commitment scale, and decoration complexity for spirits applications. Cost compression in mass-market beer and soft-drink supply is intensifying because hybrid oxy-fuel retrofits compress thermal efficiency benchmarks. Commodity beverage buyers exhibit acute price sensitivity, while premium tequila houses prioritize design flexibility over per-unit material cost.
Supply Chain Analysis
Dual-sourcing mandates from Constellation Brands and Grupo Modelo procurement teams require qualified backup furnace capacity across at least two Mexican states, compressing single-site operators from high-volume contract pools. Geographic supply concentration draws from Sonora high-purity silica quarries, Veracruz port-handling infrastructure, and Nuevo León natural gas pipeline networks. Raw material dependencies rest on imported soda ash, domestic limestone deposits, and post-consumer cullet recovery streams. Single-source vulnerability concentrates in pharmaceutical-grade sand specifications limited to select Coahuila extraction sites. Distribution runs through Bajío corridor filling-line clusters with just-in-time delivery obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a furnace electrification consolidation play, with SEMARNAT's pending packaging waste decree forcing sub-scale operators lacking closed-loop cullet networks toward distressed exit or acquisition.
For Market Incumbents: Cement hybrid oxy-fuel furnace dominance through regenerative chamber retrofits at Monterrey and Toluca production sites, securing Grupo Modelo and Constellation Brands procurement contracts against aluminum can substitution threats. Lock in pharmaceutical serialization capacity through dedicated borosilicate lines with 12-month ISO 15378 audit cycles, excluding import competition from multinational generics contracts. For New Entrants and Emerging Players: Capture Yucatán Peninsula logistics arbitrage by qualifying Progreso port infrastructure for regional furnace investment serving Mérida and Cancún beverage clusters currently importing from Veracruz. Target decorative capability convergence through digital printing integration with traditional mould embossing, offering batch-size-one customization to Tequila Valley craft distillers bypassing distributor-mediated specification processes. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-focused pharmaceutical vial specialists with NOM-252-SSA1-2011 documentation and existing COFEPRIS audit relationships in Mexico City Metro and Toluca production zones. Long-term viability hinges on furnace electrification readiness and SEMARNAT cullet recovery network integration. Watch for natural gas price volatility spikes as inflection indicators accelerating incumbent consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Oxy-Fuel Furnace Retrofit | Constellation Brands procurement specifications now prioritize suppliers demonstrating thermal efficiency gains over regenerative designs. |
| Direct-to-Distillery Design Service | Premium tequila houses in Atotonilco and Arandas retain in-house glass designers, forwarding technical drawings straight to furnace operators. |
| Closed-Loop Cullet Recovery Network | SEMARNAT Extended Producer Responsibility frameworks obligate producers to document recycled content thresholds and end-of-life collection participation. |
| Pharmaceutical Serialization Compliance | COFEPRIS alignment with FDA glass quality guidance opens dedicated vial furnace capacity for contract manufacturing organizations serving US generics. |
| Digital Decoration Integration | Digital printing convergence with traditional mould embossing enables batch-size-one customization for limited-edition spirits releases in Jalisco. |
Research Methodology
Multi-period observation of furnace capacity utilization rates, SEMARNAT regulatory filing trajectories, and Pemex natural gas pricing volatility anchored the trend analysis, supplemented by interviews with plant managers at Bajío corridor production facilities, procurement leads at Constellation Brands and Grupo Modelo, COFEPRIS regulatory affairs specialists, and pharmaceutical contract manufacturing executives. Secondary validation drew from COFEPRIS NOM-252-SSA1-2011 documentation, SEMARNAT Extended Producer Responsibility decree drafts, customs import records for container glass machinery, and SEC filings of multinational packaging conglomerates with Mexican operations. Bottom-up furnace capacity modeling and top-down beverage industry consumption estimates were triangulated against regional production cluster data.
Segment-weighting approaches distributed volume and value projections across product type, manufacturing stage, and end-user vertical dimensions, with particular attention to pharmaceutical serialization compliance tiers and premium spirits decoration intensity categories. CAGRs were derived from regression analysis of historical furnace throughput data against beverage production volumes and pharmaceutical packaging demand curves across the projection horizon. Industry-specific forecast inputs included hybrid oxy-fuel adoption rates, SEMARNAT cullet mandate implementation timelines, and COFEPRIS-FDA harmonization progress on glass quality guidance.
The model holds under stable natural gas supply conditions and gradual SEMARNAT regulatory phase-in; deviation in Pemex pipeline interruption frequency or accelerated packaging waste decree enforcement would shift furnace investment viability and competitive positioning materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Dominican Republic Container Glass Market