
 Soup Containers Market | 2026-2036
Soup Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Soup Containers Market Analytics
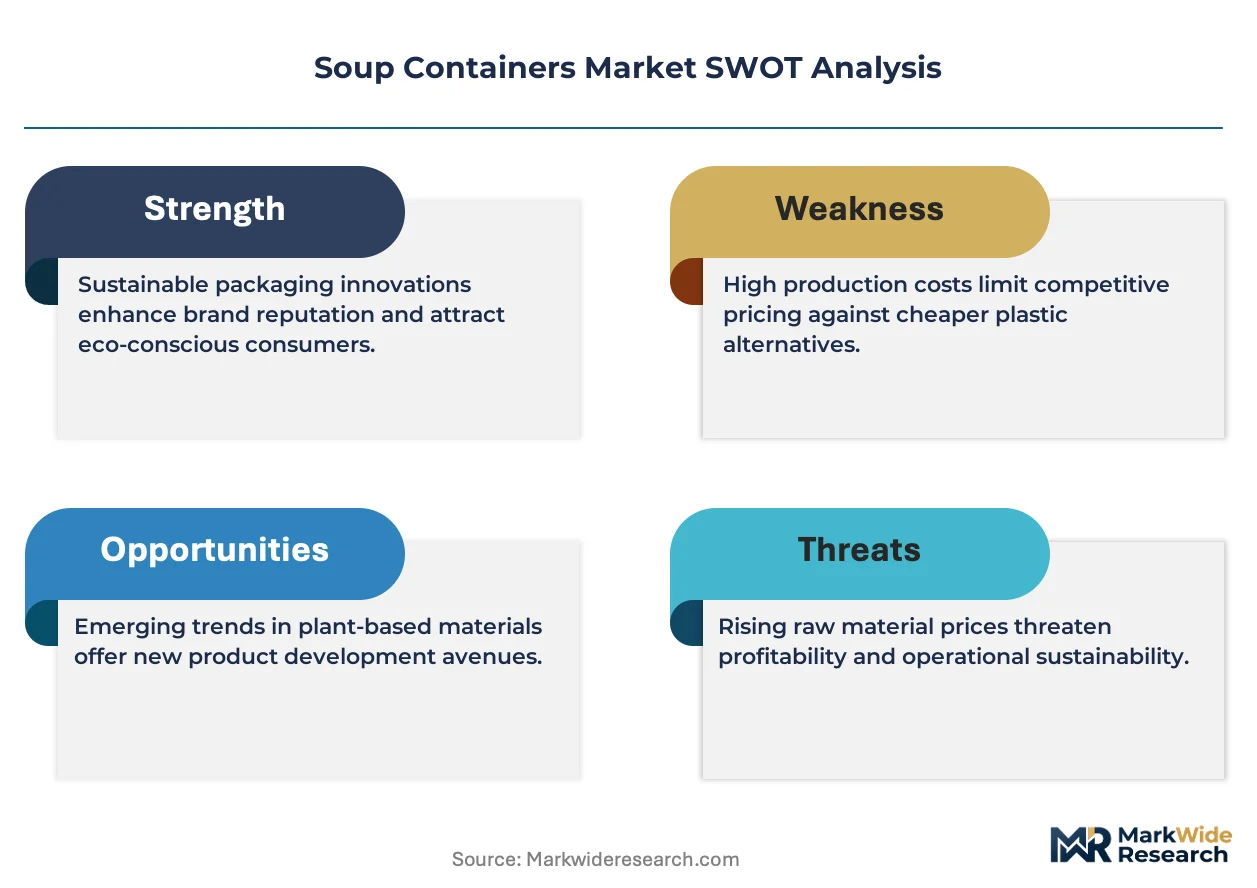
ISO 22000 certification for food-contact packaging is collapsing the supplier base as smaller molders exit rather than absorb audit and documentation costs. Huhtamaki Oyj leverages its integrated fiber-forming and barrier-coating operations to sustain European quick-service contracts. Dart Container Corporation anchors North American foam and polypropylene production through captive resin conversion and dense distribution networks.
Soup containers are rigid or semi-rigid vessels engineered to maintain thermal stability between 65°C and 85°C while preventing moisture transmission, typically constructed from polypropylene, paperboard with polyethylene extrusion, or coated molded fiber. Their primary commercial purpose is to enable off-premise consumption of hot prepared soups without leakage or flavor contamination. Paper-based formats lead unit volume in Europe where F-Gas Regulation and national plastic bans redirect foodservice procurement, while plastic bowls dominate North American fast-casual channels due to microwave compatibility and lower unit cost. Metal and glass remain marginal outside premium retail and home-delivery subscription models where reuse and aesthetic differentiation command price premiums.
The US FDA maintains food-contact substance notification requirements under 21 CFR, while the EU EFSA evaluates migration limits for paper and plastic soup containers through its food-contact materials panel. These frameworks directly determine which barrier chemistries and substrate combinations achieve commercial scale. Stakeholders must monitor evolving state-level extended producer responsibility laws in California, Oregon, and Colorado that will reshape collection infrastructure and fee structures for single-use food packaging.
Market Dynamics
EU Single-Use Plastics Directive enforcement is collapsing the supplier base for conventional plastic soup containers, forcing converters toward fiber-forming investments or exit while quick-service chains scramble to certify alternative formats before national deadlines.
Growth Catalysts
- Quick-service restaurant expansion:Chains in the United States are adding hot soup to drive-thru and delivery menus, creating pull for insulated, leak-resistant vessels that maintain food safety temperatures during transport.
- F-Gas Regulation:European Union restrictions on fluorinated greenhouse gases are accelerating paperboard barrier development, rewarding converters with in-house polyethylene extrusion or aqueous coating capabilities.
- Grab-and-go urban formats:Dense metropolitan consumption patterns in the United States favor single-serve, disposable packaging over reusable alternatives, sustaining volume demand for rigid and semi-rigid containers.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs fluctuate with propylene monomer supply disruptions, squeezing margin for North American foam and injection-molding specialists without captive resin conversion.
- Supplier concentration risk:ISO 22000 certification requirements for food-contact packaging are eliminating smaller molders in Europe, consolidating supply among integrated fiber-forming operators with audit infrastructure.
- Technical performance gaps:Molded fiber containers with aqueous barriers struggle to match polypropylene's microwave compatibility and thermal stability above 85°C, limiting substitution in fast-casual channels.
Strategic Opportunities
- California EPR implementation:Extended producer responsibility laws taking effect in California, Oregon, and Colorado will reshape collection infrastructure, creating first-mover advantage for brands with designed-for-recycling formats and fee-optimized material choices.
- Home-delivery subscription models:Premium retail and direct-to-consumer soup services are adopting glass and metal vessels for reuse and aesthetic differentiation, opening price-insensitive segments outside commodity foodservice.
- Barrier chemistry convergence:Integration of bio-based coatings with traditional paperboard extrusion is enabling fiber containers to meet FDA migration limits under 21 CFR, unlocking quick-service contracts previously held by plastic incumbents.
Industry Challenges
- Certification timeline compression:EFSA food-contact materials panel evaluations for new barrier chemistries run 18-24 months, delaying product launches and freezing R&D pipelines during regulatory uncertainty.
- Legacy equipment strandedness:Converters with sunk capital in polystyrene foam forming face costly retooling for fiber pulp molding or polypropylene thin-wall injection, with payback periods extending beyond policy-driven demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soup Containers Market |
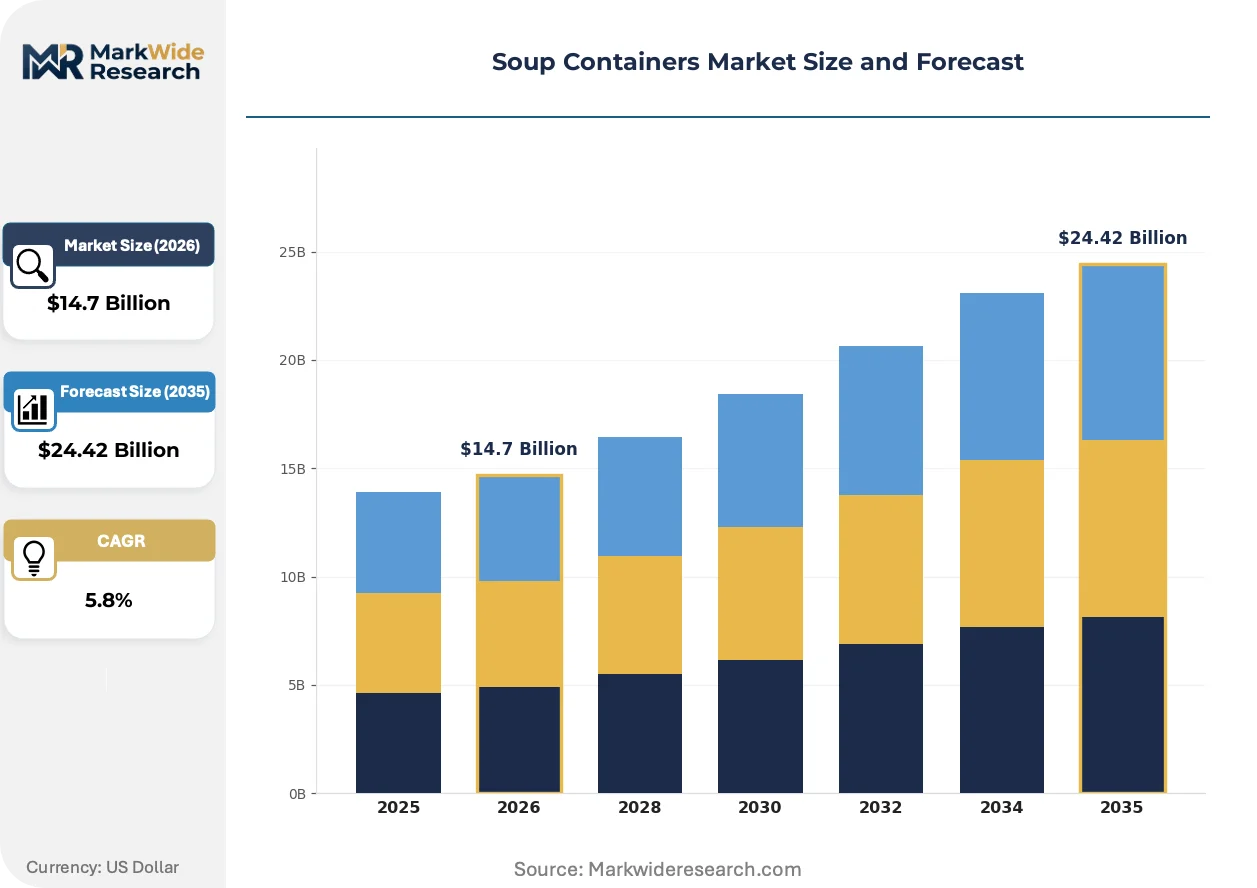
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bowl, Cup, Tumbler, Pouch Material: Plastic, Glass, Paper, Metal Size: Small, Medium, Large, Extra Large Closure Type: Screw-On, Snap-On, Lid, No Closure |
| Companies Covered | Huhtamaki Oyj, Dart Container Corporation, Genpak LLC, Sonoco Products Company, Amcor PLC, Berry Global, Ball Corporation, Crown Holdings Inc., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soup Containers Market Evolving Landscape
Active reshaping of the soup container market centers on material substitution under regulatory pressure, with fiber-based formats gaining technical ground against plastic incumbents while certification and supply consolidation determine competitive survival.
Barrier-coated molded fiber technology is bifurcating the quick-service procurement landscape. Aqueous and bio-based coatings now achieve grease and moisture resistance comparable to polyethylene extrusion for short-hold applications. European chains with 30-minute delivery guarantees are piloting these formats at scale. The technology is bifurcating vendor tiers, separating integrated fiber-forming operators with in-house coating from commodity converters dependent on outsourced barriers.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical barriers from European food-contact materials. Industrial consequence includes accelerated migration toward silicone-based and clay-based alternatives with higher unit costs but regulatory certainty. Paperboard soup containers with non-fluorinated barriers are capturing quick-service contracts in Germany and France where national plastic bans precede EU-wide deadlines.
Centralized procurement by multi-brand restaurant groups is displacing distributed purchasing at franchise level. Corporate sustainability mandates now override local operator preferences, forcing standardized container specifications across thousands of locations. This concentration is most visible in the United States, where top ten quick-service chains account for majority soup container volume and are consolidating supplier panels to three certified partners per region.
Soup Containers Market Segmentation
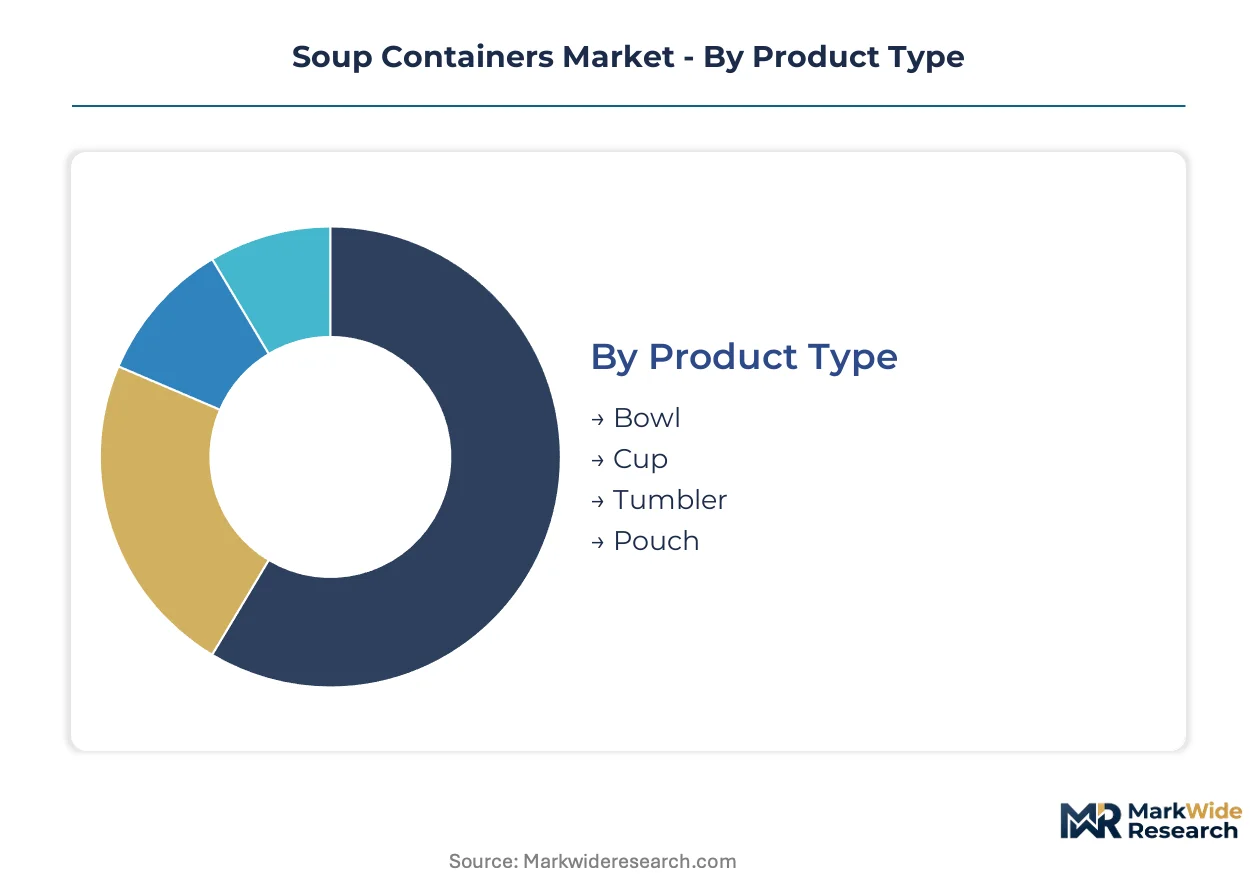
Soup container segmentation reflects divergent technical requirements across foodservice channels and the regulatory pressure reshaping material procurement. Container geometry, barrier performance, and closure integrity each determine suitability for quick-service, retail, or home-delivery applications.
Product Type:
EU Single-Use Plastics Directive and FDA food-contact substance rules under 21 CFR create divergent certification pathways for each format, with bowl and cup geometries commanding the bulk of compliance investment.
- Bowl:Wide-rim polypropylene or coated fiber vessels engineered for spoon-accessible consumption. Quick-service chains in the United States specify bowls for drive-thru soup programs where thermal retention above 65°C determines food safety compliance during transport.
- Cup:Tapered paperboard or plastic vessels with rolled rims for lid retention. European procurement is pivoting toward aqueous-barrier fiber cups as REACH restrictions eliminate fluorochemical treatments from food-contact materials.
- Tumbler:Insulated double-wall constructions for extended-hold applications. Premium retail and subscription services specify tumblers for commuter consumption patterns.
- Pouch:Flexible laminated films for shelf-stable retail soup. Retort-compatible pouches concentrate in North American retail channels requiring microwave venting features.
Bowl formats handle the majority of foodservice throughput; cup formats are gaining share fastest as fiber barrier technology matures.
Material:
Cost tiers stratify sharply, with captive resin conversion and integrated fiber-forming operations defending margin against commodity converters.
- Plastic:Polypropylene and expanded polystyrene dominate North American fast-casual channels. Microwave compatibility and sub-cent unit economics sustain plastic's hold despite EPR fee pressure in California, Oregon, and Colorado.
- Paper:Polyethylene-extruded or aqueous-coated paperboard leads European unit volume. F-Gas Regulation accelerates converter investment in barrier coating infrastructure.
- Glass:Borosilicate and soda-lime vessels for premium retail and reuse-oriented subscription models. Aesthetic differentiation commands price premiums outside commodity foodservice.
- Metal:Tinplate and aluminum for retort and ambient retail applications. Home-delivery services specify metal for durability in circular reuse systems.
Plastic retains the largest installed base; paper is climbing the fastest as regulatory deadlines compress substitution timelines.
Size:
Application use-case determines volume concentration, with single-serve formats aligning to grab-and-go urban consumption patterns.
- Small:8-12 ounce vessels for appetizer portions and children's menus. Quick-service chains specify small formats for combo meal inclusion.
- Medium:16-20 ounce standard for adult single-serve consumption. This tier captures the bulk of commuter and office lunch demand.
- Large:24-32 ounce family and sharing formats. Delivery aggregators specify large containers for multi-person order consolidation.
- Extra Large:48+ ounce catering and foodservice bulk formats. Institutional procurement concentrates here with cost-per-ounce optimization.
Medium sizes carry the majority of unit volume; large formats are expanding most quickly as delivery order values rise.
Closure Type:
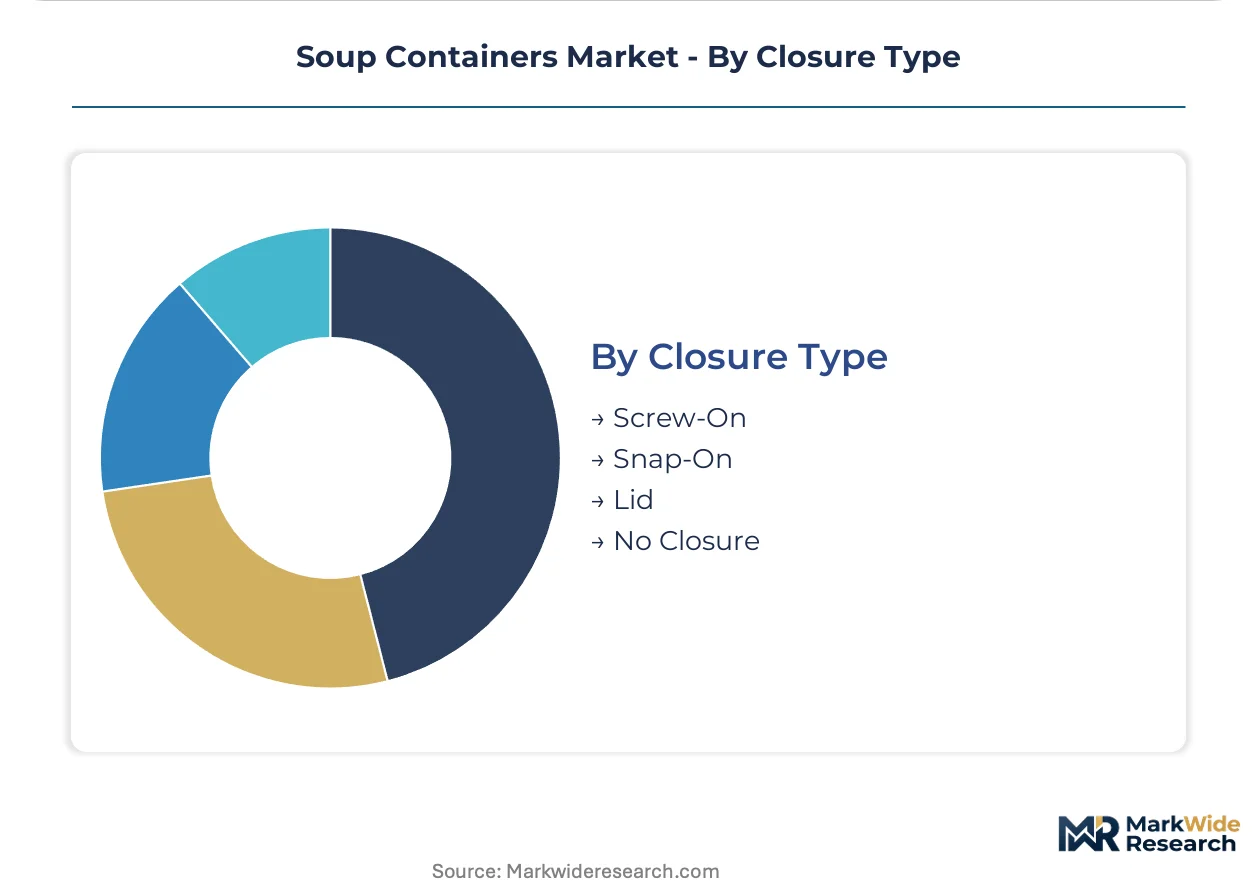
Leak resistance and resealability differentiate performance tiers, with screw-on specifications commanding certification premiums.
- Screw-On:Threaded polypropylene or bio-based polymer lids for secure transport. Premium retail and extended-hold delivery services mandate screw closures.
- Snap-On:Press-fit lids with peripheral locking beads. Quick-service chains favor snap-on for speed of service and lower unit cost.
- Lid:Separate flat or domed covers without positive attachment. Food courts and cafeteria formats specify lid-only for customer self-assembly.
- No Closure:Open vessels for immediate consumption or dine-in transfer. This tier concentrates in stadium and event catering where consumption is immediate.
Snap-on closures handle the majority of quick-service throughput; screw-on formats are gaining share fastest as delivery distance and hold-time requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility laws in California, Oregon, and Colorado are reshaping North American container procurement, while the EU Single-Use Plastics Directive compresses substitution timelines across European foodservice channels.
United States
Quick-service restaurant chains dominate soup container procurement through centralized corporate sustainability mandates. The FDA maintains food-contact substance notification requirements under 21 CFR that determine which barrier chemistries achieve commercial scale. Chicago and New York City metro areas concentrate demand for grab-and-go formats where dense urban consumption patterns sustain single-serve disposable packaging volume.
Germany
National plastic bans precede EU-wide deadlines, accelerating paperboard soup container adoption in quick-service channels. EFSA evaluates migration limits for fiber-based alternatives through its food-contact materials panel, creating 18-24 month certification timelines. The Rhine-Ruhr industrial corridor hosts integrated fiber-forming operators with in-house aqueous coating capabilities that supply certified formats to major restaurant groups.
France
REACH restrictions on per- and polyfluoroalkyl substances have eliminated fluorochemical barriers from food-contact materials. ANSM enforces national compliance deadlines that outpace broader EU schedules. The Lyon-Grenoble cluster concentrates converter investment in silicone-based and clay-based barrier alternatives for paperboard soup containers serving quick-service contracts.
United Kingdom
Post-Brexit regulatory divergence creates parallel certification tracks for food-contact packaging entering British versus EU markets. The Food Standards Agency maintains separate migration limit evaluations that extend product development timelines. Greater Manchester and Birmingham industrial zones host molders retooling from polystyrene foam toward polypropylene thin-wall injection to serve domestic quick-service demand.
China
Domestic quick-service expansion drives container demand as local chains add hot soup to delivery menus. SAMR implements national food-contact material standards under GB frameworks that increasingly align with international migration limit benchmarks. The Yangtze River Delta manufacturing belt concentrates export-oriented production of polypropylene and molded fiber formats for North American and European brand owners.
Soup Containers Market Competitive Landscape
Player mix skews toward integrated packaging conglomerates with captive barrier-coating infrastructure, creating a tiered structure where certified operators capture quick-service contracts while smaller molders exit under audit cost pressure. Two strategic archetypes dominate: fiber-forming specialists with in-house aqueous coating capabilities, and resin-integrated plastic converters with captive propylene supply. Competitive moves center on capacity expansion in barrier-coated molded fiber and strategic partnerships to secure EFSA certification timelines.
Among Nordic-integrated packaging groups, Huhtamaki Oyj exemplifies the fiber-forming archetype with European quick-service positioning. Dart Container Corporation anchors North American plastic production through dense distribution networks and captive resin conversion. Genpak LLC occupies a position within the mid-tier converter segment serving regional foodservice accounts. These three entities represent the competitive spectrum from multinational integrated operators to specialized regional suppliers.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Dart Container Corporation |
| Genpak LLC |
| Sonoco Products Company |
| Amcor PLC |
| Berry Global |
| Ball Corporation |
| Crown Holdings Inc. |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
ISO 22000 certification gates both supplier qualification and price differentiation in the soup container market, collapsing the vendor base as smaller molders absorb audit costs while integrated operators capture premium pricing for certified formats. This regulatory barrier simultaneously concentrates supply among audited operators and stratifies pricing across certification tiers, with foodservice chains paying material premiums for EFSA-validated barrier coatings.
Pricing Analysis
Certification level (ISO 22000/FDA-grade) creates the primary spread between pricing tiers, separating integrated fiber-forming operators with in-house barrier coating from commodity converters dependent on outsourced certification. Three-tier pricing structure across premium, standard, and economy levels reflects this stratification, with premium tiers commanding substantial markups for EFSA-validated aqueous barriers and extended-hold thermal performance. Cost compression in the standard tier is intensifying as resin price volatility squeezes polypropylene specialists without captive conversion. Quick-service restaurant chains demonstrate highest price sensitivity in high-volume bowl procurement, while home-delivery subscription services accept premium pricing for glass and metal reuse formats.
Supply Chain Analysis
Inventory lead times for barrier-coated molded fiber stretch 18-24 months due to EFSA food-contact materials panel evaluation cycles, freezing procurement pipelines during regulatory uncertainty. Supply concentrates in the United States, Germany, and China, with the Yangtze River Delta manufacturing belt anchoring export-oriented polypropylene and fiber production for North American and European brand owners. Raw material dependencies center on propylene monomer feedstock, aqueous coating chemistries, and certified pulp stocks. Single-source vulnerability runs through European aqueous barrier coating capacity, where REACH restrictions on fluorochemicals have eliminated alternative suppliers. Distribution runs through dense quick-service restaurant procurement networks and centralized corporate sustainability mandates that override franchise-level purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soup container market sits in cyclical recovery driven by quick-service restaurant expansion into hot soup drive-thru and delivery formats, creating sustained pull for insulated, leak-resistant vessels as chains rebuild post-pandemic throughput.
For Market Incumbents: Compound defensive positioning through backward integration into captive barrier-coating infrastructure and capacity addition in Germany's Rhine-Ruhr corridor to serve EFSA-certified European demand. The collapse of fluorochemical barriers under REACH restrictions threatens legacy coating supply chains; incumbents must secure silicone-based and clay-based alternative chemistry partnerships before national plastic bans compress substitution timelines. Certification investment represents the critical lever—operators with in-house audit infrastructure will absorb market share as smaller molders exit under ISO 22000 cost pressure. For New Entrants and Emerging Players: Anchor in California's extended producer responsibility implementation window, where designed-for-recycling fiber formats command first-mover fee advantages before Oregon and Colorado follow. The most penetrable white-space sits in premium retail and home-delivery subscription models, where glass and metal vessels for reuse systems remain underserved by incumbent foodservice-focused operators. A direct go-to-market angle through partnership with direct-to-consumer soup brands bypasses consolidated quick-service procurement panels. For Investors and Strategic Acquirers: California EPR implementation reshapes the acquisition landscape by revaluing assets with designed-for-recycling format capabilities and fee-optimized material choices. Long-term viability across the next decade hinges on regulatory compliance infrastructure rather than commodity manufacturing scale. Acquisition targets should display integrated fiber-forming with in-house aqueous coating, captive resin conversion, or established EFSA certification timelines. The signal to watch is EFSA food-contact materials panel approval velocity for novel barrier chemistries—accelerated evaluations indicate regulatory pathway clarity that unlocks quick-service contract migration from plastic incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Coating | Captures margin from outsourced aqueous chemistry and secures EFSA certification control. |
| Capacity Expansion in Certified Fiber Forming | Positions operators to absorb volume from exiting molders under ISO 22000 audit pressure. |
| Designed-for-Recycling Format Development | Creates first-mover advantage under California EPR fee structures before Oregon and Colorado implementation. |
| Alternative Barrier Chemistry Partnership | Secures silicone-based and clay-based supply chains as REACH eliminates fluorochemical options. |
| Direct-to-Consumer Channel Partnership | Bypasses consolidated quick-service procurement panels through premium retail and subscription model alignment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact substance notifications, EFSA migration limit evaluations, and quick-service restaurant sustainability disclosures, with bottom-up and top-down triangulation across the analysis window. Primary interviews engaged foodservice procurement directors, packaging converter plant managers, regulatory affairs leads at barrier chemistry suppliers, and sustainability officers at multi-brand restaurant groups. Secondary validation drew from EU Single-Use Plastics Directive implementation tracking, state-level EPR legislation in California, Oregon, and Colorado, SEC filings of integrated packaging conglomerates, and customs data on propylene monomer trade flows.
Segmentation dimensions modeled include product type geometry, material substrate, size tier, and closure specification, cross-referenced against regulatory framework clusters and foodservice channel archetypes. CAGRs were derived through demand elasticity analysis against quick-service expansion rates and substitution timeline compression under EU and state-level plastic bans. Industry-specific forecast inputs incorporated EFSA certification pipeline velocity, resin price volatility indices, and centralized procurement mandate adoption curves at top ten quick-service chains.
Decision-makers should treat outputs as directional under assumptions of sustained quick-service soup menu expansion and regulatory deadline adherence without material policy reversal; significant deviation in EFSA evaluation timelines or EPR fee structure implementation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Tin Containers Market
Containers
Grab and Go Containers Market
Containers
PUR Containers Packaging Market
Containers
Half Height Containers Market
Containers
Metal Crates Market
Containers
Algeria Container Glass Market
Containers
Acrylic Container Market
Containers
Hinged Lid Compostable Container Market
Containers
Intermediate Bulk Container (IBC) Market
Containers
Wide Mouth Jars Market
Containers
Insert Trays Market
Containers
Jerry Cans Market
Containers
Container Coating Market
Containers
Popcorn Containers Market
Containers
Rotomolded Containers Market
Containers
Asia and Africa Food Cans Market