
 PVC Container Market | 2026-2036
PVC Container Market Size, Share, and Industry Trends Forecast 2026-2036
PVC Container Market Analytics
Multi-source resin procurement is restructuring supply economics for PVC container converters. Amcor Plc leverages its global purchasing scale to offset raw material volatility. Berry Global Inc. sustains cost discipline through backward integration into preform manufacturing. Greiner Packaging International GmbH anchors European supply with specialized pharmaceutical-grade lines.
PVC containers are hollow vessels fabricated from polyvinyl chloride resin, typically formed via blow molding or injection molding to achieve wall thicknesses between 0.25 mm and 2.0 mm for chemical resistance and barrier performance. These containers serve primary functions in liquid storage, transit protection, and shelf-life extension across regulated industries. Blow molding dominates volume production for large-format chemical and beverage containers where throughput economics favor high cavitation tooling. Injection molding commands premium positioning in pharmaceutical packaging where dimensional precision and closure integrity determine compliance. Rigid containers face margin compression from polyethylene substitution in consumer goods, though chemical and pharmaceutical end uses preserve value through certification requirements.
EPA regulates vinyl chloride emissions under the Clean Air Act, compelling domestic manufacturers to deploy closed-loop vent recovery systems. REACH restricts phthalate plasticizers in EU-contact applications, redirecting formulation investment toward non-phthalate alternatives. FDA maintains extractables testing protocols for pharmaceutical PVC packaging, creating compliance barriers for uncertified imports. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Phthalate-free formulation mandates under REACH are forcing converters to rebuild compound portfolios from the resin stage upward. This regulatory compression is redistributing competitive advantage toward integrated compounders with captive plasticizer development capability.
Growth Catalysts
- REACH Annex XVII phthalate restrictions:Chemical and pharmaceutical packagers across the EU are accelerating qualification of non-phthalate PVC grades, expanding addressable volume for certified converters.
- Blow molding cavitation advances:High-output extrusion blow lines are compressing unit economics for large-format chemical containers, preserving PVC cost positioning against polyethylene substitution.
- German pharmaceutical processing cluster:Dense concentration of sterile fill-finish operations in the Rhine-Main corridor sustains premium demand for injection-molded vials and closure systems.
Market Restraints
- Vinyl chloride monomer supply concentration:European VCM production clusters in Germany and Belgium create geographic single-point vulnerability for regional converters.
- Polyethylene terephthalate barrier enhancement:Co-injected PET with oxygen scavenger layers is displacing PVC in parenteral nutrition applications where clarity and barrier converge.
- Clean Air Act vent recovery capex:EPA-mandated closed-loop systems add $2-4 million per facility for domestic blow molding operations.
Strategic Opportunities
- India CDSCO pharmaceutical packaging registration:Underpenetrated domestic sterile formulation capacity is importing European-certified PVC containers, creating local conversion opportunity.
- Multi-layer co-extrusion with EVOH:Oxygen barrier integration is unifying chemical resistance and shelf-life extension for agrochemical and pesticide end uses.
- EU Green Deal circular economy labeling:Recycled content certification pathways are opening premium positioning for converters with post-industrial regrind integration.
Industry Challenges
- FDA extractables protocol execution:Pharmaceutical packaging qualification timelines extend 18-24 months for new compound formulations, compressing product launch windows.
- Legacy blow mold retrofit complexity:Reconfiguring high-cavitation tooling for non-phthalate compound rheology requires process engineering expertise in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC Container Market |
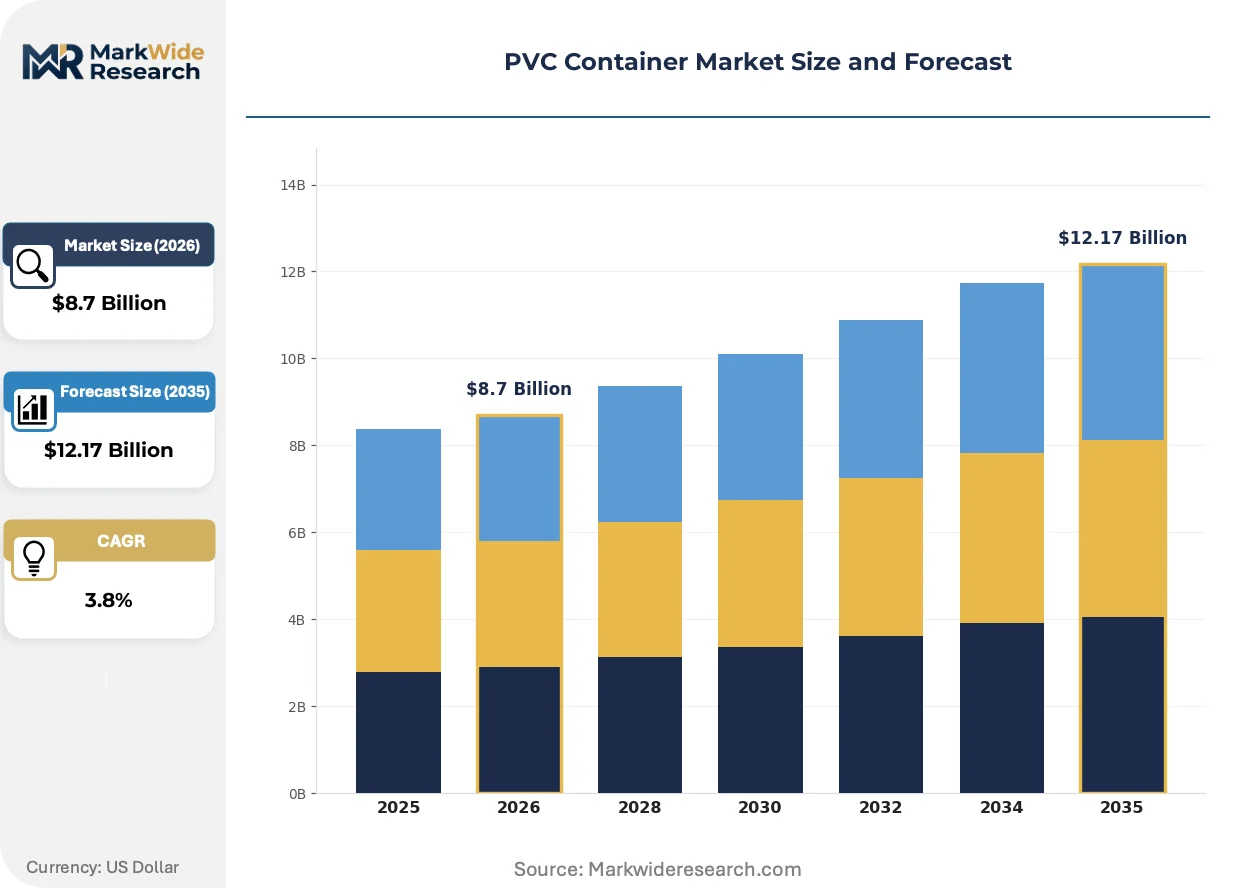
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blow Molding, Injection Molding, Thermoforming, Rigid Containers End Use Industry: Food & Beverage, Pharmaceuticals, Consumer Goods, Chemicals Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Amcor Plc, Berry Global Inc., Plastipak Holdings Inc., ALPLA Werke Alwin Lehner, Graham Packaging Co. LP, Silgan Holdings Inc., Winpak Ltd., Greiner Packaging International GmbH, Airlite Plastics Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC Container Market Evolving Landscape
Formulation chemistry and molding control systems are converging to resolve the historical trade-off between barrier performance and regulatory compliance. This technical unification is redrawing competitive boundaries between material categories.
Non-phthalate plasticizer systems based on cyclohexane dicarboxylic acid esters are unifying flexibility and migration resistance for pharmaceutical contact applications. German and Swiss pharmaceutical packagers are qualifying these compounds at accelerated pace for parenteral and ophthalmic dosage forms. The technology is unifying previously separate supply chains for medical-grade and general-purpose PVC, compressing compounder margins at the standard-grade tier.
REACH Annex XVII expansion to additional phthalate esters is redirecting R&D expenditure across European compounders. The industrial consequence is accelerated obsolescence of legacy di(2-ethylhexyl) phthalate formulations in food-contact and childcare applications. Pharmaceutical and medical device segments are responding with proactive compound requalification to preempt supply disruption.
Consolidated procurement by multinational pharmaceutical contract manufacturers is compressing supplier qualification cycles and unbundling technical service from unit pricing. Regional converters in Eastern Europe are displacing fragmented local suppliers through integrated design-to-delivery contracts. This concentration is most visible in Poland and the Czech Republic, where fill-finish capacity expansion is outpacing domestic packaging supply growth.
PVC Container Market Segmentation
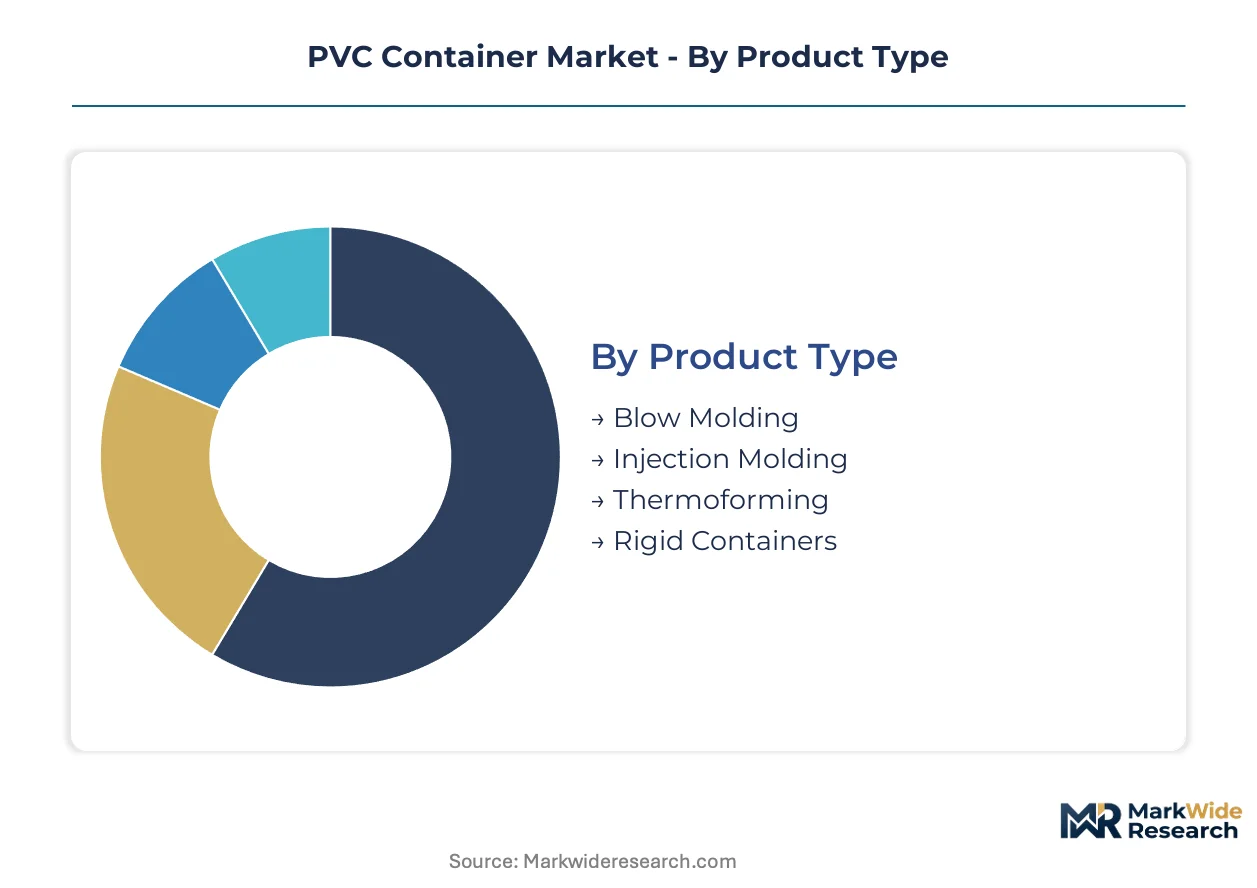
PVC container manufacturing splits across fundamentally different process economics. Blow molding commands volume through high-cavitation tooling, while injection molding extracts premium through dimensional precision demanded by regulated end uses. Understanding this segmentation exposes where margin pools concentrate versus where throughput dominates.
Product Type:
Volume production gravitates toward continuous extrusion processes. Premium positioning concentrates in precision molding where certification barriers protect pricing.
- Blow Molding:Extrusion or injection blow processes form hollow bodies with wall thicknesses optimized for chemical resistance and drop impact. Chemical processors in Germany's Rhine-Ruhr industrial corridor source large-format blow-molded drums and intermediate bulk containers under REACH-compliant compound specifications. Demand concentrates here because high-cavitation tooling amortizes capital cost across million-unit annual runs.
- Injection Molding:Closed-loop control systems achieve dimensional tolerances within 0.05 mm for pharmaceutical vial and closure applications. Sterile fill-finish operations in Switzerland and Germany's Baden-Württemberg region specify injection-molded PVC for parenteral packaging where closure integrity determines regulatory compliance. This segment captures the steepest margin premiums through FDA extractables certification requirements.
- Thermoforming:Sheet-based forming produces thin-walled trays and blister packs for unit-dose pharmaceutical applications.
- Rigid Containers:Compression-molded or rotational processes serve industrial bulk handling where structural rigidity outweighs barrier sophistication.
Mature deployment sits with blow molding. Newer deployment is concentrated in injection molding as pharmaceutical packaging qualification accelerates.
End Use Industry:
Regulatory intensity separates margin tiers. Pharmaceutical and chemical end uses preserve value through mandatory certification, while consumer goods face polyethylene substitution pressure.
- Pharmaceuticals:Primary packaging for parenteral solutions, ophthalmic preparations, and oral liquid dosages demands USP Class VI and EP 3.1 compliance. The German pharmaceutical processing cluster around Frankfurt and Basel sustains premium demand for non-phthalate PVC containers qualified under EMA guidelines. REACH Annex XVII phthalate restrictions are accelerating compound requalification timelines, consolidating supply toward integrated compounders with captive plasticizer development.
- Chemicals:Agrochemical, industrial solvent, and specialty chemical packaging prioritizes chemical resistance and UN transport certification. Belgian and Dutch chemical distributors specify multi-layer co-extruded PVC containers with EVOH barrier layers for pesticide formulations requiring shelf-life extension. Volume concentration here follows the Antwerp-Rotterdam chemical corridor's dense processing infrastructure.
- Food & Beverage:Edible oil and mineral water applications persist in Southern European markets where clarity and oxygen barrier requirements favor PVC over PET in specific niches.
- Consumer Goods:Personal care and household product containers face accelerating polyethylene and polypropylene displacement as brand owners pursue simplified recycling streams.
Mature deployment sits with chemicals. Newer deployment is concentrated in pharmaceuticals as contract manufacturers consolidate supplier bases.
Size:
Unit economics invert across the size spectrum. Small formats spread fixed certification costs across minimal resin volume, while extra-large formats amortize tooling investment through extended production runs.
- Small:Unit-dose vials, ampoules, and sample containers below 100 ml serve pharmaceutical clinical trial packaging and diagnostic reagent containment. Swiss and German diagnostic manufacturers specify small-format injection-molded PVC for automated filling line compatibility.
- Medium:100 ml to 5 liter containers span oral pharmaceutical syrups, agrochemical concentrates, and industrial cleaning formulations. Polish and Czech converters are expanding medium-format capacity to serve expanding Central European fill-finish operations.
- Large:5 liter to 50 liter drums and jerrycans dominate chemical distribution and food-grade edible oil handling. German chemical logistics providers specify large-format blow-molded PVC with integrated handles and tamper-evident closures under ADR transport regulations.
- Extra Large:Intermediate bulk containers and bulk storage vessels above 50 liters serve industrial chemical handling and pharmaceutical manufacturing supply chains.
Mature deployment sits with large formats. Newer deployment is concentrated in small formats as personalized medicine and unit-dose packaging expand.
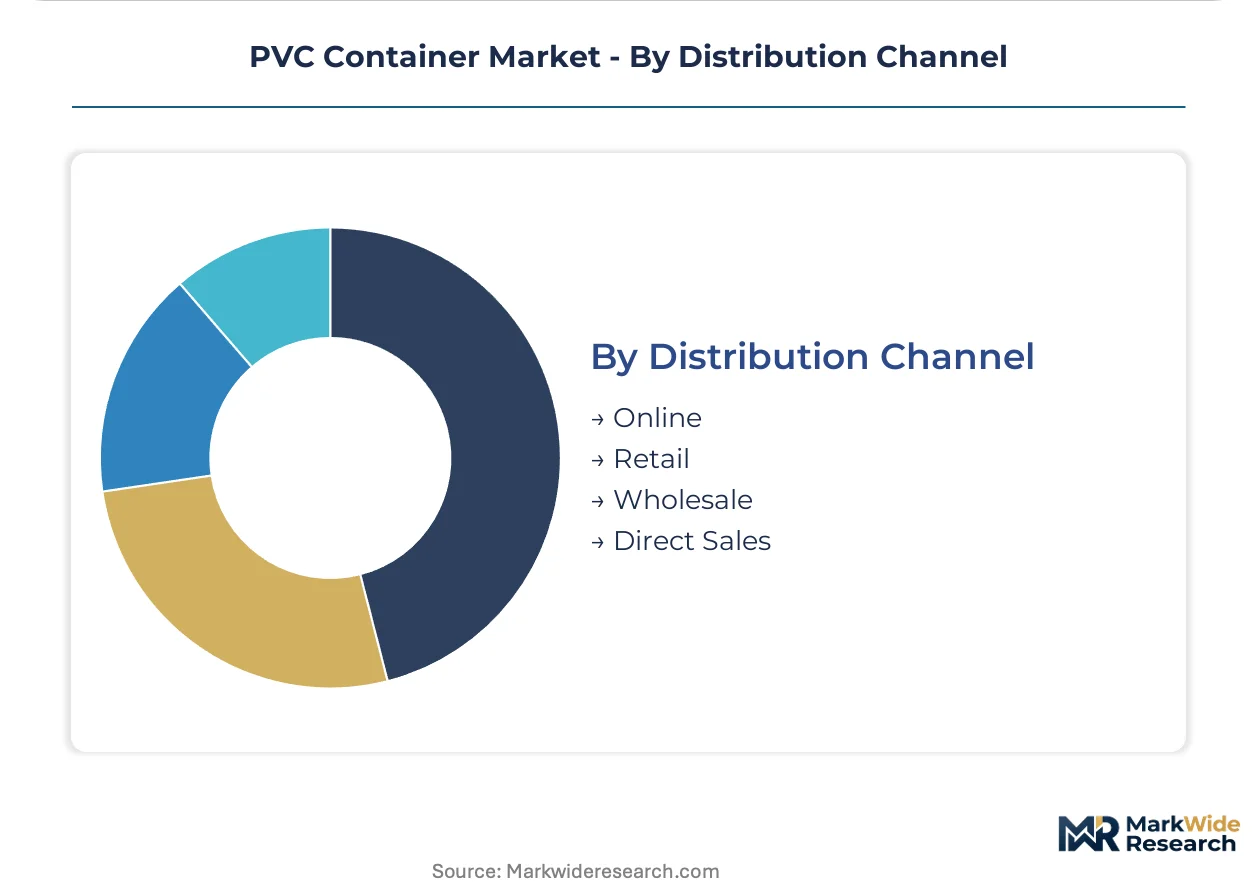
Distribution Channel:
Channel selection reflects customer scale and specification complexity. Direct relationships dominate where technical service requirements exceed standard product catalog depth.
- Direct Sales:Integrated design-to-delivery contracts with multinational pharmaceutical contract manufacturers and chemical processors. German and Swiss pharmaceutical packagers qualify direct suppliers through 18-24 month audit cycles, unbundling technical service from unit pricing.
- Wholesale:Distributor networks serve mid-scale chemical processors and regional food manufacturers with standardized container specifications. Benelux chemical distributors maintain regional PVC container inventory for just-in-time delivery to Antwerp-Rotterdam port operations.
- Retail:Hardware and packaging supply stores serve small-batch chemical handlers and artisan food producers with off-the-shelf container selections.
- Online:E-procurement platforms penetrate small-order pharmaceutical research and specialty chemical sampling applications where specification standardization permits remote qualification.
Mature deployment sits with wholesale. Newer deployment is concentrated in direct sales as pharmaceutical contract manufacturers consolidate supply bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vinyl chloride monomer production clusters in Germany and Belgium anchor European supply for PVC container converters. German chemical infrastructure along the Rhine-Ruhr corridor processes the majority of regional resin demand. Asian capacity expansion in India and China is redirecting trade flows for pharmaceutical-grade compounds.
Germany
The Rhine-Main corridor hosts dense sterile fill-finish operations demanding injection-molded vials and closure systems. REACH Annex XVII phthalate restrictions are accelerating compound requalification timelines across Baden-Württemberg pharmaceutical packagers. BASF and INEOS VCM production sites in Ludwigshafen and Cologne supply captive resin to regional converters.
United States
EPA Clean Air Act vent recovery mandates are compelling domestic blow molding facilities to deploy closed-loop systems. FDA extractables testing protocols create compliance barriers for pharmaceutical packaging imports. Gulf Coast petrochemical corridors in Texas and Louisiana concentrate resin production for container manufacturing.
India
CDSCO pharmaceutical packaging registration requirements are opening local conversion opportunities as domestic sterile formulation capacity expands. Maharashtra and Gujarat pharmaceutical clusters import European-certified PVC containers for contract manufacturing operations. Mumbai-Pune industrial corridor is attracting regional converter investment to replace imported packaging.
Switzerland
Swissmedic guidelines for parenteral packaging sustain premium demand for non-phthalate PVC compounds in Basel pharmaceutical operations. Swiss and German diagnostic manufacturers specify small-format injection-molded containers for automated filling line compatibility. Rhine-Neckar chemical logistics networks connect Swiss packagers to German resin supply.
Belgium
Antwerp-Rotterdam port infrastructure supports chemical distribution networks specifying multi-layer co-extruded containers with EVOH barrier layers. INEOS VCM production in the Port of Antwerp supplies regional converters serving agrochemical and pesticide formulation markets. Flemish chemical processors maintain just-in-time inventory relationships with Dutch and German packaging suppliers.
PVC Container Market Competitive Landscape
Capacity expansion dominates the current landscape as converters respond to pharmaceutical packaging qualification backlogs. The vendor base splits between integrated multinational compounders and specialized regional molders serving regulated end uses. Three archetypes define competitive positioning: global resin-integrated packagers, European pharmaceutical-grade specialists, and Asian emerging-market converters. M&A activity concentrates in Central European markets where contract manufacturer consolidation is compressing supplier bases. Technology licensing agreements for non-phthalate compound formulations are redistributing competitive advantage toward integrated R&D capabilities.
Among global resin-integrated packagers, Amcor Plc and Berry Global Inc. exemplify scale-driven procurement structures that offset raw material volatility through purchasing power concentration. Within the European pharmaceutical-grade tier, Greiner Packaging International GmbH anchors specialized production lines serving EMA-compliant sterile packaging demand. These three entities represent distinct competitive vectors: multinational purchasing scale, backward integration into preform manufacturing, and captive pharmaceutical-grade line specialization.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Plastipak Holdings Inc. |
| ALPLA Werke Alwin Lehner |
| Graham Packaging Co. LP |
| Silgan Holdings Inc. |
| Winpak Ltd. |
| Greiner Packaging International GmbH |
| Airlite Plastics Co. |
| Others |
Value Network & Pricing Analysis
Vinyl chloride monomer pricing volatility in the Rhine-Ruhr corridor cascades through compounder margins to pharmaceutical-grade container premiums, with German converters passing through resin cost swings via contract escalation clauses while spot chemical markets absorb more immediate adjustments.
Pricing Analysis
Warranty and technical service bundling separates direct sales contracts from wholesale transactions, with pharmaceutical packagers paying 15-25% premiums for 18-24 month extractables qualification support. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification status, volume commitment scale, and geographic delivery radius. Cost compression in standard-grade blow-molded chemical containers is intensifying because polyethylene substitution threatens volume erosion. Contract chemical processors exhibit highest price sensitivity due to formulaic pass-through arrangements, while sterile fill-finish operations show lowest sensitivity given regulatory compliance lock-in.
Supply Chain Analysis
Single-source vulnerability sits with European VCM production concentrated in Germany and Belgium, where INEOS and BASF facilities supply regional converters under long-term offtake agreements. Raw material flows draw from ethylene feedstock clusters in the Antwerp-Rotterdam port complex, phthalate and non-phthalate plasticizer compounds from Swiss and German specialty chemical producers, and calcium-zinc stabilizer systems from Austrian suppliers. Tariff exposure on imported pharmaceutical-grade compounds from India creates supply disruption risk for CDSCO-registered packagers. Distribution runs through direct sales channels for multinational pharmaceutical contract manufacturers and wholesale networks serving Benelux chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive plasticizer development and sterile fill-finish line certification represents the dominant vertical-integration race, as compounders seek to capture margin pools previously allocated to separate formulation suppliers.
For Market Incumbents: Acquire specialized pharmaceutical-grade injection molding assets in the Rhine-Main corridor to consolidate EMA-qualified capacity before contract manufacturer supplier base compression accelerates. Defend against polyethylene substitution in chemical containers by embedding multi-layer EVOH barrier technology into standard product offerings, preserving PVC cost positioning through performance differentiation rather than price competition alone. For New Entrants and Emerging Players: Launch via direct sales partnerships with Indian CDSCO-registered pharmaceutical contract manufacturers seeking localized packaging supply as domestic sterile formulation capacity expands. Target medium-format injection-molded containers for Polish and Czech fill-finish operations where regional converter capacity lags demand growth, penetrating through integrated design-to-delivery contracts that bundle technical qualification service with unit supply. For Investors and Strategic Acquirers: REACH Annex XVII expansion to additional phthalate esters is the leading indicator that integrated compounders with captive non-phthalate R&D capabilities will consolidate fragmented regional molding capacity over the next decade. Acquisition targets should display backward integration into preform manufacturing or specialized pharmaceutical-grade line certification, with compound requalification timeline compression serving as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plasticizer Development | Captive formulation capability protects margin pools from REACH-mandated compound obsolescence cycles. |
| Multi-layer Co-extrusion Capacity Expansion | EVOH barrier integration unifies chemical resistance and shelf-life extension for agrochemical end uses. |
| Pharmaceutical-grade Line Certification Investment | FDA extractables qualification creates 18-24 month barriers against uncertified import competition. |
| Regional Converter Consolidation | Central European M&A responds to contract manufacturer procurement base compression in Poland and Czech Republic. |
| Post-industrial Regrind Integration | EU Green Deal circular economy labeling opens premium positioning for certified recycled content pathways. |
Research Methodology
Independent corroboration across converter operations managers, pharmaceutical packaging procurement leads, and chemical distributor category buyers underwrites the qualitative findings in this study. Primary interviews with sterile fill-finish line engineers, regulatory affairs specialists at EMA-notified bodies, and resin procurement directors at multinational compounders were validated against secondary sources including REACH Annex XVII amendment filings, FDA extractables guidance documents, CDSCO pharmaceutical packaging registration databases, and SEC 10-K disclosures from listed packaging converters. Bottom-up volume modeling across blow molding, injection molding, thermoforming, and rigid container process categories was triangulated against top-down resin consumption estimates from European chemical industry associations.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, end-use industry, size format, and distribution channel. Pharmaceutical packaging qualification timelines, VCM production capacity utilization at German and Belgian facilities, and non-phthalate compound adoption curves served as industry-specific forecast inputs. CAGRs were derived from regression analysis of historical shipment data against regulatory implementation schedules and contract manufacturer capacity expansion announcements.
REACH enforcement intensity, FDA inspection backlog duration, and vinyl chloride monomer supply disruption events are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Stainless Steel Cask Market
Containers
HDPE Bottles Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
Lab Storage Container Market
Containers
Containerboard Market
Containers
Canning Jars Market
Containers
HDPE Crates Market
Containers
Thermoformed Containers Market
Containers
Edible Oil Cans Market
Containers
Laminated Bulk Bins Market
Containers
Container Coating Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Carboy Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
North America Insulated Shipping Containers Market
Containers
Tottle Containers Market