
 Global Flexitanks Market | 2026-2036
Global Flexitanks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexitanks Market Foresight
The flexitank supply base is consolidating around two distinct performance tiers: multi-layer barrier systems for sensitive food-grade liquids versus single-layer commodity configurations for industrial chemicals. Braid Logistics leverages its European manufacturing footprint to sustain premium certification standards for edible oil shipments. Qingdao BLT Packing Industrial Co., Ltd. anchors volume production of polyethylene flexitanks for Asian chemical exporters. SIA Flexitanks differentiates through specialized nylon-reinforced designs that compete on puncture resistance in rough-handling corridors.
A flexitank is a collapsible, single-use or limited-reuse flexible container engineered from welded polyethylene, vinyl, or nylon laminates, typically rated for 16,000 to 24,000 liters of non-hazardous liquid cargo, designed to fit within standard 20-foot ISO shipping frames. The primary commercial purpose is to convert dry van containers into bulk liquid transport assets without dedicated tank infrastructure, slashing repositioning costs for shippers of wine, palm oil, and latex. Multi-layer configurations command the deepest margin pools because their ethylene-vinyl alcohol or aluminum oxide barriers prevent oxidation in edible oils and beverages. Single-layer polyethylene dominates unit volume in chemicals and industrial liquids where oxygen ingress poses minimal spoilage risk. Logistics companies represent the most concentrated end-user channel, though beverage manufacturers are pulling fastest on food-grade certified supply as craft spirits and bulk wine trade expand.
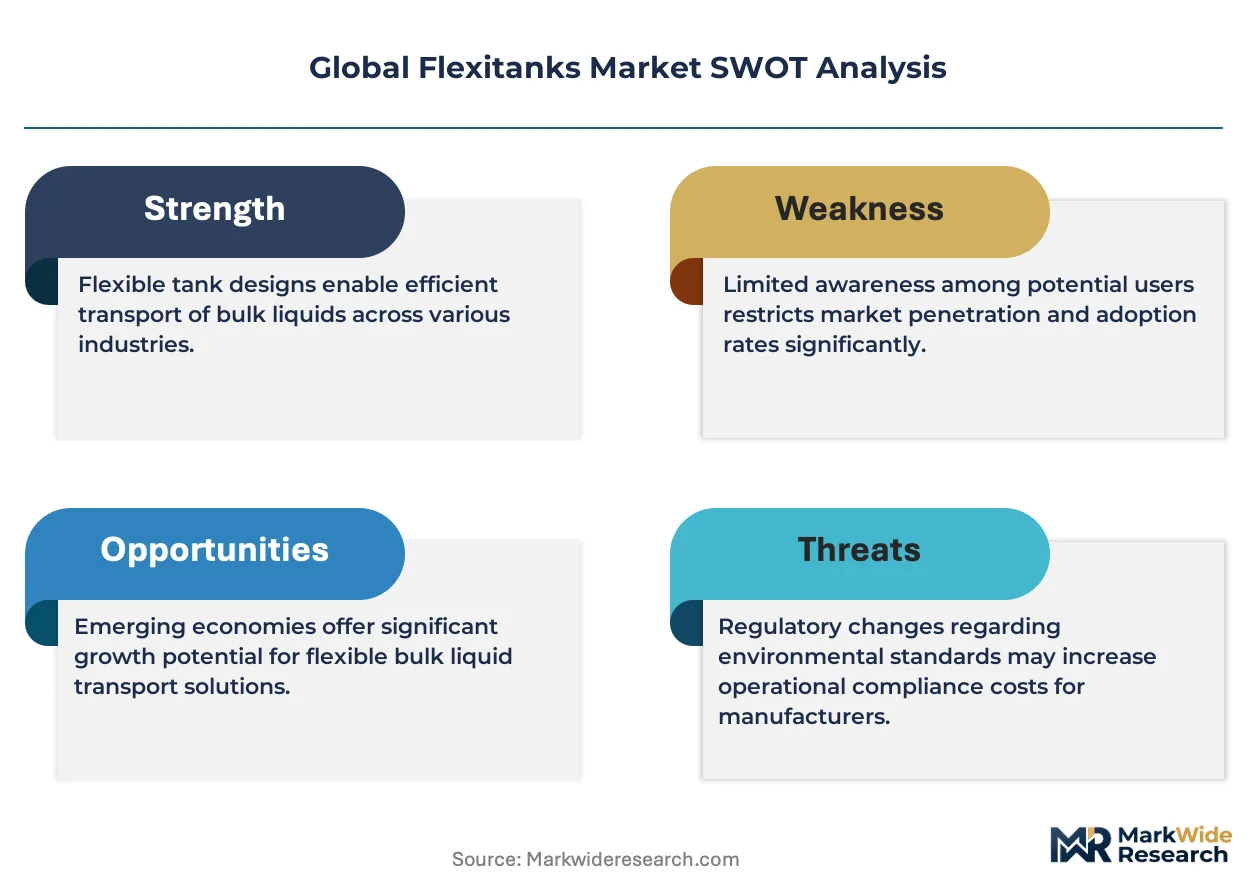
FDA food-contact regulations and EU REACH compliance on migratory substances shape material selection and adhesive chemistry for flexitanks serving North American and European food chains. China's GB standards for plastic packaging, enforced by SAMR, dictate tensile strength and seam weld testing protocols that determine market access for domestic and imported products. Stakeholders must monitor evolving extended producer responsibility frameworks across the EU Green Deal and parallel state-level packaging laws in the US, as single-use flexitank disposal costs could alter total-cost-of-ownership calculations against reusable ISO tank alternatives.
Market Dynamics
The flexitank market is bifurcating around barrier-performance tiers, with food-grade multi-layer systems commanding premium positioning against commodity single-layer chemical configurations as logistics operators recalibrate total-cost-of-ownership models.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility frameworks are accelerating converter investment in recyclable polyethylene constructions to preempt compliance costs.
- Edible oil logistics expansion:Bulk palm oil and sunflower oil shippers are displacing drum packaging with flexitank configurations to cut repositioning expenditure.
- Craft spirits distribution:Small-batch beverage producers are pulling food-grade certified supply for bulk wine and spirits transport into emerging consumption clusters.
Market Restraints
- Polyethylene resin volatility:Feedstock price swings compress margin predictability for single-layer commodity producers serving industrial chemical segments.
- Single-use disposal liability:Landfill and incineration costs under evolving EU packaging law are narrowing the cost gap against reusable ISO tank alternatives.
- Oxygen barrier limitations:Standard polyethylene constructions cannot match ethylene-vinyl alcohol performance for oxidation-sensitive edible oils.
Strategic Opportunities
- India agricultural exports:Mango pulp and ghee producers remain underpenetrated by certified food-grade flexitank suppliers despite expanding cold-chain infrastructure.
- Nylon-reinforced rough-handling corridors:Puncture-resistant laminate designs can capture premium positioning in African and Central Asian overland routes.
- Carbon accounting integration:EU CSRD disclosure requirements are creating first-mover advantage for suppliers offering lifecycle-emission-certified product lines.
Industry Challenges
- FDA food-contact certification timelines:Migratory substance testing protocols delay market entry for new adhesive chemistries by 18-24 months.
- Weld seam quality consistency:Automated heat-sealing equipment requires skilled technician calibration to prevent field failures under dynamic load conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexitanks Market |
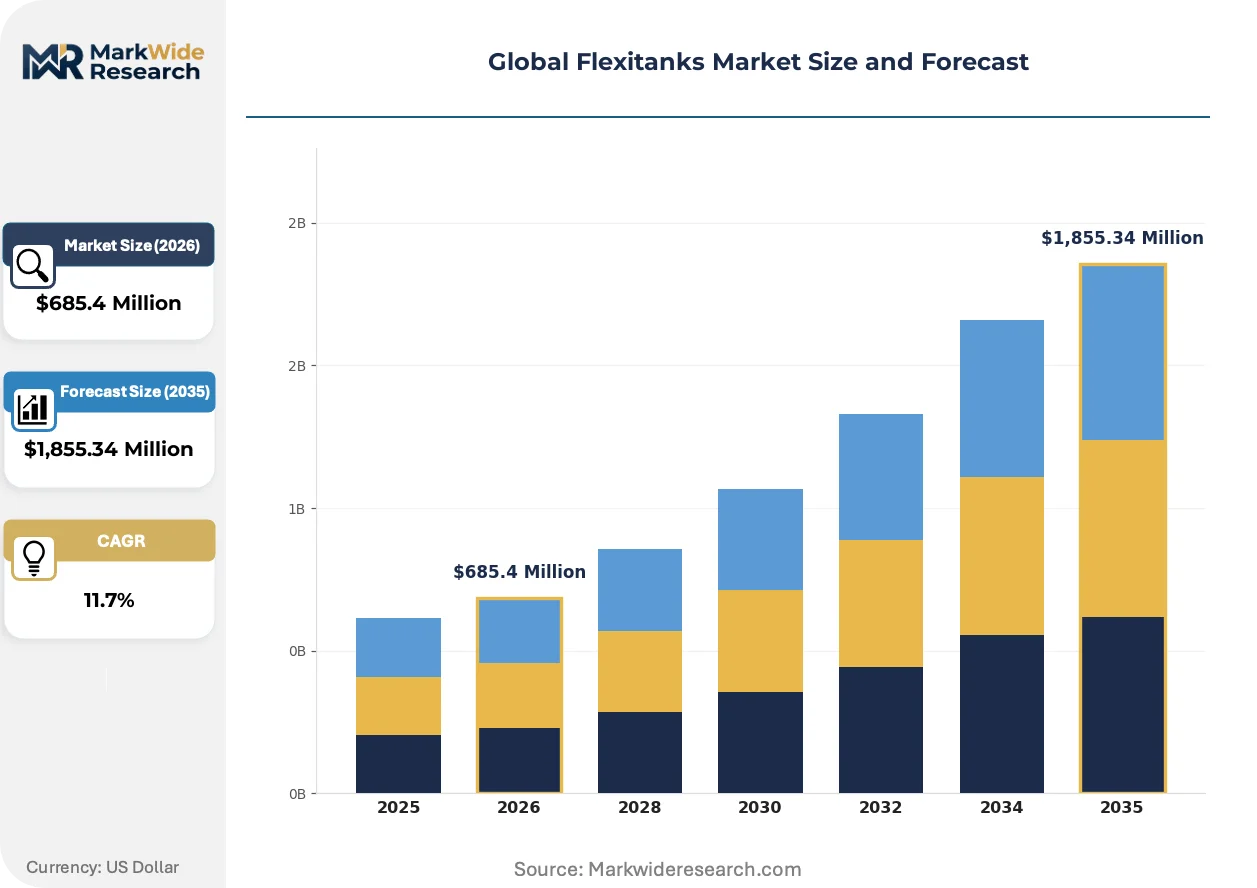
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,855.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-layer, Multi-layer, Polyethylene, Vinyl, Nylon Application: Edible Oils, Chemicals, Beverages, Water Transport, Industrial Liquids End User: Logistics Companies, Beverage Manufacturers, Chemical Processors, Water Treatment Firms Packaging Type: Bulk Bags, Iso Tanks, Drums, Intermediate Bulk Containers, Collapsible Tanks |
| Companies Covered | Braid Logistics, Bulk Liquid Solutions, SIA Flexitanks, Qingdao BLT Packing Industrial Co., Ltd., Environmental Packaging Technologies, Trans Ocean Bulk Logistics, TRUST Flexitanks, Hengxin Plastic Co., Ltd., Rishi FIBC Solutions Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexitanks Market Shifts & Advancements
Material science advances and regulatory disclosure requirements are compressing product development cycles while reshaping procurement criteria toward verifiable sustainability credentials.
Multi-layer barrier laminates incorporating ethylene-vinyl alcohol or aluminum oxide interlayers are consolidating technical leadership in edible oil and beverage applications. Premium logistics operators are specifying these configurations for oxidation-sensitive cargoes despite 40-60% unit cost premiums over single-layer alternatives. The technology is consolidating supplier margins around certification-holding converters with in-house multilayer extrusion capability.
REACH compliance on migratory substances is tightening adhesive chemistry selection for European food-chain applications. ECHA substance restriction proposals are forcing reformulation of conventional solvent-based bonding agents toward water-curable alternatives. Wine and spirits exporters are responding by consolidating procurement around converters with pre-validated EU regulatory dossiers.
Logistics operators are unbundling equipment procurement from freight forwarding contracts to negotiate direct supply relationships with flexitank manufacturers. Third-party logistics providers are losing equipment specification control as bulk liquid shippers seek captive supply agreements with certified converters. This disintermediation is most visible in China, where Qingdao and Tianjin port clusters have spawned dedicated procurement offices for major edible oil traders.
Global Flexitanks Market Segmentation
Flexitank procurement decisions pivot on barrier-performance tradeoffs against repositioning economics. Shippers of oxidation-sensitive cargoes prioritize multi-layer laminates despite unit cost premiums, while commodity chemical movers optimize for polyethylene disposability.
Product Type:
Upgrade cycles accelerate where barrier specifications outpace existing fleet capabilities, forcing logistics operators to retire single-layer inventory ahead of depreciation schedules.
- Multi-layer:Ethylene-vinyl alcohol or aluminum oxide interlayers block oxygen ingress for edible oil and beverage applications. European palm oil shippers mandate these configurations under EFSA contact-material protocols, absorbing 40-60% cost premiums to prevent cargo oxidation.
- Single-layer:Homogeneous polyethylene constructions dominate industrial chemical logistics where spoilage risk is minimal. Chinese chemical exporters at Qingdao and Tianjin ports deploy these units at scale, prioritizing unit economics over barrier performance.
- Polyethylene:The base resin for commodity flexitank production, subject to feedstock volatility that compresses converter margins.
- Vinyl:Alternative polymer formulations selected for specific chemical compatibility requirements in specialty industrial applications.
- Nylon:Reinforced laminate designs targeting puncture resistance in rough-handling corridors across African and Central Asian overland routes.
Volume placements concentrate in single-layer polyethylene; the faster expansion belongs to multi-layer barrier systems.
Application:
Cost tier stratification separates oxidation-sensitive food chains from commodity chemical flows, with certification requirements widening the procurement gap between segments.
- Edible Oils:Bulk palm oil and sunflower oil shippers displace drum packaging to cut repositioning expenditure. EU REACH compliance on migratory substances shapes adhesive chemistry selection, consolidating procurement around converters with pre-validated regulatory dossiers.
- Beverages:Craft spirits and bulk wine trade expansion pulls food-grade certified supply fastest. Small-batch producers seek direct supply relationships with certified converters, bypassing third-party logistics equipment specification control.
- Chemicals:Non-hazardous industrial liquid transport represents the highest unit-volume deployment of single-layer configurations.
- Water Transport:Emergency relief and bulk potable water logistics drive demand for collapsible, single-use containment.
- Industrial Liquids:Latex, lubricants, and glycerin shipments prioritize cost minimization over barrier sophistication.
Shipment volumes peak in edible oils; beverage logistics is climbing the fastest as craft production scales.
End User:
Customer-type concentration shifts as bulk liquid shippers internalize equipment procurement, disintermediating traditional logistics intermediaries.
- Logistics Companies:Third-party providers historically controlled equipment specification but now lose procurement authority as shippers seek captive supply agreements with certified converters.
- Beverage Manufacturers:Wineries and distilleries consolidate direct relationships with flexitank producers to secure food-grade certification chains. FDA food-contact testing timelines delay new adhesive chemistry adoption by 18-24 months.
- Chemical Processors:Industrial liquid producers optimize for total-cost-of-ownership, accepting higher per-unit flexitank costs against ISO tank repositioning liabilities.
- Water Treatment Firms:Municipal and industrial water logistics operators deploy collapsible tanks for non-potable and emergency potable applications.
Procurement authority concentrates in logistics companies; beverage manufacturers are gaining share fastest through vertical supply integration.
Packaging Type:
Competitive displacement dynamics favor flexitanks against rigid alternatives where empty return logistics erode reusable container economics.
- Iso Tanks:Dedicated stainless steel tank containers face competitive pressure from flexitank conversions of standard dry vans. Single-use disposal liability under evolving EU packaging law narrows the cost gap against reusable alternatives.
- Drums:Steel and plastic drum packaging loses share to flexitank bulk conversions in edible oil and chemical logistics, driven by handling efficiency and repositioning cost elimination.
- Bulk Bags:Flexible intermediate bulk containers compete for dry flowable cargoes but lack liquid containment capability.
- Intermediate Bulk Containers:Rigid IBC totes retain position in hazardous liquid segments where flexitank certification is unavailable.
- Collapsible Tanks:Standalone flexible containment for static storage and emergency deployment, distinct from ISO-frame flexitank configurations.
Installed base concentrates in drums and ISO tanks; flexitank conversions are expanding most quickly in edible oil and beverage corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qingdao anchors flexitank manufacturing density, with Tianjin and Shanghai port clusters driving procurement office concentration for edible oil traders seeking direct converter relationships.
China
Qingdao BLT Packing and Hengxin Plastic dominate polyethylene volume production for chemical exporters. SAMR enforces GB standards on tensile strength and seam weld testing that determine domestic market access. Tianjin port clusters host dedicated procurement offices where major edible oil traders negotiate captive supply agreements with certified converters.
United States
Beverage manufacturers in California and Pacific Northwest wine regions pull food-grade certified supply for bulk spirits transport. FDA food-contact regulations on migratory substances shape adhesive chemistry selection for North American food chains. Houston chemical corridors deploy single-layer configurations for non-hazardous industrial liquid logistics.
Germany
Braid Logistics leverages European manufacturing footprints to sustain premium certification standards for edible oil shipments. ECHA REACH compliance tightens adhesive chemistry selection, forcing reformulation toward water-curable alternatives. Hamburg port infrastructure supports multi-layer barrier system deployment for oxidation-sensitive cargo.
India
Mango pulp and ghee producers in Maharashtra and Gujarat remain underpenetrated by certified food-grade suppliers despite expanding cold-chain infrastructure. FSSAI packaging regulations govern food-contact material safety for domestic edible oil logistics. Mumbai port clusters see accelerating drum-to-flexitank conversion as palm oil shippers cut repositioning expenditure.
Brazil
Bulk soybean oil exporters in São Paulo state displace drum packaging with flexitank configurations to access European markets. ANVISA pharmaceutical and food packaging standards influence material selection for edible oil contact applications. Santos port terminals handle rising flexitank conversion volumes for agricultural commodity flows.
Global Flexitanks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier-performance tiers, with multi-layer certification holders capturing 40-60% unit cost premiums against single-layer polyethylene converters. The supply base consolidates around two performance tiers: food-grade barrier systems versus industrial chemical configurations. Three archetypes dominate: European certification-heavy specialists, Asian volume-scale polyethylene producers, and nylon-reinforced rough-handling specialists. Competitive moves center on disintermediation of logistics providers through direct shipper-converter agreements and backward integration into multilayer extrusion capability.
Among European specialists, Braid Logistics exemplifies premium-tier positioning through certification-holding operations. Qingdao BLT Packing Industrial Co., Ltd. anchors volume-scale production from China's Shandong manufacturing base. SIA Flexitanks occupies the puncture-resistant specialization tier, with nylon-reinforced designs targeting rough-handling corridors. These three represent the structural archetypes—certification-led, scale-driven, and specialization-focused—that define competitive positioning across barrier-performance tiers.
| Leading Market Players |
|---|
| Braid Logistics |
| Bulk Liquid Solutions |
| SIA Flexitanks |
| Qingdao BLT Packing Industrial Co., Ltd. |
| Environmental Packaging Technologies |
| Trans Ocean Bulk Logistics |
| TRUST Flexitanks |
| Hengxin Plastic Co., Ltd. |
| Rishi FIBC Solutions Pvt Ltd |
| Others |
Supply & Pricing Matrix
Edible oil traders operating through Qingdao and Tianjin port clusters command substantial leverage over flexitank converters, compressing margins on single-layer polyethylene configurations while sustaining premium positioning for multi-layer barrier systems certified under EU REACH protocols.
Pricing Analysis
Barrier-performance outcomes anchor flexitank pricing, with oxidation-prevention yields justifying 40-60% premiums for ethylene-vinyl alcohol laminates over commodity polyethylene. Price differentiation rests on certification grade and multilayer extrusion capability. Cost compression in single-layer chemical tiers is intensifying because feedstock volatility erodes converter margins. Chemical processors exhibit highest price sensitivity; beverage manufacturers absorb premiums for food-contact compliance.
Supply Chain Analysis
Skilled technician availability for automated heat-sealing calibration constrains quality-consistent output in Shandong, Jiangsu, and Zhejiang manufacturing zones. Raw material flows draw from polyethylene resin producers, adhesive compounders, and ethylene-vinyl alcohol film suppliers. Single-source vulnerability in multilayer barrier film imports from Japan and South Korea threatens food-grade supply continuity. Distribution runs through port-proximate procurement offices where major traders negotiate direct converter relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexitank supply is tightening around certified multilayer capacity, with in-house extrusion capability bottlenecks propping pricing power for incumbent converters holding EFSA-validated dossiers.
For Market Incumbents: To counter disintermediation by bulk liquid shippers seeking direct converter agreements, deepen captive supply relationships through backward integration into multilayer extrusion and accelerate FDA food-contact certification timelines for water-curable adhesive chemistries. For New Entrants and Emerging Players: Direct-to-shipper digital procurement platforms unlock white-space penetration in India's undercertified mango pulp and ghee logistics, with FSSAI-compliant barrier systems as the most penetrable entry vector against established logistics intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale converters with dormant EU regulatory dossiers in Germany and the Netherlands, with long-term viability hinging on CSRD-aligned lifecycle-emission certification capabilities; watch EU extended producer responsibility implementation timelines as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Multilayer Extrusion | Captures margin pools from barrier-film imports while accelerating EFSA compliance timelines. |
| Water-Curable Adhesive Reformulation | Preempts ECHA substance restrictions under REACH protocols for European food-chain access. |
| Direct Shipper-Converter Procurement Agreements | Disintermediates third-party logistics providers controlling equipment specification in China. |
| Nylon-Reinforced Rough-Handling Designs | Captures premium positioning in African and Central Asian overland corridors with puncture risks. |
| Lifecycle-Emission Certification Programs | Creates first-mover advantage under EU CSRD disclosure requirements for carbon-accounting integration. |
Research Methodology
Trade databases, customs filings, and converter regulatory dossiers formed the secondary backbone, cross-referenced against primary interviews with logistics procurement directors, flexitank plant managers, edible oil trader supply chain leads, and EFSA regulatory affairs specialists. Bottom-up unit economics triangulated against top-down trade flow analysis to validate volume and value estimates.
Bottom-up modeling segmented the market by barrier-performance tier, application sensitivity, end-user procurement authority, and regional certification cluster across the analysis window. CAGRs derived from installed base turnover rates and upgrade-cycle compression in food-grade logistics. Key inputs included polyethylene resin price trajectories and EU packaging law evolution timelines.
The model holds under stable regulatory enforcement trajectories; deviation in ECHA substance restriction acceleration or SAMR GB standard tightening would shift certification timelines and converter margin structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Cylindrical Cans Market
Containers
Light Resistant Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
PET Hinged Containers Market
Containers
Wooden Crates Market
Containers
Slide Top Tins Market
Containers
Compartment Trays Market
Containers
Cubitainer Market
Containers
Oblong Jar Market
Containers
Sample Containers Market
Containers
Packaging Bins Market
Containers
Rotomolded Containers Market
Containers
Die Cut Display Container Market
Containers
Container Market
Containers
Thermoformed Containers Market
Containers
Asia and Africa Food Cans Market