
 PET Hinged Containers Market | 2026-2036
PET Hinged Containers Market Size, Share, and Industry Trends Forecast 2026-2036
PET Hinged Containers Market Analytics
North American thermoforming capacity is rebalancing toward post-consumer recycled PET lines as virgin resin volatility pressures converter margins. Dart Container leverages backward integration into resin compounding to secure feedstock consistency across its hinged container portfolio. Berry Global anchors its position through multi-site thermoforming scale that sustains national distribution contracts with protein processors and deli chains. Pactiv competes on rapid-turn customization for regional food service distributors, navigating shorter run lengths and seasonal SKU proliferation.
PET hinged containers are thermoformed or injection-molded polyethylene terephthalate vessels with integral living hinges, typically manufactured in gauges ranging from ten to thirty mils to balance clarity, snap retention, and nested stacking efficiency for refrigerated and ambient food distribution. Clear containers dominate dollar contribution due to premium placement in deli, bakery, and prepared meal cases where visual merchandising drives purchase conversion. Microwaveable containers represent the fastest-expanding product type as convenience-oriented retailers and ghost kitchen operators specify dual-ovenable performance to reduce packaging changeovers. Food service end users command the largest volume share, though pharmaceutical compliance-grade demand is building around child-resistant latch configurations and USP Class VI material documentation.
FDA maintains food-contact notification requirements for recycled PET sources, while EPA state-delegated programs in California and Maine enforce extended producer responsibility frameworks that alter resin sourcing economics for domestic molders. CE marking under EU packaging and packaging waste directives governs export-bound volumes, with REACH SVHC thresholds influencing additive packages for colorants and slip agents. Stakeholders must monitor evolving post-consumer content mandates across multiple state jurisdictions and assess captive recycling investments against toll-compounding alternatives before committing capacity expansion.
Market Dynamics
Post-consumer recycled PET mandates across multiple state jurisdictions are redirecting converter capital toward rPET thermoforming lines, compressing virgin resin demand curves and reconfiguring supplier-buyer contracting structures.
Growth Catalysts
- Extended Producer Responsibility frameworks:California and Maine state programs impose post-consumer content minimums that pull converters toward rPET investments, locking in multi-year feedstock agreements with reclaimers.
- Ghost kitchen proliferation:Delivery-native food preparation operators specify microwaveable hinged formats to eliminate packaging changeovers between cold storage and hot service, accelerating dual-ovenable SKU adoption.
- Centralized protein processing:US and German deli chains consolidate procurement through national distribution contracts that favor high-volume thermoformers with multi-site manufacturing footprints.
Market Restraints
- rPET feedstock volatility:Bottle bale supply fluctuations and reclaiming capacity constraints create input cost instability that compresses converter margins unpredictably.
- Single-use plastic restrictions:State-level bans on conventional petroleum-based containers in Vermont and Connecticut force rapid formulation pivots before alternative resin streams mature.
- Competing substrate substitution:Molded fiber and aluminum formats capture premium prepared-meal placements where microwave performance and sustainability credentials intersect.
Strategic Opportunities
- Pharmaceutical compliance-grade expansion:Child-resistant latch configurations and USP Class VI documentation open unit-dose packaging demand from compound pharmacies and clinical trial suppliers.
- EU Green Deal alignment:CE-marked containers with verified recycled content penetrate export-bound volumes as REACH SVHC thresholds reshape additive packages for colorants and slip agents.
- Convenience retailer private label:Prepared meal case resets at 7-Eleven and Lawson Japan create white-space for clear hinged formats with extended shelf-life barrier properties.
Industry Challenges
- Thermoforming technician scarcity:Skilled die-set and thin-gauge process engineers command premium wages as rPET line conversions outpace vocational training pipeline output.
- FDA food-contact notification timelines:Recycled PET source approvals stretch 12-18 months, delaying product launches and freezing inventory positions during regulatory review.
- Legacy ERP integration:Batch traceability requirements for pharmaceutical-grade production force middleware investments that strain mid-cap converter IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Hinged Containers Market |
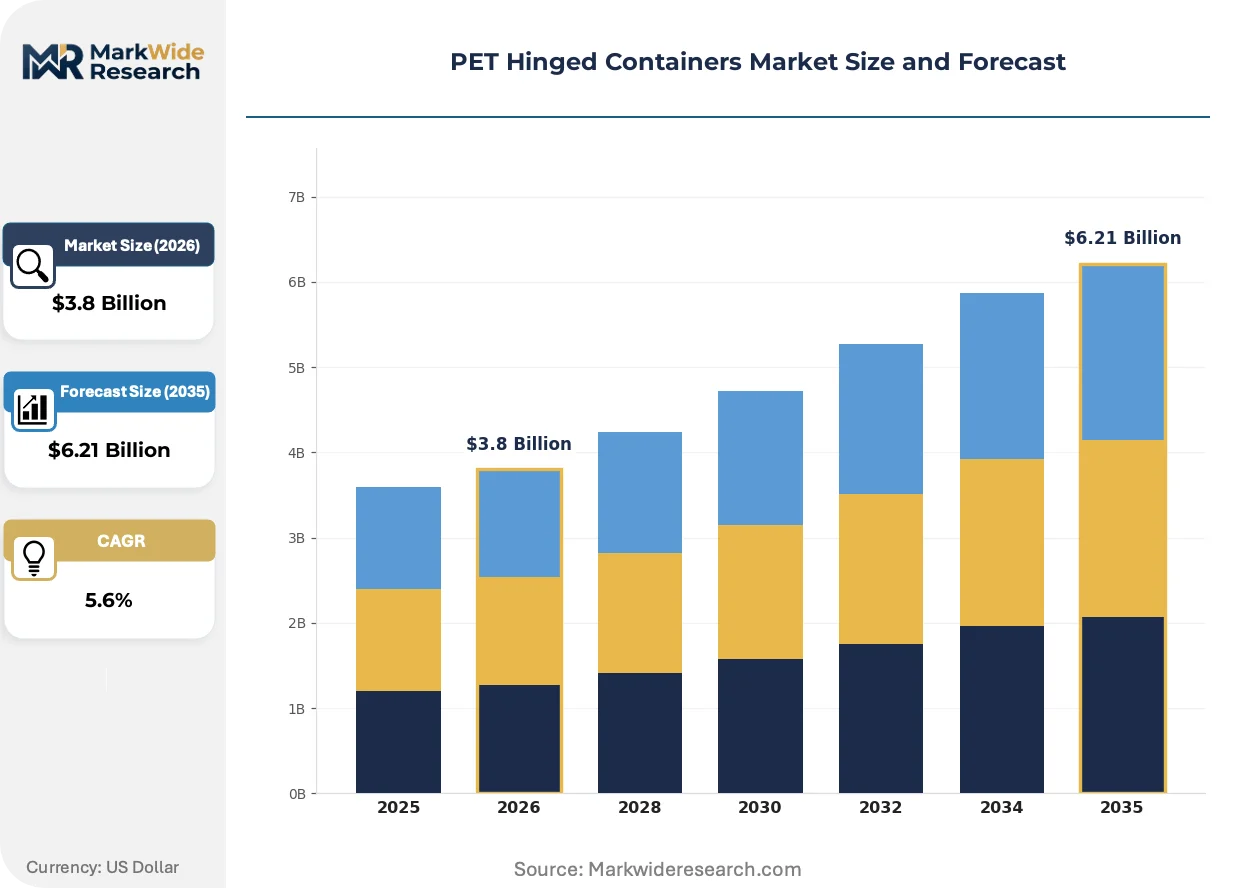
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Containers, Colored Containers, Microwaveable Containers, Biodegradable Containers End User: Food Service, Retail, Pharmaceutical, Consumer Goods Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Dart Container, Pactiv, Berry Global, Amcor, Sonoco Products Company, Silgan Holdings, Darnel Group, Amhil Enterprises, Placon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Hinged Containers Market Evolving Landscape
Material science advances and regulatory sequencing are compressing development cycles for next-generation hinged formats, with sustainability verification and performance convergence commanding parallel R&D investment.
Dual-ovenable PET copolymer formulations are expanding into ghost kitchen and convenience retail channels where single-SKU versatility reduces inventory carrying costs. Operators specify these containers for refrigerated distribution through microwave service without repackaging, collapsing traditional format segmentation. The technology is expanding into premium prepared-meal cases where visual clarity and thermal performance previously required separate packaging investments.
REACH SVHC screening protocols and EU packaging waste directive amendments are tightening additive restrictions for export-bound volumes. Colorant and slip agent suppliers reformulate masterbatch packages to maintain optical properties under reduced substance thresholds. German and French converters face the steepest compliance ramps as national implementation timelines accelerate ahead of minimum harmonization deadlines.
Consolidated procurement through national food service distributors is compressing supplier qualification cycles and unbundling technical service from unit pricing. Regional distributors lose share to broadline operators with dedicated packaging category management and EDI-integrated replenishment systems. The shift is most visible in US quick-service restaurant chains where procurement centralization at headquarters level eliminated regional specification autonomy.
PET Hinged Containers Market Segmentation
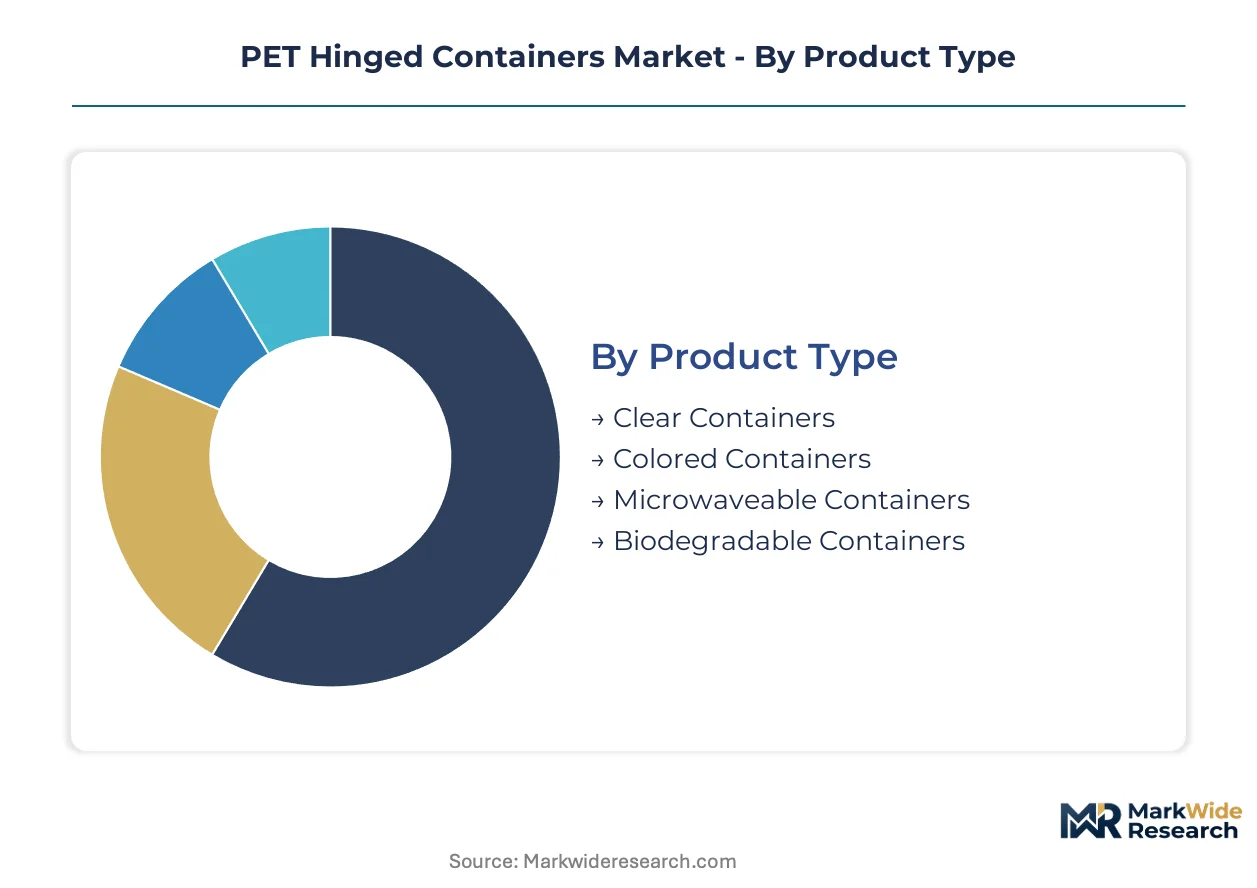
Segmentation in PET hinged containers determines which converters invest in FDA food-contact notification versus pharmaceutical-grade USP Class VI documentation. Certification pathways and end-use specifications fragment supplier strategies across product types and customer categories.
Product Type:
Clear containers require no pigment-related REACH SVHC screening, while colored formats face tighter ECHA additive thresholds. Microwaveable variants demand dual-ovenable copolymer formulations that trigger extended FDA review timelines.
- Clear Containers:Virgin and rPET formulations deliver optical clarity above 85% light transmission for refrigerated deli and bakery display cases. US and German supermarket chains specify these formats for prepared meal merchandising where visual appeal drives purchase conversion, though rPET feedstock volatility pressures margin consistency.
- Microwaveable Containers:Crystallized PET copolymers withstand temperatures to 220°C without warping, enabling direct microwave service from cold storage. Ghost kitchen operators in the United States and convenience retailers in Japan accelerate procurement of these dual-ovenable SKUs to eliminate packaging changeovers.
- Colored Containers:Masterbatch packages must comply with REACH SVHC thresholds for export-bound volumes into EU member states.
- Biodegradable Containers:PLA-PET blends and enzymatically degradable additives face limited thermoforming line compatibility.
Clear containers sit at the top of the volume ranking, with microwaveable containers climbing the fastest.
End User:
Customer concentration shapes contract structures, with national food service distributors consolidating procurement against fragmented retail and pharmaceutical buyers.
- Food Service:Quick-service restaurant chains and centralized protein processors in the United States command multi-site thermoforming contracts with EDI-integrated replenishment. California and Maine extended producer responsibility frameworks mandate post-consumer content minimums that lock converters into long-term reclaimer agreements.
- Pharmaceutical:Child-resistant latch configurations and USP Class VI material documentation open unit-dose packaging demand from compound pharmacies and clinical trial suppliers. FDA notification timelines stretch 12-18 months for recycled PET sources, freezing inventory positions during regulatory review.
- Retail:Private label specifications at convenience chains demand extended shelf-life barrier properties.
- Consumer Goods:Lower volume requirements favor regional distributors over national broadline operators.
Food service dominates absolute volume, while pharmaceutical applications are gaining share fastest.
Size:
Dimensional standardization varies by end-use, with food service favoring nested stacking efficiency and pharmaceutical requiring precise unit-dose dimensions.
- Medium:16-24 ounce capacities balance portion control with nested density for deli and prepared meal distribution. US protein processors and German supermarket chains standardize on these dimensions for refrigerated case resets, driving thermoformer die investment concentration.
- Large:32-48 ounce formats serve family-size prepared meals and bulk protein portions. Ghost kitchen operators in the United States specify these for multi-portion delivery orders, though shipping cube efficiency pressures gauge optimization.
- Small:Single-serve condiment and sampler formats face substitution pressure from portion cups.
- Extra Large:Catering and institutional trays require specialized thermoforming equipment with limited converter availability.
Medium sizes anchor production volume, with large formats expanding most quickly.
Distribution Channel:
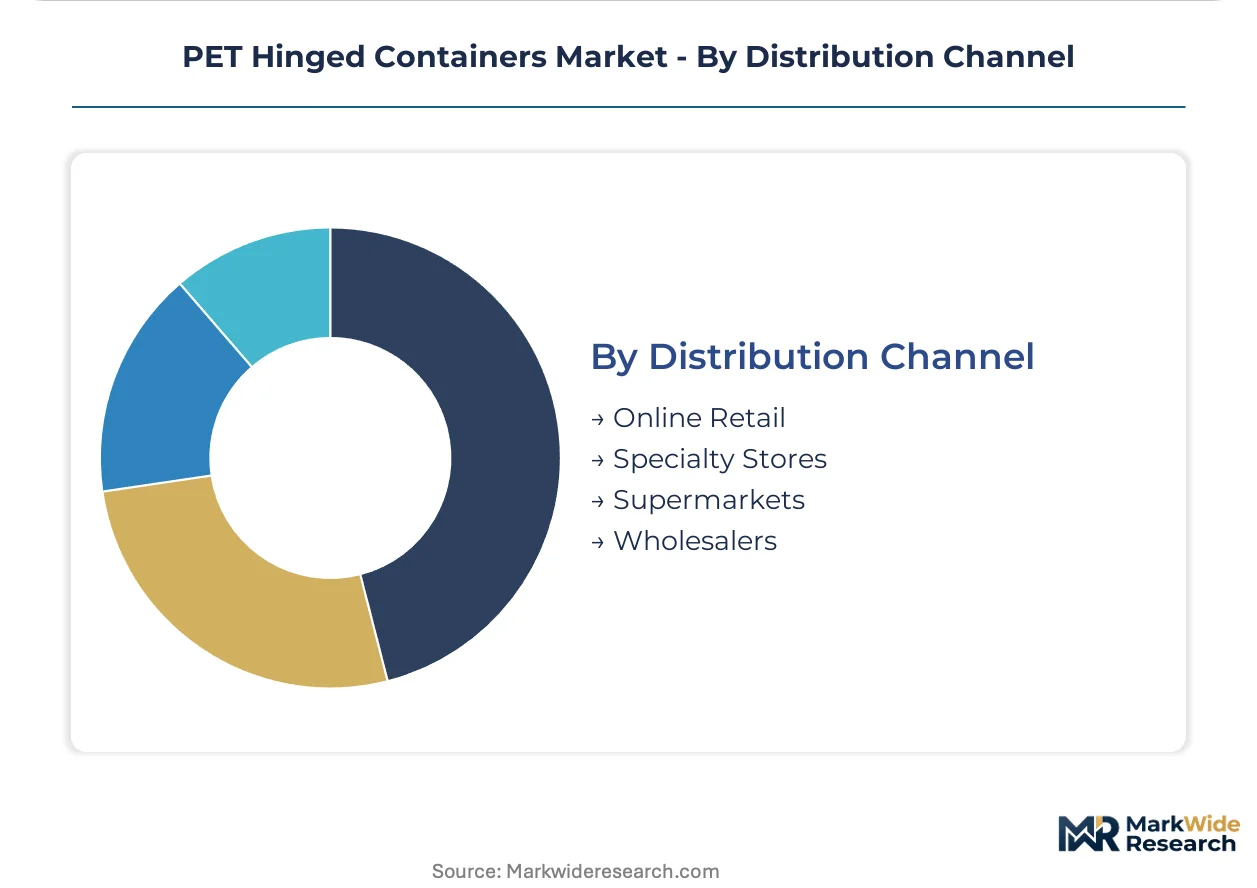
Channel selection determines technical service bundling, with broadline distributors unbundling support from unit pricing versus specialty stores demanding specification collaboration.
- Wholesalers:National food service distributors consolidate procurement for quick-service restaurant chains and protein processors across the United States. EDI-integrated replenishment systems compress supplier qualification cycles and eliminate regional specification autonomy.
- Supermarkets:Direct contracts with thermoformers for private label clear hinged formats support prepared meal case resets. 7-Eleven and Lawson Japan create white-space demand for extended shelf-life barrier properties.
- Online Retail:Smaller minimum order quantities serve regional food service distributors and independent operators.
- Specialty Stores:Restaurant supply dealers retain share through rapid-turn customization and seasonal SKU proliferation.
Wholesalers command the largest volume share, with supermarkets showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions with mature extended producer responsibility frameworks and those without compliance infrastructure is redirecting thermoforming investment toward states and countries where rPET feedstock security can be locked in through long-term reclaimer contracts.
United States
Quick-service restaurant chains and centralized protein processors command multi-site thermoforming contracts with EDI-integrated replenishment systems. California and Maine extended producer responsibility programs impose post-consumer content minimums that pull converters toward rPET investments. Chicago and Dallas-Fort Worth industrial corridors host the largest concentrations of thin-gauge thermoforming capacity serving national food service distributors.
Germany
Supermarket chains and deli operators standardize on medium-format clear hinged containers for prepared meal case resets. EU packaging waste directive amendments and REACH SVHC thresholds tighten additive restrictions for colorants and slip agents. The Rhine-Ruhr and Stuttgart manufacturing belts concentrate thermoforming operations serving export-bound volumes into neighboring member states.
China
Domestic quick-service restaurant expansion and centralized food processing drive volume demand for nested stacking formats. SAMR food-contact material regulations and provincial-level plastic restriction pilots redirect converter investment toward recyclable formulations. Yangtze River Delta industrial clusters around Shanghai and Suzhou host the largest thermoforming capacity serving both domestic and export markets.
Japan
Convenience retailers including Lawson and 7-Eleven create white-space demand for clear hinged formats with extended shelf-life barrier properties. METI circular economy guidelines and plastic resource recycling legislation shape resin sourcing decisions for domestic molders. The Kanto region around Tokyo anchors thermoforming production serving prepared meal distribution networks.
India
Quick-service restaurant chains and organized retail expansion drive procurement of microwaveable hinged formats for delivery-native food preparation. FSSAI food-contact regulations and state-level plastic waste management rules influence converter formulation strategies. Maharashtra and Gujarat industrial corridors concentrate thermoforming capacity serving western and southern regional markets.
PET Hinged Containers Market Competitive Landscape
United States producers anchor one tier through multi-site thermoforming scale and backward integration into resin compounding; European specialists hold positioning around REACH-compliant additive packages and CE-marked export volumes. The vendor base organizes around three strategic archetypes: national-scale thermoformers with captive rPET supply, regional customizers serving rapid-turn seasonal SKU proliferation, and pharmaceutical-grade specialists holding USP Class VI documentation. Dominant competitive moves include capacity conversion to post-consumer recycled PET lines and strategic partnerships with reclaimers to secure feedstock consistency.
Among United States-based fabricators, Dart Container exemplifies the backward-integrated archetype through in-house resin compounding capabilities, while Berry Global occupies a position representing multi-site thermoforming scale that sustains national distribution contracts. Pactiv sits within the rapid-turn customization tier, serving regional food service distributors navigating shorter run lengths. These three anchors illustrate how competitive positioning fragments across integration depth, geographic footprint, and service model specialization.
| Leading Market Players |
|---|
| Dart Container |
| Pactiv |
| Berry Global |
| Amcor |
| Sonoco Products Company |
| Silgan Holdings |
| Darnel Group |
| Amhil Enterprises |
| Placon Corporation |
| Others |
Value Network & Pricing Analysis
Backward integration into resin compounding anchors both supply security and pricing power for converters serving national food service distributors, locking in feedstock consistency against virgin PET volatility while compressing toll-compounding margins for non-integrated competitors.
Pricing Analysis
Distributor margin layers dominate downstream pricing, with national broadline operators extracting 15-25 point markups over converter gate prices while specialty dealers command premiums for rapid-turn customization. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade USP Class VI documentation from food-contact notification tiers and generic deli formats. Price differentiation hinges on certification burden and volume scale, with rPET content premiums eroding as California and Maine mandates normalize post-consumer minimums. Quick-service restaurant chains exhibit highest price sensitivity through consolidated procurement, while pharmaceutical buyers absorb certification-driven premiums.
Supply Chain Analysis
Dual-sourcing requirements from national food service distributors mandate multi-supplier qualification across at least two thermoforming footprints, preventing single-site dependency. Supply concentrates in the United States, China, and Germany, with bottle bale reclaiming capacity tethered to municipal collection infrastructure. Raw material flows draw from post-consumer PET bottle streams, virgin resin production, and imported rPET flake. Tariff exposure on Asian rPET imports creates input cost instability. Distribution runs through broadline food service distributors with EDI-integrated replenishment, compressing regional dealer share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PET hinged containers function as a stable compounder anchored by structural off-premise dining growth, with regulatory tailwinds on recyclability reinforcing multi-year procurement visibility for integrated converters.
For Market Incumbents: Acquire reclaimer capacity or long-term bale offtake agreements to secure rPET feedstock consistency as California and Maine extended producer responsibility frameworks tighten post-consumer content minimums. Expand thermoforming capacity in Chicago and Dallas-Fort Worth industrial corridors to defend national distribution contracts against regional customizers. FDA food-contact notification timelines for recycled PET sources represent a regulatory moat—deepen technical service bundling to lock in pharmaceutical-grade conversions. For New Entrants and Emerging Players: Launch via online retail channels serving independent ghost kitchen operators and regional food service distributors with smaller minimum order quantities and rapid-turn seasonal SKU proliferation. Target pharmaceutical compliance-grade demand where USP Class VI documentation and child-resistant latch configurations create white-space against commoditized food service supply. Penetrate convenience retailer private label specifications at chains like 7-Eleven and Lawson Japan through extended shelf-life barrier properties. For Investors and Strategic Acquirers: Consolidation pressure builds where rPET feedstock volatility compresses margins for non-integrated mid-cap converters, creating acquisition opportunities for backward-integrated platforms. Long-term viability centers on captive recycling economics versus toll-compounding alternatives across the analysis window. Signal to monitor: FDA notification timeline compression for recycled PET sources, which would accelerate inventory velocity for early movers.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Line Conversion | California EPR mandates pull capital toward post-consumer recycled capacity ahead of compliance deadlines. |
| Reclaimer Partnership | Long-term bale offtake agreements lock in feedstock consistency against bottle supply fluctuations. |
| Pharmaceutical Certification | USP Class VI documentation opens unit-dose packaging demand from compound pharmacies. |
| Dual-Ovenable Formulation | Crystallized PET copolymers capture ghost kitchen procurement eliminating packaging changeovers. |
| ERP Middleware Investment | Batch traceability systems satisfy pharmaceutical-grade production requirements straining IT budgets. |
Research Methodology
Multiple input streams — executive interviews with thermoforming plant managers, procurement leads at protein processors, distribution channel partners, and regulatory affairs directors, alongside secondary validation through FDA food-contact notifications, EPA state-delegated program filings, and SEC 10-K disclosures from packaging converters — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, end-user category, size format, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions, with rPET feedstock cost curves and regulatory implementation timelines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated state-level single-use plastic bans or prolonged FDA recycled PET source approval timelines. Deviation in bottle bale supply availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
ISO Container Market
Containers
Gable Top Container Market
Containers
LDPE Containers Market
Containers
Foldable Steel Containers Market
Containers
Light Resistant Containers Market
Containers
Collapsible Food Packaging Containers Market
Containers
Jerry Cans Market
Containers
Spout Containers Market
Containers
Tottle Containers Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Trigger Sprayer Market
Containers
Metal IBC Market
Containers
Reconditioned IBC Market
Containers
Pinch Grip Jars Market
Containers
Composite Ibcs System Market
Containers
Slip Lid Can Market