
 Snap Secure Containers Market | 2026-2036
Snap Secure Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Snap Secure Containers Market Analytics
Aftermarket service revenue for container fleet management and refurbishment programs is reshaping margin distribution across the value chain. Berry Global Inc. leverages captive resin compounding and thermoforming scale to control input costs across North American foodservice accounts. Tupperware Brands Corporation anchors its position through direct-to-consumer channel infrastructure and lifetime warranty programs that sustain replacement demand. Sabert Corporation competes in the premium disposable segment with specialized tamper-evident designs for healthcare catering and institutional food distribution.
Snap secure containers are rigid or semi-rigid receptacles incorporating mechanical snap-lock or hinge-seal closures designed to create repeatable airtight or liquid-tight seals without auxiliary fasteners, typically manufactured through injection molding or thermoforming of polypropylene or polyethylene resins for product protection, inventory containment, and transport security. Stackable containers lead the product type category due to palletization efficiency in warehouse automation systems and compatibility with ISO modular footprint standards. Plastic dominates the material segment because of its weight advantage in logistics cost calculations, though composite formulations are gaining specification in pharmaceutical cold-chain applications where thermal insulation and impact resistance converge. Retail storage applications generate the largest volume demand, while industrial use commands premium pricing through custom color-coding, RFID integration, and chemical resistance certifications.
The US FDA enforces seal-integrity standards under the Food Safety Modernization Act for food-contact snap containers, while the EU REACH regulation and evolving Packaging and Packaging Waste Directive constrain additive chemistries and mandate recyclability thresholds for plastic locking systems entering European distribution. Germany's national packaging ordinance implements extended producer responsibility fees that incentivize durable, multi-trip container designs over single-use alternatives. Stakeholders must monitor regulatory divergence between FDA migration limits and EU ECHA substance restrictions when designing unified product platforms for transatlantic supply chains.
Market Dynamics
The FDA Food Safety Modernization Act and EU Packaging and Packaging Waste Directive are compressing seal-integrity timelines and recyclability thresholds, forcing manufacturers to redesign closure geometries and resin formulations simultaneously.
Growth Catalysts
- Meal-kit cold-chain expansion:Temperature-controlled logistics operators are specifying tamper-evident snap containers with integrated gel-pack channels for last-mile pharmaceutical and fresh-food delivery.
- REACH additive restrictions:ECHA substance evaluations are phasing out legacy plasticizers, creating specification windows for compliant polypropylene grades in EU food-contact applications.
- German extended producer responsibility:The national packaging ordinance penalizes single-use formats, accelerating fleet conversions to reusable locking container systems in industrial logistics.
Market Restraints
- Propylene feedstock volatility:North American resin supply concentrates around Gulf Coast petrochemical complexes, exposing molders to hurricane-related production interruptions and price spikes.
- Multi-material recycling incompatibility:Hinge-seal containers combining polypropylene bases with thermoplastic elastomer gaskets face sorting-line rejection at European mechanical recycling facilities.
- Silicone gasket substitution:Premium cold-chain applications are migrating to silicone-overmolded closures with superior thermal cycling durability, compressing polypropylene seal margins.
Strategic Opportunities
- RFID-integrated fleet tracking:Industrial laundries and pool operators in France and the Netherlands are piloting NFC-enabled snap containers for automated inventory reconciliation and loss prevention.
- Healthcare catering specification:Hospital foodservice contractors in Switzerland and Austria are adopting color-coded, tamper-evident designs to satisfy HACCP audit protocols and reduce contamination incidents.
- ISO 18606 compliance acceleration:The packaging recoverability standard is creating certification premiums for containers designed with mono-material construction and tool-less disassembly features.
Industry Challenges
- Multi-cavity mold qualification timelines:FDA food-contact validation protocols extend new product introduction cycles by 8-14 months, constraining responsiveness to rapid-format foodservice trends.
- Automation integration complexity:Warehouse robotics deployments require dimensional tolerances tighter than legacy snap-container specifications, forcing mold retrofit investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snap Secure Containers Market |
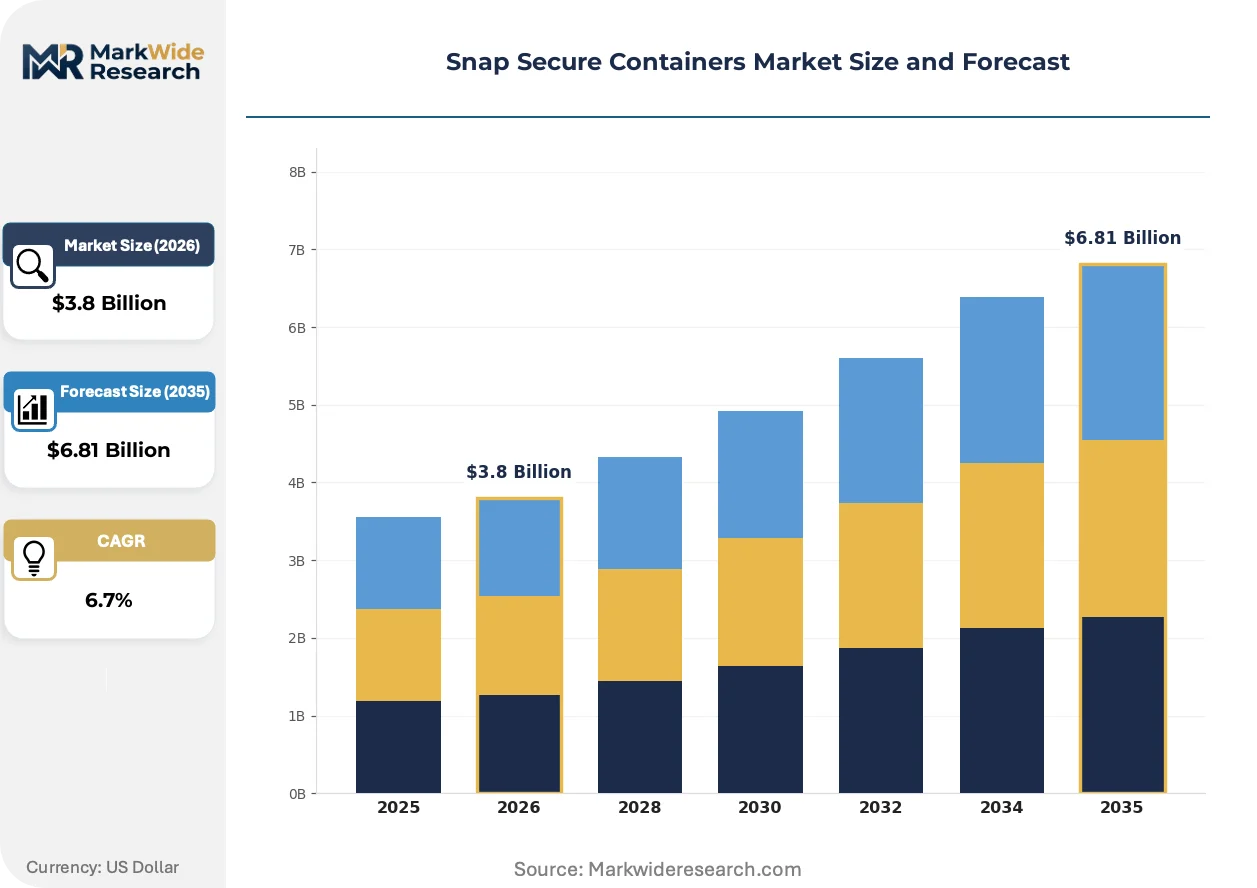
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable Containers, Foldable Bins, Locking Boxes, Recycling Bins Material: Plastic, Metal, Wood, Composite Application: Retail Storage, Industrial Use, Household Use, Transportation End User: Logistics Companies, Retailers, Manufacturers, Homeowners |
| Companies Covered | LocknLock Co. Ltd., Sistema Plastics, Snapware Corporation, Tupperware Brands Corporation, Newell Brands Inc., Berry Global Inc., Sabert Corporation, Berlin Packaging, H&K Muller GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snap Secure Containers Market Evolving Landscape
Active and intelligent packaging integration is converging with mechanical closure engineering, creating hybrid formats that communicate seal integrity without auxiliary electronics. Material science advances are dissolving the trade-off between recyclability and performance.
Barrier-coated polypropylene is hybridizing oxygen and moisture protection into thin-wall snap containers previously limited to unprotected commodity grades. Pharmaceutical distributors in Germany and the Netherlands are specifying these formats for temperature-sensitive biologics requiring 24-month stability. The technology is compressing demand for thicker-walled, multi-layer alternatives that complicate mechanical recycling streams.
EU REACH substance restrictions are accelerating migration from phthalate-based additives to bio-based plasticizers in food-contact snap seals. Compounders serving French and Italian molders are reformulating masterbatch portfolios to preempt SVHC listing impacts. The regulatory pressure is concentrating specification authority with resin suppliers capable of documenting full supply chain substance inventories.
Direct-to-institutional procurement models are displacing traditional distribution intermediaries in North American foodservice. Hospital systems and correctional facilities are consolidating container purchasing through group purchasing organizations, compressing supplier margins while demanding custom color-coding and RFID serialization. The channel consolidation is most advanced in the US Northeast and Upper Midwest, where integrated delivery networks dominate institutional food supply.
Snap Secure Containers Market Segmentation
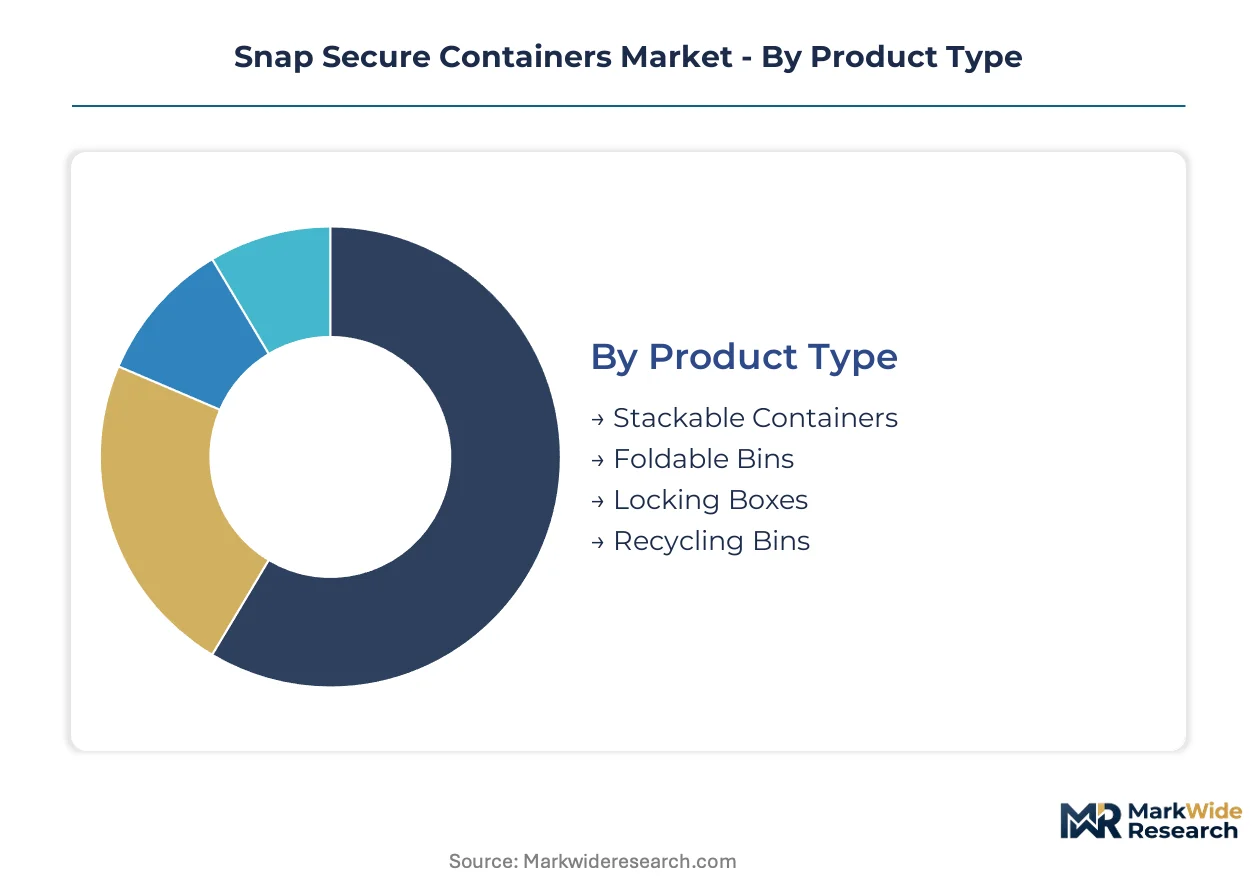
Segmentation in snap secure containers reveals divergent service intensity and margin profiles across product architectures. Aftermarket fleet management, refurbishment programs, and lifetime warranty obligations vary sharply by closure mechanism durability and material fatigue characteristics.
Product Type:
After-sales service intensity concentrates in formats subject to repetitive mechanical stress and industrial pool rotation cycles.
- Stackable Containers:Injection-molded polypropylene shells with reinforced corner posts and interlocking base rims. Warehouse automation in Germany and the Netherlands drives specification for ISO-modular footprints compatible with robotic palletizing systems.
- Locking Boxes:Hinge-seal designs with tamper-evident closures for pharmaceutical and meal-kit cold-chain applications. Swiss hospital foodservice contractors specify color-coded variants to satisfy HACCP audit protocols.
- Foldable Bins:Collapsible designs for return-trip logistics optimization.
- Recycling Bins:Municipal and institutional collection formats with standardized lid interfaces.
Stackable containers hold the largest share; momentum sits with locking boxes.
Material:
Cost tier stratification separates commodity resins from performance-engineered compounds in cold-chain and chemical-resistant specifications.
- Plastic:Polypropylene and polyethylene grades dominate through weight advantages in logistics cost calculations. EU REACH additive restrictions are forcing compounders to reformulate masterbatch portfolios away from legacy plasticizers.
- Composite:Hybrid formulations combining thermal insulation and impact resistance for pharmaceutical distribution. German cold-chain operators specify these for biologics requiring extended temperature stability.
- Metal:Steel and aluminum variants for heavy-duty industrial containment.
- Wood:Pallet-based and crate formats for specialty agricultural and artisanal product transport.
Plastic commands volume leadership; composites are climbing the fastest on regulatory and performance convergence.
Application:
Customer type and procurement scale determine whether specifications prioritize unit economics or compliance certification premiums.
- Industrial Use:Custom color-coding, RFID integration, and chemical resistance certifications command premium pricing. French and Dutch industrial laundries pilot NFC-enabled containers for automated inventory reconciliation.
- Retail Storage:High-volume demand from foodservice operators and institutional buyers through group purchasing organizations.
- Transportation:Intermodal and last-mile logistics formats with gel-pack channel integration.
- Household Use:Direct-to-consumer channels with lifetime warranty programs sustaining replacement demand.
Retail storage generates the highest volume; industrial use captures the steepest margin expansion.
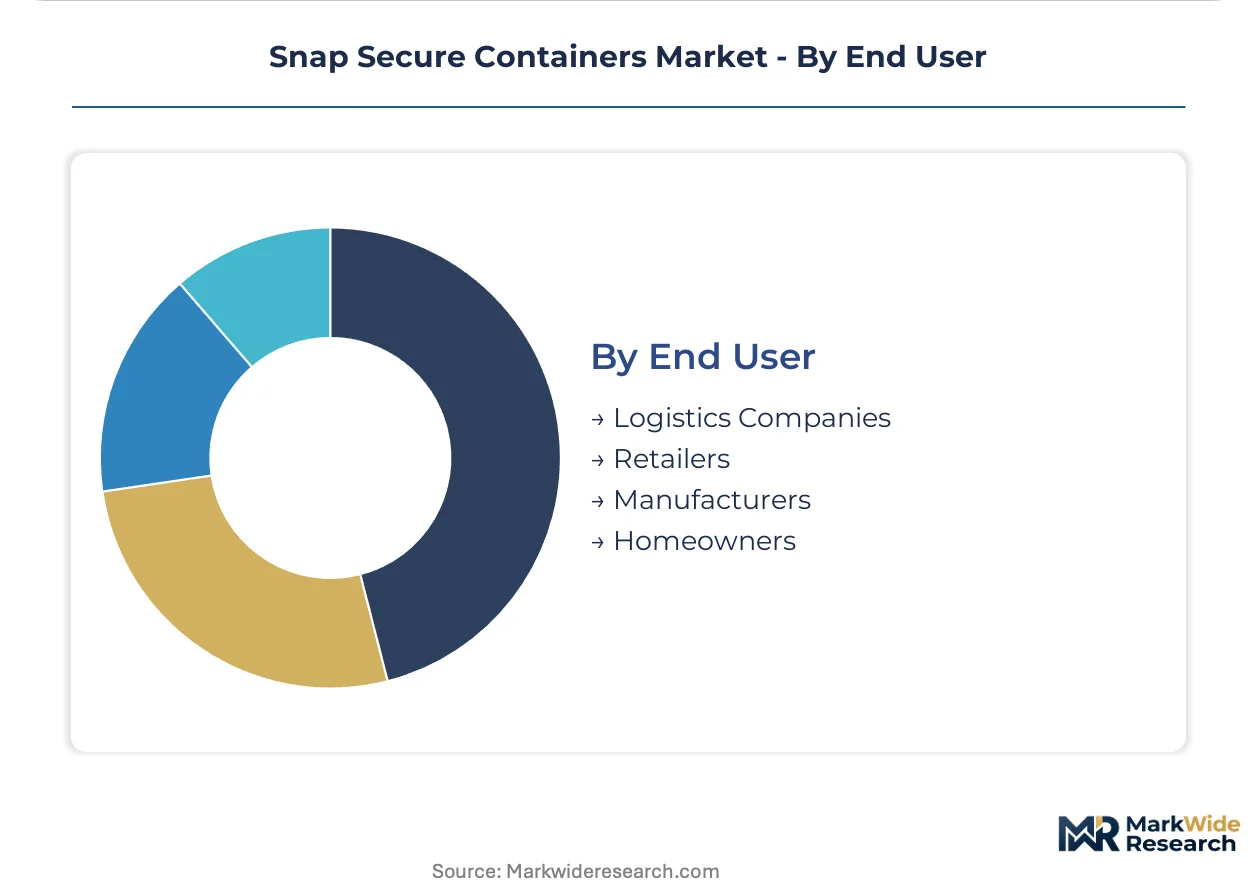
End User:
Supply concentration among logistics operators and integrated delivery networks shapes procurement standardization and custom specification authority.
- Logistics Companies:Fleet-scale operators in Germany and the US Northeast specify reusable locking systems with extended producer responsibility compliance. Pool management and refurbishment programs generate recurring service revenue.
- Retailers:Consolidated purchasing through group purchasing organizations demands custom color-coding and serialization.
- Manufacturers:Inbound parts containment and work-in-process inventory systems.
- Homeowners:Direct-to-consumer and retail channel acquisition for domestic organization.
Logistics companies anchor demand concentration; retailers are gaining procurement leverage fastest through channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German industrial buyers absorb premium specifications for reusable fleet systems, while US foodservice operators prioritize unit economics in high-volume procurement.
United States
FDA Food Safety Modernization Act compliance drives specification upgrades for tamper-evident closures in meal-kit and healthcare catering channels. Group purchasing organizations consolidate procurement for hospital systems in the Northeast and Upper Midwest. Berry Global anchors North American supply through captive resin compounding and thermoforming scale.
Germany
Extended producer responsibility fees under the national packaging ordinance accelerate conversion from single-use to reusable locking container systems. ECHA REACH substance restrictions force masterbatch reformulation away from legacy plasticizers. Industrial logistics clusters in North Rhine-Westphalia and Bavaria specify ISO-modular stackable formats for warehouse automation compatibility.
France
Industrial laundries and pool operators pilot NFC-enabled snap containers for automated inventory reconciliation. EU Packaging and Packaging Waste Directive recyclability thresholds constrain multi-material hinge-seal designs. Compounders serving molders in the Auvergne-Rhône-Alpes region reformulate portfolios to preempt SVHC listing impacts.
Switzerland
Hospital foodservice contractors adopt color-coded, tamper-evident designs to satisfy HACCP audit protocols. Swissmedic-aligned pharmaceutical distributors specify barrier-coated formats for biologics stability. The Basel and Zurich industrial corridors concentrate cold-chain specification authority for temperature-sensitive distribution.
Netherlands
Temperature-controlled logistics operators specify containers with integrated gel-pack channels for last-mile pharmaceutical delivery. ISO 18606 packaging recoverability standards create certification premiums for mono-material construction. Rotterdam-area distribution hubs drive demand for RFID-integrated fleet tracking systems.
Snap Secure Containers Market Competitive Landscape
Capability concentration sits with resin compounders and precision molders; scale advantage sits with integrated packaging conglomerates. The market structures around three tiers: captive resin producers with thermoforming scale, direct-to-consumer channel specialists, and premium disposable fabricators. Consolidation pressure runs through group purchasing organization leverage and automation-driven specification tightening. Strategic moves center on backward integration into resin compounding and RFID serialization partnerships.
Among North American packaging conglomerates, Berry Global Inc. and Newell Brands Inc. exemplify scale-driven archetypes with captive supply chain control. Tupperware Brands Corporation anchors the direct-to-consumer tier through warranty-backed replacement demand. Sabert Corporation occupies a position within the premium disposable segment serving healthcare and institutional channels.
| Leading Market Players |
|---|
| LocknLock Co. Ltd. |
| Sistema Plastics |
| Snapware Corporation |
| Tupperware Brands Corporation |
| Newell Brands Inc. |
| Berry Global Inc. |
| Sabert Corporation |
| Berlin Packaging |
| H&K Muller GmbH |
| Others |
Value Network & Pricing Analysis
Gulf Coast petrochemical concentration around propylene feedstock production anchors margin distribution downstream, with captive resin compounding operations capturing value that contract molders forfeit during feedstock price spikes. Aftermarket fleet management revenue pools sit with operators who control refurbishment cycles and extended warranty obligations across reusable container lifespans.
Pricing Analysis
After-sales service contracts and refurbishment program revenue drive lifetime value capture across industrial container fleets. Three-tier pricing structure across premium, standard, and economy levels separates RFID-integrated pharmaceutical specifications from commodity foodservice disposables. Cost compression in the standard tier is intensifying because group purchasing organizations consolidate hospital and institutional procurement volumes. Logistics operators demonstrate the least price sensitivity due to total-cost-of-ownership calculations that weight durability and fleet tracking capabilities above unit acquisition cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Berry Global's captive thermoforming operations and Sabert Corporation's specialized healthcare fabrication lines. Resin supply draws from US Gulf Coast petrochemical complexes, German compounders serving EU REACH-compliant masterbatch formulations, and Chinese polypropylene producers. Single-source vulnerability runs through hurricane-exposed Gulf Coast propylene production that interrupts North American molding operations. Distribution runs through group purchasing organizations for institutional buyers and direct fleet management contracts for logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment. FDA food-contact validation protocols and EU REACH substance documentation create switching costs that lock in specification authority for established compounders and molders.
For Market Incumbents: Insulate specification authority by deepening backward integration into REACH-compliant resin compounding and accelerating RFID serialization partnerships with Dutch and French industrial laundries. Silicone gasket substitution in premium cold-chain applications threatens polypropylene seal margins; defend by piloting barrier-coated hybrid formats with equivalent thermal cycling performance. For New Entrants and Emerging Players: Mid-tier healthcare catering contractors in Switzerland and Austria represent the most penetrable entry point, as these operators seek color-coded tamper-evident alternatives to satisfy HACCP audit protocols without incumbent volume commitments. Direct-to-institutional procurement models bypass traditional distribution intermediaries and enable specification authority capture before group purchasing organization consolidation advances. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across RFID-integrated fleet management systems as NFC-enabled container deployments require serialization infrastructure and software platform investments. Target molders with documented EU substance inventories and established refurbishment program revenue streams. Monitor German extended producer responsibility fee adjustments as the signal for reusable format conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global's captive supply control insulates margin from Gulf Coast feedstock volatility. |
| RFID Serialization Partnership | Dutch industrial laundries pilot NFC-enabled containers for automated inventory reconciliation. |
| REACH-Compliant Masterbatch Reformulation | French compounders preempt SVHC listing impacts to secure EU food-contact specification authority. |
| Direct-to-Institutional Channel Development | US hospital systems consolidate procurement through group purchasing organizations demanding custom color-coding. |
| Barrier-Coated Format Introduction | German pharmaceutical distributors specify oxygen-protected thin-wall alternatives to multi-layer containers. |
Research Methodology
The analysis maps product type architectures, material grade specifications, and end-use procurement patterns, each validated through procurement managers at logistics operators, compounder technical directors, and foodservice distribution executives. Primary fieldwork combined structured interviews with secondary validation against FDA food-contact submission databases, EU ECHA substance inventory filings, and customs trade records for polypropylene resin flows. Bottom-up segment sizing and top-down macro anchoring triangulate volume and value estimates.
Assumptions held fixed include regulatory enforcement intensity of FDA seal-integrity standards and EU packaging waste directive recyclability thresholds, while propylene feedstock pricing and automation adoption rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass closure mechanism durability, resin formulation compliance tier, and channel procurement concentration. CAGRs derive from fitted growth curves against historical adoption patterns in meal-kit logistics and pharmaceutical cold-chain expansion.
Macroeconomic conditions sit as an overlay; deviation in resin commodity pricing, logistics automation capex cycles, or transatlantic regulatory harmonization would shift the trajectory. Quarterly review of German packaging ordinance fee adjustments, ECHA SVHC candidate list updates, and Gulf Coast petrochemical operating rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Snap-Lock Container Market
Containers
Slip Lid Can Market
Containers
Containerboard Market
Containers
Half Height Containers Market
Containers
Popcorn Containers Market
Containers
Pails Market
Containers
2 Piece Cans Market
Containers
Cups and Lids Market
Containers
Lever Lid Cans Market
Containers
Container Fixed Fittings Market
Containers
Stainless Steel Cask Market
Containers
Square Pails Market
Containers
Global Food Containers Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
Collapsible Crate Market
Containers
Wide Mouth Jars Market