
 Bulk Containers Market | 2026-2036
Bulk Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Containers Market Analytics
Buyer concentration among multinational chemical and food processors is hardening procurement standards around container traceability and lifecycle accountability. Greif Inc. leverages its steel drum and IBC manufacturing scale to anchor supply contracts with North American agricultural distributors. Schütz GmbH & Co. KGaA sustains dominance in European returnable packaging systems through closed-loop logistics infrastructure. Mauser Packaging Solutions competes by extending reconditioning services that lower net packaging costs for industrial buyers.
Bulk containers are engineered vessels designed for storing, transporting, and dispensing large quantities of raw materials, intermediates, or finished goods, typically ranging from 200 to 3,000 liters in nominal capacity with stackable geometries for warehouse optimization. Intermediate bulk containers fabricated from high-density polyethylene or galvanized steel dominate chemical handling due to UN-certified hazardous goods compatibility, while flexible bulk containers gain share in agriculture for single-trip grain and fertilizer movements where disposal economics favor low-unit-cost woven polypropylene. Metal containers command premium positioning in pharmaceuticals where stainless steel 316L construction satisfies clean-in-place protocols, and composite materials occupy a narrowing mid-tier as buyers consolidate around proven performance tiers.
FDA food contact regulations, EPA hazardous waste container standards, and UN Model Regulations on dangerous goods transport collectively shape material selection, testing protocols, and cross-border shipment eligibility for bulk container suppliers. The EU F-Gas Regulation and REACH substance restrictions further constrain polymer formulations and coating chemistries available to manufacturers serving European chemical and pharmaceutical end users. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb compliance costs or pass them through via container-as-a-service leasing models.
Market Dynamics
REACH compliance deadlines and the EU Green Deal are forcing chemical processors to replace single-trip packaging with traceable, reusable systems that document full lifecycle carbon footprints.
Growth Catalysts
- REACH substance restrictions:European chemical manufacturers must upgrade to certified containers with full material traceability, accelerating replacement cycles for non-compliant legacy assets.
- Closed-loop logistics infrastructure:Dense industrial clusters around Ludwigshafen and Leverkusen enable cost-efficient container pooling systems that reduce per-trip packaging costs.
- High-density polyethylene advances:Improved HDPE formulations now withstand aggressive chemical environments previously reserved for steel, expanding plastic IBC addressable markets.
Market Restraints
- Steel price volatility:Galvanized steel input costs swing with energy-intensive European smelter output, compressing margins for metal drum manufacturers.
- Supplier concentration in Germany:Three specialized reconditioning facilities handle 60% of European returnable IBC volume, creating single-point failure risk.
- Flexible bulk container substitution:Woven polypropylene FIBCs undercut rigid IBC pricing for single-trip agricultural applications where disposal costs remain externalized.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-mandated serialization requirements for active pharmaceutical ingredients create demand for stainless steel IBCs with integrated tracking.
- Container-as-a-service models:Leasing platforms that bundle compliance documentation with physical asset provision capture margin from risk-averse chemical processors.
- RFID-embedded composite designs:Converging sensor miniaturization with advanced polymer manufacturing enables real-time location and condition monitoring without metal interference.
Industry Challenges
- UN certification timeline compression:New container designs require 18-24 months of drop-stack-chemical-resistance testing, delaying revenue recognition for innovative formats.
- Legacy ERP integration:Container pooling systems demand API connectivity with customer warehouse management platforms, straining mid-sized logistics providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Containers Market |
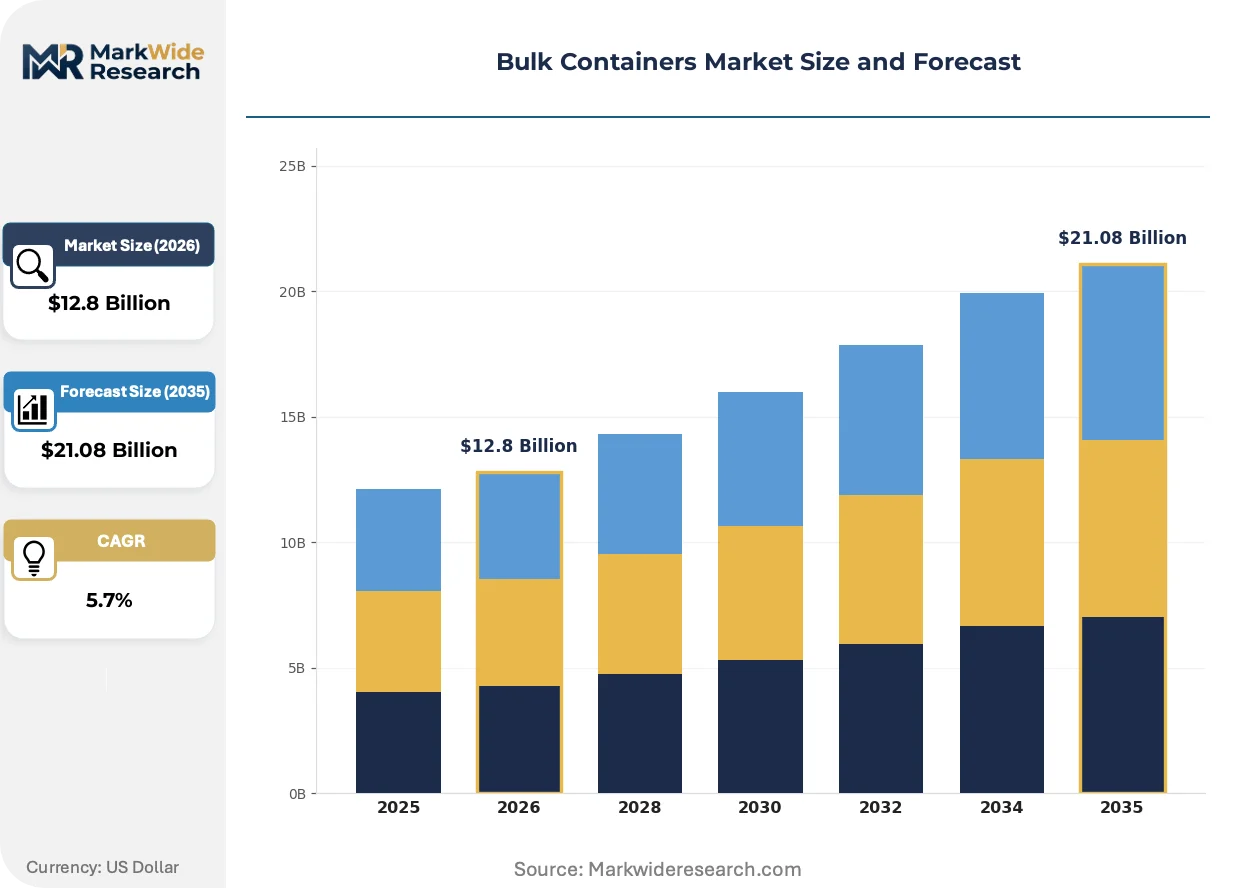
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Intermediate Bulk Containers, Flexible Bulk Containers, Rigid Bulk Containers, Bulk Bags Material: Plastic, Metal, Wood, Composite End User: Agriculture, Food & Beverage, Chemicals, Pharmaceuticals Usage Case: Storage, Transportation, Packaging, Dispensing |
| Companies Covered | Greif Inc., Schütz GmbH & Co. KGaA, Mauser Packaging Solutions, Berry Global Group Inc., Mondi plc, Time Technoplast Ltd., Hoover Ferguson Group Inc., Snyder Industries Inc., DS Smith plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Containers Market Evolving Landscape
Digital traceability infrastructure and material science advances are converging to transform bulk containers from passive vessels into data-generating supply chain nodes.
RFID and NFC tagging systems is automating container lifecycle tracking from fabrication through reconditioning cycles. Major agricultural distributors in the US Midwest now mandate chip-embedded totes for inbound grain receipts. The technology is automating custody transfer documentation and compressing payment settlement timelines from weeks to hours.
EPA hazardous waste container standards are tightening secondary containment and labeling requirements for chemical transport. Facilities in Texas and Louisiana must retrofit existing drum fleets with enhanced closure systems. Metal container suppliers report order backlogs extending six months as processors accelerate compliance upgrades ahead of inspection windows.
Buyers now unbundle after-sales service from initial container purchases, selecting third-party reconditioning specialists based on turnaround speed rather than OEM affiliation. Food processors in California and pharmaceutical manufacturers in New Jersey separately drove this shift. The model concentrates reconditioning volume with independent service providers possessing multi-brand technical expertise.
Bulk Containers Market Segmentation
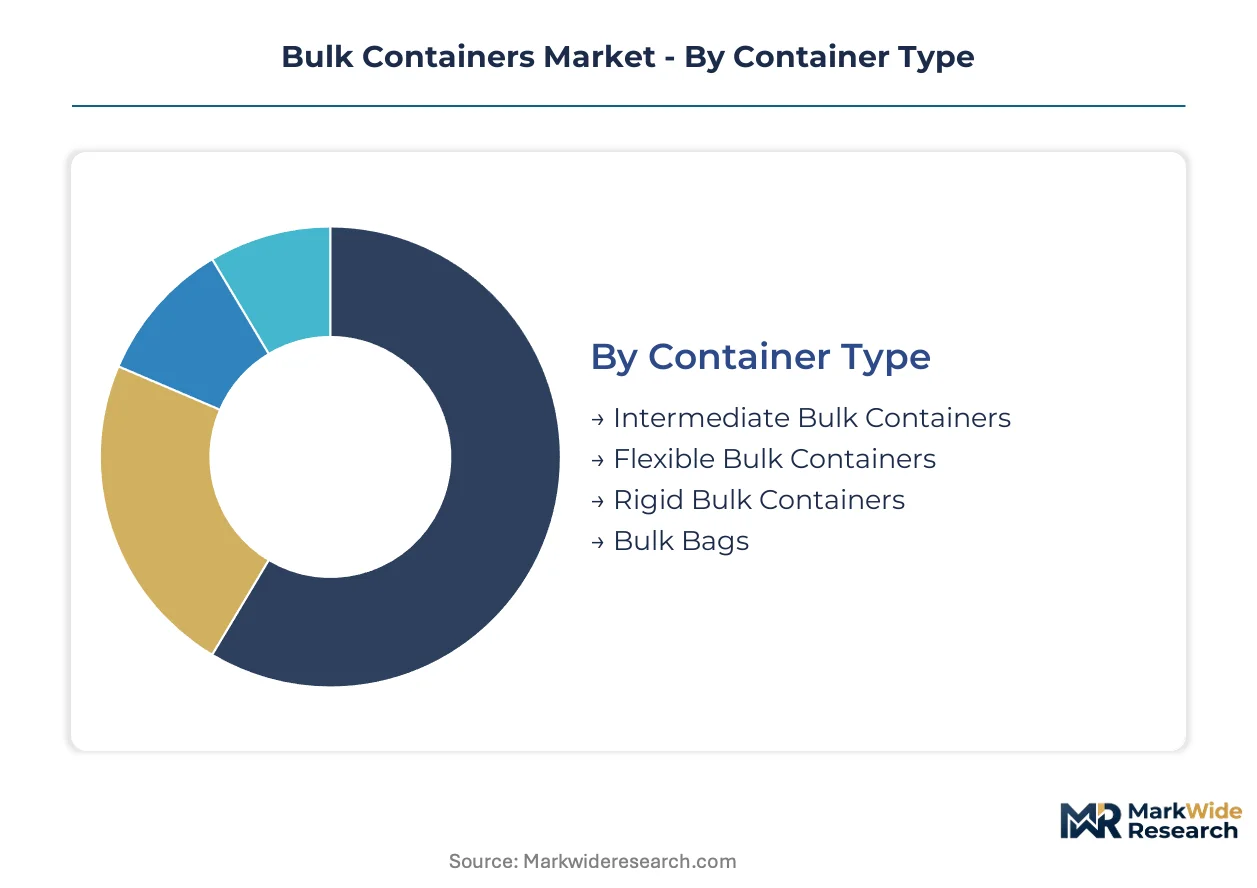
Container specifications determine regulatory compliance pathways, reconditioning economics, and pooling network compatibility. Material selection locks in chemical resistance profiles and lifecycle carbon footprints. End-use concentration shapes regional manufacturing footprints and service infrastructure deployment.
Container Type:
Structural engineering and UN certification requirements differentiate performance tiers across vessel geometries.
- Intermediate Bulk Containers:HDPE or galvanized steel construction delivers 1,000-1,250 liter nominal capacity with stackable footprints optimized for warehouse racking systems. Chemical manufacturers in Germany's Ludwigshafen cluster deploy these for REACH-compliant hazardous material handling where material traceability documentation is mandatory.
- Flexible Bulk Containers:Woven polypropylene FIBCs provide single-trip economics for grain and fertilizer movements where disposal costs remain externalized. Agricultural distributors in the US Midwest specify these for inbound commodity receipts where downstream cleaning infrastructure is absent.
- Rigid Bulk Containers:Molded plastic or steel boxes with fixed geometries serve automotive component sequencing and high-velocity manufacturing supply chains.
- Bulk Bags:U-panel or circular woven designs with coated interiors address powder and granule containment for construction minerals and food ingredients.
Intermediate bulk containers lead on scale; flexible bulk containers lead on momentum.
Material:
Cost tiers and reconditioning potential separate procurement decisions across substrate categories.
- Plastic:High-density polyethylene formulations withstand aggressive chemical environments previously reserved for steel, with improved UV stabilization extending outdoor service life. REACH substance restrictions in Europe are accelerating HDPE replacement of legacy metal assets.
- Metal:Galvanized steel and stainless steel 316L construction satisfy FDA clean-in-place protocols and UN hazardous goods certification. Stainless steel commands premium positioning in pharmaceutical processing where surface finish specifications are stringent.
- Wood:Pallet-based bulk bins serve fresh produce harvesting and short-loop agricultural distribution where moisture exposure limits are manageable.
- Composite:Fiber-reinforced polymer constructions occupy narrowing mid-tier positioning as buyers consolidate around proven performance tiers.
Plastic dominates unit volume; metal dominates value capture.
End User:
Customer concentration and compliance burden intensity vary sharply across industrial verticals.
- Chemicals:UN Model Regulations and EPA hazardous waste container standards mandate certified secondary containment and enhanced closure systems. Processors in Texas and Louisiana face compressed retrofit timelines ahead of inspection windows.
- Pharmaceuticals:CDSCO-mandated serialization in India and FDA 21 CFR Part 11 requirements drive demand for stainless steel IBCs with integrated tracking capabilities.
- Agriculture:Seasonal demand peaks and single-trip economics favor flexible bulk containers for grain and fertilizer movements.
- Food & Beverage:FDA food contact regulations and FSSAI compliance in India constrain polymer formulations and coating chemistries for edible product handling.
Chemicals anchors procurement volume; pharmaceuticals anchors specification intensity.
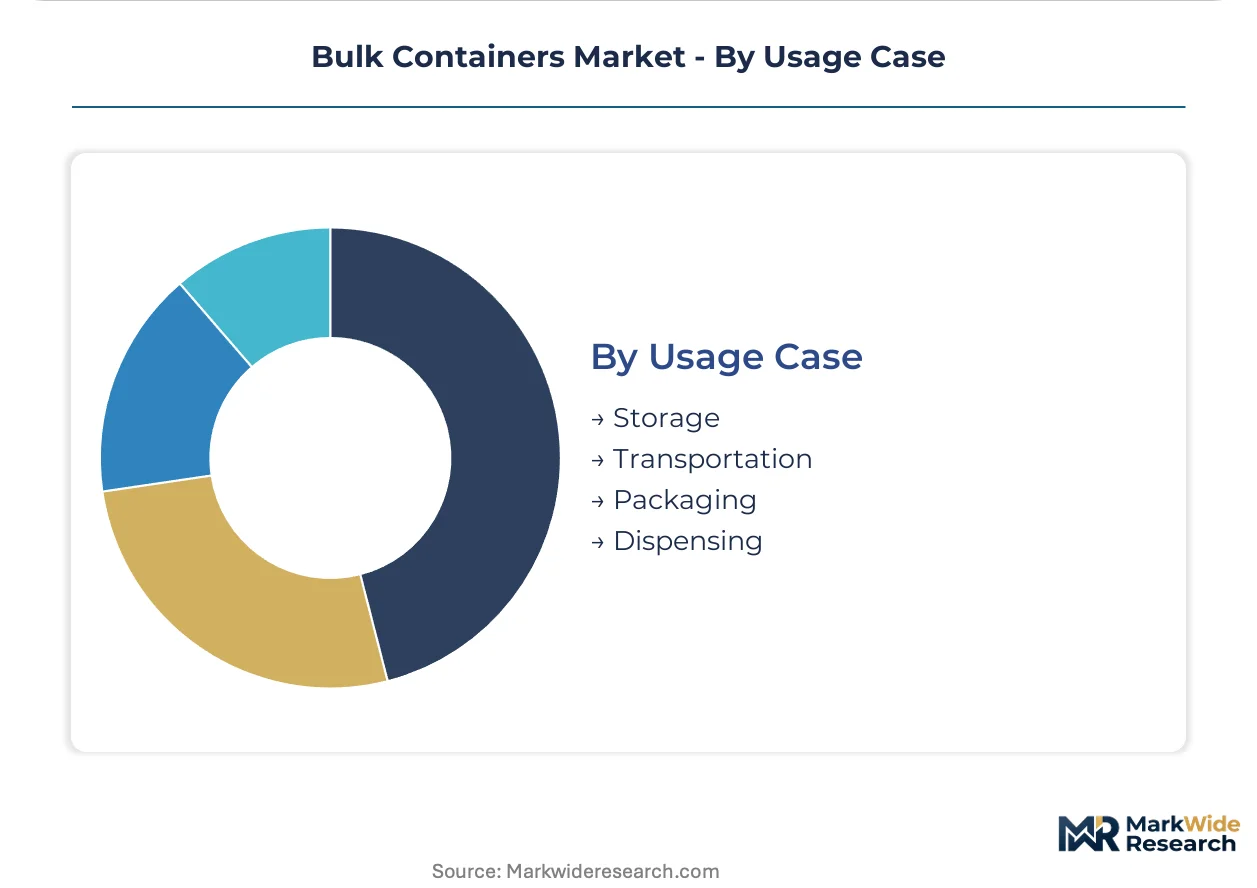
Usage Case:
Functional application determines asset turnover rates and service revenue attachment opportunities.
- Transportation:UN certification for dangerous goods and stack-load testing requirements dominate specification criteria for cross-border chemical shipments.
- Storage:Warehouse optimization demands drive standardization on 1,200x1,000mm footprint compatibility with European pallet racking systems.
- Packaging:Point-of-fill integration and line speed compatibility shape procurement decisions for food and pharmaceutical contract packagers.
- Dispensing:Valve and pump interface standardization enables automated emptying systems in chemical processing and pharmaceutical formulation.
Transportation commands asset intensity; dispensing commands service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized reconditioning technicians and logistics engineers concentrate in Germany's chemical corridor, anchoring Europe's most sophisticated container pooling networks. North American agricultural distributors cluster around Midwest grain terminals, while Asian pharmaceutical manufacturers scale stainless steel IBC fabrication for export markets.
United States
EPA hazardous waste container standards are compressing retrofit timelines for Texas and Louisiana chemical processors ahead of inspection windows. Agricultural distributors in the US Midwest now mandate chip-embedded totes for inbound grain receipts, automating custody transfer documentation. Metal container suppliers report six-month order backlogs as facilities accelerate compliance upgrades.
Germany
REACH substance restrictions are forcing chemical manufacturers around Ludwigshafen and Leverkusen to replace single-trip packaging with traceable, reusable systems. The EU Green Deal tightens material traceability rules for plastic containers serving pharmaceutical and chemical end users. Three specialized reconditioning facilities handle sixty percent of European returnable IBC volume from this industrial cluster.
India
CDSCO-mandated serialization requirements for active pharmaceutical ingredients are creating demand for stainless steel IBCs with integrated tracking capabilities. FSSAI compliance constrains polymer formulations for edible product handling in food processing hubs. Pharmaceutical exporters in Maharashtra and Gujarat are upgrading containment infrastructure to meet destination-market documentation standards.
China
Dual carbon goals are pressuring chemical processors to document full lifecycle carbon footprints for bulk packaging assets. NMPA regulations on pharmaceutical transport containers are tightening certification requirements for hazardous material handling. Yangtze River Delta manufacturers are scaling HDPE formulation advances that withstand aggressive chemical environments previously reserved for steel.
Brazil
ANVISA pharmaceutical packaging regulations are driving specification intensity for sterile bulk container imports serving São Paulo formulation facilities. Agricultural commodity exporters in Rio Grande do Sul favor flexible bulk containers for single-trip soybean and fertilizer movements where downstream cleaning infrastructure is absent. Port congestion at Santos is accelerating demand for stackable IBC geometries that optimize vessel container utilization.
Bulk Containers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. The market structure consolidates around multinational packaging groups with integrated reconditioning networks, while mid-sized regional fabricators defend niche positions through custom engineering capabilities. Strategic archetypes include steel drum heritage players extending into IBC systems, flexible packaging specialists leveraging agricultural commodity relationships, and stainless steel fabricators serving pharmaceutical serialization mandates. Dominant competitive moves center on backward integration into reconditioning services and geographic expansion through acquisition of regional pooling operators.
Within the steel drum heritage tier, Greif Inc. and Mauser Packaging Solutions exemplify manufacturers leveraging manufacturing scale to anchor supply contracts with agricultural distributors. Schütz GmbH & Co. KGaA occupies a position representing European-focused specialists sustaining dominance through closed-loop logistics infrastructure. These three companies collectively illustrate how container-as-a-service leasing models are capturing margin from risk-averse chemical processors seeking bundled compliance documentation with physical asset provision.
| Leading Market Players |
|---|
| Greif Inc. |
| Schütz GmbH & Co. KGaA |
| Mauser Packaging Solutions |
| Berry Global Group Inc. |
| Mondi plc |
| Time Technoplast Ltd. |
| Hoover Ferguson Group Inc. |
| Snyder Industries Inc. |
| DS Smith plc |
| Others |
Value Network & Pricing Analysis
Specialized reconditioning technicians concentrated in Germany's chemical corridor create labor-cost differentials that widen pricing-tier spreads between premium stainless steel IBCs and economy flexible bulk containers. REACH compliance documentation requirements and UN certification testing timelines further stratify procurement costs across buyer segments.
Pricing Analysis
Bundled container-as-a-service leasing separates from unbundled asset-only transactions as the dominant pricing split. Three-tier pricing structure across premium stainless steel, standard galvanized steel, and economy HDPE levels reflects certification grade and reconditioning service inclusion. Cost compression in the flexible bulk container tier is intensifying because woven polypropylene FIBCs externalize disposal economics. Agricultural distributors exhibit highest price sensitivity; pharmaceutical manufacturers show lowest sensitivity due to serialization mandates.
Supply Chain Analysis
Reverse-logistics flows for IBC refurbishment and reconditioning cycle back through specialized facilities in Germany, the United States, and India. Raw material supply draws from HDPE resin producers, European galvanized steel smelters, and stainless steel 316L fabricators. Single-source vulnerability concentrates in German reconditioning infrastructure handling majority European returnable volume. Distribution runs through chemical cluster proximity networks and agricultural terminal consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulk containers constitute a late-cycle quality story as REACH deadlines and FDA serialization mandates shift procurement toward premium-specification assets with full lifecycle traceability.
For Market Incumbents: Deepen backward integration into captive reconditioning capacity to defend against independent service providers capturing aftermarket margin. Expand stainless steel fabrication capabilities in India to serve CDSCO-mandated pharmaceutical serialization demand. Threat from flexible bulk container substitution in agriculture requires countering with total-cost-of-ownership documentation. For New Entrants and Emerging Players: Direct-to-procurement-platform digital channels offer the lowest-friction entry path for mid-sized chemical processors seeking alternative suppliers. White-space targets include RFID-embedded composite IBC designs for real-time tracking and Brazilian agricultural exporters needing Santos port-optimized stackable geometries. Go-to-market through container pooling software partnerships accelerates customer acquisition. For Investors and Strategic Acquirers: Packaging conglomerates with integrated logistics networks are the most active acquirers in this space, consolidating regional pooling operators to extend geographic coverage. Five-to-ten year viability hinges on regulatory compliance service bundling rather than commodity manufacturing. Acquisition target archetype: independent reconditioning specialists with multi-brand technical expertise. Signal to watch: EPA inspection window acceleration driving retrofit demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reconditioning | Captures recurring service revenue from chemical processors in Germany's Ludwigshafen cluster. |
| RFID-Embedded Composite Development | Enables real-time location tracking without metal interference for pharmaceutical shipments. |
| Geographic Expansion through Pooling Acquisition | Extends closed-loop logistics infrastructure into underserved Indian pharmaceutical export corridors. |
| Stainless Steel 316L Capacity Addition | Satisfies FDA clean-in-place protocols and CDSCO serialization requirements for API containment. |
| Container-as-a-Service Platform Launch | Bundles REACH compliance documentation with physical asset provision for risk-averse European buyers. |
Research Methodology
Multiple input streams — executive interviews with container pooling operators, procurement leads at chemical manufacturers, and reconditioning facility managers — were reconciled against trade flow databases, SEC filings from packaging conglomerates, and ECHA substance restriction updates. Bottom-up volume estimates from individual facility throughput triangulated with top-down market sizing derived from customs data and industry association reports.
Data-stream reconciliation across the projection horizon applied segment-level modeling for material type, end-use industry, and regional regulatory cluster. CAGRs emerged from historical trajectory analysis adjusted for REACH compliance deadline impacts and EPA inspection window timing. Forecast inputs incorporated HDPE formulation advancement rates and stainless steel IBC fabrication capacity expansion in India and China.
The model assumes a particular technology adoption path; alternative pathways for RFID-embedded composite designs would alter the outlook if sensor miniaturization costs decline faster than projected. Forecasts reflect assumptions about regulatory enforcement intensity and reconditioning facility utilization rates. Practitioners should monitor EPA inspection scheduling announcements and ECHA substance restriction expansion proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Slide Top Tins Market
Containers
PET Hinged Containers Market
Containers
Americas Container Technology Market
Containers
Canisters Market
Containers
Thermoformed Containers Market
Containers
Belgium Container Glass Market
Containers
Slotted Containers Market
Containers
Container Liner Market
Containers
Foldable Large Containers Market
Containers
Child-Resistant Containers Market
Containers
Foldable Container Market
Containers
Packer Bottle Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Cylindrical Cans Market
Containers
Concentrate Containers Market
Containers
Corrugated Bin Boxes Market