
 Cubesat Market | 2026-2036
Cubesat Market Size, Share, and Industry Trends Forecast 2026-2036
Cubesat Market Intelligence
Small satellite launch brokering is rewriting how payload capacity reaches orbit. Planet Labs PBC leverages its vertically integrated manufacturing to sustain rapid constellation replenishment cycles. Spire Global, Inc. anchors its position through proprietary radio occultation sensor networks for weather analytics.
A CubeSat denotes a miniaturized spacecraft built to standardized 10 cm × 10 cm × 10 cm unit dimensions, with mass typically below 1.33 kg per unit, designed for rapid prototyping and low-cost orbital access. Standard CubeSats and nanosatellites dominate current production volumes due to their compatibility with rideshare launch economics and simplified power budgets. Earth observation applications command the widest deployment base, while technology demonstration missions attract early-stage funding from government agencies testing novel subsystems.
FCC licensing requirements govern spectrum allocation and orbital debris mitigation for U.S.-based operators, while ESA's Clean Space initiative and ISO 24113 set debris-limitation benchmarks for European missions. NASA's CubeSat Launch Initiative provides no-cost deployment pathways that shape procurement behavior among academic and research institutions. Stakeholders must monitor evolving orbital traffic management protocols and frequency coordination rules as constellation density multiplies.
Market Dynamics
Launch cost compression and rideshare aggregation are fundamentally restructuring how payload operators access orbital slots, compressing deployment timelines from years to months for standardized form factors.
Growth Catalysts
- Streamlined FCC Licensing:The FCC's revised small satellite rules eliminated procedural bottlenecks for U.S. operators, cutting authorization timelines by more than half.
- Radio Occultation Networks:Weather analytics providers are deploying proprietary sensor constellations to capture atmospheric data previously unavailable from government sources.
- Agriculture Analytics:Commercial Earth observation operators are expanding constellation density to serve crop monitoring and insurance underwriting workflows.
Market Restraints
- Launch Capacity Concentration:Rideshare availability clusters around a limited set of launch providers and orbital planes, creating scheduling bottlenecks.
- Solar Array Supply:Miniaturized photovoltaic substrate production concentrates in East Asian manufacturing hubs, exposing operators to input cost volatility.
- Orbital Debris Liability:ISO 24113 compliance mandates end-of-life disposal systems that add mass and complexity to sub-2 kg platforms.
Strategic Opportunities
- Lunar Payload Services:NASA's Commercial Lunar Payload Services program channels sustained procurement budgets toward miniaturized spacecraft for cislunar missions.
- Dual-Use Weather Data:Convergence of radio occultation sensors with machine learning inference at the edge opens defense and civilian forecasting markets.
- Academic Deployment Pathways:NASA's CubeSat Launch Initiative provides no-cost orbital access that shapes procurement behavior among research institutions.
Industry Challenges
- RF Engineering Talent:Frequency coordination and spectrum management expertise remains scarce as constellation density multiplies.
- Integration Complexity:Subsystem miniaturization demands specialized cleanroom facilities and precision assembly workflows that strain capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cubesat Market |
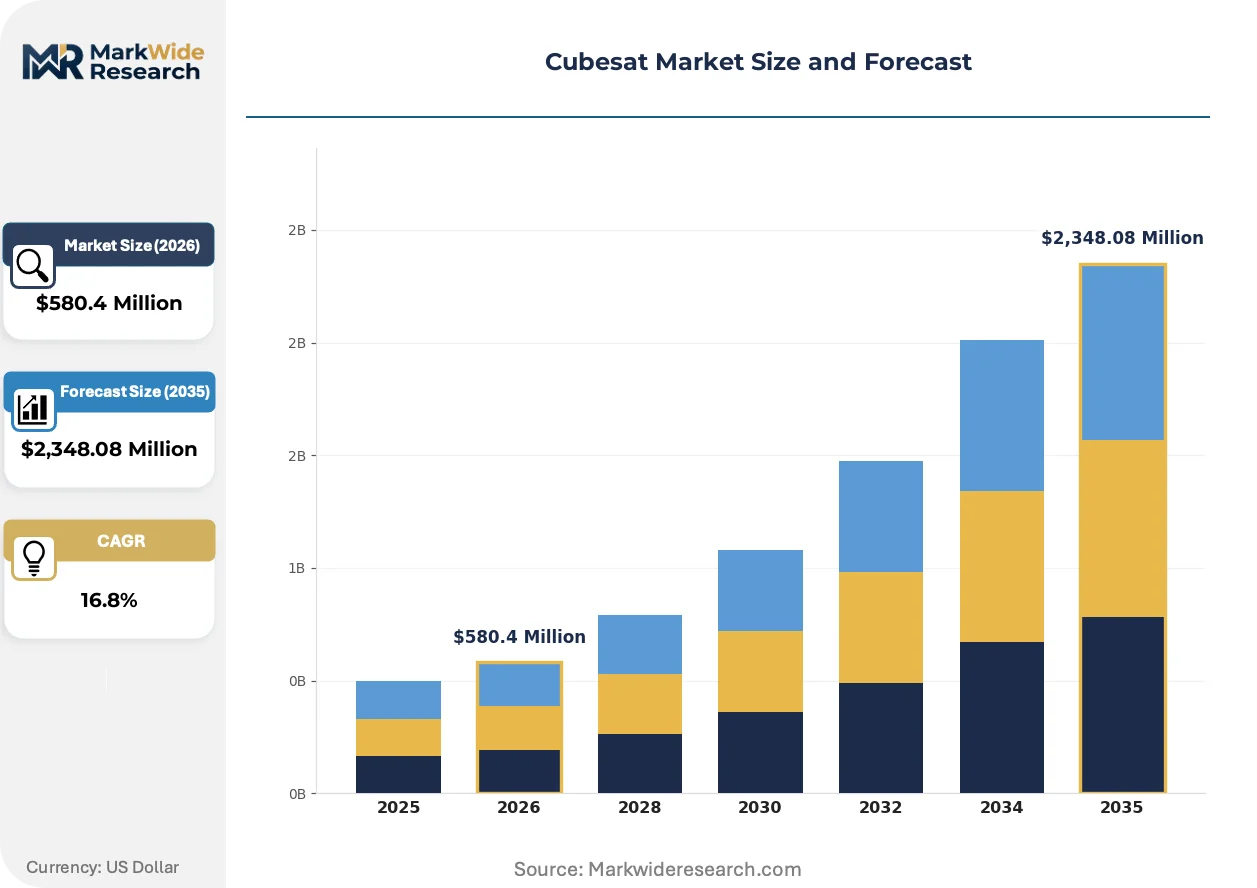
| Market Size in 2026 | $580.4 Million |
| Market Size in 2035 | $2,348.08 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standard Cubesats, Nanosatellites, Picosatellites, Microsatellites Application: Earth Observation, Communication, Scientific Research, Technology Demonstration End User: Academic Institutions, Government Agencies, Commercial Enterprises, Non-Profit Organizations Deployment Method: Dedicated Launch, Secondary Payload, International Space Station, Space Tugs |
| Companies Covered | Planet Labs PBC, Spire Global, Inc., Blue Canyon Technologies, LLC, Tyvak Nano-Satellite Systems, Inc., GomSpace, EnduroSat, AAC Clyde Space, Rocket Lab USA, Inc., Pumpkin, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cubesat Market Strategic Shifts & Innovations
Propulsion and power subsystem miniaturization is compressing platform mass budgets while expanding mission duration capabilities. Three developments are actively reshaping competitive positioning.
Electric propulsion is migrating from experimental demonstration to operational constellations. Commercial operators are adopting iodine-fueled thrusters for station-keeping and deorbit maneuvers. This technology is migrating from high-value science missions to commodity Earth observation buses, enabling multi-year operational lifetimes previously reserved for larger platforms.
REACH compliance deadlines in Europe are accelerating material substitution in printed circuit board substrates and solar cell interconnects. Manufacturers serving ESA missions must certify halogen-free laminates and lead-free solder joints. Small satellite builders targeting European anchor customers are redesigning avionics stacks to satisfy ECHA substance restrictions ahead of 2026 enforcement windows.
University procurement offices are consolidating payload development contracts under multi-year master agreements with established integrators. This channel consolidation displaces fragmented vendor relationships and accelerates standardization around flight-proven bus architectures. The shift is most visible in U.S. academic institutions participating in NASA's standardized deployment programs.
Cubesat Market Segmentation
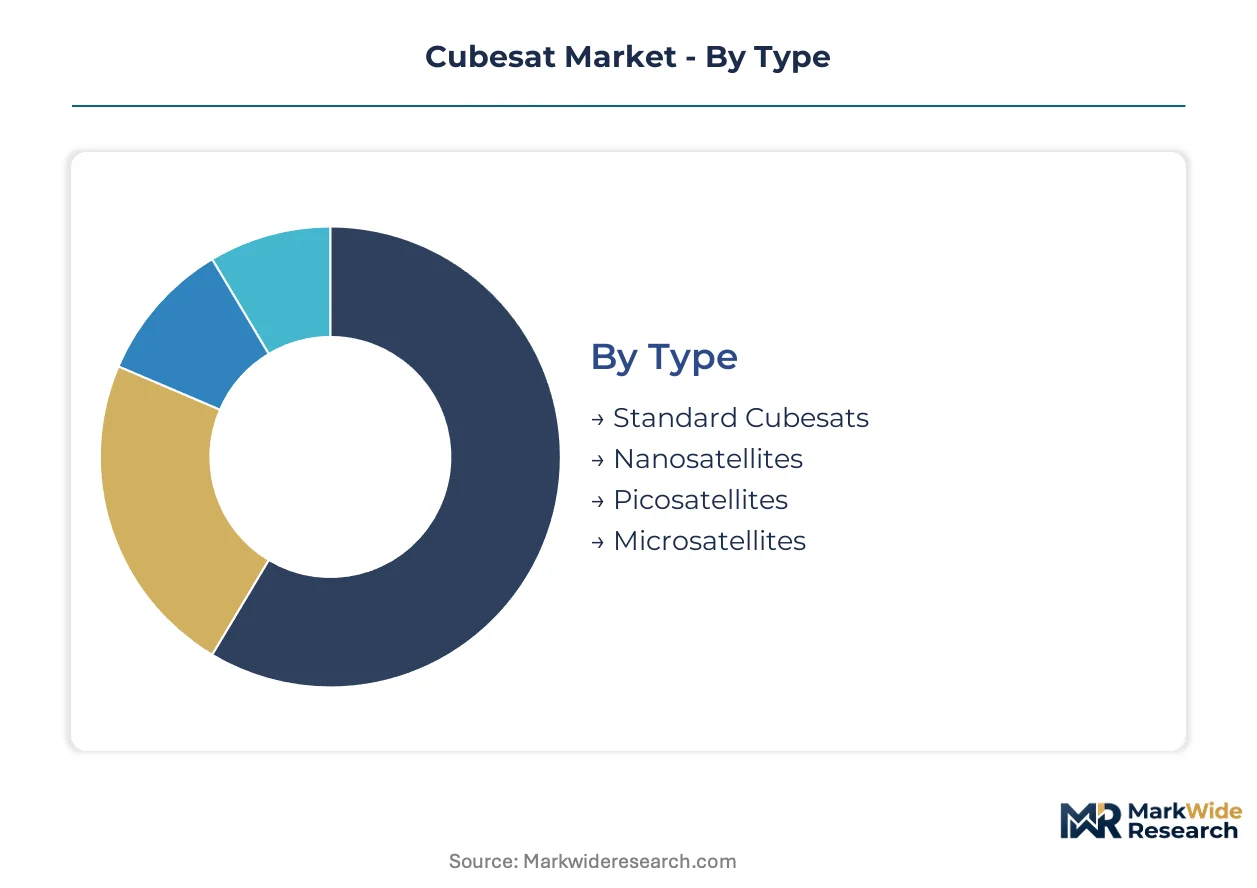
CubeSat segmentation reveals how standardized form factors, application requirements, and orbital access economics reshape procurement patterns across stakeholder classes. Platform mass categories determine launch aggregation possibilities, while end-user identity governs funding cycles and mission design constraints.
Type:
Platform mass tiers segment the market by launch economics compatibility and subsystem integration complexity.
- Standard Cubesats:These 10 cm × 10 cm × 10 cm units adhere to the Cal Poly CubeSat Design Specification, enabling rideshare slot aggregation with minimal integration overhead. NASA's CubeSat Launch Initiative prioritizes these form factors for academic deployments, channeling sustained procurement volume through standardized deployment pathways.
- Nanosatellites:Encompassing 1U through 6U configurations with mass budgets up to 12 kg, these platforms balance sensor payload capacity against launch cost compression. Commercial Earth observation operators in the United States favor 3U and 6U buses for agriculture analytics constellations, where proprietary radio occultation sensors demand expanded power and volume allocations.
- Picosatellites:Sub-1 kg platforms including PocketQube and femtosatellite variants serve technology demonstration missions with severe mass constraints.
- Microsatellites:Platforms between 10 kg and 100 kg occupy a transitional zone, attracting defense and cislunar applications requiring propulsion and extended mission durations.
Standard Cubesats command the established base. The steepest expansion runs through nanosatellites.
Application:
Mission purpose determines payload specification, orbital selection, and data product monetization pathways.
- Earth Observation:Multispectral and hyperspectral imaging payloads dominate commercial deployment, serving crop monitoring and insurance underwriting workflows. FCC licensing streamlines spectrum coordination for U.S.-based operators, accelerating constellation replenishment cycles.
- Communication:Store-and-forward messaging and IoT connectivity services target remote asset tracking applications. Maritime and aviation end-users in the United States drive procurement for beyond-line-of-sight data relay.
- Scientific Research:Ionospheric monitoring and space weather instrumentation attracts NASA and NSF funding cycles.
- Technology Demonstration:Novel subsystem validation missions de-risk propulsion and power innovations for operational constellations.
Earth observation commands the established base. Communication applications are climbing the fastest.
End User:
Funding source and procurement authority shape mission timelines, risk tolerance, and platform specification requirements.
- Academic Institutions:University-led missions leverage NASA's no-cost deployment pathways, consolidating procurement under multi-year master agreements with established integrators. Cleanroom facility access and RF engineering talent scarcity constrain program scale at U.S. research universities.
- Government Agencies:NASA's Commercial Lunar Payload Services and Space Force procurement budgets channel sustained investment into miniaturized spacecraft for cislunar and defense applications.
- Commercial Enterprises:Venture-backed constellation operators prioritize rapid deployment cycles and data product monetization.
- Non-Profit Organizations:Limited procurement volume concentrates on education outreach and open-data Earth observation missions.
Government agencies command the established base. Commercial enterprises are gaining share fastest.
Deployment Method:
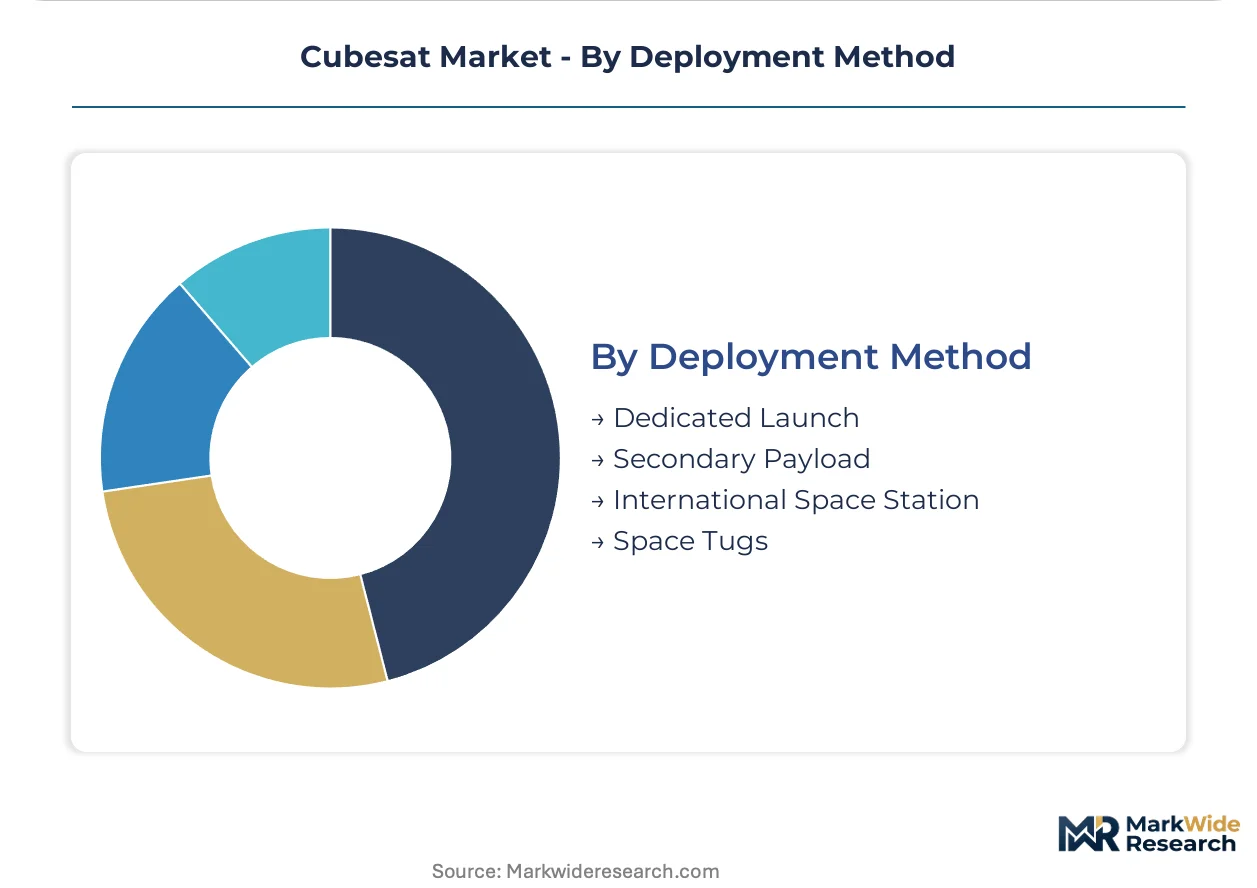
Orbital access mechanisms segment the market by schedule certainty, orbital plane selection, and integration complexity trade-offs.
- Dedicated Launch:Single-manifest missions deliver precise orbital insertion for formation flying and specialized inclination requirements. Premium pricing limits adoption to defense and high-value science missions.
- Secondary Payload:Rideshare aggregation dominates commercial Earth observation deployments, compressing deployment timelines from years to months. Launch capacity concentration around limited U.S. providers creates scheduling bottlenecks.
- International Space Station:Deployment from the Japanese Kibo module and U.S. commercial cargo vehicles serves academic and technology demonstration missions with ISS-compatible orbital parameters.
- Space Tugs:Orbital transfer vehicles from emerging providers promise plane change and altitude adjustment services, expanding rideshare accessibility to non-standard orbits.
Secondary payload commands the established base. Space tugs show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vandenberg Space Force Base and Cape Canaveral anchor United States orbital access capacity. These launch complexes channel rideshare aggregation economics that compress deployment timelines for standardized CubeSat form factors.
United States
NASA's Commercial Lunar Payload Services program and Space Force procurement budgets drive sustained demand for miniaturized spacecraft platforms. FCC streamlined small satellite licensing rules, cutting authorization timelines by more than half for domestic operators. Los Angeles and Denver metropolitan areas concentrate vertically integrated constellation operators and component manufacturing facilities serving Earth observation missions.
Germany
REACH compliance deadlines accelerate material substitution in printed circuit board substrates for ESA-class missions. ECHA substance restrictions mandate halogen-free laminates and lead-free solder joints ahead of 2026 enforcement windows. Munich and Stuttgart host precision assembly cleanroom facilities supplying European academic and commercial CubeSat programs.
Japan
University procurement offices consolidate payload development contracts under multi-year master agreements with established integrators. METI funding cycles support technology demonstration missions validating novel propulsion subsystems. Tokyo and Tsukuba research corridors concentrate RF engineering talent for frequency coordination and spectrum management.
United Kingdom
ISO 24113 debris-limitation benchmarks shape end-of-life disposal system requirements for sub-2 kg platforms. UK Space Agency grant programs channel investment into formation flying and specialized inclination missions. Harwell Science and Innovation Campus anchors satellite applications clusters linking academic institutions with commercial Earth observation operators.
India
ISRO's PSLV rideshare program offers cost-competitive secondary payload access to sun-synchronous orbits for international CubeSat operators. Department of Space procurement frameworks prioritize technology demonstration missions with severe mass constraints. Bengaluru and Hyderabad host subsystem suppliers specializing in miniaturized photovoltaic substrates and avionics integration.
Cubesat Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying standardized subsystems. The vendor base organizes around three strategic archetypes: vertically integrated constellation operators, modular bus manufacturers, and precision component fabricators. Consolidation pressure runs through university procurement channel consolidation and rideshare launch aggregation economics. Dominant competitive moves include strategic partnerships with launch providers and portfolio diversification into lunar payload services.
Among U.S.-based operators, Planet Labs PBC and Spire Global, Inc. exemplify vertically integrated constellation business models. GomSpace represents European modular platform specialization. These three entities anchor distinct competitive vectors: rapid constellation replenishment cycles, proprietary sensor network deployment, and standardized bus architectures for academic and commercial integrators.
| Leading Market Players |
|---|
| Planet Labs PBC |
| Spire Global, Inc. |
| Blue Canyon Technologies, LLC |
| Tyvak Nano-Satellite Systems, Inc. |
| GomSpace |
| EnduroSat |
| AAC Clyde Space |
| Rocket Lab USA, Inc. |
| Pumpkin, Inc. |
| Others |
Cost & Logistics Intelligence
Rideshare launch capacity underutilization in the United States is compressing slot pricing and forcing component suppliers to absorb margin pressure through volume commitments. This utilization dynamic rewards constellation operators with multi-satellite manifests while squeezing standalone academic missions into premium pricing tiers.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with three-tier pricing separating dedicated launch premiums from rideshare aggregation rates and ISS deployment economy slots. Price differentiation hinges on orbital plane specificity and FCC licensing priority status, with standard sun-synchronous access commanding mid-tier positioning. Pricing pressure stems from launch provider concentration around Vandenberg and Cape Canaveral facilities. Academic institutions exhibit highest price sensitivity, while defense and cislunar missions demonstrate lowest elasticity due to mission-critical orbital insertion requirements.
Supply Chain Analysis
Contract manufacturing concentration rests with East Asian photovoltaic substrate foundries and European precision assembly cleanrooms serving ESA-class missions. Geographic supply concentration centers on Taiwan for miniaturized solar cells, Germany for halogen-free PCB laminates, and Japan for RF component fabrication. Raw material dependencies include high-efficiency gallium arsenide wafers, iodine propellant formulations, and REACH-compliant solder interconnects. Single-source vulnerability in electric thruster valve assemblies poses structural risk. Distribution runs through vertically integrated constellation operators and university procurement master agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where data-analytics subscription layers expand faster than hardware unit economics, rewarding operators who bundle edge-compute inference with sensor network access.
For Market Incumbents: Pre-empt rideshare scheduling bottlenecks by securing multi-year launch provider commitments before capacity tightens. Deepen backward integration into iodine-fueled thruster production to capture propulsion margin pools and de-risk single-source valve vulnerabilities. FCC licensing priority status represents a defensible moat worth reinforcing through regulatory affairs investment. For New Entrants and Emerging Players: Build out lunar payload services capabilities ahead of NASA Commercial Lunar Payload Services procurement acceleration, targeting the cislunar segment where incumbent presence remains thin. Academic technology demonstration missions offer the most penetrable entry vector, with master agreement consolidation creating procurement pathway clarity. Lead with standardized 3U bus architectures that slot into existing rideshare aggregation workflows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electric propulsion subsystem manufacturing as iodine thruster production scales beyond experimental demonstration. Long-term viability favors modular bus manufacturers with flight-proven heritage and ESA certification pathways. Acquisition target archetypes include precision component fabricators holding REACH-compliant cleanroom capacity. The signal to watch is NASA CubeSat Launch Initiative funding allocation shifts as indicator of academic channel health.| Strategic Initiative | Industry Significance |
|---|---|
| Launch Provider Partnership | Secures rideshare slot priority before Vandenberg capacity constraints tighten. |
| Iodine Thruster Integration | Enables multi-year station-keeping for Earth observation constellations previously limited to chemical propulsion. |
| REACH Compliance Certification | Unlocks ESA procurement channels ahead of 2026 ECHA enforcement windows. |
| University Master Agreement | Consolidates fragmented academic procurement into recurring revenue streams. |
| Lunar Payload Capability | Positions for NASA CLPS program awards as cislunar mission frequency accelerates. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with satellite bus integrators, launch procurement officers, university program managers, and FCC regulatory specialists; and secondary validation against NASA budget justifications, ESA Clean Space technical notes, SEC filings from publicly traded constellation operators, and rideshare launch manifest databases. Bottom-up unit economics modeling triangulated against top-down addressable market sizing.
Forecast inputs considered platform mass tier adoption curves, rideshare launch cost compression trajectories, and regulatory licensing velocity across the analysis window. Segmentation dimensions modeled include form factor category, application purpose, end-user funding source, and deployment mechanism. CAGRs were derived from satellite unit deployment pipelines and launch provider capacity expansion announcements. Industry-specific inputs incorporated FCC authorization timeline trends and ESA technology demonstration mission cadence.
Stress conditions across launch provider consolidation, solar cell supply disruptions, and orbital debris liability threshold adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding rideshare aggregation economics and regulatory streamlining sustainability. Quarterly review of NASA CLPS procurement award velocity and FCC small satellite application backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
China Satellite-Based Earth Observation Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
China Satellite Imagery Services Market
Satellite
North America Remote Sensing Services Market
Satellite
Germany Satellite Communications Market
Satellite
Reconnaissance Satellite Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Satellite Compass Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Russia Satellite Imagery Services Market
Satellite
Germany Satellite Connectivity Market
Satellite
Italy Satellite Communication Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
4K Satellite Broadcasting Market
Satellite
All-Electric Propulsion Satellites Market