
 Satellite Compass Market | 2026-2036
Satellite Compass Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Compass Market Insights
Aftermarket service revenue is narrowing toward firmware updates and calibration contracts as hardware commoditization accelerates. Furuno leverages its Japanese manufacturing base to sustain premium positioning in multi-antenna systems. Garmin competes through consumer-channel dominance in recreational maritime segments. Kongsberg Maritime anchors its portfolio in offshore energy and autonomous vessel integration.
A satellite compass determines heading by measuring carrier-phase differences across multiple GNSS antennas, achieving accuracy within 0.1 degrees without magnetic interference. The device serves critical navigation functions where magnetic compasses fail near steel hulls or polar regions. Multi-antenna configurations lead product demand in commercial shipping, while single-antenna variants capture cost-sensitive recreational buyers. RTK technology commands the highest precision tier in hydrographic surveying, and IMU integration is emerging as the fastest-growing technology segment for UAV stabilization applications. Maritime navigation remains the mature revenue base, though precision agriculture and geospatial mapping represent expanding margin pools.
FCC equipment authorization governs signal reception architectures in United States deployments, while ETSI standards regulate European GNSS terminal interoperability. IMO resolution MSC.252(83) mandates satellite compass carriage for vessels over 150 gross tonnage, directly shaping replacement cycles and certification costs. Japan's MIC enforces radio equipment conformity that affects Nippon-market product design. Stakeholders must monitor multi-constellation compatibility investments as Galileo and BeiDou expand service coverage.
Market Dynamics
Fleet modernization mandates and GNSS resilience requirements are compressing replacement cycles while East Asian manufacturing clusters tighten supply-side concentration around multi-antenna architectures.
Growth Catalysts
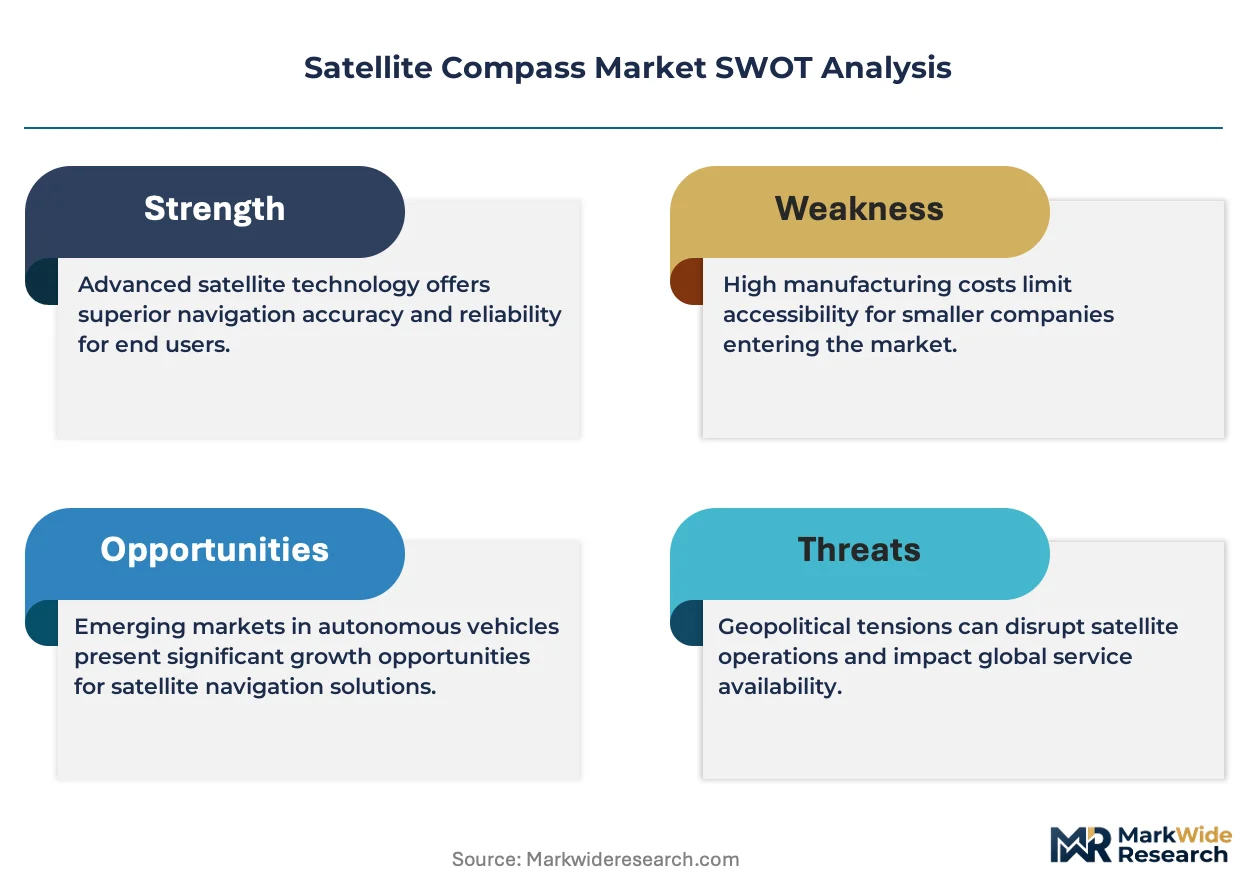
- IMO Resolution MSC.252(83):Mandatory satellite compass carriage for vessels exceeding 150 gross tonnage accelerates hardware refresh across commercial shipping fleets.
- Autonomous vessel integration:Unmanned surface vehicles and remotely operated ships demand centimeter-level heading precision that magnetic compasses cannot provide.
- RTK-GNSS convergence:Real-time kinematic positioning integration with satellite compasses enables sub-decimeter accuracy for hydrographic surveying operations.
Market Restraints
- Multi-frequency receiver cost structure:Galileo E6 and BeiDou B3 signal compatibility requires expensive RF front-end redesigns that inflate bill-of-materials.
- Antenna array supply concentration:Precision ceramic patch antenna manufacturing clusters in South Korean and Japanese component suppliers create single-source vulnerability.
- Magnetic compass residual demand:SOLAS-compliant backup requirements and small-craft price sensitivity preserve low-cost alternative navigation.
Strategic Opportunities
- Precision agriculture expansion:Autonomous tractor guidance systems in Brazilian and Australian farming operations represent underpenetrated demand for single-antenna cost-optimized units.
- UAV stabilization applications:IMU-satellite compass fusion for commercial drone photogrammetry creates technology convergence white space.
- EU Space Programme deployment:Galileo High Accuracy Service commercialization provides regulatory tailwind for multi-constellation receiver upgrades.
Industry Challenges
- RF interference mitigation engineering:L-band jamming and spoofing threats require specialized signal-processing expertise that remains scarce in marine electronics talent pools.
- Type approval timeline compression:FCC Part 25 and ETSI EN 303 413 certification cycles extend 14-18 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Compass Market |
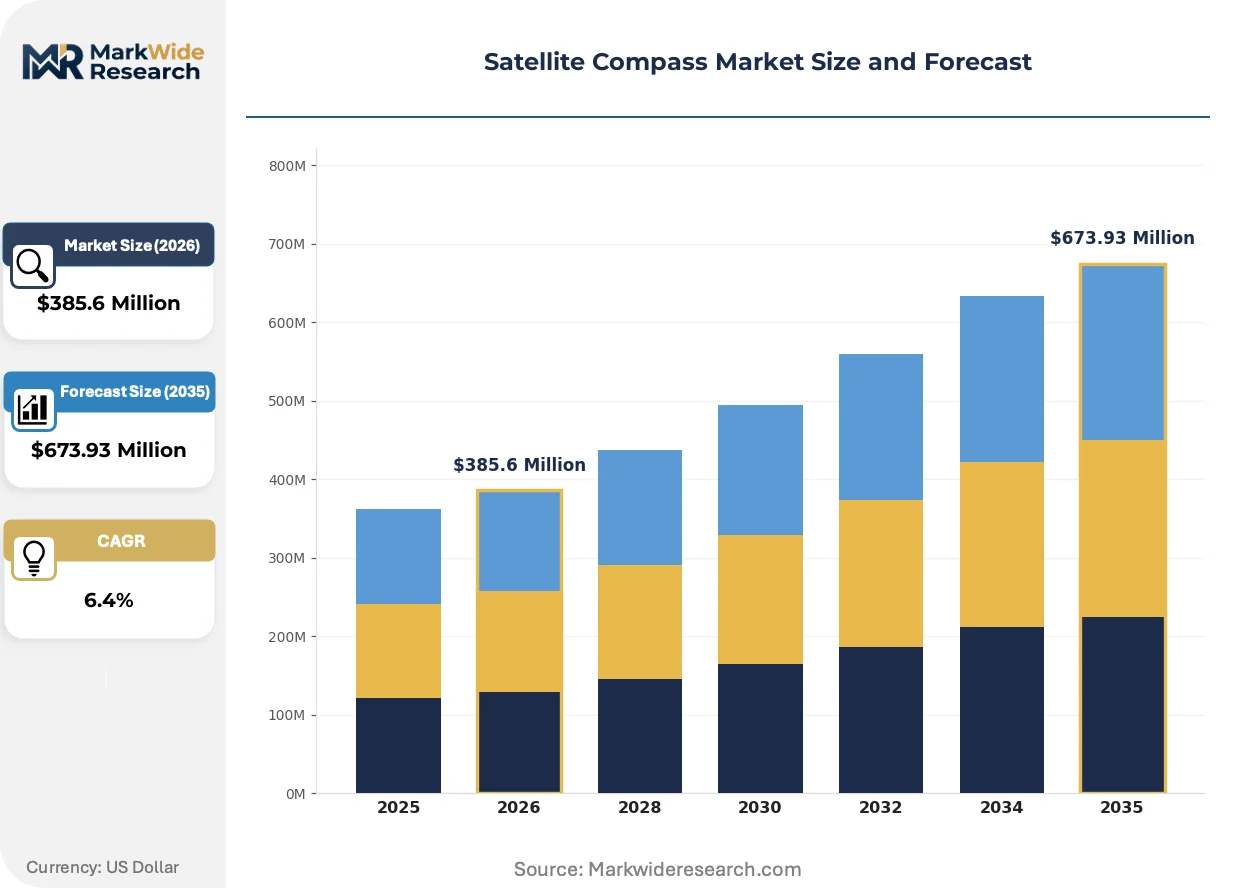
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Antenna, Single-Antenna, Dual-Frequency, Triple-Frequency, Multi-Constellation Technology: GNSS, RTK, PPP, IMU Integration, Differential Positioning Application: Maritime Navigation, Surveying, Unmanned Aerial Vehicles, Precision Agriculture, Geospatial Mapping End User: Shipping Operators, Survey Companies, UAV Manufacturers, Agricultural Firms, Mapping Agencies |
| Companies Covered | Furuno, Garmin, ComNav Marine, Kongsberg Maritime, Japan Radio Company, Advanced Navigation, SI-TEX Marine Electronics, Koden Electronics, Simrad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Compass Market Trends and Innovations
Carrier-phase differential techniques and multi-constellation architectures are redefining performance benchmarks while service revenue migrates toward predictive maintenance and calibration subscriptions.
Multi-frequency RTK-enabled satellite compasses achieve 0.02-degree heading accuracy through L1/L2/L5 signal processing and ionospheric correction algorithms. Offshore energy operators and dredging contractors are adopting these systems for dynamic positioning reference. Single-frequency hardware is rendering obsolete in applications demanding sub-meter absolute positioning.
Japan's MIC radio equipment conformity certification now mandates BeiDou B1C compatibility for type-approved maritime terminals. This regulatory expansion forces firmware architecture redesigns and antenna impedance matching adjustments. Shipbuilders in Nagasaki and Yokohama are accelerating multi-constellation receiver procurement to preempt certification delays.
Service contract unbundling separates hardware procurement from calibration and firmware update subscriptions. Fleet operators now source compasses through shipyard integrators while contracting directly with sensor manufacturers for predictive maintenance. This channel disintermediation concentrates in European commercial shipping, where vessel management companies centralize technical procurement decisions.
Satellite Compass Market Segmentation
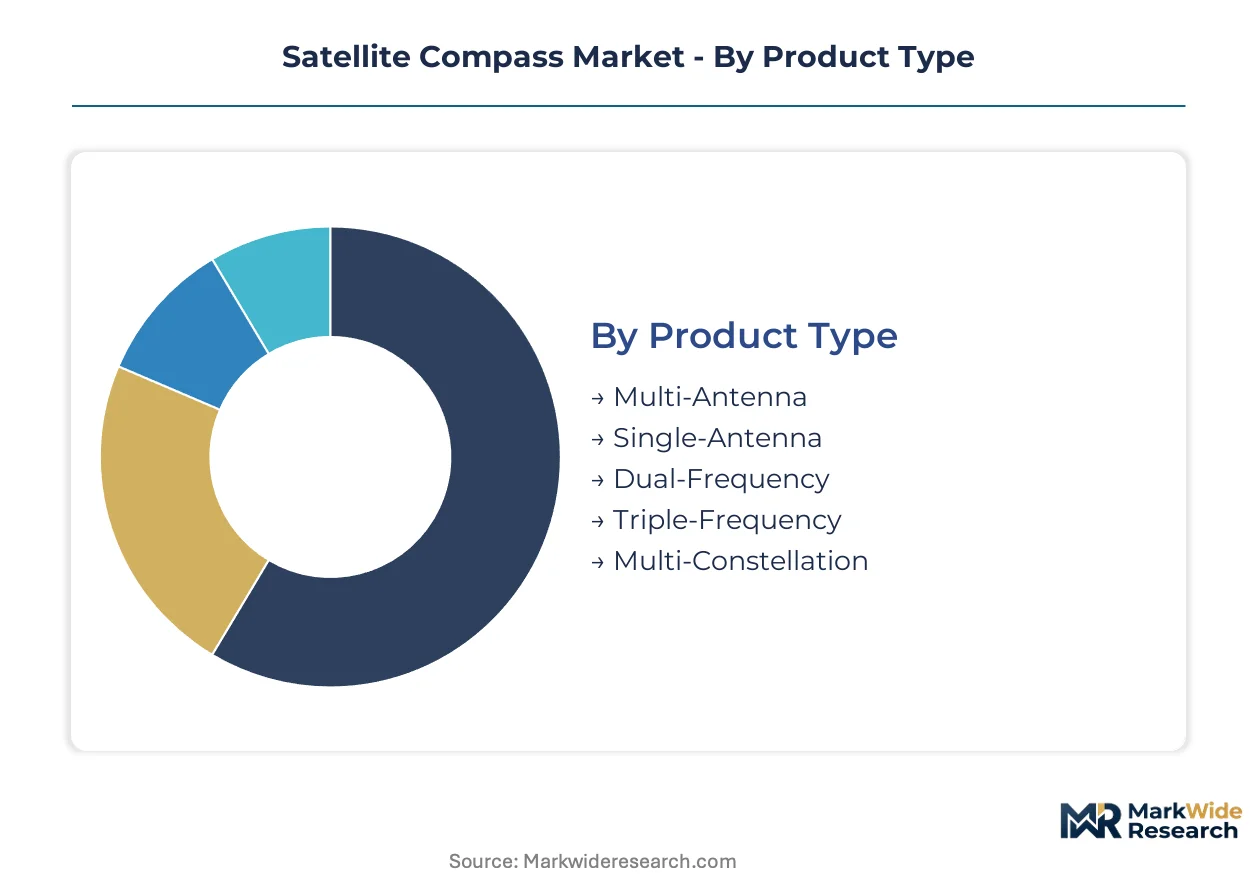
Segmentation in satellite compasses reveals divergent replacement economics across product tiers. Hardware refresh cycles stretch from recreational single-antenna units to mission-critical multi-frequency systems deployed in offshore energy.
Product Type:
Multi-antenna configurations command the longest operational lifecycles through modular upgrade paths, while single-antenna variants face compressed replacement from smartphone-integrated alternatives.
- Multi-Antenna:Carrier-phase differential processing across three or more antennas achieves 0.1-degree heading accuracy without magnetic interference. Commercial shipping fleets in South Korea and Japan specify these for dynamic positioning compliance, with replacement driven by IMO certification renewal rather than hardware failure.
- Single-Antenna:Cost-optimized units leverage single-frequency GNSS for recreational maritime and light agricultural guidance. Brazilian soybean operators and Australian broadacre farmers are adopting these for autosteering retrofits where absolute precision is secondary to cost containment.
- Dual-Frequency:L1/L2 signal reception enables ionospheric correction for sub-meter positioning in hydrographic survey vessels.
- Triple-Frequency:L1/L2/L5 architectures support modernized GPS and Galileo signals for centimeter-level accuracy in dredging operations.
- Multi-Constellation:GPS, GLONASS, Galileo, and BeiDou interoperability ensures signal availability in urban canyons and polar regions.
Multi-Antenna anchors the volume base while Multi-Constellation gains share at the steepest rate.
Technology:
Technology tiers stratify by precision economics, with differential positioning commanding premium pricing and IMU fusion capturing emerging demand in aerial mobility.
- GNSS:Standard satellite-based positioning without augmentation serves entry-level maritime and agricultural applications where meter-level accuracy suffices.
- RTK:Real-time kinematic positioning delivers 0.02-degree heading accuracy through carrier-phase integer ambiguity resolution. Offshore energy operators in the North Sea and Gulf of Mexico deploy RTK-enabled compasses for jack-up rig positioning, with procurement tied to charter contract cycles.
- PPP:Precise Point Positioning converges to centimeter accuracy without base station dependency, suiting transoceanic shipping lanes.
- IMU Integration:Sensor fusion with inertial measurement units maintains heading during GNSS signal blockage. UAV manufacturers in Switzerland and Israel specify these for photogrammetry missions where brief satellite occlusion corrupts mapping outputs.
- Differential Positioning:Beacon-based correction networks persist in coastal regions with established marine radio infrastructure.
GNSS sustains the installed base while IMU Integration expands most quickly in aerial applications.
Application:
Application demand fragments between mature maritime replacement and emerging precision agriculture deployment.
- Maritime Navigation:IMO-mandated carriage for vessels exceeding 150 gross tonnage creates regulated replacement demand. Fleet operators in Hamburg and Singapore centralize procurement through vessel management companies, compressing vendor margins through volume aggregation.
- Surveying:Hydrographic and geodetic survey contractors require RTK-grade heading for multibeam sonar orientation. Port authorities in Rotterdam and Shanghai are upgrading dredging fleets to triple-frequency systems for channel maintenance precision.
- Unmanned Aerial Vehicles:Commercial drone photogrammetry and inspection missions demand lightweight, low-power heading sensors.
- Precision Agriculture:Autonomous tractor guidance in Brazil, Australia, and Ukraine represents underpenetrated demand for cost-optimized single-antenna units.
- Geospatial Mapping:Mobile mapping vehicles and backpack systems integrate satellite compasses for sensor orientation in urban environments.
Maritime Navigation generates the revenue core while Precision Agriculture offers the steepest expansion trajectory.
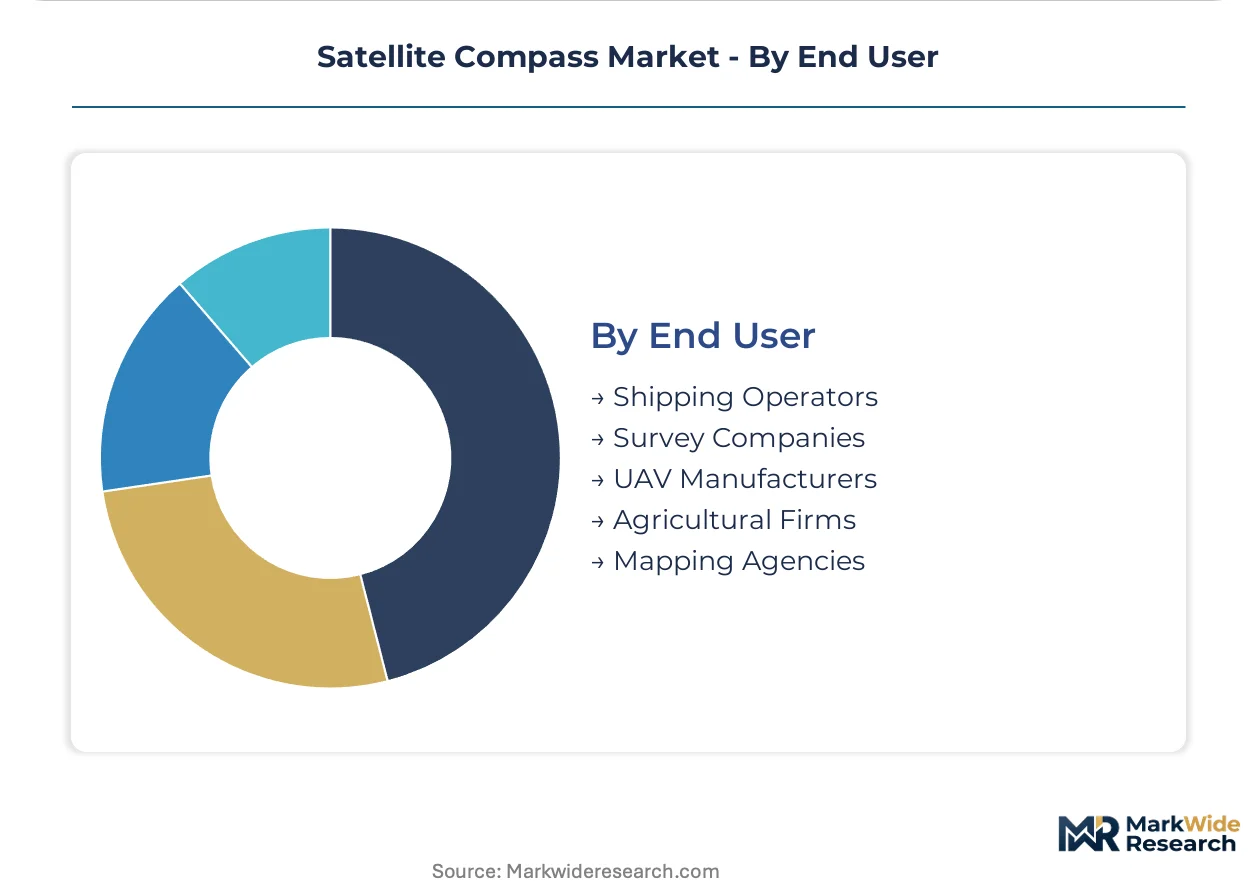
End User:
End-user procurement patterns diverge between centralized fleet technical management and distributed equipment integration.
- Shipping Operators:Container lines and bulk carriers specify multi-antenna systems through shipyard newbuild contracts. Technical procurement decisions concentrate in Copenhagen, Geneva, and Tokyo headquarters, with lifecycle costing favoring premium hardware over ten-year depreciation.
- Survey Companies:Hydrographic contractors maintain mixed fleets of owned and chartered vessels with heterogeneous sensor requirements.
- UAV Manufacturers:Drone OEMs in Shenzhen and Tel Aviv source compact heading modules through electronics distributors, prioritizing size and power over absolute precision.
- Agricultural Firms:Large-scale farming cooperatives and equipment dealerships drive aftermarket retrofit demand for autosteering upgrades.
- Mapping Agencies:National cartographic authorities specify multi-constellation receivers for geodetic network maintenance and mobile mapping infrastructure.
Shipping Operators dominate contract value while Agricultural Firms are climbing the fastest in unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in satellite compass procurement varies sharply by application tier. Recreational maritime buyers in Australia and Brazil prioritize unit cost over precision specifications. Commercial shipping operators in Japan and South Korea accept premium pricing for IMO-certified multi-antenna systems with decade-long service horizons.
Japan
Shipbuilders in Nagasaki and Yokohama drive multi-antenna system demand for newbuild contracts exceeding 150 gross tonnage. The country's MIC radio equipment conformity certification now mandates BeiDou B1C compatibility, forcing firmware architecture redesigns. Manufacturing clusters in Tokyo Bay concentrate precision ceramic patch antenna production for regional supply security.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor fleet modernization programs requiring RTK-grade heading sensors. The Korea Communications Commission enforces radio equipment certification timelines that compress product launch windows. Busan-Ulsan shipbuilding complexes source multi-constellation receivers to preempt IMO compliance delays on export vessels.
United States
Offshore energy operators in the Gulf of Mexico deploy triple-frequency systems for jack-up rig positioning precision. FCC Part 25 equipment authorization governs signal reception architectures with 14-18 month certification cycles. Houston technical procurement offices centralize sensor specifications for North Sea and West Africa charter operations.
Brazil
Soybean cooperatives in Mato Grosso and Rio Grande do Sul adopt single-antenna units for autosteering retrofits on legacy tractor fleets. ANVISA regulatory frameworks for precision agriculture equipment remain less prescriptive than maritime certification standards. Campinas equipment dealerships channel cost-optimized hardware to broadacre farming operations.
Germany
Container lines headquartered in Hamburg specify multi-antenna systems through shipyard newbuild contracts with ten-year depreciation horizons. ETSI EN 303 413 standards regulate GNSS terminal interoperability across European fleet deployments. Bremerhaven vessel management companies centralize technical procurement decisions, compressing vendor margins through volume aggregation.
Satellite Compass Market Competitive Landscape
Capability concentration sits with multi-antenna precision specialists; scale advantage sits with consumer-channel electronics distributors. The market structures around three tiers: Japanese and Norwegian manufacturers anchor premium maritime certification, consumer marine electronics brands capture recreational volume, and emerging sensor fusion specialists occupy aerial mobility niches. Dominant competitive moves include firmware subscription unbundling and multi-constellation receiver architecture licensing.
Among Japanese precision electronics manufacturers, Furuno and Japan Radio Company occupy positions within the IMO-certified maritime tier. Kongsberg Maritime anchors the Nordic offshore energy specialization. Garmin exemplifies consumer-channel scale advantage in recreational segments. These three represent distinct capability-scale positioning without overlapping core customer bases.
| Leading Market Players |
|---|
| Furuno |
| Garmin |
| ComNav Marine |
| Kongsberg Maritime |
| Japan Radio Company |
| Advanced Navigation |
| SI-TEX Marine Electronics |
| Koden Electronics |
| Simrad |
| Others |
Pricing and Supply Chain Analysis
Single-source vulnerability in precision ceramic patch antenna manufacturing compresses both hardware margins and supply security, forcing pricing stratification across certification tiers while concentrating procurement leverage in South Korean and Japanese shipbuilding clusters.
Pricing Analysis
Firmware calibration subscriptions and predictive maintenance contracts now drive lifetime value capture as hardware commoditization accelerates. Pricing stratifies across IMO-certified premium tiers, standard multi-antenna configurations, and economy single-antenna units. Cost compression in recreational maritime segments intensifies because smartphone-integrated alternatives displace standalone hardware. Brazilian agricultural cooperatives exhibit highest price sensitivity, while Hamburg-based container lines accept premium positioning for decade-long depreciation cycles.
Supply Chain Analysis
Extended payment terms from shipyard integrators strain component supplier cash conversion cycles. Manufacturing clusters in South Korea, Japan, and coastal China anchor RF front-end and antenna array production. Bill-of-materials draws from precision ceramics, multi-frequency receiver chipsets, and ionospheric correction firmware. Tariff exposure on Chinese-sourced RF components threatens margin stability. Distribution runs through shipyard system integrators, vessel management companies, and agricultural equipment dealerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around IMO certification creates formidable defensive moats, with type approval timelines and multi-constellation firmware requirements locking in incumbent advantages.
For Market Incumbents: Pre-empt emerging UAV stabilization demand through IMU-satellite compass fusion R&D before Israeli and Swiss drone OEMs consolidate supplier relationships. Deepen backward integration into precision ceramic antenna production to offset South Korean supply concentration. Accelerate Galileo High Accuracy Service certification to capture EU Space Programme tailwinds. For New Entrants and Emerging Players: Ukrainian broadacre farming operations present immediate white-space opportunity for cost-optimized single-antenna units with simplified firmware architectures. Target precision agriculture retrofit channels through Campinas and Mato Grosso equipment dealerships. Pursue white-label partnerships with Brazilian agribusiness cooperatives to bypass maritime certification barriers. For Investors and Strategic Acquirers: IMO Resolution MSC.252(83) implementation reshapes the acquisition landscape toward multi-constellation firmware capabilities and MIC-type-approved product portfolios. Five-to-ten-year viability favors targets with captive BeiDou B1C and Galileo E6 compatibility. Monitor Japan MIC certification queue lengths as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Firmware Architecture Licensing | Galileo E6 and BeiDou B3 compatibility unlocks IMO-certified premium tier access. |
| IMU-Satellite Compass Fusion Development | Swiss and Israeli UAV OEMs specify sensor fusion for photogrammetry mission integrity. |
| Predictive Maintenance Subscription Unbundling | Hamburg vessel management companies centralize technical procurement through direct manufacturer contracts. |
| Precision Ceramic Antenna Backward Integration | Tokyo Bay manufacturing clusters secure supply security against Korean single-source exposure. |
| Galileo High Accuracy Service Certification Investment | EU Space Programme commercialization mandates receiver upgrades across Rotterdam and Hamburg fleets. |
Research Methodology
Operator-level perspectives from fleet technical managers, shipyard integration engineers, hydrographic survey contractors, and agricultural equipment dealers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through IMO resolution texts, FCC Part 25 equipment authorization databases, ETSI EN 303 413 standards documentation, and MIC radio equipment conformity bulletins. Bottom-up unit shipment estimates triangulated against top-down fleet modernization expenditure patterns.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across antenna configuration tiers, differential positioning technology grades, maritime versus agricultural application splits, and end-user procurement centralization levels. CAGRs derived from replacement cycle compression analysis and multi-constellation receiver upgrade elasticity. Forecast inputs incorporated GNSS constellation deployment timelines and regional regulatory certification queue data.
Macroeconomic conditions sit as an overlay; deviation in shipbuilding order backlogs, agricultural commodity prices, or L-band spectrum allocation would shift the trajectory. Forecasts reflect documented assumptions on IMO enforcement consistency and multi-constellation signal availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Remote Sensing Services Market
Satellite
Satellite Imaging Market
Satellite
Satellite Communication System Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
4K Satellite Broadcasting Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
Global LEO Satellite Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
Small Satellite Launch Market
Satellite
Optical Satellite Communication Market
Satellite
Communication Satellite Launch Services Market
Satellite
Reconnaissance Satellite Market
Satellite
Satellite Parts and Components Market
Satellite
M2M Satellite Communication Market
Satellite
Argentina Satellite-Based Earth Observation Market
Satellite
US Satellite Connectivity Market