
 Russia Satellite Imagery Services Market | 2026-2036
Russia Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Satellite Imagery Services Market Insights
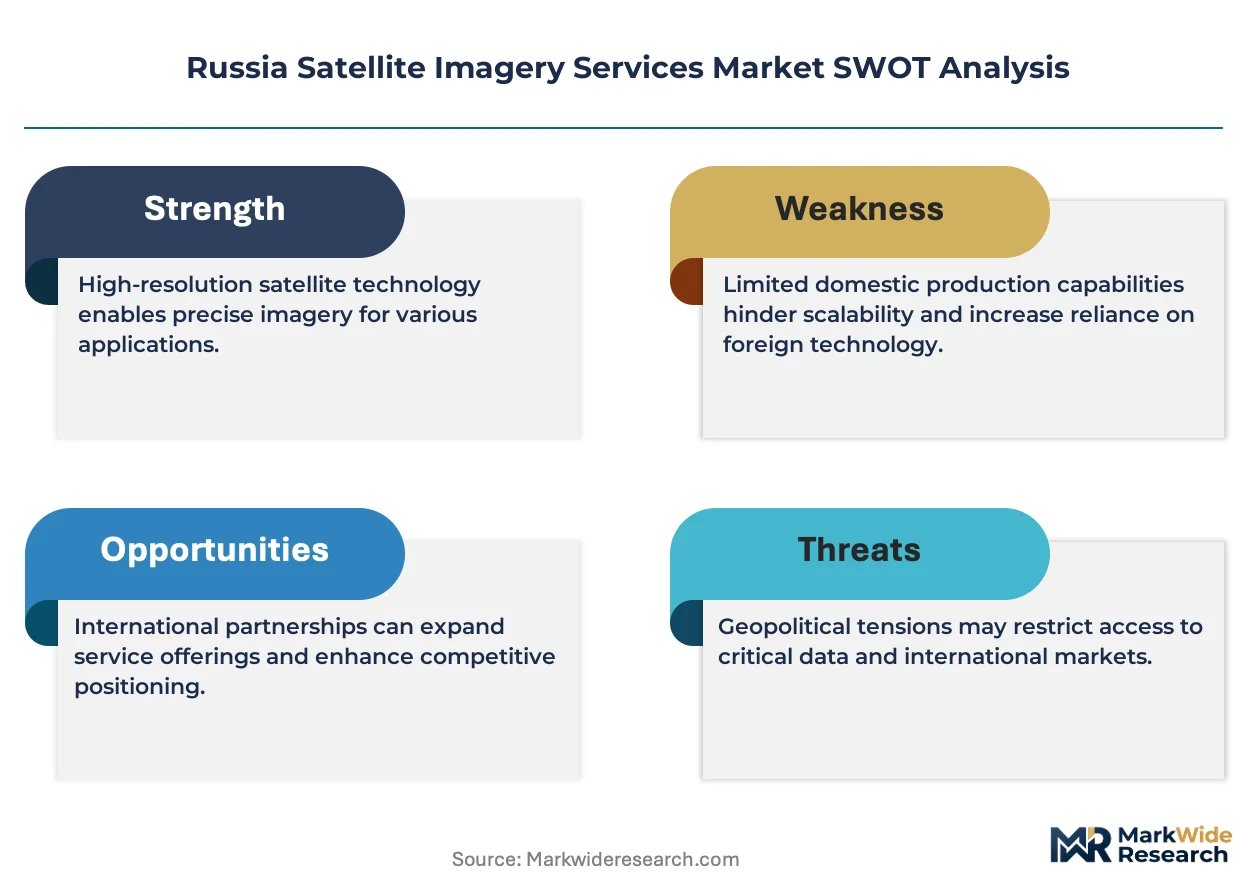
High-resolution synthetic aperture radar is expanding its share of defense procurement budgets as cloud-penetrating capability replaces optical-only reliance in northern latitudes. SCANEX Group leverages its domestic ground station network to sustain data delivery advantages across Siberian and Arctic zones. Gazprom Space Systems anchors its position through captive demand from energy pipeline monitoring, while Geospatial Agency Innoter competes on specialized analytics for mineral exploration clients.
Russia satellite imagery services encompass the acquisition, processing, analysis, and distribution of Earth observation data captured by orbital platforms, with spatial resolutions ranging from sub-meter panchromatic to 30-meter multispectral coverage for agricultural indexing. These services support operational decision-making in terrain modeling, resource extraction planning, and environmental compliance verification across vast territorial extents. Optical imaging dominates current government contract volumes, though radar imaging segments are gaining structural priority in defense and Arctic maritime applications where all-weather reliability commands premium pricing. Agriculture and oil & gas applications represent mature revenue pools, while urban planning segments are attracting renewed municipal investment as regional governments digitize land-use cadasters.
Roscosmos licensing frameworks and national data security protocols restrict foreign satellite operator market access, creating protected demand channels for domestic service providers. The country's technical standards body mandates encryption and territorial distribution controls on imagery exceeding specified resolution thresholds, shaping procurement specifications for defense and intelligence end users. Stakeholders must monitor evolving restrictions on cross-border data flows and resolution thresholds that could reshape competitive boundaries between state-affiliated and independent analytics vendors.
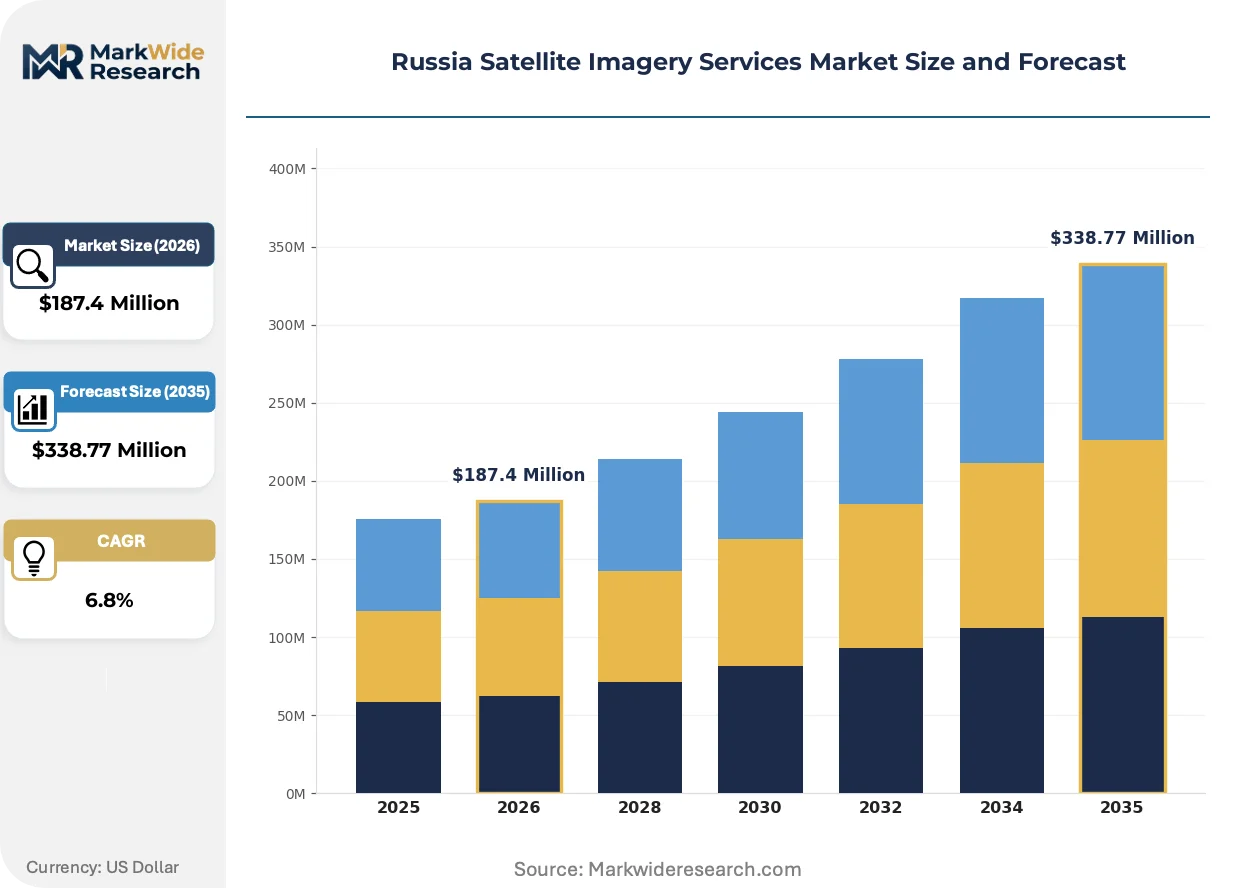
Market Dynamics
Roscosmos licensing frameworks and national data security protocols are compressing foreign operator access while concentrating procurement authority around state-affiliated ground station networks and domestic analytics vendors.
Growth Catalysts
- Arctic maritime surveillance mandates:Northern Sea Route traffic monitoring requirements are pulling radar-capable satellite tasking into defense procurement pipelines.
- Ministry of Defense resolution thresholds:Updated technical specifications for border monitoring are expanding sub-meter optical imagery contract volumes.
- Pipeline integrity regulations:Gazprom and Transneft operational mandates are sustaining recurring monitoring service subscriptions across Siberian corridor infrastructure.
Market Restraints
- Ground station capital intensity:Arctic and Far East receiver network expansion demands sustained infrastructure investment beyond commercial operator balance sheets.
- Launch capacity bottlenecks:Soyuz and Angara manifest prioritization for federal payloads creates satellite deployment queue uncertainty for commercial constellation operators.
- Foreign component substitution timelines:Western electronics import substitution programs are extending sensor payload qualification cycles by 18-24 months.
Strategic Opportunities
- Far East agricultural indexing:Amur and Primorsky Krai regional governments are digitizing cadaster systems without mature local analytics vendor presence.
- SAR-optical sensor fusion:Defense and energy clients are requesting unified analytics platforms combining all-weather coverage with spectral classification.
- Municipal urban planning digitization:Regional capital cities outside Moscow are launching geospatial database modernization tenders with limited incumbent competition.
Industry Challenges
- Geospatial data scientist scarcity:Russian university programs produce insufficient machine learning specialists trained on orbital imagery feature extraction.
- Cross-border data transfer compliance:Service providers face operational friction routing analytics outputs to international energy and mining clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Satellite Imagery Services Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Observation, Mapping, Surveillance, Disaster Management Application: Agriculture, Forestry, Oil & Gas, Urban Planning Technology: Optical Imaging, Radar Imaging, Multispectral Imaging, Hyperspectral Imaging End User: Government, Defense, Environmental Agencies, Research Institutions |
| Companies Covered | Roscosmos Space Agency, SCANEX Group, Gazprom Space Systems, Geospatial Agency Innoter, East View Geospatial, Data East, Glavkosmos, Racurs, NextGIS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Satellite Imagery Services Market Trends and Innovations
Synthetic aperture radar capabilities are penetrating previously optical-dependent application segments as cloud cover and seasonal darkness expose coverage gaps in northern latitudes. Three distinct shifts are restructuring competitive positioning and procurement specifications.
Multi-frequency SAR payloads are absorbing mission profiles previously assigned to electro-optical sensors in maritime domain awareness and ice monitoring applications. Northern Fleet and Rosatomflot operational units are mandating all-weather tasking for route planning through ice-consolidated waters. This technology shift is compressing pricing premiums historically commanded by high-revisit optical constellations in Arctic service contracts.
Roscosmos has tightened orbital data encryption standards for imagery exceeding 0.5-meter ground sample distance, mandating domestic ground processing and territorial storage. Commercial operators must now route raw feeds through licensed domestic facilities before foreign client distribution. Defense and intelligence procurement specifications are absorbing these requirements fastest, while energy sector contracts face compliance timeline extensions.
Subscription-based tasking models are displacing per-scene procurement in agricultural and pipeline monitoring verticals. Large energy and logistics clients are consolidating vendor relationships around annual capacity reservations rather than transactional imagery purchases. This behavioral shift concentrates most visibly in the Central Federal District, where federal procurement centers and geospatial analytics clusters enable direct vendor-client negotiation.
Russia Satellite Imagery Services Market Segmentation
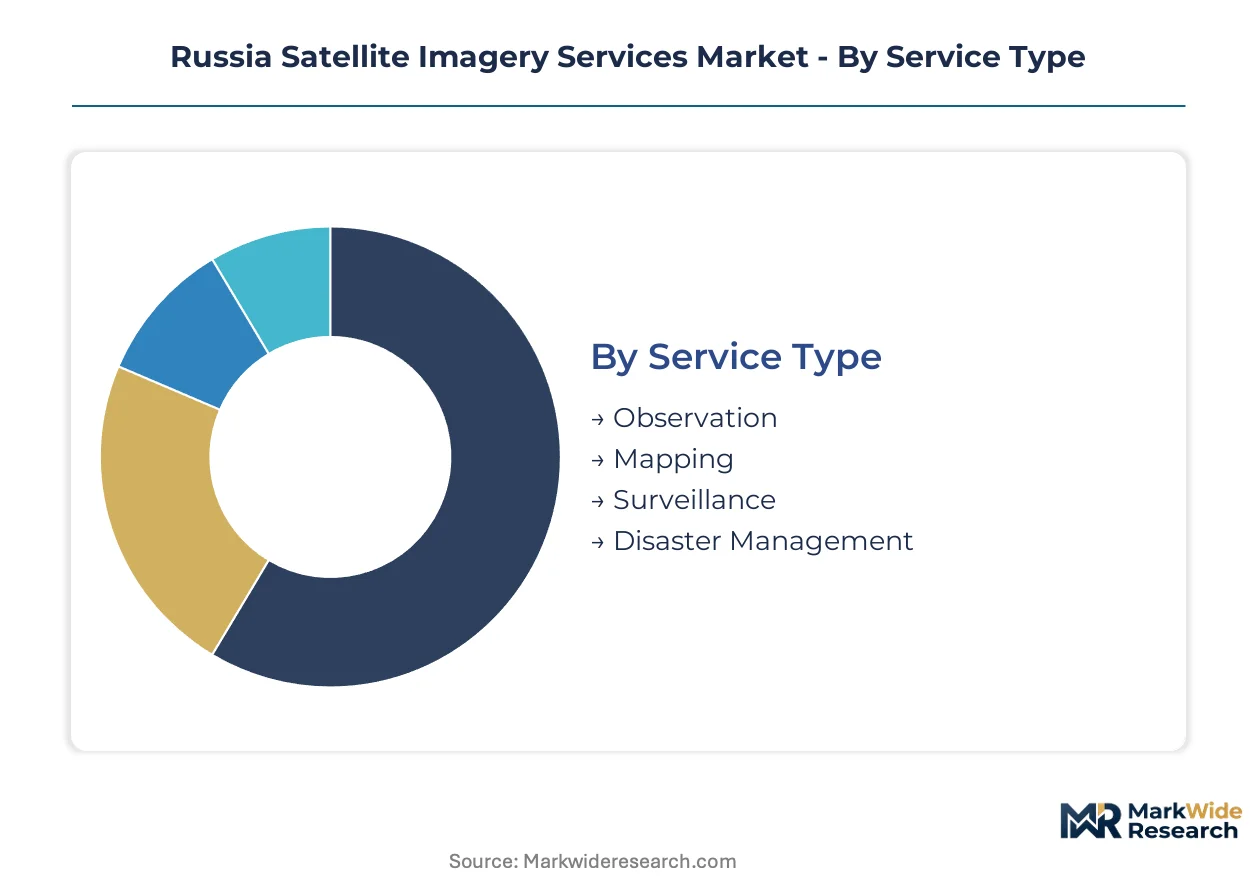
Russia's satellite imagery market fragments across procurement authority, technical capability, and end-use security classification. Segment boundaries shift as defense procurement absorbs commercial analytics platforms and Roscosmos licensing restructures foreign data access.
Service Type:
Government buyers differentiate service tiers by operational tempo and data latency requirements, not merely spatial resolution.
- Observation:Standard acquisition services deliver archived imagery with 24-72 hour turnaround for agricultural indexing and cadaster verification. Demand clusters in the Central Federal District where federal procurement centers enable direct contract negotiation with SCANEX Group and domestic ground station operators.
- Surveillance:Persistent monitoring with sub-hourly revisit frequencies supports border infrastructure and strategic asset tracking. The Ministry of Defense resolution thresholds mandate this tier for northern and eastern perimeter coverage, compressing pricing premiums historically attached to reactive tasking.
- Mapping:Large-area orthorectification for topographic base layers serves mineral exploration licensing and pipeline route planning.
- Disaster Management:Rapid-response tasking protocols activate for wildfire monitoring and flood extent mapping across Siberian and Far East federal districts.
Volume sits with Observation; growth tilts toward Surveillance.
Application:
Revenue concentration follows extractive industry operational mandates and state infrastructure monitoring obligations.
- Oil & Gas:Pipeline integrity regulations require recurring thermal anomaly detection and third-party interference monitoring across the Siberian corridor. Gazprom and Transneft sustain multi-year subscriptions combining optical and radar feeds, with SAR-optical fusion gaining priority for all-weather reliability.
- Agriculture:Crop health indexing and yield forecasting leverage 10-30 meter multispectral coverage for regional subsidy allocation. Amur and Primorsky Krai governments are digitizing cadaster systems without mature local vendor presence, opening procurement opportunities.
- Forestry:Illegal logging detection and fire risk assessment utilize seasonal imagery stacks for concession compliance.
- Urban Planning:Municipal geospatial database modernization concentrates in regional capitals outside Moscow with limited incumbent competition.
Revenue concentrates in Oil & Gas; steepest expansion trajectory appears in Urban Planning.
Technology:
Platform selection hinges on atmospheric penetration needs and orbital data security classification under Roscosmos encryption mandates.
- Radar Imaging:Synthetic aperture radar payloads penetrate cloud cover and seasonal darkness that disable optical systems in Arctic latitudes. Northern Fleet and Rosatomflot operational units mandate all-weather tasking for ice-consolidated route planning, compressing historical premiums commanded by high-revisit optical constellations.
- Optical Imaging:Sub-meter panchromatic and multispectral sensors dominate current government contract volumes for border monitoring and strategic asset identification. Roscosmos tightened encryption standards for imagery exceeding 0.5-meter ground sample distance, mandating domestic ground processing before foreign distribution.
- Multispectral Imaging:Five-to-ten band spectral classification supports agricultural health indexing and mineral exploration target generation.
- Hyperspectral Imaging:Narrow-band spectral signatures enable material identification for environmental contamination assessment and precision agriculture.
Procurement volume favors Optical Imaging; capability investment shifts toward Radar Imaging.
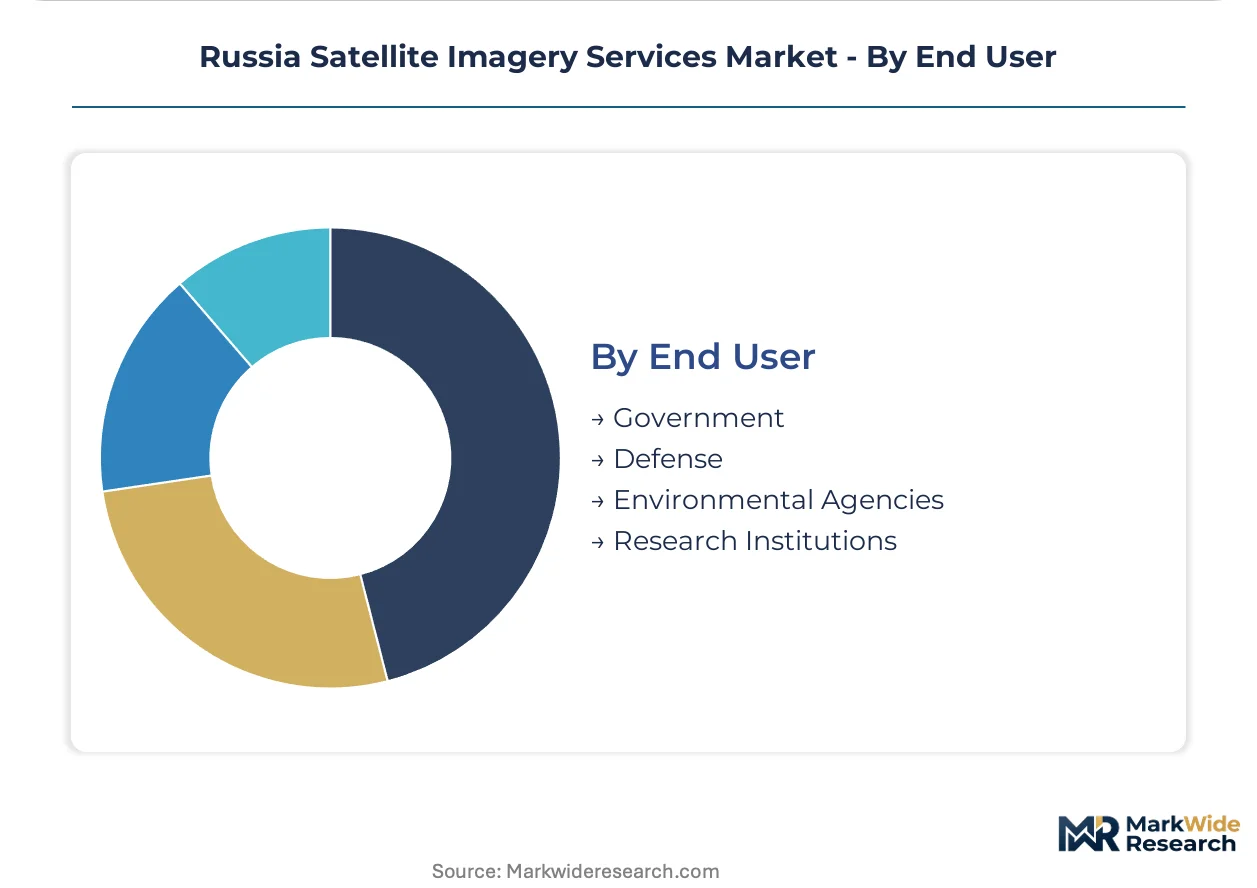
End User:
Security clearance and data sovereignty requirements partition vendor access and pricing structures.
- Defense:Classified procurement pipelines absorb high-resolution SAR and optical feeds for border monitoring and maritime domain awareness. Updated technical specifications expand sub-meter imagery contract volumes while mandating domestic ground station routing and territorial storage.
- Government:Federal and regional agencies procure cadaster modernization, infrastructure monitoring, and environmental compliance verification through licensed domestic distributors.
- Environmental Agencies:Wildfire, flood, and pollution monitoring utilize lower-resolution archives with rapid tasking escalation protocols.
- Research Institutions:Academic access to archived datasets supports climate and geophysical studies within cross-border data transfer compliance frameworks.
Budget authority concentrates in Defense; institutional expansion appears in Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates in Moscow and the surrounding Central Federal District, where federal defense contracts and geospatial analytics clusters create demand density unmatched elsewhere in the country.
Central Federal District
Ministry of Defense resolution thresholds for sub-meter border monitoring imagery sustain contract volumes here. Roscosmos licensing frameworks mandate domestic ground processing for high-resolution feeds, routing commercial operators through licensed Moscow facilities. The capital hosts SCANEX Group headquarters and federal procurement centers that negotiate directly with imagery vendors.
Northwestern Federal District
Arctic maritime surveillance mandates from Northern Fleet operational units pull radar-capable satellite tasking into regional procurement pipelines. Rosatomflot icebreaker route planning requires all-weather SAR coverage through ice-consolidated waters. Saint Petersburg anchors the ground station network serving Barents Sea and Kara Sea monitoring obligations.
Siberian Federal District
Transneft and Gazprom pipeline integrity regulations require recurring thermal anomaly detection across the Siberian corridor infrastructure. The national space regulator's territorial distribution controls apply to imagery exceeding resolution thresholds for energy sector critical assets. Novosibirsk clusters geospatial analytics capacity for wildfire monitoring and concession compliance verification.
Far Eastern Federal District
Amur and Primorsky Krai regional governments are digitizing cadaster systems without mature local analytics vendor presence, opening procurement opportunities. The Ministry of Defense eastern perimeter coverage requirements expand surveillance-tier contract volumes for border infrastructure tracking. Vladivostok serves as the maritime domain awareness coordination point for Northern Sea Route eastern terminus operations.
Ural Federal District
Mineral exploration licensing and resource extraction planning sustain demand for large-area orthorectification services. The technical standards body mandates encryption controls on imagery used for strategic asset identification in the extractive sector. Yekaterinburg concentrates specialized analytics vendors serving metals and mining clients with spectral classification capabilities.
Russia Satellite Imagery Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with state-affiliated entities commanding defense procurement pipelines while independent analytics vendors compete for commercial verticals. The vendor base concentrates around ground station network operators and domestic data processors licensed under Roscosmos frameworks. Three archetypes dominate: state-space holding companies with captive launch and orbital assets, regional ground station networks with Siberian and Arctic coverage advantages, and specialized analytics boutiques serving extractive industry clients. Competitive moves center on SAR-optical sensor fusion platform development and Far East regional expansion to capture agricultural indexing digitization tenders.
Within the state-affiliated tier, Roscosmos Space Agency and Glavkosmos occupy positions controlling orbital data encryption standards and launch manifest prioritization. Among independent analytics specialists, SCANEX Group exemplifies the ground station network archetype with domestic receiver infrastructure spanning Siberian and Arctic zones. Gazprom Space Systems anchors the captive demand model through energy sector vertical integration. These three represent distinct competitive positioning strategies: regulatory gatekeeping, geographic coverage moats, and sector-specific demand capture.
| Leading Market Players |
|---|
| Roscosmos Space Agency |
| SCANEX Group |
| Gazprom Space Systems |
| Geospatial Agency Innoter |
| East View Geospatial |
| Data East |
| Glavkosmos |
| Racurs |
| NextGIS |
| Others |
Pricing and Supply Chain Analysis
Ground station infrastructure costs cascade through pricing tiers as Roscosmos licensing mandates domestic processing for high-resolution feeds, concentrating capital requirements among Moscow-based operators while compressing margins for regional competitors lacking licensed facilities.
Pricing Analysis
Volume concentrates in standardized observation-tier subscriptions while surveillance-grade tasking retains margin premiums. Three-tier pricing structure across premium, standard, and economy levels separates defense-classified SAR-optical fusion from municipal cadaster indexing and agricultural archive access. Pricing pressure stems from subscription consolidation among Gazprom and Transneft, which negotiate annual capacity reservations rather than transactional per-scene purchases. Municipal governments in Far East districts exhibit highest price sensitivity due to budget constraints, while Ministry of Defense contracts show lowest sensitivity given mission-critical mandates.
Supply Chain Analysis
Geospatial data scientist scarcity in Russian university programs constrains analytics capacity expansion across Novosibirsk and Yekaterinburg processing clusters. Sensor payload manufacturing draws from domestic electronics substitution programs and residual Western component channels through third-country intermediaries. Single-source vulnerability sits with Soyuz and Angara launch manifests, where federal payload prioritization creates deployment queue uncertainty for commercial constellation operators. Distribution runs through SCANEX Group's Siberian ground station network and licensed Moscow facilities before client delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roscosmos encryption mandates and territorial distribution controls erect a cost-of-compliance barrier that protects domestic incumbents with licensed ground infrastructure while excluding foreign operators lacking domestic processing capacity.
For Market Incumbents: Deepen Arctic ground station coverage to capture Northern Fleet radar tasking mandates before competitors replicate Siberian receiver networks. Invest in SAR-optical sensor fusion platforms as defense clients consolidate vendor relationships around unified analytics capabilities. Threat substitution looms from Chinese satellite operators seeking Roscosmos licensing partnerships. For New Entrants and Emerging Players: Enter via Far East agricultural indexing tenders in Amur and Primorsky Krai, where regional governments digitize cadasters without mature local vendor presence. Target municipal urban planning modernization in regional capitals outside Moscow, where limited incumbent competition creates procurement openings. Go-to-market angle: subscription-based capacity reservations with rapid tasking escalation protocols for disaster response. For Investors and Strategic Acquirers: Rosatomflot icebreaker route planning contract awards are the leading indicator that Arctic maritime surveillance mandates are accelerating radar-capable satellite procurement pipelines. Long-term viability favors ground station network operators with territorial distribution licenses over pure-play analytics boutiques lacking infrastructure moats. Acquisition target archetype: specialized SAR processing shops with defense security clearances. Signal to watch: Ministry of Defense resolution threshold updates expanding sub-meter optical contract volumes.| Strategic Initiative | Industry Significance |
|---|---|
| SAR-Optical Sensor Fusion Platform Development | Defense and energy clients consolidate procurement around unified all-weather analytics capabilities. |
| Far East Ground Station Network Expansion | Amur and Primorsky Krai digitization tenders create first-mover advantages in underserved regions. |
| Roscosmos Licensing Compliance Investment | Domestic processing mandates protect market access against foreign operator encroachment. |
| Subscription-Based Capacity Reservation Model | Gazprom and Transneft procurement behavior shifts from transactional to recurring revenue structures. |
| Geospatial Data Scientist Training Partnerships | University pipeline gaps constrain analytics scaling for machine learning feature extraction demand. |
Research Methodology
Roscosmos regulatory filings, Ministry of Defense procurement registers, and energy sector infrastructure monitoring contracts formed the secondary backbone, supplemented by customs data on satellite component imports and ground station licensing records. Primary interviews with ground station operators, defense procurement officers, geospatial analytics directors, and regional government IT heads validated segment assumptions. Bottom-up triangulation across service type, application, and technology dimensions converged with top-down macroeconomic anchoring.
Historical trendline analysis of defense budget allocation patterns and energy sector operational mandates informed projection frameworks across the analysis window. Segmentation modeling incorporated service tier, end-use security classification, platform technology, and regional procurement authority. CAGRs derived from weighted scenario analysis of launch capacity constraints, foreign component substitution timelines, and licensing regime evolution. Industry-specific inputs included Northern Sea Route traffic growth assumptions and pipeline integrity regulation enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Roscosmos licensing threshold adjustments or accelerated foreign electronics substitution programs. Forecasts reflect documented assumptions regarding defense procurement tempo and energy sector capital expenditure continuity. Material deviation in Angara launch manifest prioritization or cross-border data transfer restriction tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
India Satellite Communication Market
Satellite
Satellite Data Analytics Services Market
Satellite
Europe Satellite Connectivity Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
Commercial Satellite Launch Service Market
Satellite
North America Satellite Manufacturing Market
Satellite
Italy Satellite Communication Market
Satellite
South Korea Satellite Communication Market
Satellite
Satellite Broadband Market
Satellite
Global Maritime Satellite Communication Market
Satellite
Military Satellite Market
Satellite
China Satellite Imagery Services Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Communication Satellite Launch Services Market
Satellite
Vehicle Mounted Satellite Communication Station Market