
 Germany Satellite Communications Market | 2026-2036
Germany Satellite Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Satellite Communications Market Insights
CE marking under the EU Radio Equipment Directive is bifurcating the vendor landscape for satellite ground equipment sold in Germany. Airbus Defence and Space GmbH leverages its Ottobrunn manufacturing base to control domestic military payload integration. OHB SE specializes in smallsat platforms and competes for institutional orbit slots. Deutsche Telekom anchors commercial service distribution through its terrestrial backhaul infrastructure.
Satellite communications denotes the transmission of data, voice, and video signals via artificial orbiting relays operating in allocated frequency bands, typically employing parabolic antennas with gain specifications exceeding 30 dBi for ground terminals. The primary purpose spans defense command networks, broadcast content distribution, and broadband backhaul for regions lacking fiber infrastructure. Low Earth Orbit technology captures the fastest expansion as constellation operators reduce latency below 50 milliseconds for consumer broadband. Government end users dominate procurement value through classified military payloads and dual-use infrastructure. Maritime application demand is maturing for merchant fleet connectivity, though agriculture remains nascent for precision farming data relay.
The Bundesnetzagentur enforces frequency coordination under EU spectrum frameworks, while the German Space Agency at DLR governs orbital slot registration and national launch authorizations. These bodies shape market access by requiring domestic encryption standards for government contracts and mandating debris mitigation plans for constellation licensing. Stakeholders must monitor how the EU Space Law initiative redefines liability regimes for satellite operators serving German territory.
Market Dynamics
NATO interoperability mandates are restructuring German defense procurement toward sovereign Low Earth Orbit constellations, redirecting capital from geostationary systems to domestic payload integration capabilities clustered around Ottobrunn and Munich.
Growth Catalysts
- CE marking requirements:The EU Radio Equipment Directive is filtering non-compliant ground equipment vendors from German defense channels. Domestic manufacturers with Ottobrunn testing facilities capture institutional procurement preference.
- Maritime fleet connectivity:Merchant shipping operators are replacing VSAT terminals with flat-panel phased arrays for Ku-band and Ka-band services. Port authorities in Hamburg and Bremerhaven mandate real-time cargo tracking.
- DLR national launch authorizations:The German Space Agency's streamlined debris mitigation licensing is accelerating constellation deployment timelines. Bavarian aerospace clusters secure priority orbital slot registration.
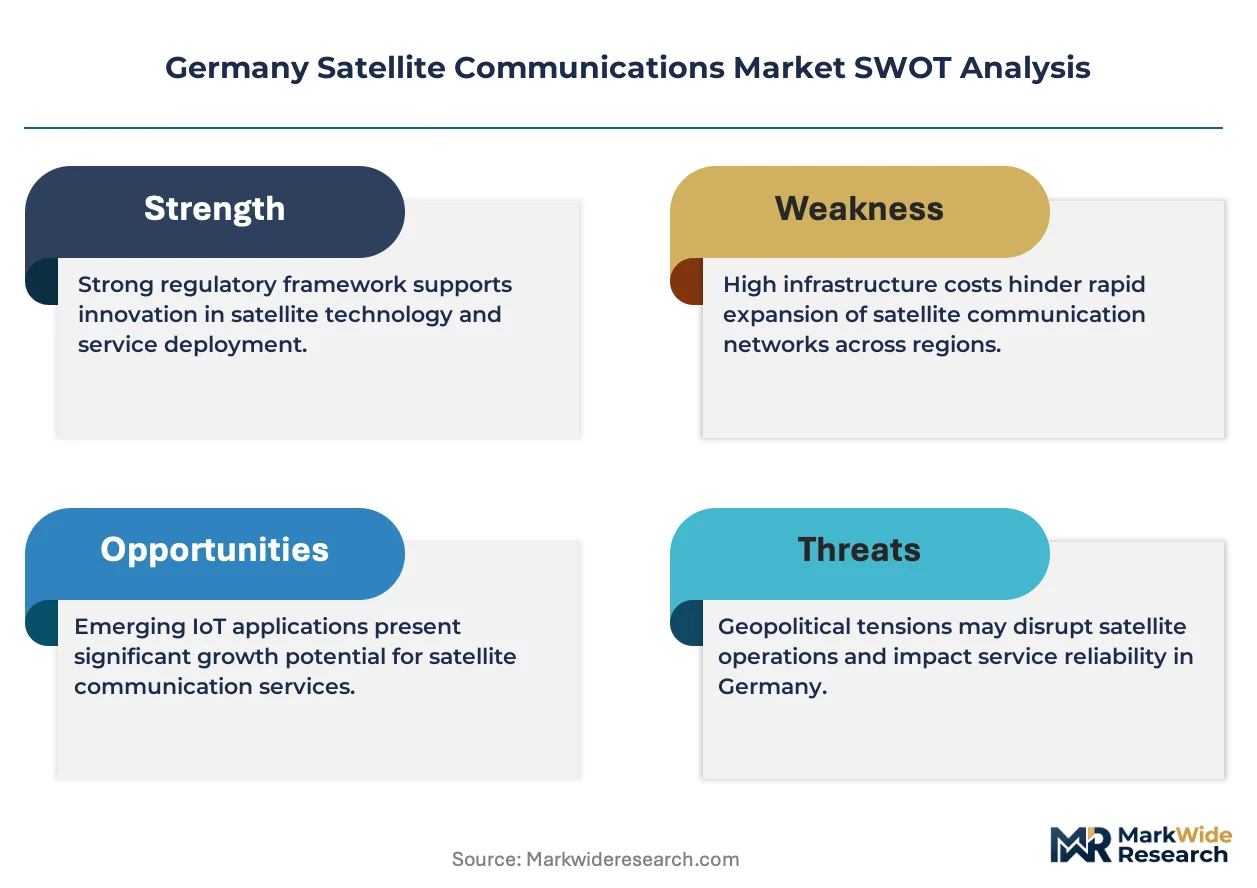
Market Restraints
- Frequency coordination bottlenecks:Bundesnetzagentur spectrum allocation delays extend terminal certification cycles by 8-14 months for Ka-band ground stations.
- Gallium nitride supply concentration:RF power amplifier substrates depend on single-source foundries in Taiwan, exposing Bavarian payload integrators to input cost volatility.
- Optical fiber substitution:Deutsche Telekom's terrestrial 5G backhaul expansion is compressing satellite broadband demand in urban corridors where fiber penetration exceeds 85%.
Strategic Opportunities
- Baden-Württemberg precision agriculture:Underpenetrated farm telemetry in the Rhine Valley creates white space for dual-use Earth observation downlinks. Agricultural cooperatives lack dedicated satellite data contracts.
- EU Space Law liability regimes:Pending orbital debris accountability frameworks will favor German operators with domestic insurance underwriting and captive launch capabilities.
- Quantum key distribution integration:Convergence of photonic satellite links with post-quantum cryptography standards opens classified government channel expansion beyond current AES-256 limitations.
Industry Challenges
- RF systems engineering talent scarcity:Microwave design and antenna modeling expertise concentrates with retiring defense sector veterans in the Munich aerospace corridor.
- ITAR-controlled component licensing:US State Department export restrictions on cryogenic low-noise amplifiers delay German military payload qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Satellite Communications Market |
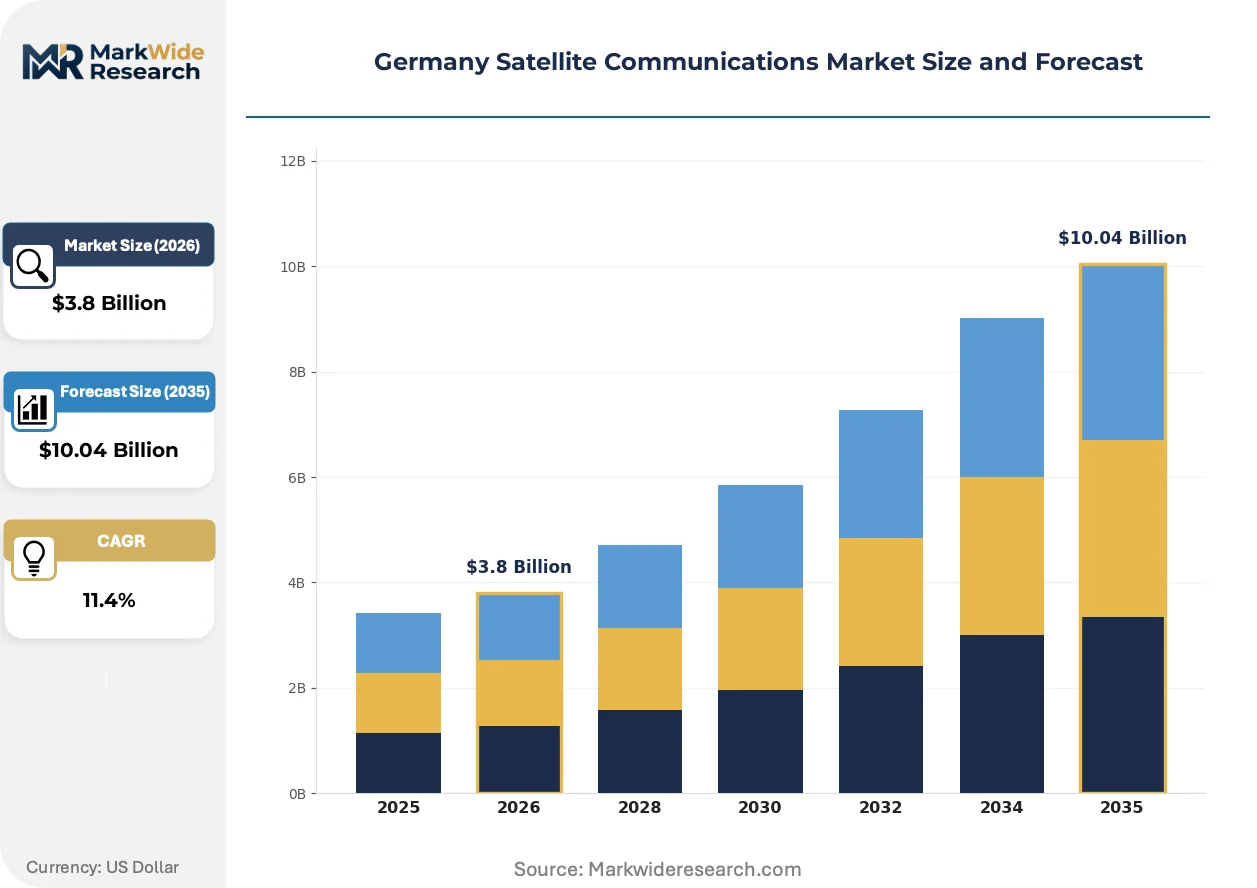
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, Hybrid End User: Government, Military, Telecommunications, Broadcasting Service Type: Internet, Video Distribution, Telemetry, Remote Sensing Application: Maritime, Aeronautical, Disaster Recovery, Agriculture |
| Companies Covered | Viasat Inc., Inmarsat Global Limited, Spaceopal GmbH, Thales Group, Intelsat, Airbus Defence and Space GmbH, Deutsche Telekom, OHB SE, SES S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Satellite Communications Market Trends and Innovations
Flat-panel electronically steered antennas are compressing terminal form factors while software-defined radios enable multi-orbit service handoffs. These shifts are reconfiguring ground equipment supply chains and procurement specifications across defense and commercial segments.
Phased array terminals with no moving parts are displacing parabolic dish architectures in mobile military platforms. The Bundeswehr's SATCOM modernization program is mandating these systems for armored vehicle integration. This displacement is compressing mechanical antenna supplier margins while elevating semiconductor content value in Bavarian manufacturing.
CE marking enforcement under the EU Radio Equipment Directive is bifurcating vendor eligibility for German government contracts. Non-EU manufacturers face extended conformity assessment procedures through notified bodies in Munich. Defense integrators with in-house EMC testing capabilities are internalizing compliance workflows to bypass third-party bottlenecks.
Long-term service contracts with performance-based availability guarantees are replacing equipment-centric procurement in maritime and energy sectors. Ship operators now contract directly with constellation operators, bypassing traditional systems integrators. This pattern is most visible in North Sea offshore wind farm connectivity, where turbine operators demand 99.95% uptime commitments with penalty clauses.
Germany Satellite Communications Market Segmentation
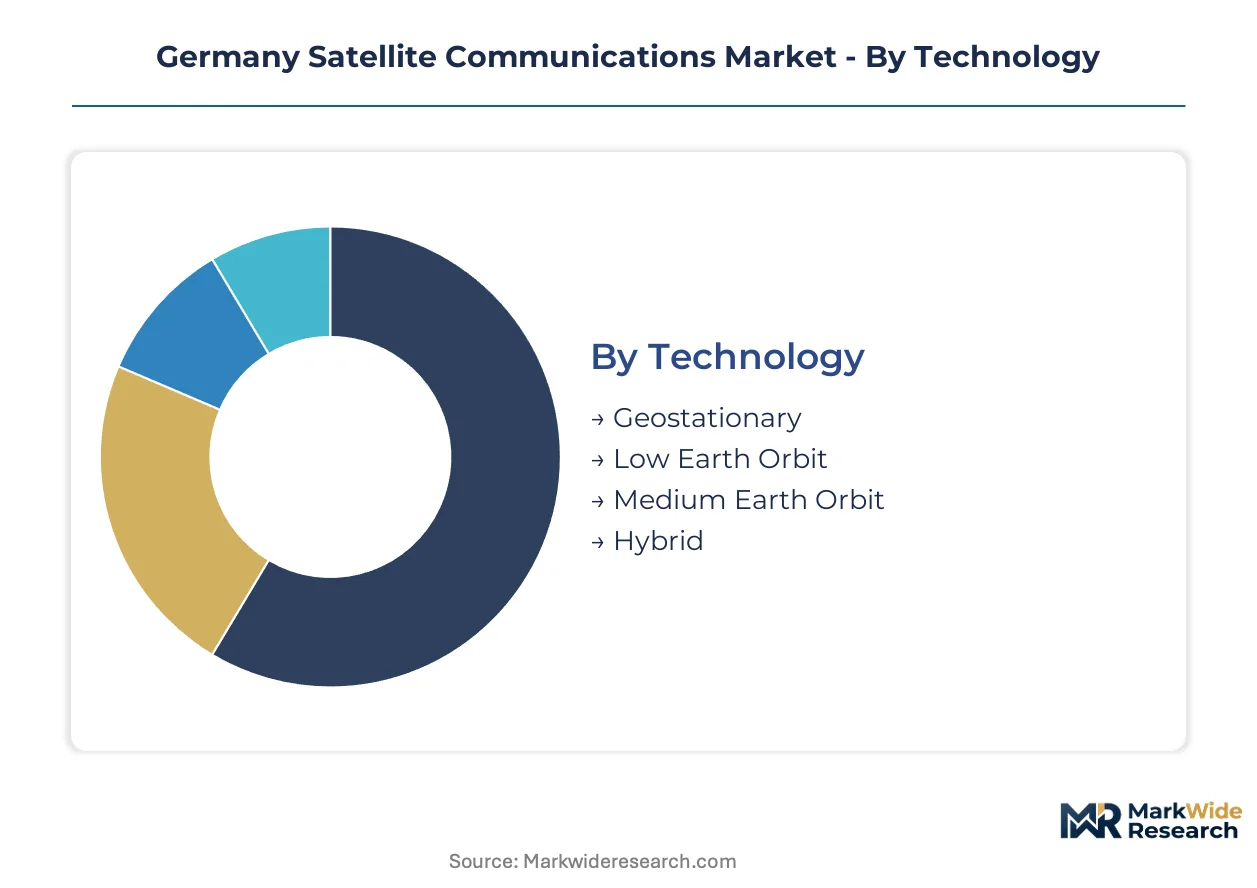
German satellite communications procurement bifurcates between sovereign defense requirements and commercial service distribution. Segmentation reveals how NATO interoperability mandates, DLR orbital licensing, and Bundesnetzagentur spectrum frameworks redirect capital across technology tiers and end-use verticals.
Technology:
Domestic manufacturing concentrates in Bavaria for Low Earth Orbit payloads, while Geostationary systems rely on imported platforms from European primes. Export-led segments serve NATO allied demand through Ottobrunn integration facilities.
- Low Earth Orbit:Constellations operate below 2,000 kilometers altitude with latency specifications under 50 milliseconds. Bavarian aerospace clusters in Ottobrunn and Munich capture institutional procurement preference under DLR national launch authorization frameworks. Government end users dominate through classified military payload demand.
- Geostationary:Fixed orbital positions at 35,786 kilometers enable persistent coverage footprints for broadcast content distribution. Procurement concentrates with Airbus Defence and Space GmbH leveraging domestic payload integration capabilities. CE marking under EU Radio Equipment Directive filters non-compliant ground equipment vendors from defense channels.
- Medium Earth Orbit:Intermediate altitude constellations balance latency against coverage economics for maritime fleet connectivity.
- Hybrid:Multi-orbit service architectures enable seamless handoffs between geostationary and non-geostationary assets.
Geostationary holds the largest share; momentum sits with Low Earth Orbit.
End User:
Cost tier stratification separates classified military procurement from commercial service distribution through Deutsche Telekom terrestrial backhaul infrastructure.
- Government:Federal ministries and civil agencies procure dual-use infrastructure under national space funding frameworks. Demand concentrates in Berlin and Bonn administrative centers with encryption standards mandating domestic payload integration.
- Military:Bundeswehr SATCOM modernization mandates flat-panel phased arrays for armored vehicle integration. NATO interoperability requirements redirect capital from legacy geostationary terminals to sovereign Low Earth Orbit capabilities clustered around Ottobrunn.
- Telecommunications:Deutsche Telekom anchors commercial service distribution through terrestrial 5G backhaul expansion.
- Broadcasting:Content distribution networks rely on geostationary capacity for linear television signal relay.
Military commands the premium tier; government dual-use infrastructure shows steepest expansion trajectory.
Service Type:
Application-driven demand separates consumer broadband from institutional telemetry and Earth observation downlinks.
- Internet:Consumer broadband services compete against Deutsche Telekom fiber penetration exceeding 85% in urban corridors. Flat-panel electronically steered antennas compress terminal form factors for maritime and aeronautical mobility segments.
- Telemetry:Machine-to-machine data relay supports industrial asset tracking and environmental monitoring. Port authorities in Hamburg and Bremerhaven mandate real-time cargo tracking for merchant fleet connectivity.
- Video Distribution:Linear broadcast content delivery relies on geostationary capacity with established downlink infrastructure.
- Remote Sensing:Earth observation downlinks serve agricultural cooperatives in Baden-Württemberg lacking dedicated satellite data contracts.
Internet captures volume leadership; telemetry gains share fastest through industrial IoT deployment.
Application:
Maturity gradients separate established maritime connectivity from nascent precision agriculture segments in the Rhine Valley.
- Maritime:Merchant shipping operators replace VSAT terminals with flat-panel phased arrays for Ku-band and Ka-band services. Hamburg and Bremerhaven port authorities drive regulatory mandates for real-time cargo visibility.
- Disaster Recovery:Emergency communications infrastructure deploys rapidly deployable terminals for network restoration. Civil defense procurement prioritizes interoperability with NATO allied systems.
- Aeronautical:In-flight connectivity demand matures for commercial aviation routes with spectrum coordination through Bundesnetzagentur frameworks.
- Agriculture:Farm telemetry in Baden-Württemberg remains underpenetrated for precision farming data relay through dual-use Earth observation downlinks.
Maritime holds established revenue concentration; disaster recovery infrastructure shows climbing deployment urgency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bundeswehr procurement offices concentrate demand in Berlin and Bonn, while Bavarian aerospace clusters around Ottobrunn and Munich execute payload integration for sovereign constellation programs.
Bavaria
Airbus Defence and Space GmbH dominates military payload manufacturing from its Ottobrunn facility, supplying NATO-interoperable terminals under DLR launch authorization frameworks. The Bundesnetzagentur enforces CE marking for ground equipment through Munich-based notified bodies. Ottobrunn's aerospace corridor aggregates subsystem suppliers for Low Earth Orbit constellation assembly.
North Rhine-Westphalia
Deutsche Telekom anchors commercial service distribution through terrestrial 5G backhaul infrastructure in Cologne and Düsseldorf. The state's dense fiber penetration exceeds 85% in urban corridors, compressing satellite broadband demand. Industrial IoT telemetry for Rhine-Ruhr manufacturing clusters drives residual satellite connectivity procurement.
Baden-Württemberg
Precision agriculture in the Rhine Valley remains underpenetrated for farm telemetry and Earth observation downlinks. Agricultural cooperatives lack dedicated satellite data contracts despite favorable terrain for remote sensing applications. Stuttgart's automotive engineering base generates secondary demand for connected vehicle test fleets.
Hamburg
Port authorities mandate real-time cargo tracking for merchant fleet connectivity through Ku-band and Ka-band services. Maritime terminal procurement concentrates at Hamburg and Bremerhaven, replacing legacy VSAT with flat-panel phased arrays. The city's logistics operators contract directly with constellation operators for 99.95% uptime guarantees.
Berlin-Brandenburg
Federal ministries and civil agencies procure dual-use infrastructure under national space funding frameworks. The German Space Agency at DLR governs orbital slot registration from its Cologne headquarters with administrative coordination in Berlin. Government encryption standards mandate domestic payload integration for classified channels.
Germany Satellite Communications Market Competitive Landscape
Player mix skews toward defense-integrated primes with captive manufacturing capabilities. The vendor base concentrates around Bavarian aerospace clusters where payload integration and ground equipment testing co-locate. Two strategic archetypes dominate: sovereign constellation operators with DLR launch authorizations, and terrestrial telecom incumbents leveraging fiber backhaul for hybrid service distribution. Competitive moves center on vertical integration into RF component manufacturing and strategic partnerships for multi-orbit service architectures.
Among defense-integrated primes, Airbus Defence and Space GmbH and OHB SE exemplify contrasting scale positions within the sovereign payload tier. Airbus Defence and Space GmbH occupies the integrated systems anchor role through its Ottobrunn manufacturing base, while OHB SE represents the specialized smallsat platform segment competing for institutional orbit slots. Thales Group and Viasat Inc. sit within the multinational equipment supplier archetype, serving NATO interoperability requirements without domestic manufacturing concentration.
| Leading Market Players |
|---|
| Viasat Inc. |
| Inmarsat Global Limited |
| Spaceopal GmbH |
| Thales Group |
| Intelsat |
| Airbus Defence and Space GmbH |
| Deutsche Telekom |
| OHB SE |
| SES S.A. |
| Others |
Pricing and Supply Chain Analysis
Long-term service contracts with performance-based availability guarantees lock in supply access for constellation operators while anchoring price visibility through penalty clauses and uptime commitments. This structure concentrates procurement power with maritime and energy sector buyers who demand 99.95% reliability from Bavarian payload integrators.
Pricing Analysis
Cost-plus contracts with gallium nitride substrate indexation dominate military payload procurement, passing through RF power amplifier foundry costs to Bundeswehr programs. Three-tier pricing structure across premium, standard, and economy levels separates NATO-interoperable terminals from commercial maritime equipment and consumer broadband terminals. Cost compression in standard-tier ground equipment is intensifying because CE marking compliance bottlenecks favor domestic Ottobrunn manufacturers with in-house EMC testing. Government end users exhibit lowest price sensitivity due to encryption mandates, while merchant shipping operators negotiate aggressively on flat-panel terminal leases.
Supply Chain Analysis
Strategic stockpiling of gallium nitride substrates and cryogenic low-noise amplifiers prevails over just-in-time preferences given single-source foundry exposure in Taiwan and ITAR-controlled US export licensing delays. Geographic supply concentration centers on Taiwan for RF power amplifier substrates, the United States for cryogenic low-noise amplifiers, and Germany for payload integration and ground equipment assembly. Raw material dependencies span gallium nitride wafers, specialized aluminum alloys for antenna structures, and radiation-hardened semiconductors. Single-source vulnerability in Taiwanese gallium nitride foundries poses structural risk. Distribution runs through Airbus Defence and Space GmbH's Ottobrunn facility for military channels and Deutsche Telekom's terrestrial backhaul for commercial services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retiring microwave design expertise in the Munich aerospace corridor constrains payload qualification timelines, creating a bottleneck that favors incumbents with captive RF engineering talent and disadvantages entrants lacking defense sector heritage.
For Market Incumbents: Consolidate RF systems engineering capabilities through targeted hiring of retiring Bundeswehr veterans and acquisition of specialized antenna modeling boutiques in Bavaria. Deepen backward integration into gallium nitride substrate sourcing to mitigate Taiwan foundry concentration. CE marking enforcement through Munich-based notified bodies creates a defensive moat against non-EU equipment vendors. For New Entrants and Emerging Players: Anchor in Baden-Württemberg precision agriculture, where farm telemetry penetration remains minimal and agricultural cooperatives lack dedicated satellite data contracts. Target Rhine Valley Earth observation downlinks as the most penetrable application segment. Pursue direct partnerships with DLR for streamlined debris mitigation licensing to bypass orbital slot registration queues. For Investors and Strategic Acquirers: Capital is best deployed toward sovereign constellation operators with captive DLR launch authorizations and domestic payload integration capabilities clustered around Ottobrunn. Long-term viability over a multi-year horizon rests on NATO interoperability mandate durability and national space funding framework continuity. Watch for EU Space Law liability regime finalization as the inflection signal for insurance underwriting and debris accountability cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Flat-Panel Phased Array Manufacturing Scale-Up | Captures Bundeswehr armored vehicle integration mandates displacing parabolic dish architectures. |
| Multi-Orbit Service Architecture Partnership | Enables seamless handoffs between geostationary and Low Earth Orbit assets for maritime clients. |
| DLR Debris Mitigation Licensing Investment | Accelerates constellation deployment timelines through priority orbital slot registration. |
| Quantum Key Distribution Integration | Opens classified government channel expansion beyond current AES-256 encryption limitations. |
| Terrestrial 5G Backhaul Hybridization | Leverages Deutsche Telekom infrastructure for commercial service distribution in urban corridors. |
Research Methodology
Operator-level perspectives from constellation program managers, Bundeswehr procurement officers, DLR licensing administrators, and maritime fleet connectivity directors anchored the qualitative base. Primary interviews with payload integration engineers at Ottobrunn facilities and flat-panel antenna procurement leads at Hamburg port authorities combined with secondary validation through Bundesnetzagentur spectrum allocation records, DLR orbital slot registries, and EU Space Law legislative tracking. Bottom-up terminal deployment estimates and top-down national space funding appropriations underwent cross-triangulation.
Sensitivity analysis tested forecast robustness across gallium nitride substrate cost volatility scenarios and ITAR licensing delay assumptions throughout the projection horizon. Segmentation dimensions modeled encompass orbital altitude tier, end-user classification, service type, and application maturity. CAGRs derived from installed base growth trajectories and replacement cycle compression in legacy geostationary terminals. Industry-specific inputs included NATO interoperability mandate implementation pacing and DLR national launch authorization throughput capacity.
Material uncertainties — Bundesnetzagentur spectrum allocation delays, EU Space Law liability regime finalization, and gallium nitride foundry supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding DLR debris mitigation licensing efficiency and NATO interoperability procurement continuity. Revision becomes warranted when ITAR-controlled component export restrictions intensify beyond current State Department baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Bus Market
Satellite
South Korea Satellite Communication Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Nanosatellite Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Satellite Launch Vehicle (SLV) Market
Satellite
Cubesat Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Middle East Satellite Communications Market