
 Asia-Pacific VHF Air-Ground Communication Stations Market | 2026-2036
Asia-Pacific VHF Air-Ground Communication Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific VHF Air-Ground Communication Stations Market Insights
China's civil aviation infrastructure build-out is reconfiguring supplier dynamics across the region. Thales Group leverages its digital air traffic management portfolio to anchor contracts with expanding airport authorities. Chengdu Spaceon Electronics Co. Ltd. competes on domestic manufacturing scale, while Rohde & Schwarz sustains technology leadership in software-defined radio architectures for ground-based installations.
VHF air-ground communication stations transmit voice and data between aircraft and ground facilities in the 118-136 MHz aeronautical band, with ground-based transceivers typically delivering 25-50 watts output power to ensure reliable line-of-sight coverage across terminal and en-route airspace. Fixed stations dominate installed base value due to permanent air traffic control infrastructure, while software-defined radio represents the fastest-growing technology segment as militaries and civil operators seek waveform agility without hardware replacement. Digital technology segments command margin concentration because certification complexity and interoperability standards limit vendor participation.
China's MIIT enforces GB standards for radio equipment type approval, while India's WPC coordinates with DGCA on aeronautical spectrum assignments; Australia's ACMA maintains separate VHF channel plans that fragment procurement specifications. Japan's MIC and South Korea's MSIT are converging toward ICAO-compliant digital standards, tightening compliance costs for non-specialized suppliers. Stakeholders must monitor spectrum harmonization negotiations between national regulators and ICAO working groups to anticipate equipment refresh cycles and certification pathway changes.
Market Dynamics
China's MIIT spectrum reallocation is compressing equipment refresh cycles across the Asia-Pacific, forcing manufacturers to accelerate digital certification timelines while militaries in Southeast Asia expand procurement of software-defined ground stations.
Growth Catalysts
- Digital waveform migration:Military operators across Southeast Asia are replacing analog VHF infrastructure with software-defined radio architectures that enable multi-band interoperability without hardware swaps.
- Coastal corridor expansion:India's DGCA is mandating redundant ground station coverage along high-density aviation routes connecting Mumbai, Chennai, and Port Blair.
- GB standard harmonization:China's MIIT is consolidating type-approval pathways for aeronautical VHF equipment, reducing certification friction for domestic suppliers.
Market Restraints
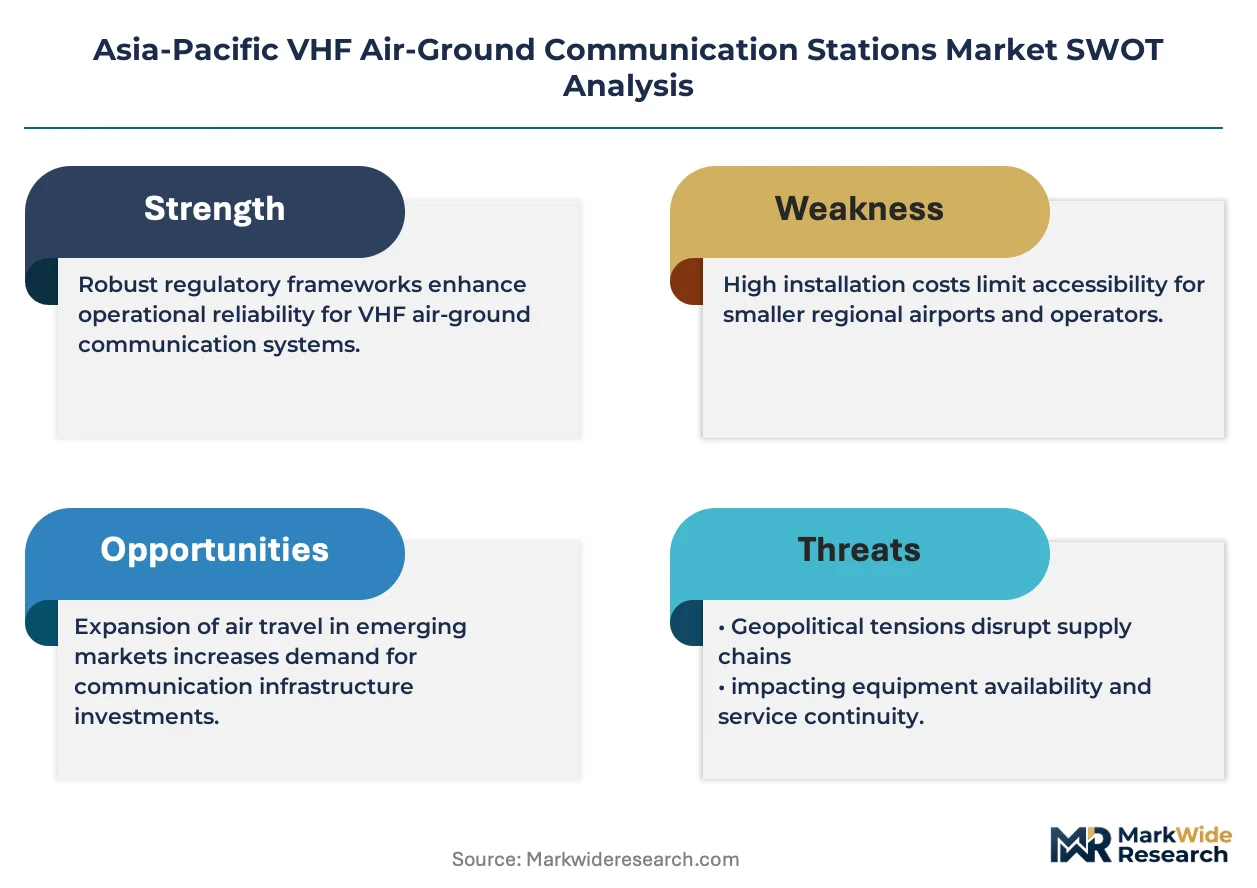
- GaN component supply concentration:Gallium nitride power amplifiers for high-output transceivers depend on concentrated substrate fabrication in East Asian foundries.
- Interoperability certification costs:Australia's ACMA maintains non-harmonized channel plans that fragment procurement specifications and duplicate testing burdens.
- Satellite-based CPDLC substitution:Controller-pilot data link communications via Inmarsat and Iridium networks are displacing voice-dependent VHF for oceanic routes.
Strategic Opportunities
- Island-hopping route infrastructure:Indonesia's archipelagic aviation network requires portable and deployable VHF stations for remote airstrip connectivity.
- Dual-use civil-military platforms:South Korea's MSIT is incentivizing waveform-agile transceivers that serve both air traffic control and defense coordination functions.
- Remote monitoring integration:Ground station operators are converging VHF maintenance with IP-based telemetry networks to enable predictive fault detection.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in high-frequency analog design and EMC compliance is concentrating among aging workforces in Japan and Australia.
- Legacy system integration friction:India's AAI operates mixed-vintage VHF infrastructure that complicates digital overlay deployments without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific VHF Air-Ground Communication Stations Market |
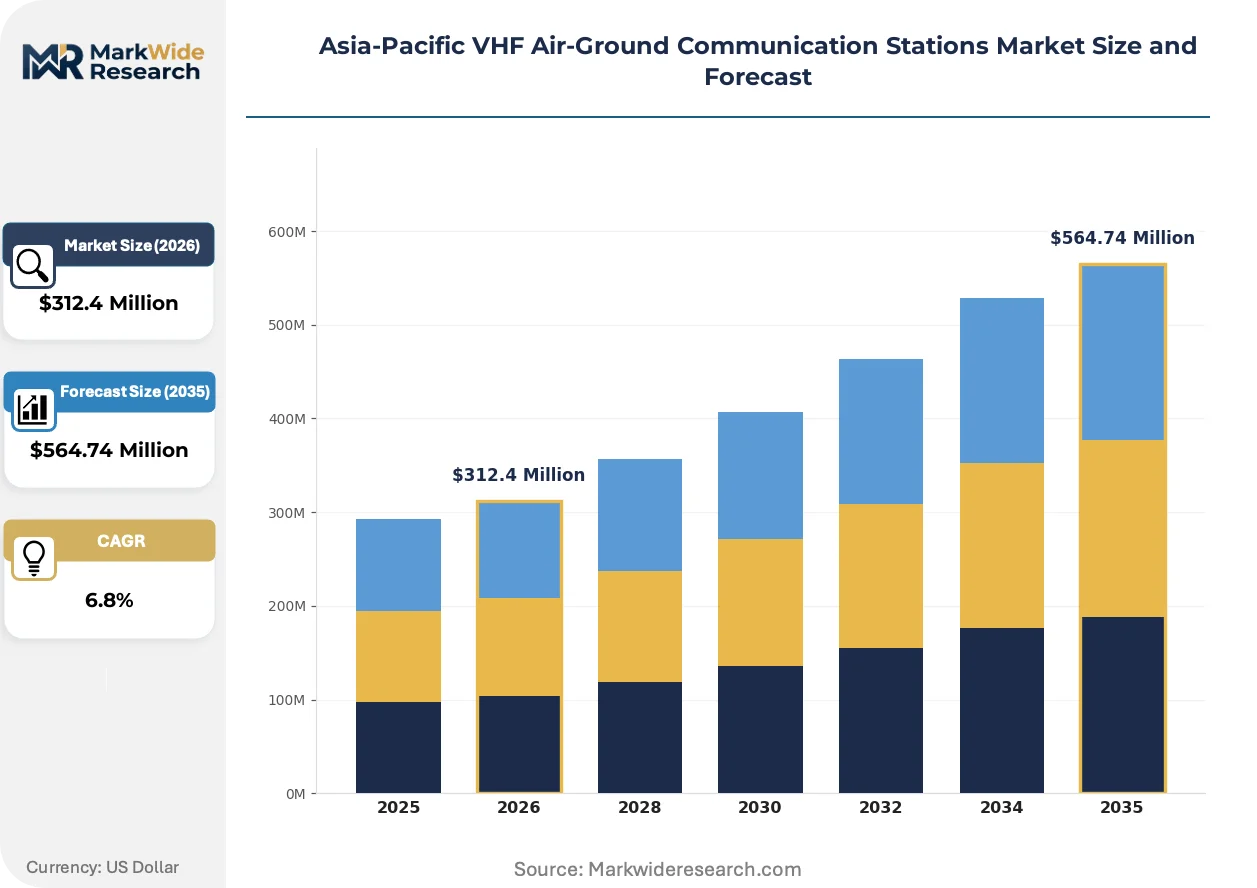
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Stations, Mobile Stations, Portable Stations, Base Stations End User: Civil Aviation, Military Operations, Emergency Services, Air Traffic Control Technology: Analog Technology, Digital Technology, Hybrid Technology, Software-Defined Radio Installation: Onshore, Offshore, Ground-Based, Transportable |
| Companies Covered | Thales Group, Honeywell International Inc, Collins Aerospace, Chengdu Spaceon Electronics Co. Ltd., Jotron Asia Pte Ltd, Rohde & Schwarz, Leonardo S.p.A., Raytheon Technologies Corporation, AEROTHAI Business, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific VHF Air-Ground Communication Stations Market Trends and Innovations
Software-defined architectures are displacing hardware-fixed transceivers across both civil and military procurement channels, compressing equipment lifecycles and reshaping supplier value capture toward firmware and integration services.
Software-defined radio is virtualizing baseband processing functions that previously required dedicated analog circuitry. Military procurement offices in Thailand and Vietnam are specifying SDR platforms for 70% of new ground station awards. This shift is virtualizing supplier margins away from hardware bill-of-materials toward perpetual licensing and waveform update subscriptions.
Japan's MIC is converging national VHF channel plans toward ICAO-compliant digital standards by 2027. The policy compresses equipment refresh timelines for domestic airports and eliminates grandfathering provisions for analog-only installations. Domestic system integrators are responding by pre-certifying dual-mode analog-digital transceivers to capture accelerated replacement demand.
Airport authorities are unbundling maintenance contracts from initial equipment procurement, creating standalone service revenue pools. Ground station OEMs in China and South Korea are establishing captive technical service subsidiaries to capture recurring aftermarket value. This restructuring is most visible in India's greenfield airport developments where 15-year service agreements are now standard tender requirements.
Asia-Pacific VHF Air-Ground Communication Stations Market Segmentation
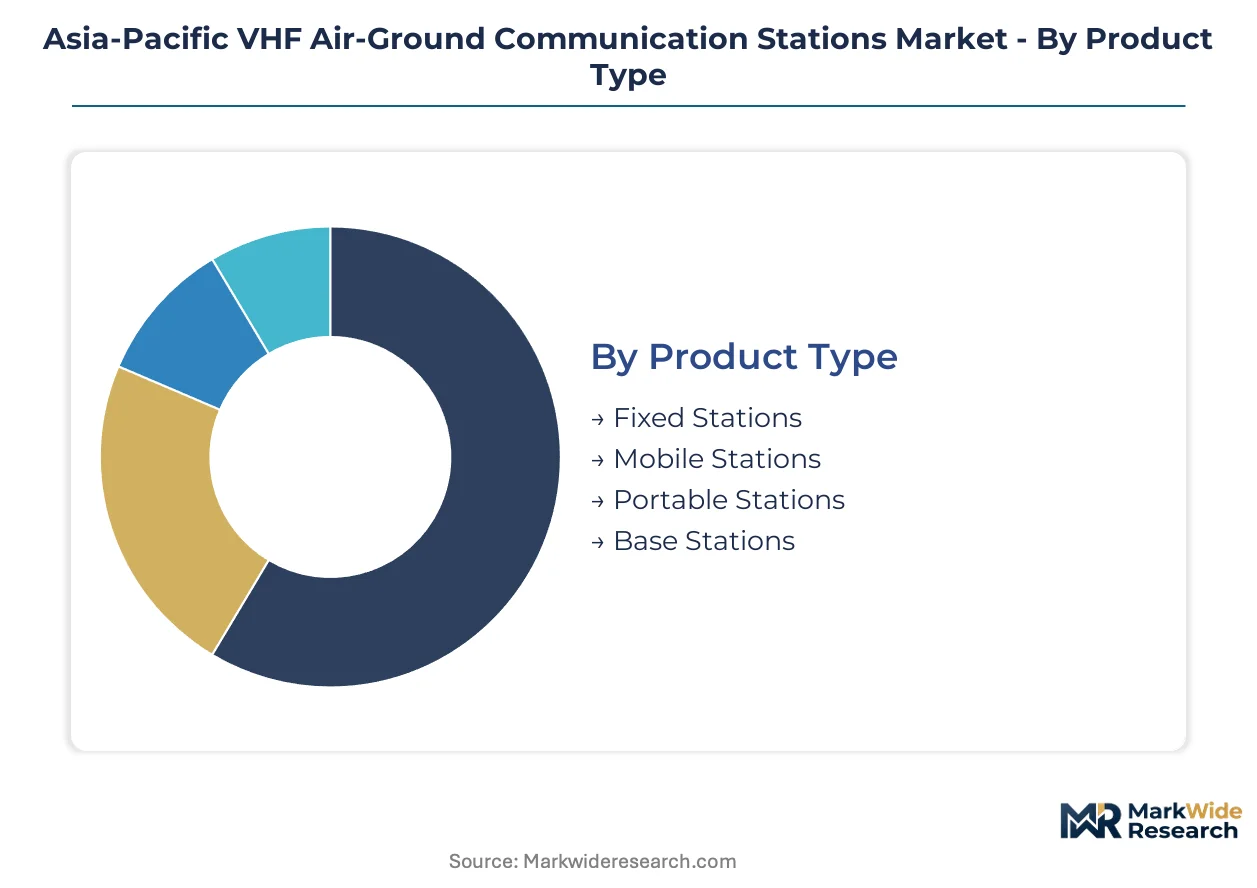
VHF air-ground communication stations fragment across four critical dimensions that determine procurement specifications, certification pathways, and aftermarket service intensity. Product type dictates infrastructure permanence and maintenance scheduling. Technology selection governs interoperability mandates and upgrade cadence. End-user requirements diverge sharply between civil regulatory compliance and military waveform agility. Installation environment shapes environmental hardening and deployment logistics.
Product Type:
After-sales service intensity varies dramatically across station mobility classes, with fixed installations demanding sustained technical support contracts and portable units requiring rapid field repair networks.
- Fixed Stations:Permanent ground installations anchor terminal and en-route air traffic control infrastructure with 25-50 watt output power configurations. India's AAI and China's civil aviation authorities concentrate procurement along high-density coastal corridors where redundant coverage mandates double-station deployment at critical nodes.
- Mobile Stations:Vehicle-mounted transceivers serve temporary airfield activation and emergency response scenarios with rapid redeployment capability. Southeast Asian militaries in Thailand and Vietnam are expanding procurement for expeditionary airbase operations where infrastructure permanence is impractical.
- Portable Stations:Man-portable units deliver emergency VHF coverage for remote airstrip activation.
- Base Stations:Centralized hub configurations coordinate multiple remote transceiver sites through IP backhaul integration.
Fixed stations hold the largest share; momentum sits with mobile stations.
End User:
Customer procurement authority fragments across regulatory bodies with divergent certification timelines and budget cycles, stretching sales engagement horizons.
- Civil Aviation:Commercial airline operators and airport authorities procure ICAO-compliant equipment subject to national regulator type-approval. China's MIIT GB standard harmonization is compressing certification friction for domestic suppliers serving expanding airport infrastructure.
- Military Operations:Defense procurement offices prioritize software-defined architectures enabling multi-band interoperability without hardware replacement. Southeast Asian militaries specify SDR platforms for the majority of new ground station awards, virtualizing supplier margins toward firmware licensing.
- Emergency Services:Search and rescue coordination centers require deployable VHF coverage for disaster response scenarios.
- Air Traffic Control:ANSPs operate under sovereign regulatory mandates with equipment refresh cycles tied to spectrum reallocation policies.
Civil aviation commands the installed base; military operations are expanding most quickly.
Technology:
Component cost structures diverge sharply between analog legacy systems with mature supply chains and digital architectures requiring specialized FPGA and software engineering.
- Analog Technology:Legacy amplitude modulation transceivers dominate India's mixed-vintage AAI infrastructure where digital overlay deployment faces service continuity constraints. Japan's MIC elimination of grandfathering provisions is accelerating replacement timelines.
- Digital Technology:Fully digital baseband processing enables advanced modulation schemes and error correction. Certification complexity and interoperability standards limit vendor participation, concentrating margin capture among specialized suppliers.
- Hybrid Technology:Dual-mode analog-digital transceivers bridge migration timelines for regulators phasing out legacy compatibility.
- Software-Defined Radio:Virtualized waveform processing eliminates hardware swaps for protocol updates, compressing equipment lifecycles while extending revenue through subscription models.
Analog technology retains substantial installed base; software-defined radio shows the steepest expansion trajectory.
Installation:
Environmental exposure severity drives differentiation in enclosure sealing, thermal management, and corrosion protection specifications.
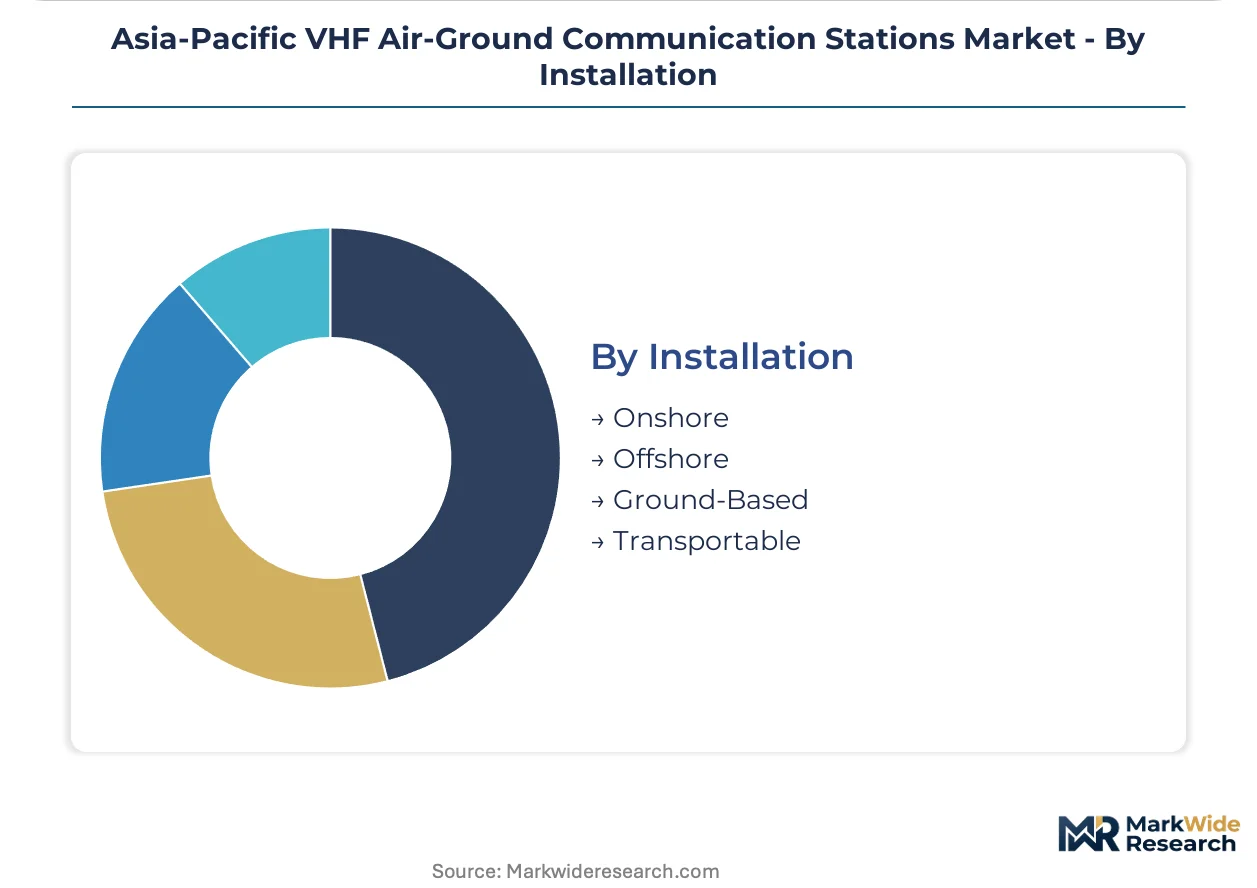
- Onshore:Standard ground installations at established airports with controlled climate exposure.
- Offshore:Maritime platforms and island facilities require salt-spray hardened enclosures and redundant power systems. Indonesia's archipelagic network concentrates demand for corrosion-resistant transceivers.
- Ground-Based:Permanent terrestrial infrastructure with tower-mounted antennas for line-of-sight optimization.
- Transportable:Rapidly deployable configurations for temporary operations and disaster recovery where infrastructure pre-positioning is impossible.
Ground-based installations dominate procurement volume; transportable configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication for high-frequency transceivers clusters in East Asian foundries, while system integration and certification expertise concentrates among established defense-electronics hubs across the region. Procurement authority fragments across national regulators with divergent spectrum policies and equipment standards.
China
Domestic airport expansion and military modernization are accelerating procurement of digital ground stations. MIIT spectrum reallocation is tightening GB standard certification requirements for aeronautical VHF equipment. Chengdu and Xi'an host concentrated defense-electronics manufacturing where state-affiliated integrators anchor supply relationships.
India
Coastal aviation corridors connecting Mumbai, Chennai, and Port Blair are mandating redundant ground station coverage. DGCA coordinates with WPC on aeronautical spectrum assignments that complicate equipment import timelines. Bengaluru and Hyderabad clusters concentrate system integration capability for civil and dual-use applications.
Japan
Domestic airport infrastructure refresh is compressing equipment replacement timelines toward 2027. MIC convergence toward ICAO-compliant digital standards is eliminating grandfathering provisions for analog installations. Nagoya and Tokyo metropolitan areas host specialized RF engineering firms with aging technical workforces.
South Korea
MSIT incentives for waveform-agile transceivers are bridging civil air traffic control and defense coordination requirements. Dual-use procurement specifications favor domestic system integrators with established military relationships. Seoul Capital Area concentrates both certification authority and technical service networks.
Australia
Remote airfield connectivity and offshore maritime platform requirements sustain demand for transportable VHF configurations. ACMA maintains non-harmonized channel plans that fragment procurement specifications from regional standards. Perth and Darwin serve as logistics hubs for archipelagic and offshore deployment networks.
Asia-Pacific VHF Air-Ground Communication Stations Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying GaN amplifiers and FPGA modules to multiple downstream vendors. Market structure tilts toward consolidated system integration where certification barriers limit new entry, while upstream component supply concentrates among specialized RF foundries. Three archetypes dominate: defense-heritage conglomerates with captive air traffic management portfolios, domestic champions leveraging local certification relationships, and European specialists exporting software-defined architectures. Competitive maneuvering centers on waveform licensing arrangements and captive technical service subsidiaries to capture aftermarket value.
Among defense-heritage conglomerates, Thales Group and Raytheon Technologies Corporation exemplify platform integrators with established ANSP relationships across multiple Asia-Pacific jurisdictions. Rohde & Schwarz occupies a position as the European specialist archetype, representing technology leadership in software-defined radio architectures without domestic manufacturing presence in the region. These three anchors illustrate how certification complexity and sovereign procurement preferences fragment competitive positioning across national markets.
| Leading Market Players |
|---|
| Thales Group |
| Honeywell International Inc |
| Collins Aerospace |
| Chengdu Spaceon Electronics Co. Ltd. |
| Jotron Asia Pte Ltd |
| Rohde & Schwarz |
| Leonardo S.p.A. |
| Raytheon Technologies Corporation |
| AEROTHAI Business |
| Others |
Pricing and Supply Chain Analysis
GaN substrate fabrication concentration in East Asian foundries creates single-source vulnerability that compresses margin spreads between premium certified and standard-grade VHF transceivers while forcing buyers toward long-term offtake contracts with captive suppliers.
Pricing Analysis
China's MIIT GB standard harmonization dictates the pricing tier structure across the Asia-Pacific, separating ICAO-compliant digital installations from legacy analog configurations. Three-tier pricing stratifies across certified-digital, hybrid-transition, and economy-analog levels, with certification complexity and waveform agility as primary differentiation drivers. Cost compression in the economy tier is intensifying because India's AAI procurement mandates favor lowest-compliant-bid awards. Military procurement offices show least price sensitivity due to mission-critical interoperability requirements.
Supply Chain Analysis
Gallium nitride wafers and high-frequency FPGA modules feed from concentrated fabrication clusters in Taiwan, South Korea, and Japan. Raw material dependencies span GaN substrates, RF power transistors, and precision filter components. Single-source vulnerability concentrates in GaN epitaxy capacity held by two dominant foundry operators. Distribution runs through defense-electronics system integrators with established certification relationships rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific VHF air-ground communication stations market sits at an early-cycle expansion phase where software-defined radio adoption is accelerating replacement timelines beyond historical equipment lifecycles.
For Market Incumbents: Entrench certification authority by pre-positioning dual-mode analog-digital transceivers ahead of Japan's MIC grandfathering elimination and Australia's ACMA harmonization shifts. Deepen backward integration into GaN amplifier supply through captive foundry relationships or long-term substrate offtakes, neutralizing single-source chokepoint exposure that threatens margin stability. For New Entrants and Emerging Players: Build out portable and transportable station capabilities targeting Indonesia's archipelagic aviation network and India's island-hopping coastal corridors where infrastructure permanence constraints exclude fixed-station incumbents. Partner with domestic system integrators in South Korea and Vietnam to bypass sovereign procurement preference barriers. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors software-defined radio specialists with waveform licensing revenue models over hardware-centric legacy suppliers. Five-to-ten-year viability hinges on recurring firmware subscription capture rather than transactional equipment sales. Monitor Japan's MIC 2027 digital convergence deadline as the critical inflection signal for accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Migration | Virtualizes supplier margins toward perpetual waveform licensing and compresses hardware refresh cycles. |
| GaN Supply Chain Captive Integration | Secures substrate access against East Asian foundry concentration and stabilizes transceiver cost structures. |
| Dual-Use Civil-Military Certification | Captures South Korea MSIT incentives bridging air traffic control and defense coordination procurement. |
| Remote Monitoring Service Unbundling | Creates standalone 15-year technical service revenue pools at India's greenfield airport developments. |
| Indonesian Archipelagic Deployment Network | Establishes rapid field repair infrastructure for portable station demand across remote airstrip connectivity. |
Research Methodology
Desk research of ICAO regulatory filings, national spectrum assignment databases, and defense procurement disclosures preceded structured interviews with air navigation service procurement directors, military communications engineering leads, RF component supplier technical directors, and airport authority infrastructure planners. Secondary validation drew from MIIT type-approval registries, DGCA tender documentation, ACMA spectrum plans, and customs trade flow records. Bottom-up equipment shipment analysis triangulated against top-down national aviation infrastructure budget allocations.
Forecast assumptions held China's MIIT spectrum reallocation timeline and Japan's MIC digital convergence policy as fixed boundary conditions while varying software-defined radio penetration rates and GaN supply availability scenarios. Segmentation modeling spanned product mobility class, technology architecture, end-user procurement authority, and installation environment hardness. CAGRs derived from equipment refresh cycle compression analysis and military procurement acceleration patterns across Southeast Asian defense modernization programs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by GaN substrate suppliers or accelerated SDR adoption by Southeast Asian militaries would shift outcomes beyond modeled ranges. Cross-checking against ICAO Asia-Pacific regional office infrastructure deployment tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Aviation Weather Radar Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Military Navigation Systems Market
Aircraft Navigation and Communication
Digital Radiosonde Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Air Traffic Control Market
Aircraft Navigation and Communication
GPS and GNSS Receivers in Aviation Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Electronic Navigational Charts (ENC) Market
Aircraft Navigation and Communication
Defense Advanced GPS Receiver (DAGR) Market
Aircraft Navigation and Communication
Europe Air Traffic Management Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market