
 Satellite Based Augmentation Systems (SBAS) Market | 2026-2036
Satellite Based Augmentation Systems (SBAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Based Augmentation Systems (SBAS) Market Analysis
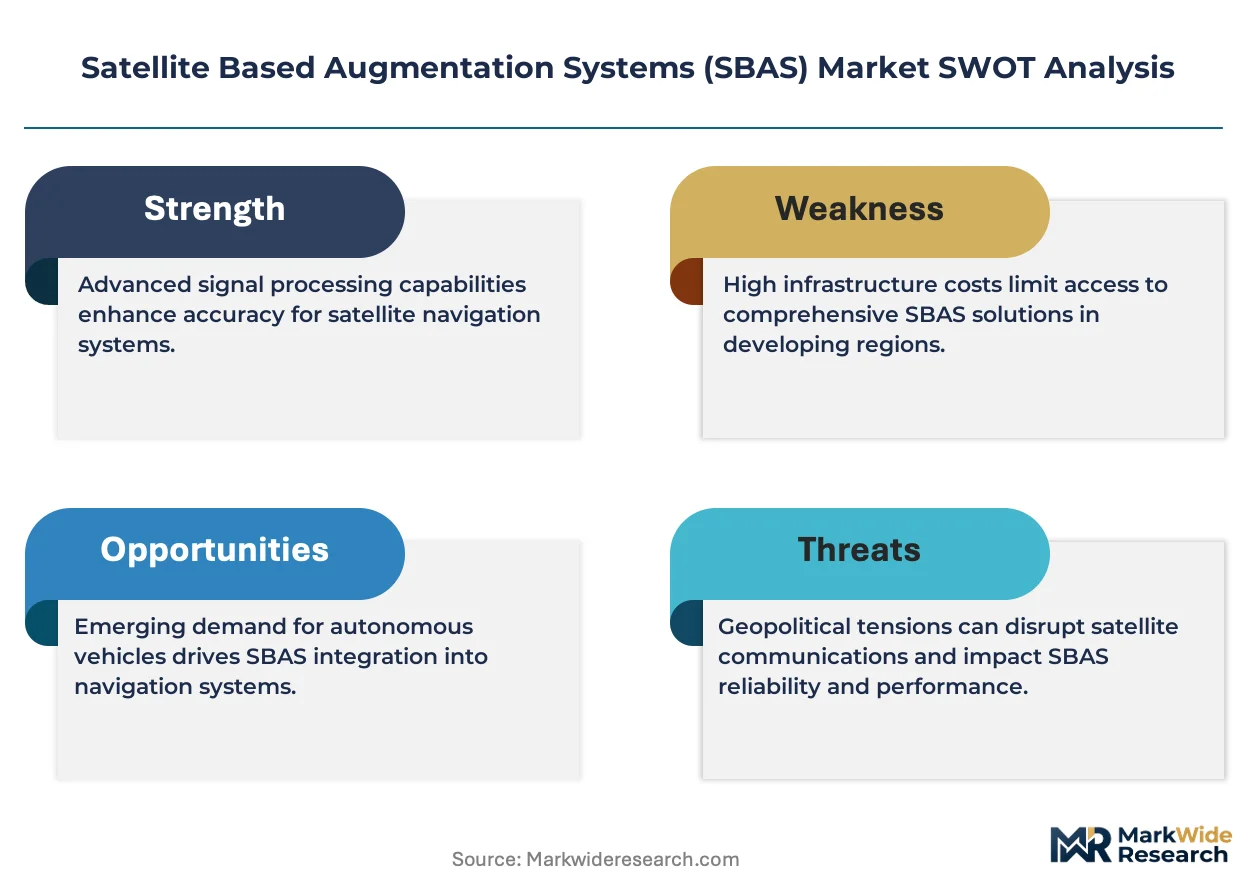
Modular ground-station deployment is broadening buyer choice across the SBAS value chain. Thales Group leverages its geostationary payload expertise to anchor European coverage expansion. Raytheon Technologies Corporation sustains its position through R&D intensity in signal-correction algorithms. Honeywell International Inc. dominates avionics integration, controlling the terminal-equipment channel into commercial airlines.
Satellite Based Augmentation Systems constitute differential-GNSS networks that broadcast real-time integrity and correction data via geostationary satellites, achieving sub-meter horizontal accuracy for safety-critical applications. The architecture comprises reference stations, master control centers, and uplink facilities that generate and disseminate augmentation messages to user receivers. Space-Based Augmentation currently leads installed value, though Hybrid Systems represent the fastest-expanding configuration as operators merge terrestrial and orbital assets for redundancy. GPS technology retains the largest receiver base, while Galileo-compatible terminals capture margin pools in European-regulated aviation and marine segments.
The Federal Aviation Administration's WAAS program shapes North American product standards, requiring dual-frequency avionics for LPV approach minima. EASA mandates EGNOS adoption for precision approaches under EU airspace regulations, while ICAO standards govern cross-border interoperability. China's BeiDou SBAS deployment by the national satellite navigation office introduces a parallel certification track for Asian operators. Stakeholders must monitor spectrum allocation decisions and multi-constellation receiver mandates as regulatory fragmentation creates distinct compliance zones.
Market Dynamics
Aviation authorities are mandating SBAS-enabled precision approaches as the primary structural force reshaping deployment schedules, with Australia's Civil Aviation Safety Authority and the European Union Aviation Safety Agency driving retrofit cycles across commercial fleets.
Growth Catalysts
- LPV Approach Mandates:The FAA's WAAS program requires dual-frequency avionics for lower landing minima, forcing fleet upgrades across US-registered carriers operating into regional airports.
- Maritime Corridor Digitization:Port authorities in Singapore and Rotterdam are integrating SBAS-derived positioning into automated vessel traffic management systems for container terminal approach lanes.
- Galileo EGNOS Certification:EASA's Safety-of-Life standards for precision approaches are accelerating ground infrastructure deployments across EU member states' aviation networks.
Market Restraints
- Geostationary Slot Scarcity:Orbital positioning for SBAS payloads concentrates among established satellite operators, limiting new entrants' coverage expansion options.
- Dual-Frequency Receiver Cost:Aviation-grade multi-constellation terminals require expensive RF front-end components, compressing adoption in general aviation segments.
- Spectrum Coordination Friction:L-band allocation disputes between aeronautical and mobile satellite services create regulatory uncertainty for augmentation signal planning.
Strategic Opportunities
- Drone Integration Pathways:Uncrewed aerial system corridors in Germany and France are piloting SBAS for beyond-visual-line-of-sight operations, opening non-aviation demand pools.
- Hybrid System Architectures:Operators merging terrestrial reference networks with orbital assets are capturing redundancy premiums from safety-critical marine and rail applications.
- BeiDou SBAS Parallel Certification:China's national satellite navigation office is establishing alternative compliance tracks for Asian operators seeking multi-constellation resilience.
Industry Challenges
- GNSS Signal Engineer Scarcity:Specialized expertise in ionospheric modeling and integrity monitoring algorithms remains concentrated among legacy system architects, constraining vendor scaling.
- Multi-Constellation Certification Timelines:Receiver approvals spanning GPS, Galileo, and BeiDou simultaneously extend type certification cycles for avionics manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Based Augmentation Systems (SBAS) Market |
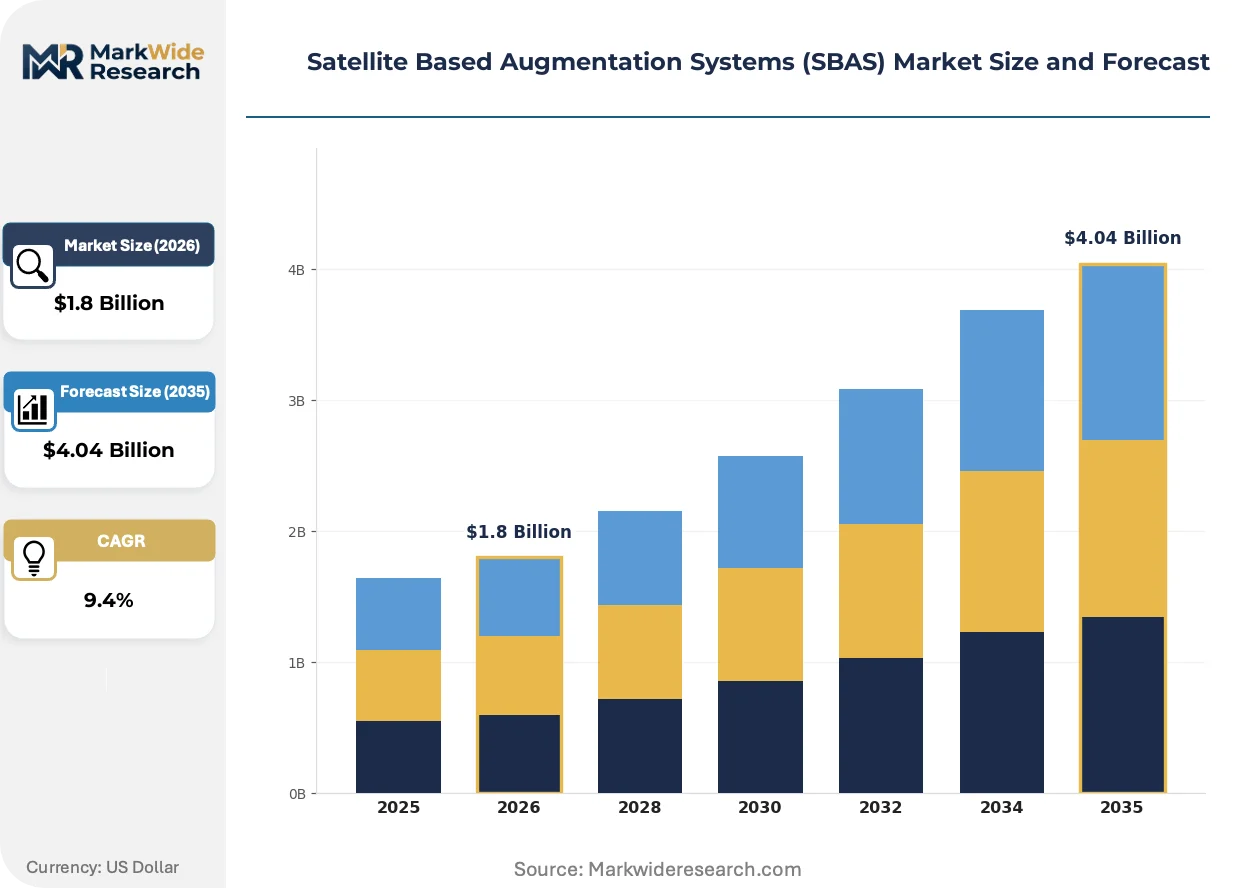
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-Based Augmentation, Space-Based Augmentation, Hybrid Systems, Integrity Monitoring Technology: GPS, GLONASS, Galileo, BeiDou End User: Aerospace, Agriculture, Transportation, Marine Application: Surveying, Navigation, Precision Farming, Disaster Management |
| Companies Covered | Raytheon Technologies Corporation, Honeywell International Inc., Thales Group, Lockheed Martin Corporation, Northrop Grumman Corporation, Airbus SE, Boeing, Garmin Ltd., Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Based Augmentation Systems (SBAS) Market Emerging Trajectories
Dual-frequency multi-constellation receivers are displacing legacy single-system terminals as the dominant avionics configuration, compressing equipment refresh cycles and reshaping supplier competitive positions across aviation and marine segments.
Multi-frequency signal processing is consolidating receiver architectures by enabling simultaneous GPS L1/L5 and Galileo E1/E5a tracking in single-chipsets. Regional airlines in Australia and Brazil are adopting these terminals ahead of regulatory deadlines to standardize fleet configurations. This consolidation is compressing the addressable market for single-frequency legacy equipment and forcing component suppliers to retool fabrication lines.
The EU's F-Gas Regulation is restricting fluorinated greenhouse gas use in ground station cooling systems, compelling master control center operators to adopt closed-loop thermal management or natural refrigerant alternatives. European SBAS infrastructure providers face retrofit investments or operational penalties for non-compliance. Ground facility upgrades in France and Germany are prioritizing ammonia-based cooling to meet phase-down schedules.
Airlines are unbundling SBAS capability from bundled avionics service contracts, shifting toward line-replaceable-unit procurement with separate integrity monitoring subscriptions. Low-cost carriers in Southeast Asia are driving this fragmentation to match equipment life cycles with lease terms. This pattern is most visible in Indonesia and Vietnam, where rapid fleet expansion favors modular upgrade paths over integrated system purchases.
Satellite Based Augmentation Systems (SBAS) Market Segmentation
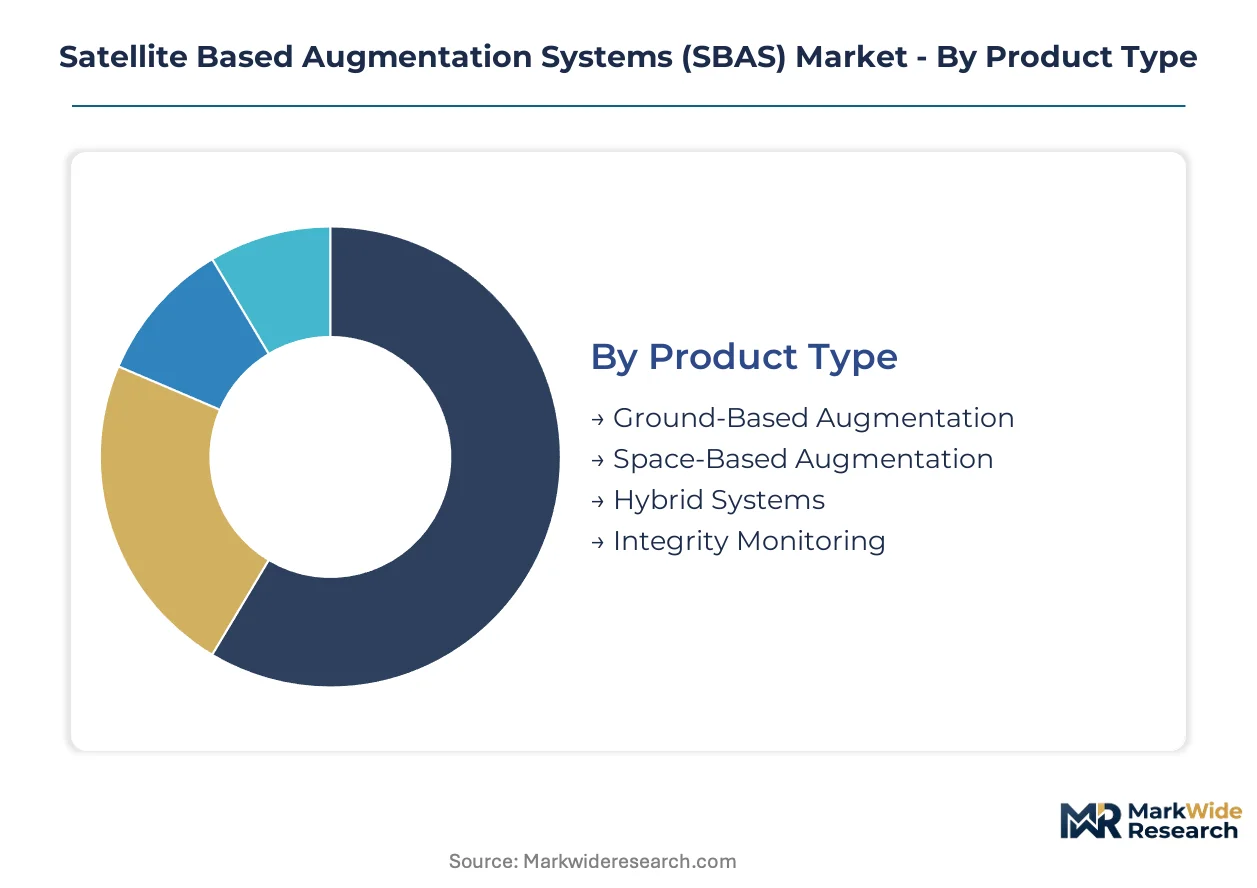
SBAS procurement patterns diverge sharply across operational domains, with aviation authorities driving certification requirements that cascade through equipment specifications. Buyers segment their investments by redundancy needs, constellation compatibility, and approach-minima targets rather than hardware cost alone.
Product Type:
Redundancy mandates and coverage gaps determine whether operators invest in orbital assets, terrestrial networks, or fused architectures.
- Space-Based Augmentation:Geostationary satellites broadcast integrity and correction data over continental footprints. Australia's Civil Aviation Safety Authority mandates this configuration for precision approaches across the Sydney-Melbourne corridor, forcing fleet-wide retrofits.
- Hybrid Systems:Merged terrestrial reference networks with orbital assets deliver redundancy premiums for safety-critical applications. Port authorities in Singapore and Rotterdam specify these architectures for automated vessel traffic management in container terminal approach lanes.
- Ground-Based Augmentation:Local-area differential corrections serve airport precision-landing zones without satellite dependency. Regional airports in Brazil deploy these where geostationary coverage remains sparse.
- Integrity Monitoring:Real-time fault detection and exclusion algorithms validate signal trustworthiness for Safety-of-Life operations. EASA certification requirements accelerate ground infrastructure upgrades across EU member states.
Volume sits with Space-Based Augmentation; growth tilts toward Hybrid Systems.
Technology:
Receiver chipset architecture and regulatory certification timelines shape constellation selection for fleet operators.
- GPS:The established L1/L5 signal structure anchors WAAS compliance for FAA-mandated LPV approaches. US-registered carriers operating into regional airports face forced upgrades as dual-frequency avionics become mandatory.
- Galileo:E1/E5a compatibility captures margin pools in European-regulated aviation and marine segments. EASA's Safety-of-Life standards require EGNOS-certified terminals for precision approaches under EU airspace regulations.
- BeiDou:China's national satellite navigation office establishes parallel certification tracks for Asian operators seeking multi-constellation resilience.
- GLONASS:Russian constellation signals provide backup coverage in high-latitude operations where GPS geometry degrades.
Installed base concentrates with GPS; certification velocity favors Galileo.
End User:
Safety-critical mandates and automation roadmaps determine segment investment intensity.
- Aerospace:Commercial airlines and business aviation operators drive equipment refresh cycles as aviation authorities mandate SBAS-enabled precision approaches. Australia's Civil Aviation Safety Authority and EASA shape retrofit schedules across their respective jurisdictions.
- Marine:Automated vessel traffic management systems in Singapore and Rotterdam integrate SBAS-derived positioning for container terminal approach lanes.
- Transportation:Rail signaling and autonomous vehicle corridors pilot augmentation for lane-level positioning accuracy.
- Agriculture:Precision farming operations leverage sub-meter accuracy for automated guidance in row-crop planting and harvesting.
Revenue concentrates in Aerospace; application expansion runs through Marine.
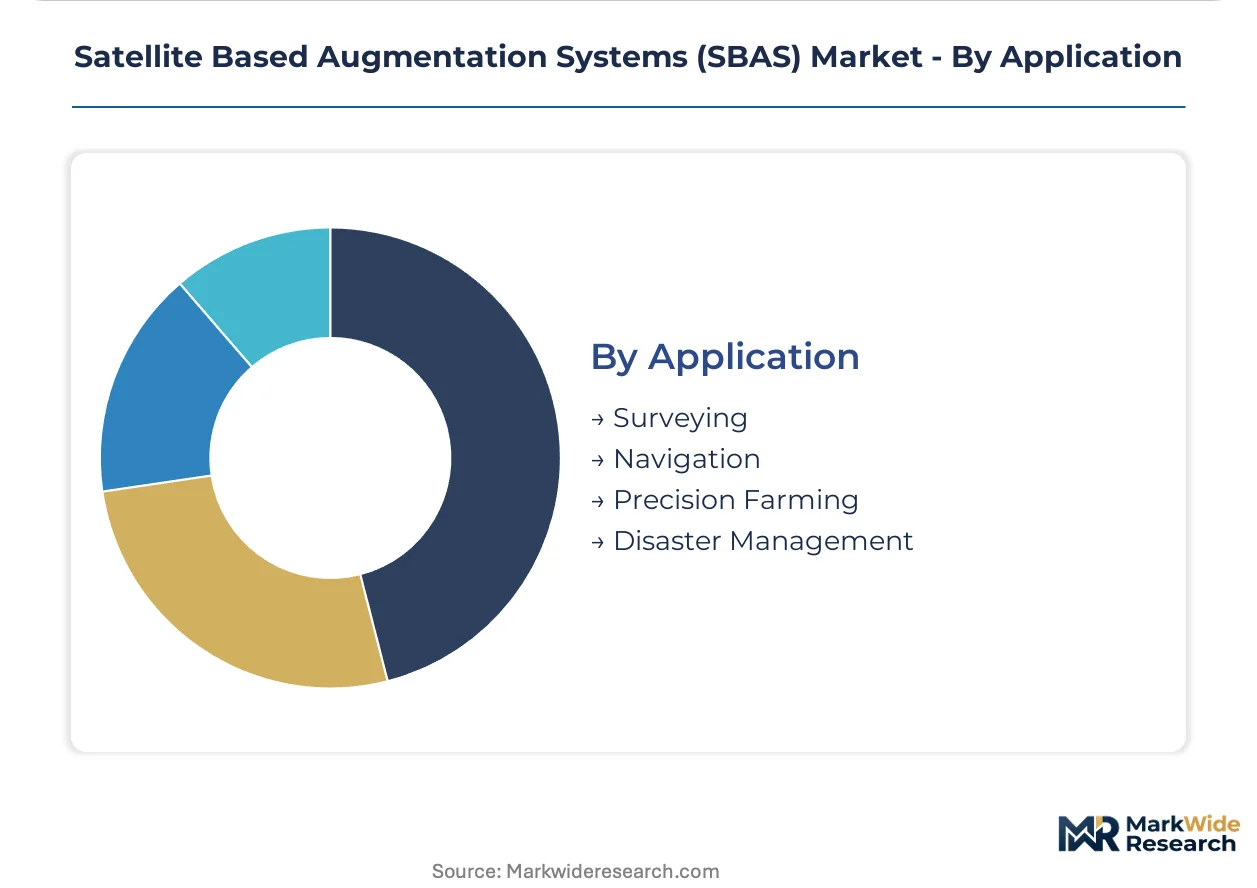
Application:
Accuracy requirements and operational tempo dictate whether sub-meter positioning justifies infrastructure investment.
- Navigation:Continuous positioning for moving platforms demands real-time integrity validation. Aviation and marine operators dominate this segment with Safety-of-Life certification requirements.
- Precision Farming:Automated machinery guidance relies on repeatable sub-meter accuracy for input optimization and yield mapping.
- Surveying:Static and kinematic measurement applications require centimeter-level accuracy through carrier-phase differential techniques.
- Disaster Management:Rapid deployment positioning supports emergency response coordination where infrastructure damage compromises terrestrial references.
Deployment scale favors Navigation; automation integration advances fastest in Precision Farming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Dubai and Shenzhen concentrate SBAS equipment manufacturing and regional distribution hubs, attracting avionics suppliers through customs duty exemptions and streamlined certification pathways for aerospace components.
United States
FAA WAAS program mandates drive dual-frequency avionics retrofits across US-registered commercial fleets. The FAA's LPV approach requirements force equipment upgrades at regional airports lacking ILS infrastructure. Dallas-Fort Worth and Seattle aerospace clusters host major avionics integration facilities serving domestic airlines.
Germany
EASA EGNOS Safety-of-Life certification accelerates ground infrastructure deployments across German aviation networks. The EU F-Gas Regulation compels master control center operators to adopt ammonia-based cooling systems in ground facilities. Munich and Hamburg anchor European SBAS payload engineering and ground station manufacturing.
China
BeiDou SBAS deployment by China's national satellite navigation office establishes parallel certification tracks for Asian operators. MIIT spectrum allocation policies govern L-band augmentation signal planning for domestic aviation corridors. Beijing-Tianjin-Hebei cluster hosts satellite payload integration facilities serving regional airlines.
Australia
Civil Aviation Safety Authority mandates SBAS-enabled precision approaches across the Sydney-Melbourne aviation corridor, forcing fleet-wide retrofits. CASA regulatory deadlines compress equipment procurement timelines for domestic carriers. Sydney and Melbourne airports serve as pilot deployment sites for next-generation approach procedures.
Singapore
Port Authority vessel traffic management systems integrate SBAS-derived positioning for automated container terminal operations. Maritime and Port Authority of Singapore mandates sub-meter accuracy for vessel approach lanes in the Strait of Malacca. Tuas Port development incorporates hybrid augmentation architectures for autonomous vessel guidance.
Satellite Based Augmentation Systems (SBAS) Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the SBAS value chain, creating a tiered structure where scale advantages in satellite manufacturing confront agility in avionics integration. The market consolidates around three strategic archetypes: defense-aerospace conglomerates controlling geostationary payload deployment, avionics specialists dominating terminal equipment channels, and ground infrastructure providers capturing master control center upgrades. Competitive moves center on multi-constellation receiver certification races and strategic partnerships with national navigation offices seeking sovereign augmentation capabilities.
Within the defense-aerospace tier, Raytheon Technologies Corporation and Lockheed Martin Corporation exemplify conglomerates leveraging geostationary expertise and government contract relationships. Honeywell International Inc. and Thales Group occupy positions spanning avionics integration and ground infrastructure, representing hybrid archetypes that bridge terminal equipment and network operations. Garmin Ltd. anchors the commercial aviation and general aviation specialist segment, concentrating on receiver manufacturing without upstream satellite assets.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Honeywell International Inc. |
| Thales Group |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Airbus SE |
| Boeing |
| Garmin Ltd. |
| Hexagon AB |
| Others |
Supply Flow & Price Mechanics
Fleet retrofit mandates from Australia's CASA and EASA are compressing procurement timelines and forcing suppliers to pre-position inventory, which elevates working capital requirements and transmits cost premiums through the avionics channel.
Pricing Analysis
Lead-time premiums dominate pricing negotiations as airlines facing CASA and EASA deadlines pay 15-25% markups for accelerated delivery slots. The market operates on a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by certification tier (FAA WAAS versus EASA EGNOS) and after-sales service bundling. Cost compression in general aviation receivers is intensifying because RF front-end component suppliers face capacity constraints. Low-cost carriers in Southeast Asia exhibit the highest price sensitivity, while business aviation operators absorb premiums for multi-constellation terminals.
Supply Chain Analysis
Dual-sourcing requirements from EASA and FAA certification bodies mandate that avionics manufacturers qualify multiple RF chipset suppliers, fragmenting procurement leverage. Manufacturing concentrates in the United States, Germany, and China, with final assembly drawing from Taiwanese semiconductor foundries and Japanese precision component suppliers. Supply chain risk centers on single-source vulnerability for radiation-hardened geostationary payload components. Distribution runs through authorized avionics dealers and direct OEM channels to airline technical operations centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over geostationary payload capacity and ground station networks determines margin capture. Players are pursuing downstream channel control through captive avionics integration facilities.
For Market Incumbents: Deploy multi-constellation certification investment to lock in EASA and FAA approval timelines before regulatory deadlines harden. Incumbents should acquire specialized ionospheric modeling firms to internalize algorithm development and defend against emerging pure-play software entrants. Capacity addition in Australian ground station networks captures CASA-mandated retrofit demand. For New Entrants and Emerging Players: Ground infrastructure providers represent the most penetrable entry point, as EGNOS and WAAS network expansions require modular master control center upgrades. New entrants should target Brazil's regional airport segment, where geostationary coverage gaps create demand for ground-based augmentation alternatives. A joint development agreement with national navigation offices offers the clearest go-to-market path. For Investors and Strategic Acquirers: The window for entry favors hybrid system architects with terrestrial-orbital fusion capabilities over pure satellite operators. Long-term viability rests on capturing recurring integrity monitoring subscription revenue rather than one-time equipment sales. Acquisition targets should demonstrate EASA Safety-of-Life certification progress. The signal to watch is BeiDou SBAS certification timeline acceleration, which would fragment compliance zones and elevate multi-constellation receiver valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Receiver Certification | EASA and FAA dual approvals compress competitor entry timelines for aviation terminals. |
| Ground Station Network Expansion | CASA-mandated Sydney-Melbourne corridor upgrades create captive demand pools. |
| Hybrid System Architecture Development | Singapore and Rotterdam port authorities specify redundancy for automated vessel traffic. |
| Integrity Monitoring Subscription Model | Indonesian and Vietnamese low-cost carriers favor unbundled procurement matching lease terms. |
| Geostationary Payload Partnership | Thales and Raytheon anchor European coverage through government contract relationships. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with avionics integration engineers, airline fleet planning directors, ground station procurement managers, and satellite payload program managers. Secondary sources included FAA WAAS program documentation, EASA EGNOS certification databases, ICAO standards publications, and customs records for SBAS equipment trade flows. Bottom-up equipment shipment analysis and top-down navigation services revenue estimates were triangulated to validate market sizing.
Data-stream reconciliation across reference station deployment schedules, avionics retrofit announcements, and geostationary launch manifests informed the analytical framework. Segmentation dimensions modeled encompassed product type (space-based, hybrid, ground-based), technology (GPS, Galileo, BeiDou, GLONASS), end user (aerospace, marine, transportation, agriculture), and application (navigation, precision farming, surveying, disaster management). CAGRs were derived from equipment procurement timelines tied to regulatory mandate deadlines and fleet replacement cycles, with cross-validation against satellite operator revenue disclosures and avionics manufacturer order backlogs.
Caveats apply where geostationary slot allocation delays, L-band spectrum disputes, or multi-constellation certification timeline extensions could materially shift the outlook. Forecasts reflect assumptions regarding regulatory mandate adherence, supply chain capacity scaling, and constellation operational readiness. Deviation in EASA or FAA certification velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global Dish Antennas Market
Satellite
Satellite Gateway Market
Satellite
Tactical Satellite Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Satellite Transponder Market
Satellite
Satellite Antenna Market
Satellite
Broadband Satellite System Market
Satellite
4K Satellite Broadcasting Market
Satellite
Satellite Services Market
Satellite
North America Remote Sensing Satellites Market
Satellite
Africa Satellite Connectivity Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
North America Mobile Satellite Services Market