
 Brazil Satellite-Based Earth Observation Market | 2026-2036
Brazil Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Satellite-Based Earth Observation Market Insights
CE marking requirements for commercial remote sensing payloads is bifurcating the vendor landscape between qualified system integrators and component suppliers. Maxar Technologies leverages its end-to-end constellation management capabilities to anchor premium contracts with federal defense clients. INPE sustains operational dominance through its indigenous satellite manufacturing pipeline and ground station network across Amazonian territories. Visiona Tecnologia Espacial S.A. competes on domestic content requirements embedded in public procurement frameworks.
Satellite-based earth observation encompasses the acquisition, processing, and distribution of geospatial data from orbital platforms carrying optical, radar, or multi-spectral instruments, typically operating at altitudes between 400 and 700 kilometers with revisit cycles ranging from daily to bi-weekly depending on constellation density. The primary commercial purpose centers on delivering actionable intelligence for resource management, infrastructure planning, and environmental compliance verification. Imaging satellites occupy the largest revenue pool given their established role in agricultural commodity trading and carbon credit verification, while synthetic aperture radar platforms represent the fastest-expanding technology segment due to all-weather operational reliability over cloud-prone Amazonian basins. Government agencies command the dominant end-user channel through multi-year budget allocations for territorial monitoring, though private sector adoption accelerates fastest among agribusiness consortia seeking supply chain traceability certification.
ANVISA regulates data privacy frameworks affecting health-related geospatial applications, while the Brazilian Space Agency (AEB) governs orbital licensing and frequency coordination under national space policy directives that prioritize sovereign data control. INPE additionally administers the TerraClass land cover classification protocol that shapes product standardization for deforestation monitoring contracts. Stakeholders must monitor pending revisions to Brazil's geospatial data classification regime, as reclassification of certain imagery products could restrict cross-border data flows or create new licensing obligations for foreign-owned constellation operators serving Brazilian territory.
Market Dynamics
INPE's indigenous satellite manufacturing pipeline and TerraClass land cover classification protocol are compressing procurement cycles for federal deforestation monitoring contracts, forcing foreign constellation operators to localize data processing infrastructure or exit sovereign service agreements.
Growth Catalysts
- Soybean commodity trading:Agribusiness consortia in Mato Grosso and Goiás require persistent satellite monitoring for supply chain traceability certification to EU deforestation-free import regulations.
- TerraClass protocol standardization:INPE's land cover classification mandates create recurring revenue streams for domestic analytics providers serving federal environmental enforcement agencies.
- Synthetic aperture radar:All-weather imaging capabilities penetrate persistent cloud cover over Amazonian basins, enabling year-round pasture health monitoring for cattle operations.
Market Restraints
- Ground station infrastructure concentration:Amazonian ground station networks remain concentrated around INPE-operated facilities, creating single-point-of-failure risk for real-time data downlink services.
- CE marking compliance costs:Commercial remote sensing payloads face bifurcated vendor qualification requirements between system integrators and component suppliers, elevating procurement friction for foreign hardware.
- Optical imaging substitution:Uncrewed aerial vehicle fleets offer higher-resolution alternatives for sub-500 hectare monitoring tasks, pressuring pricing for low-altitude satellite tasking.
Strategic Opportunities
- Carbon credit verification:Emerging demand from voluntary carbon markets requires satellite-derived biomass estimation for REDD+ project validation in Pará and Amazonas states.
- Multi-sensor fusion analytics:Convergence of optical, radar, and thermal infrared data streams enables new product categories for soil moisture prediction in Center-West agricultural zones.
- State-level procurement frameworks:Tocantins and Rondônia environmental secretariats are establishing independent satellite imagery acquisition budgets outside federal INPE channels.
Industry Challenges
- Geospatial data science talent scarcity:Brazilian universities produce insufficient machine learning specialists trained in orbital mechanics and spectral analysis for agricultural yield forecasting.
- Legacy system integration complexity:State environmental agencies operate fragmented GIS platforms that resist API-level interoperability with modern satellite data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Satellite-Based Earth Observation Market |
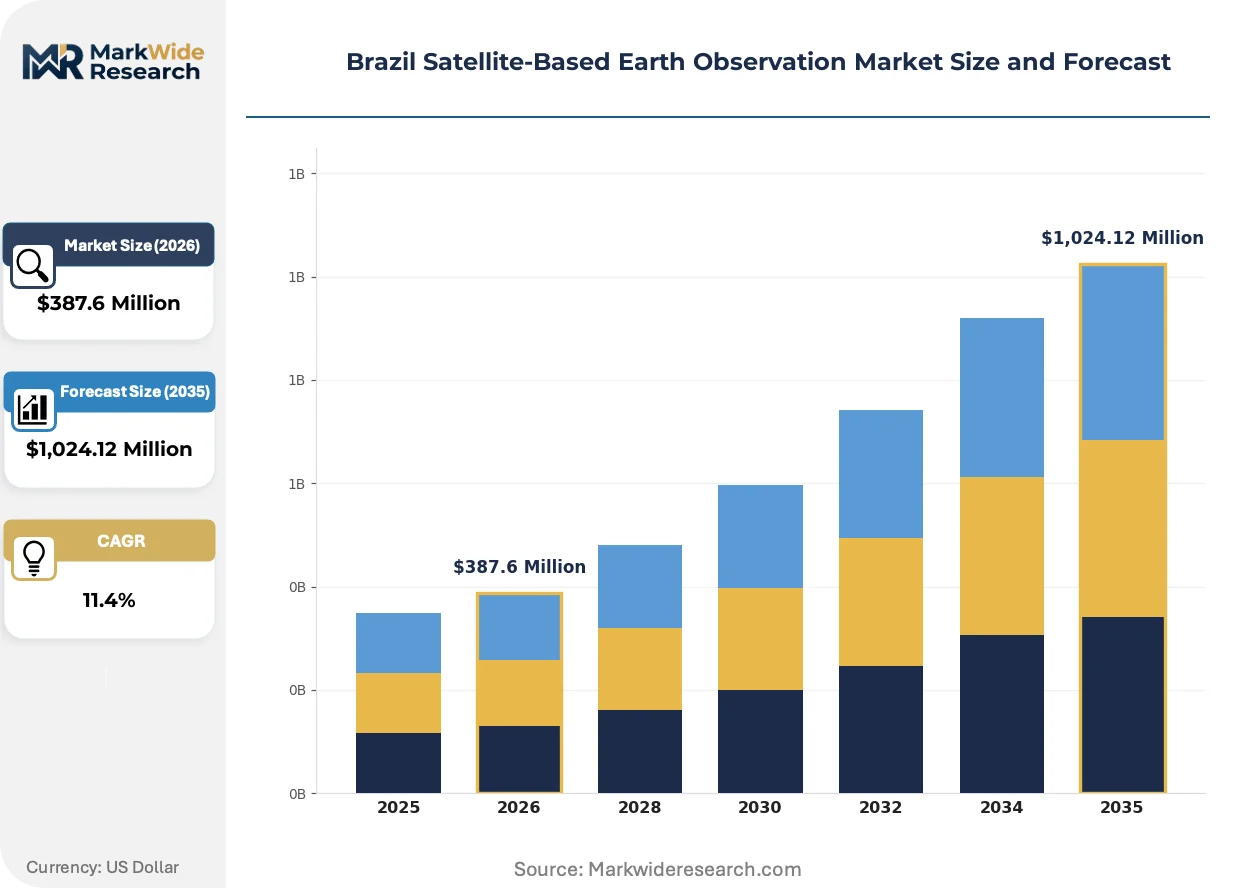
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Satellites, Radar Satellites, Multi-Sensor Systems, CubeSats Application: Agriculture Monitoring, Urban Planning, Disaster Management, Environmental Monitoring End User: Government Agencies, Research Institutions, Private Sector, Non-Governmental Organizations Technology: Optical Sensors, Synthetic Aperture Radar, Hyperspectral Imaging, Ground Stations |
| Companies Covered | Brazilian Space Agency (AEB), Maxar Technologies, National Institute for Space Research (INPE), EarthDaily Analytics, BlackSky, Visiona Tecnologia Espacial S.A., Embraer S.A., Planet Labs, Embratel Star One, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Satellite-Based Earth Observation Market Trends and Innovations
Small-satellite constellation architectures are fragmenting the incumbent vendor base, while regulatory mandates for supply chain traceability accelerate demand for automated change-detection algorithms across Brazilian agricultural frontiers.
Hyperspectral imaging payloads are decomposing the traditional value chain for agricultural commodity risk assessment. Large trading houses in São Paulo now task dedicated orbital sensors for protein content prediction in soybean shipments. This capability is compressing margins for generic multispectral providers who cannot resolve biochemical signatures at sub-10 meter resolution.
ANVISA's pending frameworks for health-related geospatial data privacy are creating compliance overhead for epidemiological mapping applications. Remote sensing providers serving public health agencies must now segment patient-adjacent location data from commercial imagery products. The pharmaceutical and hospital supply chain vertical is responding by demanding sovereign cloud processing within Brazilian territory.
Subscription-based imagery access is displacing per-scene procurement for mid-sized agribusiness operators. Rural credit cooperatives in Mato Grosso do Sul now bundle satellite monitoring into crop insurance products, embedding analytics costs into lending margins. This channel shift is most visible among cattle ranchers seeking pasture rotation compliance documentation for export certification.
Brazil Satellite-Based Earth Observation Market Segmentation
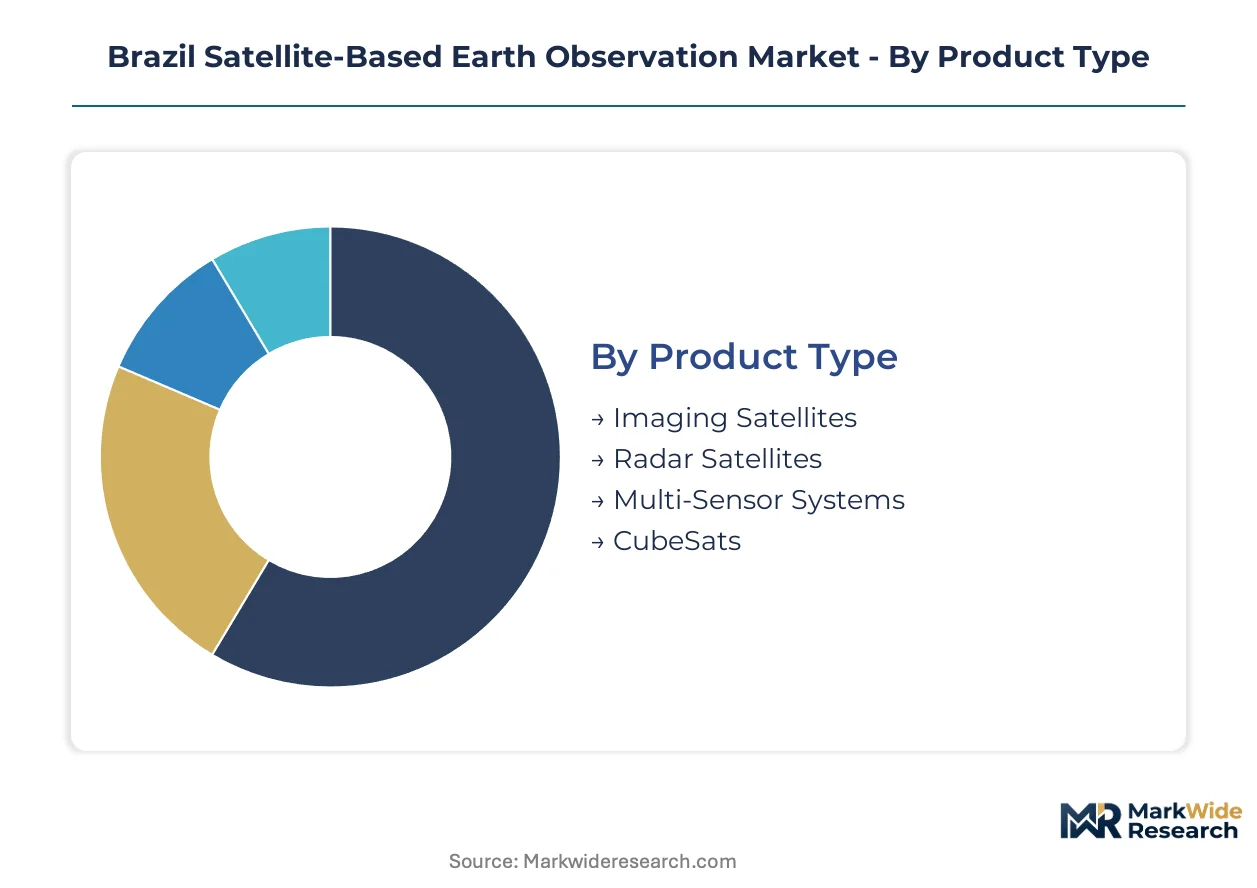
Brazil's satellite-based earth observation market fragments across product architectures, application verticals, and procurement channels. Each segment carries distinct localization requirements and sovereign data constraints that reshape vendor qualification pathways.
Product Type:
Domestic manufacturing capabilities concentrate in imaging and radar platforms, while CubeSat procurement draws heavily on foreign component supply chains subject to CE marking compliance.
- Imaging Satellites:Optical payloads operating at 400-700 kilometer altitudes with multispectral bands deliver sub-meter resolution for agricultural commodity verification. Demand clusters in Mato Grosso soybean trading houses seeking EU deforestation-free certification documentation.
- Radar Satellites:Synthetic aperture radar platforms penetrate persistent Amazonian cloud cover with all-weather imaging reliability. Cattle operations in Pará and Rondônia deploy these for year-round pasture boundary monitoring where optical sensors fail.
- Multi-Sensor Systems:Fused optical-radar-thermal architectures enable soil moisture prediction and biomass estimation for carbon credit verification projects.
- CubeSats:Standardized 10x10x10 centimeter form factors reduce launch mass costs for university research consortia and state-level environmental monitoring pilots.
Imaging satellites command the established base. The steepest expansion runs through radar satellites.
Application:
Revenue concentration tilts toward compliance-driven use cases where regulatory mandates override pure cost optimization.
- Agriculture Monitoring:Crop yield forecasting and supply chain traceability dominate procurement volumes. Rural credit cooperatives in Goiás and Mato Grosso do Sul bundle satellite analytics into crop insurance products, embedding monitoring costs into lending margins.
- Environmental Monitoring:INPE's TerraClass protocol mandates create recurring federal contracts for land cover classification and deforestation alert systems. State environmental secretariats in Tocantins and Amazonas establish independent acquisition budgets outside federal channels.
- Urban Planning:Municipal governments in São Paulo and Brasília deploy orbital imagery for informal settlement mapping and infrastructure corridor planning.
- Disaster Management:ANA and civil defense agencies require rapid-tasking capabilities for flood extent mapping in Pantanal wetlands and landslide risk zones in Rio de Janeiro's coastal mountains.
Agriculture monitoring commands the established base. The steepest expansion runs through environmental monitoring.
End User:
Procurement authority fragments across federal budget allocations, state-level environmental secretariats, and private sector traceability mandates.
- Government Agencies:INPE, IBAMA, and AEB anchor demand through multi-year sovereign data contracts. Federal mandates prioritize domestic content requirements and ground station localization.
- Private Sector:Agribusiness consortia and commodity trading houses drive fastest adoption growth. Large São Paulo trading houses now task dedicated orbital sensors for protein content prediction in soybean shipments.
- Research Institutions:Universities and INPE research divisions access subsidized imagery for algorithm development and TerraClass protocol refinement.
- Non-Governmental Organizations:Conservation groups deploy satellite analytics for REDD+ project validation and illegal logging detection in indigenous territories.
Government agencies command the established base. The steepest expansion runs through private sector adoption.
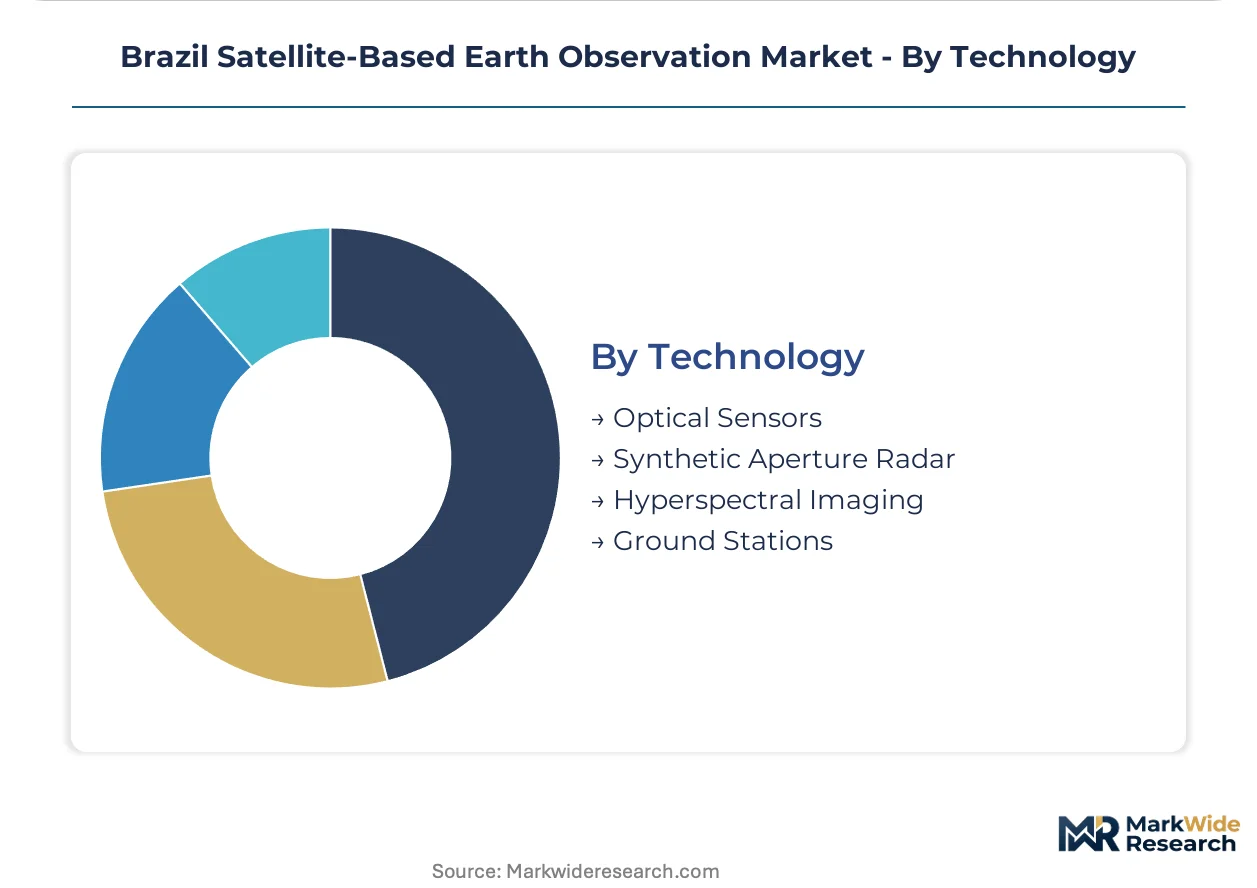
Technology:
Platform capabilities diverge between established optical architectures and emerging hyperspectral and radar modalities.
- Optical Sensors:Multispectral imagers in visible and near-infrared bands support established agricultural yield forecasting workflows. Pricing pressure intensifies from uncrewed aerial vehicle substitution for sub-500 hectare monitoring tasks.
- Synthetic Aperture Radar:Active microwave systems enable all-weather, day-night imaging over cloud-prone Amazonian basins. Cattle ranchers in Mato Grosso rely on these for pasture rotation compliance documentation.
- Hyperspectral Imaging:Narrow spectral bands resolve biochemical signatures for protein content and moisture prediction. Large trading houses deploy these for commodity risk assessment at sub-10 meter resolution.
- Ground Stations:Amazonian downlink infrastructure concentrates around INPE-operated facilities, creating single-point-of-failure risks for real-time data services.
Optical sensors command the established base. The steepest expansion runs through synthetic aperture radar.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Alcântara Launch Center in Maranhão anchors Brazil's orbital access infrastructure, positioning the country as the dominant satellite earth observation hub across Latin America. State-level procurement frameworks and federal sovereign data mandates concentrate demand in specific sub-regions.
São Paulo
Commodity trading houses in São Paulo drive premium-tier demand for hyperspectral tasking and protein content analytics in soybean shipments. ANVISA's pending health-related geospatial privacy frameworks are forcing pharmaceutical supply chain operators to demand sovereign cloud processing within state boundaries. The São Paulo metropolitan corridor hosts the densest concentration of private sector analytics providers serving agribusiness consortia.
Mato Grosso
Soybean and cattle operations in Mato Grosso require persistent radar monitoring for EU deforestation-free certification compliance. INPE's TerraClass protocol mandates create recurring federal contracts for land cover classification services delivered to regional IBAMA enforcement units. Rural credit cooperatives in Cuiabá and Rondonópolis now bundle satellite analytics into crop insurance products.
Pará
Cattle ranchers in Pará deploy synthetic aperture radar for year-round pasture boundary monitoring where optical sensors fail under persistent cloud cover. State environmental secretariats are establishing independent imagery acquisition budgets outside federal INPE channels. The Belém metropolitan area anchors emerging demand for REDD+ carbon credit verification services.
Goiás
Agribusiness consortia in Goiás require satellite-derived supply chain traceability documentation for export certification to European markets. The National Spatial Data Infrastructure policy mandates standardized geospatial data sharing across state agricultural agencies. Goiânia-based analytics providers specialize in crop yield forecasting for the Center-West grain belt.
Amazonas
Ground station infrastructure concentrates around INPE-operated facilities in Manaus, creating single-point-of-failure risks for real-time data downlink services. State-level environmental secretariats are piloting independent satellite imagery budgets for indigenous territory monitoring. Conservation NGOs deploy orbital analytics for illegal logging detection in hard-to-access rainforest corridors.
Brazil Satellite-Based Earth Observation Market Competitive Landscape
Listed leaders compete with private specialists across sovereign data contracting, creating a bifurcated vendor landscape between qualified system integrators and component suppliers. The market structure concentrates around three strategic archetypes: domestic satellite manufacturers with indigenous ground station networks, foreign constellation operators with end-to-end management capabilities, and specialized analytics providers serving compliance-driven verticals. Dominant competitive moves include localization of data processing infrastructure to satisfy federal content requirements and strategic partnerships with state environmental agencies seeking independent procurement channels.
Within the domestic manufacturing tier, Visiona Tecnologia Espacial S.A. and Embraer S.A. exemplify vendors positioned to capture public procurement frameworks through domestic content compliance. Maxar Technologies and Planet Labs represent foreign constellation operators that must localize infrastructure or exit sovereign service agreements under INPE's contracting pressure. These named entities anchor the competitive dynamics without exhaustively mapping the vendor base.
| Leading Market Players |
|---|
| Brazilian Space Agency (AEB) |
| Maxar Technologies |
| National Institute for Space Research (INPE) |
| EarthDaily Analytics |
| BlackSky |
| Visiona Tecnologia Espacial S.A. |
| Embraer S.A. |
| Planet Labs |
| Embratel Star One |
| Others |
Pricing and Supply Chain Analysis
Multi-year sovereign data contracts anchor both supply access and price visibility for foreign constellation operators serving Brazilian territory, locking in ground station localization requirements and domestic content thresholds that compress margin flexibility.
Pricing Analysis
Volume-discount tiering structures separate federal defense clients from mid-sized agribusiness operators and rural credit cooperatives. Subscription-based imagery access is displacing per-scene procurement, embedding analytics costs into crop insurance lending margins. Price differentiation hinges on certification grade for TerraClass protocol compliance and sovereign cloud processing mandates under ANVISA frameworks. Cost compression in low-altitude optical tasking is intensifying because uncrewed aerial vehicle fleets offer higher-resolution alternatives for sub-500 hectare monitoring. Government agencies exhibit lowest price sensitivity due to budget allocation rigidity, while cattle ranchers seeking pasture rotation documentation show highest elasticity.
Supply Chain Analysis
Inbound logistics costs from European and North American component suppliers face elevated freight exposure through Santos port congestion and container availability constraints on trans-Atlantic lanes. Satellite manufacturing draws from United States, France, and Japan for optical sensor arrays, radar transmitters, and precision gyroscopic stabilization systems. Raw material dependencies center on gallium arsenide semiconductors, carbon-fiber composite structures, and specialized thermal control coatings. Single-source vulnerability concentrates in INPE-operated Amazonian ground station networks. Distribution runs through federal procurement channels, state environmental secretariats, and agribusiness consortia seeking supply chain traceability certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
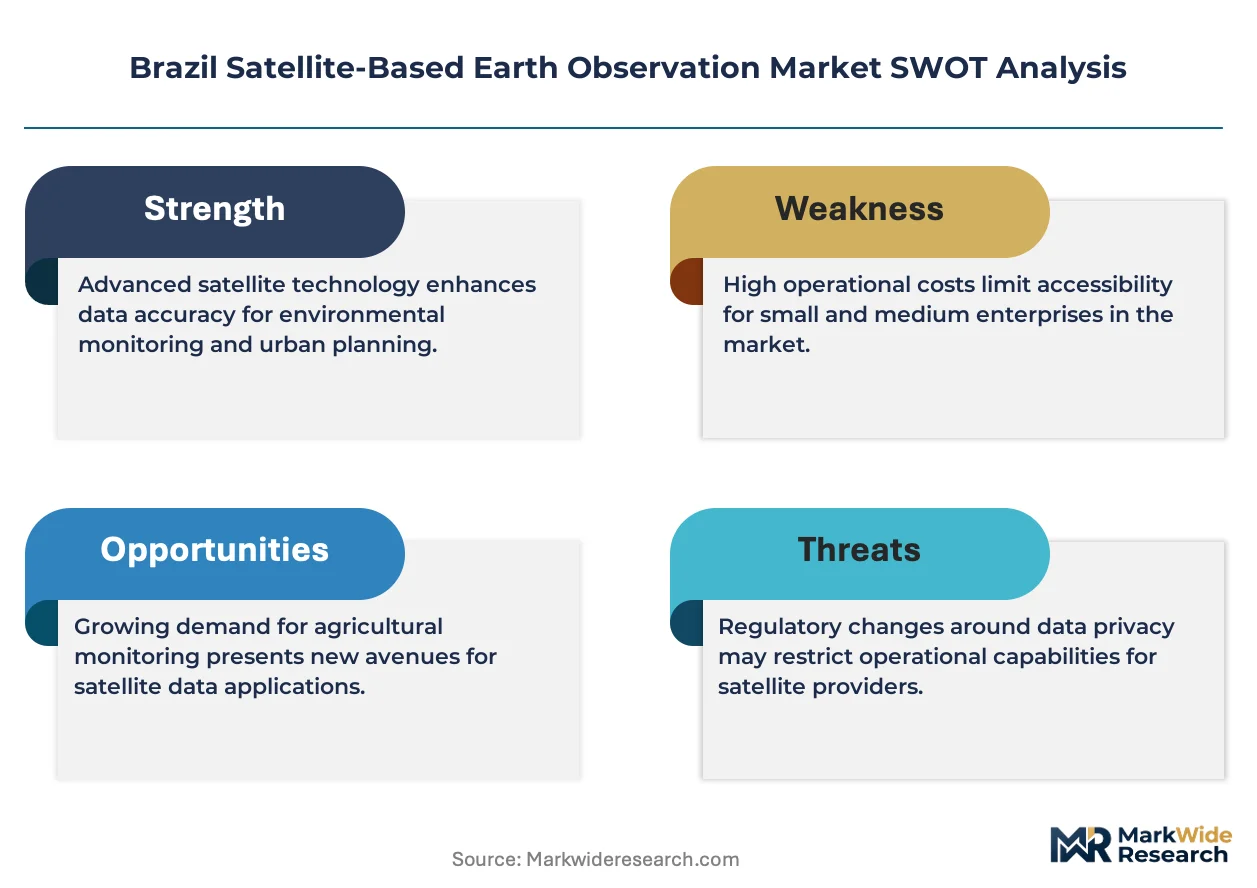
Synthetic aperture radar capabilities are disrupting established optical imaging dominance, creating white-space opportunities for all-weather analytics providers as EU deforestation-free regulations harden compliance requirements.
For Market Incumbents: Secure long-term anchor contracts with INPE and IBAMA before state-level environmental secretariats establish independent procurement channels. Deepen backward integration into indigenous satellite manufacturing pipelines to satisfy domestic content mandates embedded in federal tenders. Vertical control over ground station networks defends against foreign constellation operators localizing data processing infrastructure. For New Entrants and Emerging Players: Lead with hyperspectral imaging tasking for protein content prediction in soybean shipments, targeting São Paulo commodity trading houses with premium analytics bundles. Carbon credit verification services in Pará and Amazonas states represent the most penetrable white space. A go-to-market angle through rural credit cooperatives embeds monitoring costs into existing lending relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among analytics providers serving TerraClass protocol mandates with multi-year federal enforcement contracts. Long-term viability centers on vendors with sovereign data control capabilities and Amazonian ground station infrastructure. Acquisition targets should demonstrate API-level interoperability with fragmented state environmental agency GIS platforms. The signal to watch is pending revisions to Brazil's geospatial data classification regime that could restrict cross-border data flows.| Strategic Initiative | Industry Significance |
|---|---|
| Ground Station Localization | Satisfies INPE domestic content requirements and secures federal sovereign data contracts. |
| Hyperspectral Sensor Deployment | Enables protein content prediction for São Paulo trading houses at sub-10 meter resolution. |
| API-Level GIS Integration | Overcomes legacy system fragmentation across state environmental agency platforms. |
| Carbon Credit Verification Partnership | Captures emerging REDD+ project validation demand in Pará and Amazonas states. |
| Radar-Optical Fusion Analytics | Delivers year-round pasture monitoring for cattle operations under persistent Amazonian cloud cover. |
Research Methodology
Initial hypotheses were tested against primary input from satellite constellation operators, agribusiness procurement directors, INPE research scientists, and state environmental secretariat officials and refined through secondary validation. Primary fieldwork drew from AEB licensing officers, IBAMA enforcement unit managers, rural credit cooperative lending officers, and commodity trading house risk analysts. Secondary sources included AEB orbital licensing databases, INPE TerraClass land cover classification protocols, ANVISA pending geospatial privacy frameworks, and federal procurement transparency portals. Bottom-up demand modeling from individual state budgets and top-down macroeconomic triangulation anchored volume estimates.
Variance-decomposition framing isolated drivers across product architecture, application vertical, and procurement channel dimensions. Segmentation modeling captured imaging versus radar platform splits, agriculture monitoring versus environmental compliance use cases, and government agency versus private sector end-user dynamics. CAGRs were derived from fitted growth curves against historical budget allocation patterns and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated EU deforestation-free regulation compliance deadlines and state-level satellite imagery budget pilot programs.
Forecasts assume regulatory continuity in AEB orbital licensing, ANVISA geospatial privacy, and INPE TerraClass standardization regimes; material policy shifts would require re-modeling. Specific risks include reclassification of imagery products restricting cross-border data flows, CE marking compliance cost escalation for foreign hardware, and ground station infrastructure concentration creating service interruption vulnerabilities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Tactical Satellite Market
Satellite
Asia-Pacific Small Satellite Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Global LEO Satellite Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
EMEA Satellite Antenna Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Global Small Satellite Service Market
Satellite
Mexico Satellite Connectivity Market
Satellite
North America Satellite IoT Market
Satellite
Satellite Parts and Components Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Nanosatellite Market
Satellite
Satellite Broadband Market
Satellite
Satellite Communications Service Market