
 Eastern Europe and North Africa Satellite Communication Market | 2026-2036
Eastern Europe and North Africa Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Eastern Europe and North Africa Satellite Communication Market Analysis
Software-defined payload architectures is reconfiguring how satellite operators provision capacity across Eastern Europe and North Africa. SES S.A. leverages its O3b mPOWER constellation to deliver low-latency services across Mediterranean shipping lanes. Eutelsat anchors its regional position through high-throughput Ka-band coverage of North African terrestrial networks. Thales Group specializes in military-grade waveform encryption for government end users from Warsaw to Cairo.
Satellite communication encompasses the transmission of voice, data, and video signals via artificial orbital relays operating across C-band, Ku-band, Ka-band, and emerging Q/V-band frequencies, with link budgets engineered to overcome path loss exceeding 200 dB over 36,000 km geostationary distances. Its primary purpose is to extend connectivity to regions lacking fiber infrastructure or requiring rapid deployable networks. Broadband service type captures the dominant revenue pool as fiber-backfill demand surges in Romanian and Bulgarian rural zones. Low Earth Orbit technology is expanding fastest among constellation operators seeking to reduce round-trip latency below 50 milliseconds for telemedicine and disaster recovery applications. Geostationary platforms retain margin strength in direct-to-home broadcasting across Egyptian and Algerian households.
Poland's Office of Electronic Communications enforces spectrum coordination rules that shape Ku-band licensing for VSAT deployments across the Carpathian Basin. Egypt's National Telecommunications Regulatory Authority mandates in-country gateway presence for foreign satellite operators serving Sinai and Red Sea corridors. The EU F-Gas Regulation constrains refrigerant choices for ground station thermal management in Romanian and Hungarian teleport facilities. Stakeholders must monitor how national security designations for orbital spectrum reshape procurement eligibility for military and telecommunications end users across both regions.
Market Dynamics
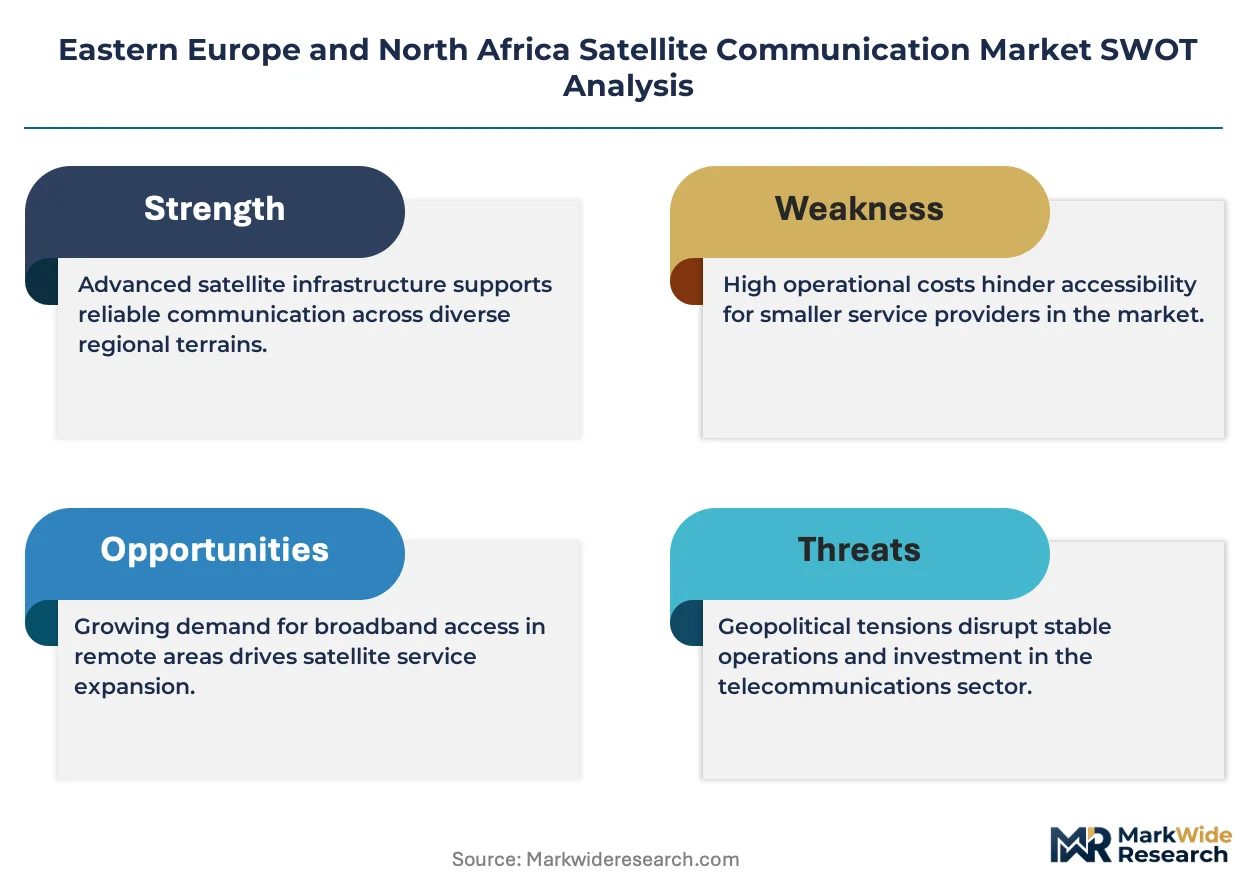
Low Earth Orbit constellations are collapsing the latency premium that once justified geostationary pricing across Mediterranean shipping corridors and Balkan backhaul networks.
Growth Catalysts
- EU F-Gas Regulation:Ground station operators in Hungary and Romania are retrofitting teleport thermal systems, creating retrofit demand for compliant cooling infrastructure.
- Maritime VSAT:Suez Canal transit volumes are pulling dedicated bandwidth contracts for vessel tracking and crew welfare applications.
- Ka-band proliferation:High-throughput spot beams are enabling fiber-competitive pricing in Bulgarian and Romanian rural broadband zones.
Market Restraints
- Spectrum licensing fragmentation:Poland's Office of Electronic Communications imposes Ku-band coordination rules that extend deployment timelines for VSAT networks.
- Gateway localization mandates:Egypt's National Telecommunications Regulatory Authority requires in-country earth stations, raising capital barriers for foreign operators.
- Launch capacity bottlenecks:Ride-share manifest scarcity is constraining constellation refresh cycles for regional operators.
Strategic Opportunities
- Telemedicine backhaul:Romanian and Bulgarian health ministries are soliciting low-latency links for rural diagnostic imaging transmission.
- Military waveform encryption:NATO interoperability standards are opening procurement channels for secure satellite terminals across Polish and Romanian defense sectors.
- Disaster recovery networks:Rapid-deployable VSAT kits are penetrating civil protection agencies in Egypt and Algeria.
Industry Challenges
- RF engineering talent scarcity:Specialized satellite communications expertise concentrates in Warsaw and Cairo, leaving regional teleport operations understaffed.
- Legacy integration complexity:Government end users in Algeria and Egypt maintain C-band infrastructure that resists seamless handoff to multi-orbit architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eastern Europe and North Africa Satellite Communication Market |
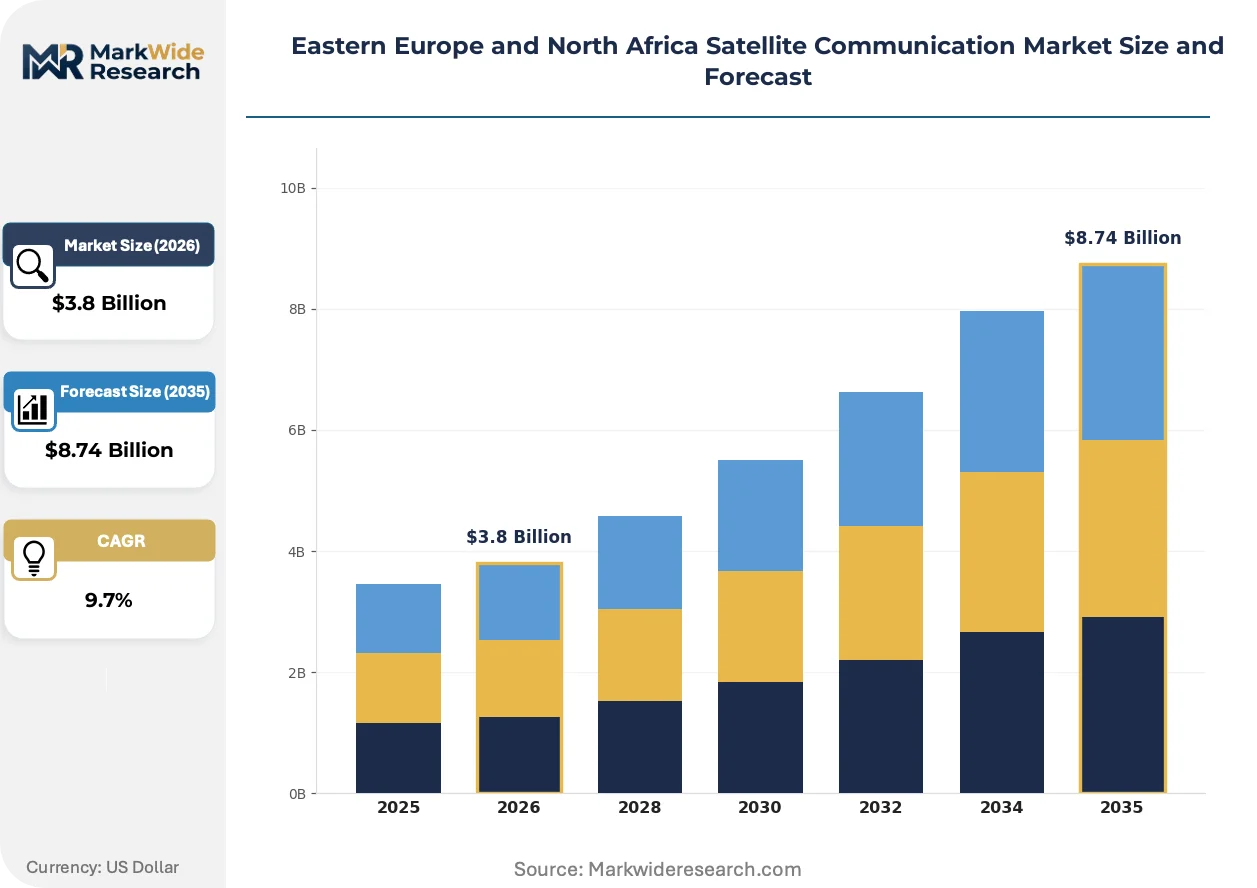
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadband, Direct-to-Home, VSAT, Mobile Services End User: Government, Military, Telecommunications, Broadcasting Application: Telemedicine, Disaster Recovery, Remote Sensing, Education Technology: Geostationary, Medium Earth Orbit, Low Earth Orbit, Adaptive Coding |
| Companies Covered | SES S.A., Viasat, Inc., Eutelsat, Intelsat, Iridium Communications Inc., Thales Group, Telesat, Airbus SE, Gilat Satellite Networks Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eastern Europe and North Africa Satellite Communication Market Emerging Trajectories
Orbital diversity is reshaping how capacity gets provisioned across Eastern Europe and North Africa, with technical and regulatory vectors converging on interoperability and latency reduction.
Software-defined radio payloads are collapsing the hardware refresh cycle for satellite operators serving North African terrestrial networks. Egyptian and Algerian mobile backhaul providers are adopting reconfigurable modems that switch between geostationary and medium Earth orbit beams without truck rolls. This compression of equipment lifecycle economics is forcing ground segment vendors to abandon fixed-function appliance strategies.
Poland's spectrum coordination framework is tightening Ku-band licensing requirements for VSAT deployments across the Carpathian Basin. The Office of Electronic Communications now mandates interference studies that extend permitting timelines by several quarters. Romanian and Hungarian teleport operators are responding by consolidating earth station clusters to streamline regulatory filings.
Defense procurement patterns are rotating toward multi-orbit resilience requirements across Warsaw and Bucharest. Military end users are unbundling single-vendor satellite service contracts in favor of architecture-agnostic waveform specifications. This behavioral shift is most visible in Polish border surveillance programs, where request-for-proposal documents now explicitly require seamless handoff between geostationary and low Earth orbit constellations.
Eastern Europe and North Africa Satellite Communication Market Segmentation
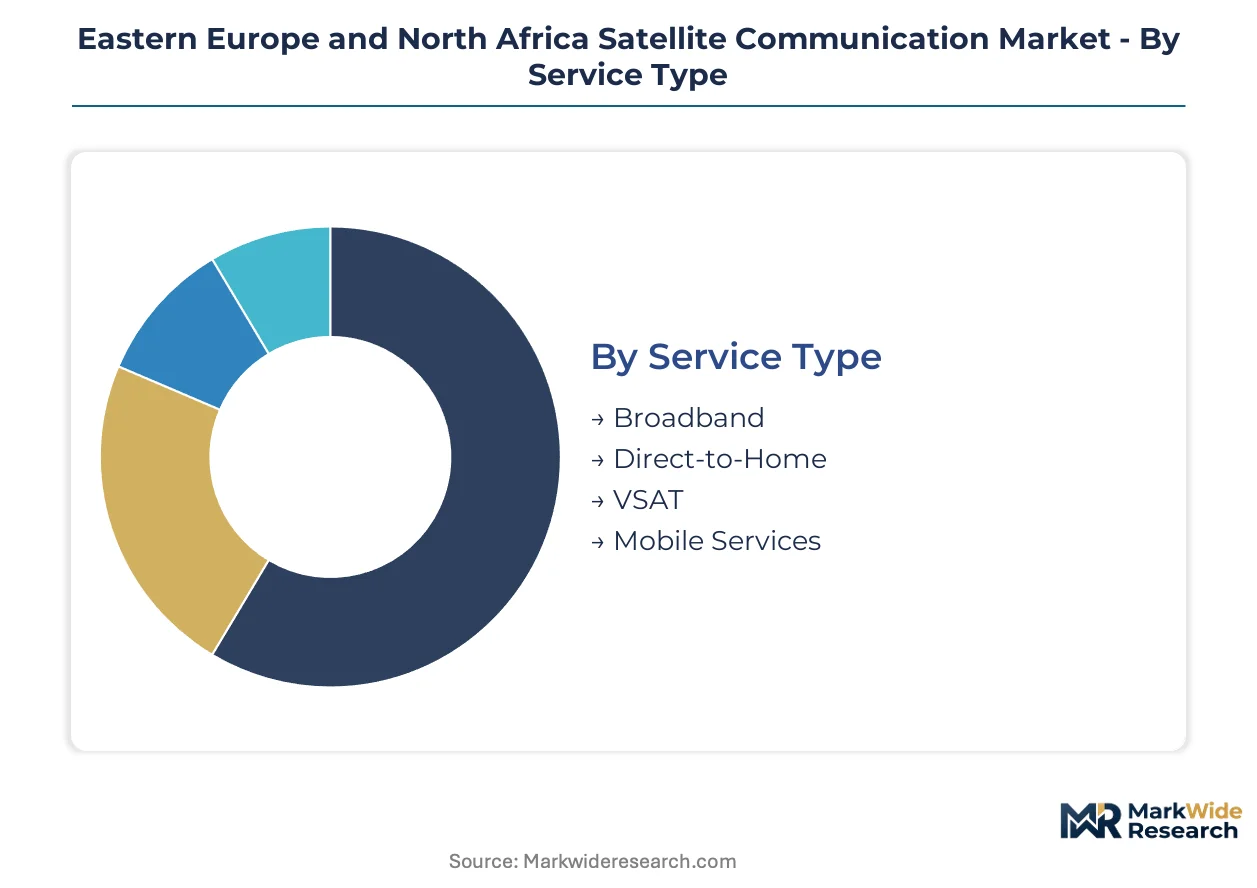
Segmentation reveals how satellite capacity flows across distinct use cases and orbital architectures in Eastern Europe and North Africa. Each dimension exposes different procurement rhythms, from military waveform specifications to rural broadband subsidy eligibility. Understanding these splits clarifies where pricing power concentrates versus where commoditization pressures mount.
Service Type:
Mature broadcast services anchor revenue stability while emerging connectivity formats capture the steepest expansion curves across Romanian and Egyptian deployments.
- Broadband:High-throughput spot beams deliver fiber-backfill capacity to Bulgarian and Romanian rural zones where terrestrial infrastructure gaps exceed 40 kilometers. Polish ISPs are procuring Ka-band links under national broadband subsidy frameworks.
- VSAT:Maritime terminals dominate Suez Canal corridor contracts, with Egyptian port authorities mandating dual-antenna redundancy for vessel tracking systems. Crew welfare bandwidth quotas are rising.
- Direct-to-Home:Geostationary Ku-band beams serve Algerian and Egyptian households with linear television packages.
- Mobile Services:Satellite-to-cellular backhaul extends coverage to North African desert transport corridors.
Broadband retains volume leadership; VSAT holds the steepest expansion curve.
End User:
Customer type segmentation separates long-cycle defense procurement from fast-turn commercial deployments across Warsaw and Cairo.
- Military:NATO interoperability standards drive secure terminal acquisitions across Polish and Romanian defense sectors. Waveform encryption specifications now mandate seamless handoff between geostationary and low Earth orbit constellations.
- Government:Egyptian civil protection agencies are procuring rapid-deployable VSAT kits for Sinai emergency response networks.
- Telecommunications:Algerian mobile operators lease C-band capacity for rural base station backhaul.
- Broadcasting:Egyptian state television maintains geostationary transponder contracts for national coverage.
Military segments command premium pricing; government procurement is climbing fastest.
Application:
Use case diversity spans latency-sensitive medical imaging to intermittent disaster response across Balkan and North African terrain.
- Telemedicine:Romanian health ministries are soliciting low-latency links for rural diagnostic imaging transmission. Bulgarian regional hospitals require sub-100 millisecond round-trip for teleradiology consultations.
- Disaster Recovery:Rapid-deployable terminals penetrate civil protection agencies in Egypt and Algeria. Portable VSAT kits activate within 90 minutes of infrastructure failure.
- Remote Sensing:Agricultural monitoring contracts concentrate in Hungarian and Romanian farming cooperatives.
- Education:Egyptian satellite-delivered curriculum reaches Sinai schools beyond fiber reach.
Telemedicine applications are gaining share fastest; disaster recovery retains deployment volume leadership.
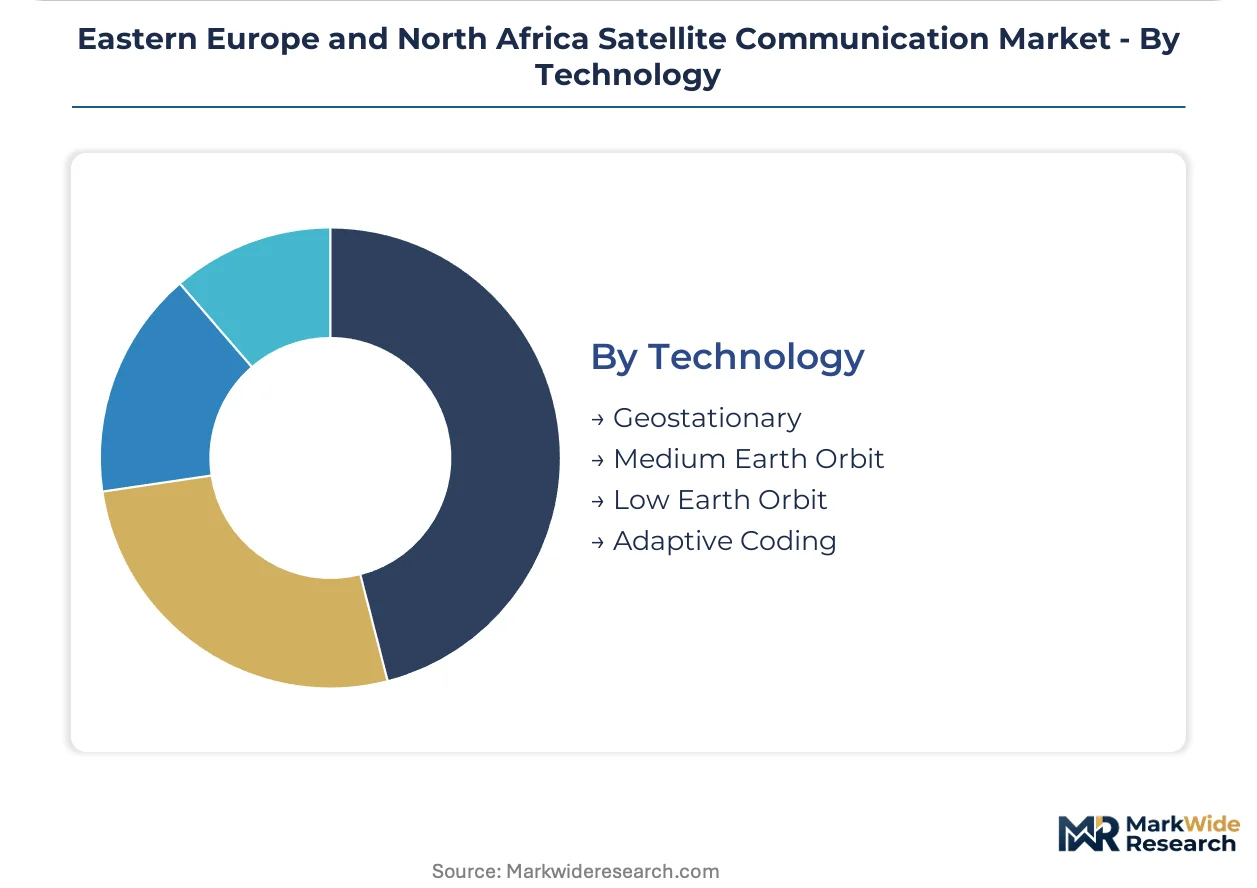
Technology:
Orbital altitude and signal processing architectures determine latency, coverage economics, and regulatory treatment across the analysis window.
- Low Earth Orbit:Constellation operators reduce round-trip latency below 50 milliseconds for telemedicine and disaster recovery applications. SES S.A. leverages O3b mPOWER to deliver services across Mediterranean shipping lanes.
- Geostationary:Retains margin strength in direct-to-home broadcasting across Egyptian and Algerian households. Ka-band spot beams enable fiber-competitive rural broadband pricing.
- Medium Earth Orbit:O3b heritage systems serve maritime and enterprise backhaul with intermediate latency tradeoffs.
- Adaptive Coding:Software-defined modems switch between orbital beams without hardware replacement.
Geostationary platforms retain volume leadership; low Earth orbit architectures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and maritime logistics coordinators concentrate satellite bandwidth demand across Poland, Romania, Egypt, and Algeria. National regulatory frameworks fragment spectrum licensing timelines. Urban teleport clusters anchor ground infrastructure deployment.
Poland
Polish defense modernization programs drive secure terminal acquisitions for NATO interoperability standards. The Office of Electronic Communications enforces Ku-band coordination rules that extend VSAT permitting timelines. Warsaw hosts the dominant teleport cluster serving Carpathian Basin backhaul networks.
Romania
Romanian health ministries solicit low-latency links for rural diagnostic imaging transmission. The EU F-Gas Regulation constrains refrigerant choices for ground station thermal management in Hungarian and Romanian facilities. Bucharest anchors enterprise VSAT procurement for Balkan broadband backfill.
Egypt
Egyptian port authorities mandate dual-antenna maritime VSAT redundancy for Suez Canal vessel tracking systems. The National Telecommunications Regulatory Authority requires in-country gateway presence for foreign satellite operators. Cairo concentrates civil protection agency procurement for rapid-deployable emergency response kits.
Algeria
Algerian mobile operators lease C-band capacity for rural base station backhaul in desert transport corridors. The country's national telecommunications regulator shapes licensing frameworks for satellite-to-cellular integration. Algiers anchors state television geostationary transponder contracts for national coverage.
Hungary
Hungarian teleport operators consolidate earth station clusters to streamline regulatory filings under tightening EU coordination requirements. The EU F-Gas Regulation drives retrofit demand for compliant cooling infrastructure. Budapest hosts regional satellite operations serving Central European enterprise networks.
Eastern Europe and North Africa Satellite Communication Market Vendor Landscape
Channel-controlling players compete with product-specialist players across Eastern Europe and North Africa. The market structure tiers between constellation operators with integrated ground networks and component-focused equipment vendors. Strategic archetypes include orbital capacity wholesalers, military-grade waveform specialists, and teleport infrastructure providers. Competitive moves concentrate on multi-orbit service bundling and defense certification acquisition.
Among Luxembourg and France-based operators, SES S.A. and Eutelsat exemplify the integrated constellation-wholesaler archetype with O3b mPOWER and Ka-band coverage positioning. Thales Group represents the defense-specialist tier with military-grade encryption capabilities. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| SES S.A. |
| Viasat, Inc. |
| Eutelsat |
| Intelsat |
| Iridium Communications Inc. |
| Thales Group |
| Telesat |
| Airbus SE |
| Gilat Satellite Networks Ltd. |
| Others |
Supply Flow & Price Mechanics
Gateway localization mandates in Egypt function as a regulatory chokepoint that compresses pricing tier spreads between premium military-grade terminals and standard commercial VSAT equipment while simultaneously forcing foreign operators into capital-intensive in-country facility investments. This structural barrier reshapes supply chain geography toward Cairo-centric earth station clusters and eliminates price arbitrage opportunities that once existed through regional teleport consolidation.
Pricing Analysis
Cost-plus contracts with launch service indexation dominate capacity procurement agreements across Eastern European and North African operators. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified military terminals from enterprise-grade maritime VSAT and consumer direct-to-home equipment. Pricing pressure stems from LEO constellation overcapacity in Mediterranean shipping corridors. Government defense segments show least price sensitivity; rural broadband ISPs in Romania and Bulgaria exhibit highest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates with Thales Alenia Space facilities in France, Airbus Defence and Space operations in Germany, and regional integration hubs in Poland. Gallium nitride power amplifiers, phased array antenna substrates, and radiation-hardened chipsets constitute critical input dependencies. Single-source vulnerability concentrates in Ukrainian titanium alloy supplies for launch vehicle structures. Distribution runs through Warsaw and Cairo teleport clusters serving as regional aggregation points for terminal equipment deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as multi-orbit interoperability requirements splinter procurement specifications across Polish defense, Egyptian maritime, and Romanian telemedicine verticals. Each vertical demands distinct waveform certifications and latency thresholds that resist vendor consolidation.
For Market Incumbents: Harden terminal certification portfolios against emerging LEO-native competitors by acquiring military waveform encryption capabilities and securing NATO interoperability designations. Prioritize backward integration into phased array antenna production to capture margin from radio frequency subsystem suppliers. Defensive consolidation of Cairo and Warsaw teleport assets will choke distribution access for foreign constellation operators. For New Entrants and Emerging Players: Algerian desert transport corridors represent the most penetrable white-space target, with mobile backhaul demand outpacing C-band capacity deployment. Bulgarian rural health networks offer second-entry potential through low-latency telemedicine link procurement. Go-to-market execution should anchor on rapid-deployable VSAT kit leasing models rather than satellite capacity resale. For Investors and Strategic Acquirers: Egypt's National Telecommunications Regulatory Authority gateway mandate reshapes the acquisition landscape by inflating asset values for in-country earth station operators. Long-term viability centers on multi-orbit service orchestration capabilities spanning geostationary, medium Earth orbit, and low Earth orbit architectures. Target acquisition archetype: teleport operators with existing Cairo presence and military certification pathways. Signal to monitor: Polish Office of Electronic Communications spectrum coordination rule amendments affecting Ku-band licensing timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Service Bundling | Polish defense procurement now mandates seamless handoff between geostationary and LEO constellations. |
| Military Waveform Certification | NATO interoperability standards in Warsaw and Bucharest create vendor lock-in for encrypted terminal suppliers. |
| In-Country Gateway Construction | Egypt's NTRA mandate forces foreign operators into capital-intensive Cairo earth station investments. |
| Software-Defined Payload Integration | Reconfigurable modems eliminate truck-roll costs for Algerian mobile backhaul providers switching orbital beams. |
| Teleport Cluster Consolidation | Hungarian and Romanian operators streamline EU F-Gas regulatory filings through Budapest facility aggregation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade databases, and satellite operator capacity disclosures. Primary interviews encompassed teleport operations directors, defense procurement officers at Polish and Romanian ministries, maritime VSAT contract managers at Suez Canal Authority, and spectrum coordination specialists at national telecommunications regulators. Secondary validation drew from EU F-Gas Regulation implementation reports, NATO standardization agreements, and satellite industry spectrum allocation databases. Bottom-up terminal shipment analysis triangulates against top-down capacity lease revenue estimates.
Forecast inputs incorporate service type segmentation, orbital architecture technology splits, end-user procurement patterns, and application-specific latency requirements across the projection horizon. Modeled dimensions span broadband, VSAT, direct-to-home, and mobile service categories; military, government, telecommunications, and broadcasting end users; plus telemedicine, disaster recovery, remote sensing, and education applications. CAGRs derive from elasticity-adjusted demand curves for fiber-backfill rural connectivity and maritime bandwidth expansion. Industry-specific inputs include Suez Canal transit volume correlations and NATO defense modernization budget trajectories.
Practitioners should monitor launch manifest availability, Egyptian gateway mandate enforcement consistency, and Polish spectrum coordination backlog duration for early signals of forecast deviation. Quarterly review of NATO terminal procurement award announcements and Suez Canal Authority VSAT contract tenders is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
Satellite Communication System Market
Satellite
India Satellite Connectivity Market
Satellite
Satellite Broadband Market
Satellite
Indonesia Satellite Communications Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Advanced Satellite Market
Satellite
Communication Satellite Launch Services Market
Satellite
Commercial Satellite Launch Service Market
Satellite
North America Satellite Launch Vehicle Market
Satellite
Europe Satellite Bus Market
Satellite
Nanosatellite Market
Satellite
North America Satellite IoT Market
Satellite
Satellite Internet Market
Satellite
Middle East Satellite Communications Market
Satellite
Russia Satellite Communications Market