
 North America Remote Sensing Services Market | 2026-2036
North America Remote Sensing Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Remote Sensing Services Market Insights
The North America Remote Sensing Services Market is rebalancing between premium analytics-intensive offerings and commodity imagery subscriptions. Maxar Technologies leverages its government heritage and high-resolution satellite constellation to command premium positioning. Planet Labs PBC sustains daily-coverage density through its Dove and SkySat fleets. L3Harris Technologies anchors defense and intelligence contracts with multispectral and radar integration.
Remote sensing services encompass the acquisition, processing, and interpretation of geospatial data from aerial platforms and orbital sensors, typically resolving features at sub-meter to thirty-meter scales depending on payload and altitude. These services convert raw electromagnetic reflectance into actionable intelligence for land-use classification, infrastructure assessment, and environmental surveillance. Satellite imaging leads in revenue scale due to persistent coverage and defense contracting, while LiDAR captures the fastest expansion driven by utility corridor mapping and autonomous vehicle training datasets. GIS services concentrate margin pools in enterprise subscriptions and municipal enterprise licensing.
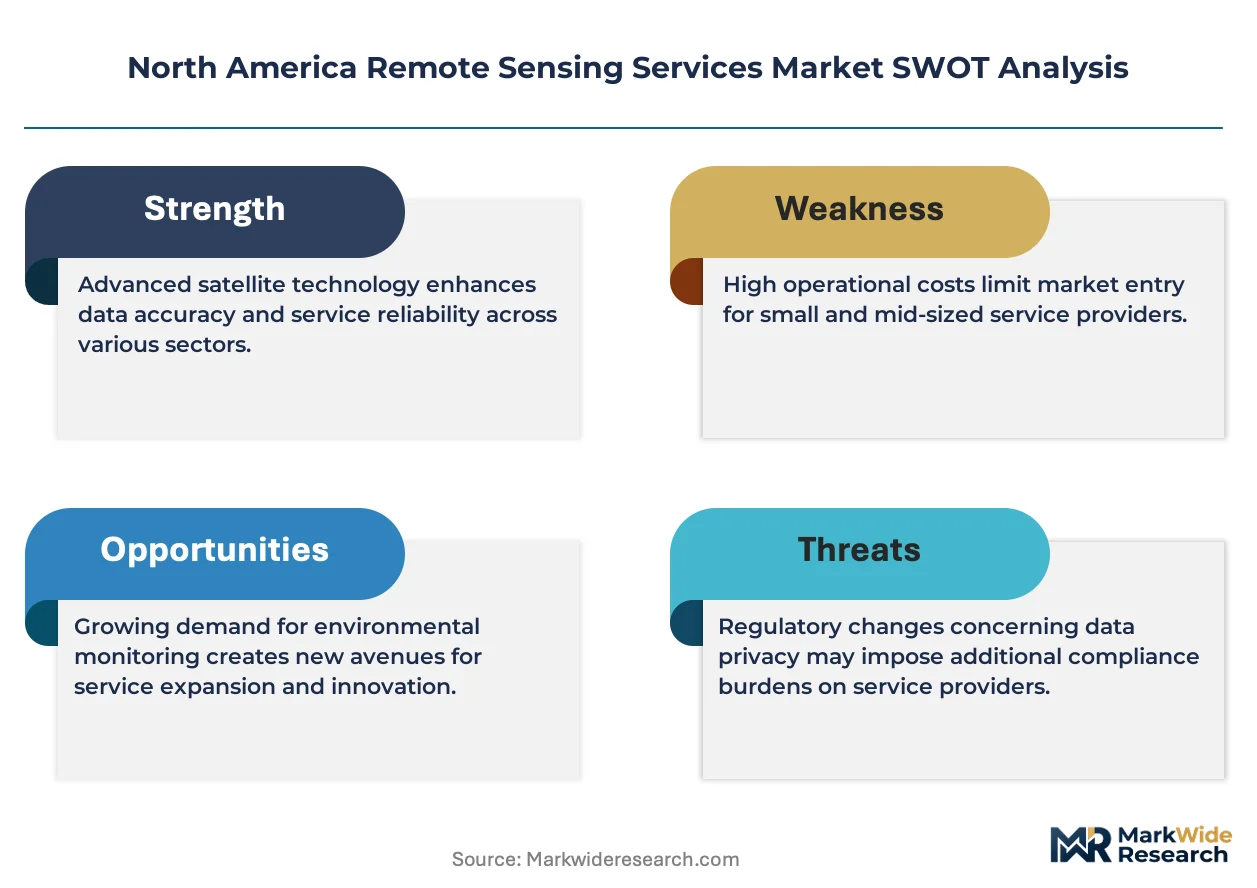
The FAA governs commercial drone operations under Part 107, constraining altitude and beyond-visual-line-of-sight activity that directly limits aerial survey scalability. FCC spectrum allocations for Earth observation downlinks shape satellite operator market access across the United States and Canada. Stakeholders must monitor evolving NOAA licensing requirements for private remote sensing spacecraft and anticipate how state-level privacy statutes in California and Texas will constrain thermal and multispectral data collection over private land.
Market Dynamics
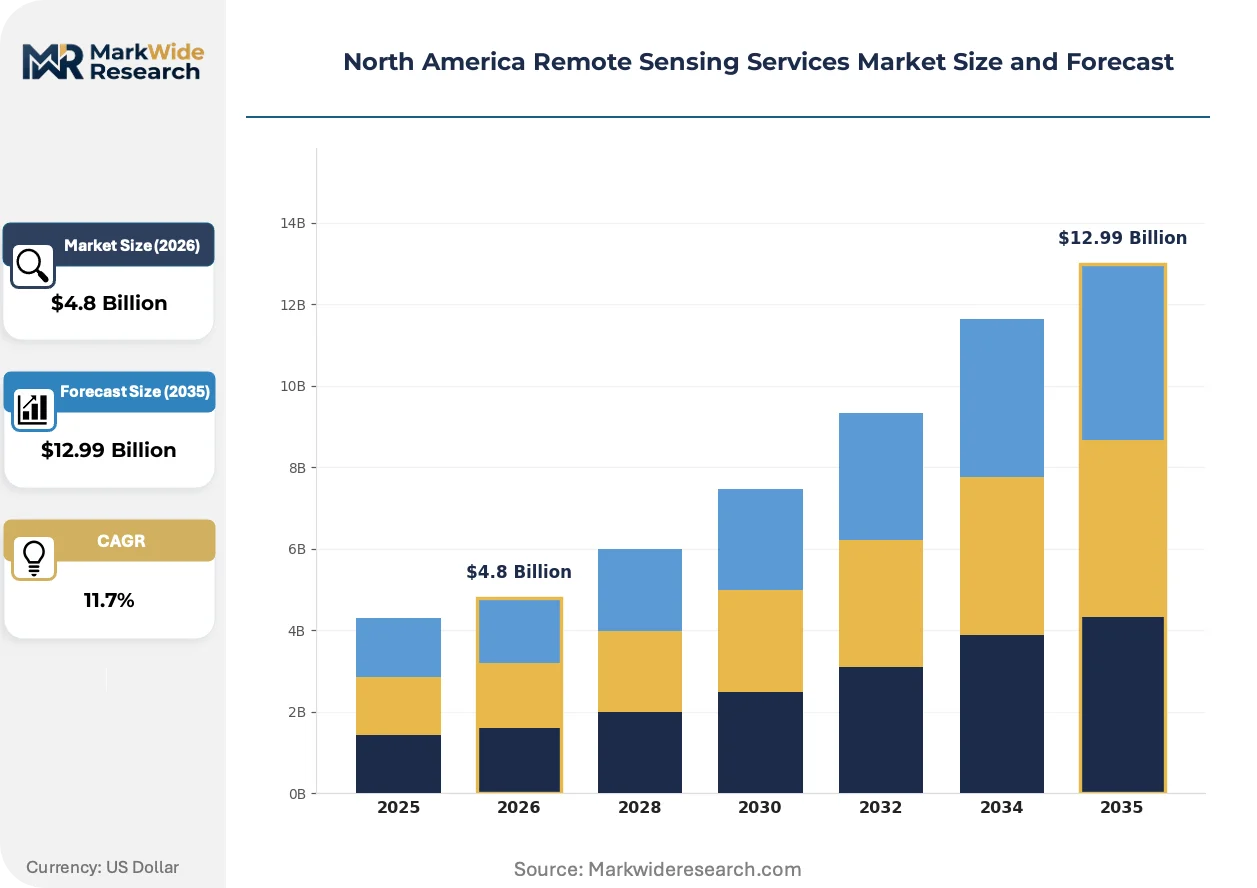
The North America Remote Sensing Services Market is bifurcating between defense-grade analytics contracts and commoditized imagery subscriptions, with FAA Part 107 altitude restrictions and NOAA spacecraft licensing timelines determining operational scalability for aerial versus orbital providers.
Growth Catalysts
- Precision Agriculture Adoption:California's Central Valley growers deploy multispectral crop health monitoring to optimize irrigation and fertilizer application, converting raw satellite reflectance into yield-maximizing prescriptions.
- FAA Part 107 Expansion:Beyond-visual-line-of-sight waiver approvals for utility corridor inspection are extending drone survey coverage across Texas and Oklahoma energy infrastructure networks.
- Hyperspectral Sensor Miniaturization:Reduced payload weights and power requirements are enabling new-class small satellites to capture 200+ spectral bands for mineral exploration and methane leak detection.
Market Restraints
- Launch Cost Concentration:Dependence on SpaceX Falcon 9 and emerging Blue Origin New Glenn capacity creates bottleneck risk for constellation replenishment schedules.
- Spectrum Allocation Friction:FCC Earth observation downlink licensing backlogs delay market entry for new satellite operators seeking Ka-band and X-band allocations.
- LiDAR Hardware Cost Structure:Solid-state laser emitter and photodetector component costs constrain aerial survey margins despite rising utility demand.
Strategic Opportunities
- Canadian Arctic Sovereignty Monitoring:Underpenetrated northern territories present whitespace for ice-road integrity and permafrost subsidence tracking services contracted through Natural Resources Canada.
- IRA Carbon Credit Verification:Inflation Reduction Act greenhouse gas monitoring mandates create tailwind demand for satellite-based emissions quantification across oil and gas basins.
- AI-ML Fusion Analytics:Convergence of convolutional neural networks with synthetic aperture radar data is enabling all-weather crop classification and infrastructure damage assessment.
Industry Challenges
- Geospatial Data Scientist Scarcity:Shortage of professionals proficient in both remote sensing physics and Python-based machine learning pipelines constrains analytics service expansion.
- State Privacy Statute Fragmentation:Divergent thermal and multispectral data collection restrictions across California, Texas, and Illinois municipal codes complicate nationwide service standardization.
- Legacy GIS Integration Complexity:ArcGIS and QGIS enterprise deployments require custom API development to ingest real-time satellite feeds, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Remote Sensing Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Aerial Survey, Satellite Imaging, LiDAR, GIS Technological Method: Multispectral, Hyperspectral, Radar, Optical Application Domain: Agriculture, Environmental Monitoring, Urban Planning, Disaster Management Customer Segment: Government Agencies, Private Sector, Research Institutions, Non-profits |
| Companies Covered | Maxar Technologies, Planet Labs PBC, L3Harris Technologies, Lockheed Martin Corporation, Satellite Imaging Corporation, Terra Remote Sensing, The Sanborn Map Company, Airborne Sensing Corporation, Spectir, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Remote Sensing Services Market Trends and Innovations
Synthetic aperture radar capabilities, regulatory frameworks for commercial space operations, and buyer procurement preferences are restructuring competitive positioning across the North America Remote Sensing Services Market.
Synthetic aperture radar (SAR) satellites penetrate cloud cover and darkness to deliver persistent all-weather surveillance. Agricultural insurers and disaster response agencies in the Gulf Coast and Pacific Northwest are adopting SAR-derived flood extent mapping at accelerating pace. This technology is electrifying catastrophe modeling and crop loss verification by eliminating the weather-dependent downtime that constrains optical imagery value.
The FCC's streamlined small satellite licensing framework reduces orbital authorization timelines from years to months for qualifying spacecraft. Commercial remote sensing operators are consolidating spectrum applications and debris mitigation plans to qualify for accelerated review. Canadian operators face parallel pressure under revised ISED radiocommunication regulations, with Vancouver and Toronto emerging as secondary regulatory filing hubs.
Enterprise buyers are unbundling imagery acquisition from analytics processing, contracting directly with cloud-agnostic algorithm providers. Municipal governments and mid-size agricultural cooperatives are displacing traditional full-service vendors with API-first platforms that ingest Planet Labs or Maxar feeds. This pattern concentrates most visibly in California's Central Valley, where irrigation districts now license detection algorithms separately from underlying satellite subscriptions.
North America Remote Sensing Services Market Segmentation
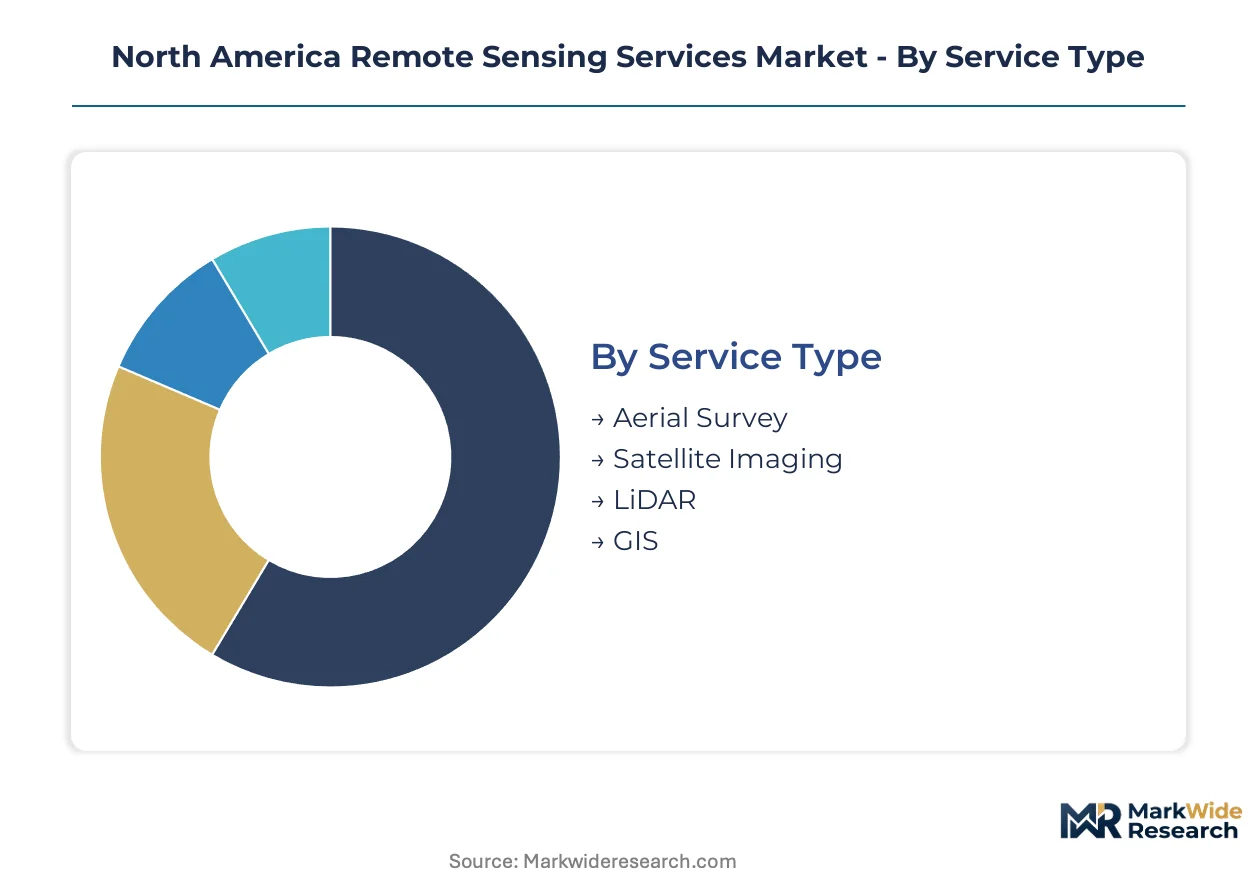
Remote sensing services fragment across acquisition platforms, spectral capabilities, and buyer procurement sophistication. Each segmentation axis reveals distinct margin profiles and regulatory exposure that shape vendor strategy across the United States and Canada.
Service Type:
Satellite imaging commands volume leadership through persistent coverage and defense contracting, while LiDAR captures premium pricing in corridor mapping applications.
- Satellite Imaging:Orbital platforms deliver sub-meter to thirty-meter resolution across vast footprints. Demand concentrates in California's Central Valley agricultural corridor where irrigation districts license daily crop health monitoring. Defense and intelligence contracts anchor revenue stability through NOAA-licensed spacecraft operations.
- LiDAR:Solid-state laser systems generate dense point clouds for utility corridor inspection and autonomous vehicle training datasets. Texas energy monitoring hubs drive fastest expansion as FAA Part 107 BVLOS waivers extend aerial survey coverage across Oklahoma pipeline networks. Hardware component costs constrain margins despite rising utility demand.
- Aerial Survey:Manned and unmanned aircraft capture on-demand high-resolution imagery for localized projects. Municipal governments in Illinois and Ohio deploy drone fleets for infrastructure assessment under altitude-restricted Part 107 frameworks.
- GIS:Geospatial information systems concentrate margin pools in enterprise subscriptions and municipal licensing. ArcGIS and QGIS deployments require custom API development to ingest real-time satellite feeds, extending implementation timelines for mid-size agricultural cooperatives.
Today's leader: Satellite Imaging. Tomorrow's challenger: LiDAR.
Technological Method:
Optical methods dominate current procurement while hyperspectral and radar capabilities expand addressable use cases through weather-independent performance.
- Optical:Passive sensors capture visible and near-infrared reflectance for vegetation index calculation and land-use classification. California growers and Texas ranchers constitute the core installed base for commodity imagery subscriptions.
- Radar:Synthetic aperture radar penetrates cloud cover and darkness to enable all-weather surveillance. Gulf Coast agricultural insurers adopt SAR-derived flood extent mapping for catastrophe modeling, eliminating weather-dependent downtime that constrains optical value. This segment climbs the fastest as satellite operators launch dedicated SAR constellations.
- Multispectral:Five-to-ten band sensors balance spectral discrimination with data volume for operational crop monitoring. FAA Part 107 drone regulations govern most aerial multispectral collection over private land.
- Hyperspectral:Two-hundred-plus band capture enables mineral exploration and methane leak detection. Reduced payload weights and power requirements are enabling new-class small satellites to expand orbital hyperspectral capacity.
Optical methods anchor present revenue. Radar capabilities unlock future expansion.
Application Domain:
Agriculture absorbs the largest service volume while environmental monitoring gains regulatory tailwind from federal greenhouse gas mandates.
- Agriculture:Multispectral crop health monitoring optimizes irrigation and fertilizer application across the Great Plains. Yield-maximizing prescriptions convert raw satellite reflectance into actionable farm management decisions.
- Environmental Monitoring:IRA carbon credit verification mandates create demand for satellite-based emissions quantification across oil and gas basins. EPA compliance reporting and state-level methane regulations accelerate procurement.
- Urban Planning:Municipal governments deploy LiDAR and optical imagery for zoning enforcement and infrastructure inventory. State privacy statutes in California and Texas constrain thermal data collection over residential areas.
- Disaster Management:FEMA and state emergency agencies leverage rapid post-event imagery for damage assessment and resource allocation. SAR-derived flood mapping penetrates storm clouds when optical sensors are grounded.
Agriculture dominates transaction volume. Environmental monitoring rides regulatory momentum.
Customer Segment:
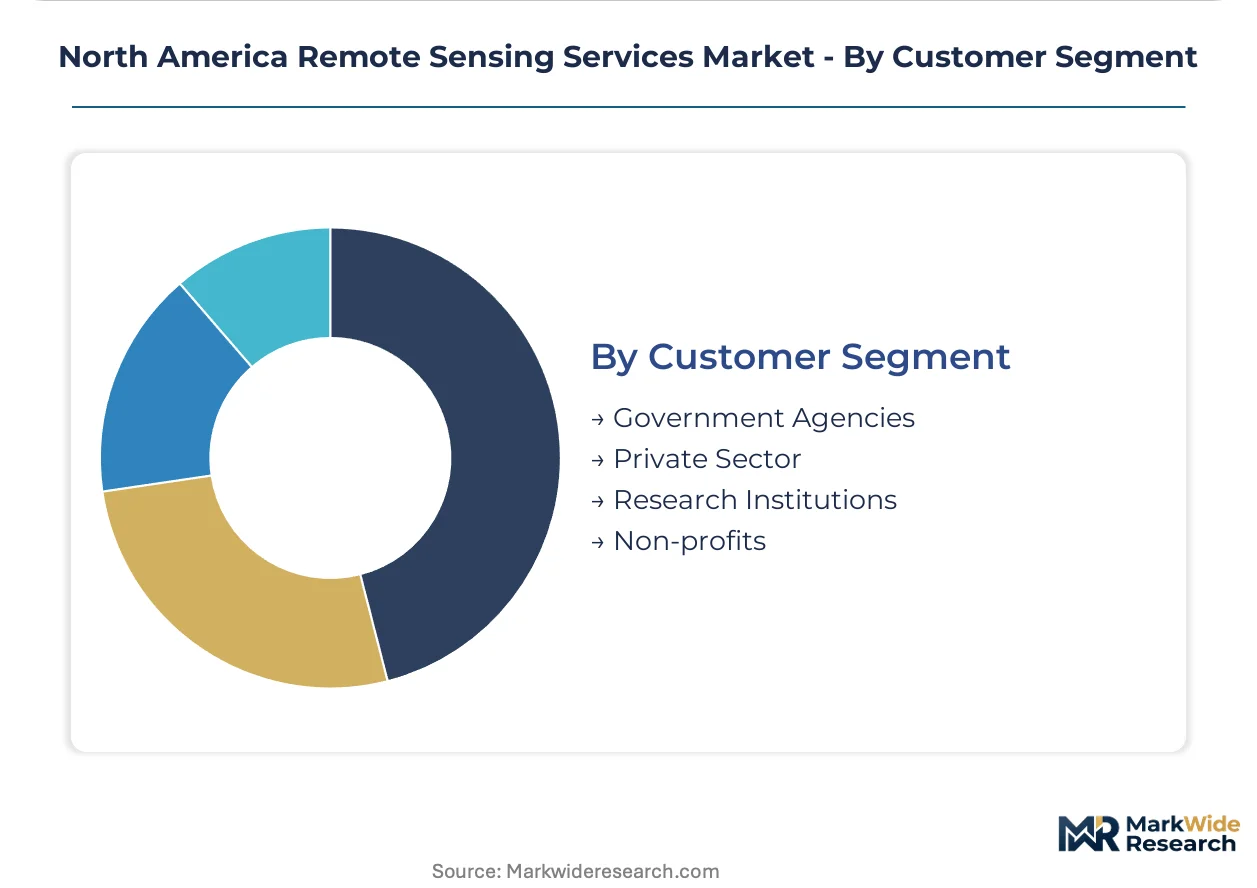
Government contracting provides revenue stability while private sector buyers drive unbundling of imagery from analytics.
- Government Agencies:Defense, intelligence, and civilian agencies anchor demand through multi-year satellite imagery contracts. NOAA licensing requirements for private remote sensing spacecraft shape vendor qualification pathways.
- Private Sector:Energy, agriculture, and insurance buyers increasingly license detection algorithms separately from underlying satellite subscriptions. API-first platforms displace traditional full-service vendors in California irrigation districts.
- Research Institutions:Universities and national laboratories access archived and tasking data for climate and land-use studies. FCC spectrum allocations for Earth observation downlinks influence academic partnership structures.
- Non-profits:Conservation organizations and humanitarian agencies leverage subsidized imagery for protected area monitoring and crisis response. Grant-funded procurement follows different budget cycles than commercial or government buyers.
Government agencies anchor contract value. Private sector buyers reshape service delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's Arctic sovereignty monitoring contracts trail the United States in scale but exceed Mexico's nascent commercial satellite services sector. Regulatory divergence between FAA Part 107 waivers and ISED radiocommunication frameworks creates distinct operational corridors across the three North American markets.
United States
California's Central Valley irrigation districts and Texas energy monitoring hubs drive multispectral crop health and methane detection demand. FAA Part 107 beyond-visual-line-of-sight waivers extend drone survey coverage across Oklahoma pipeline networks. Los Angeles and Houston anchor commercial satellite downlink licensing activity under FCC Earth observation spectrum allocations.
Canada
Natural Resources Canada contracts for ice-road integrity and permafrost subsidence tracking services in underpenetrated northern territories. ISED radiocommunication regulations govern orbital authorization timelines, with Vancouver and Toronto emerging as secondary regulatory filing hubs. Alberta's oil sands operators procure satellite-based emissions quantification for provincial methane reduction mandates.
Mexico
Aguascalientes and Jalisco agricultural cooperatives adopt precision irrigation monitoring from U.S.-based API-first platforms. The Secretariat of Communications and Transportation oversees commercial drone altitude restrictions that constrain aerial survey scalability relative to FAA frameworks. Pemex pipeline corridors in Veracruz and Tamaulipas represent emerging demand for utility infrastructure inspection.
North America Remote Sensing Services Market Competitive Landscape
Top-tier vendors anchor defense-grade analytics contracts, while mid-tier operators compete on imagery subscription density and API accessibility. The market exhibits tiered consolidation around government heritage players and emerging small-satellite constellations. Three archetypes dominate: legacy defense contractors with NOAA-licensed spacecraft, commercial imagery aggregators with daily-coverage fleets, and aerial survey specialists leveraging FAA Part 107 waivers. Competitive moves concentrate on spectrum application consolidation for accelerated FCC review and hyperspectral payload miniaturization for methane detection services.
Within the government-contractor archetype, Maxar Technologies and L3Harris Technologies occupy positions shaped by multi-year defense and intelligence satellite imagery awards. Planet Labs PBC exemplifies the commercial imagery aggregator model through its Dove and SkySat fleet operations. These three entities represent the competitive spectrum from premium analytics-intensive offerings to commoditized subscription services across the United States and Canadian markets.
| Leading Market Players |
|---|
| Maxar Technologies |
| Planet Labs PBC |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Satellite Imaging Corporation |
| Terra Remote Sensing |
| The Sanborn Map Company |
| Airborne Sensing Corporation |
| Spectir |
| Others |
Pricing and Supply Chain Analysis
IRA greenhouse gas monitoring mandates gate qualified supply and premium-tier pricing access for satellite-based emissions verification services. Vendors demonstrating EPA-compliant methane quantification methodologies command subscription premiums from oil and gas basin operators while uncertified competitors face price compression in commoditized imagery segments.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for optical imagery subscriptions as Planet Labs and Maxar expand constellation density. Three-tier pricing structure across premium analytics, standard imagery, and economy data feeds separates defense-grade SAR fusion from agricultural vegetation indices. Price differentiation rests on spectral band count and NOAA licensing status. Pricing pressure stems from API-first platforms unbundling algorithms from underlying satellite feeds. Municipal irrigation districts exhibit highest price sensitivity while intelligence agencies demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Denver and Toronto aggregate sensor payloads and ground station hardware for North American deployment. Component manufacturing concentrates in the United States, Canada, and Germany for solid-state laser emitters and photodetector arrays. Raw material dependencies include rare earth elements for sensor optics, gallium arsenide for RF components, and specialized alloys for satellite bus structures. Single-source vulnerability around SpaceX Falcon 9 launch capacity threatens constellation replenishment schedules. Distribution runs through direct vendor-to-operator contracts with limited third-party logistics penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hyperspectral analytics tiers as solid-state component costs compress and IRA verification mandates create premium pricing power.
For Market Incumbents: Anchor defense-grade contract stability through NOAA spacecraft licensing renewals and accelerated FCC spectrum application consolidation. Deepen backward integration into solid-state laser emitter production to offset photodetector cost volatility. Counter emerging API-first platforms by bundling real-time satellite feeds with proprietary convolutional neural network detection algorithms. For New Entrants and Emerging Players: Begin with Canadian Arctic sovereignty monitoring whitespace where Natural Resources Canada contracts remain underpenetrated relative to United States defense spending density. Target Alberta oil sands operators seeking provincial methane compliance verification as the most penetrable buyer segment. Pursue go-to-market partnerships with existing ground station networks to bypass orbital authorization timeline disadvantages. For Investors and Strategic Acquirers: Roll-up economics work for aerial survey specialists with FAA Part 107 BVLOS waiver portfolios because regulatory scarcity constrains new entrant capacity expansion. Five-to-ten year viability favors operators consolidating multispectral drone fleets with SAR satellite tasking rights. Monitor FCC small satellite licensing queue depth as inflection indicator for constellation replenishment bottleneck risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Payload Miniaturization | Enables 200+ band methane detection on small satellites for IRA compliance verification. |
| BVLOS Waiver Portfolio Expansion | Extends drone survey coverage across Texas and Oklahoma pipeline networks under FAA Part 107. |
| API-First Platform Development | Allows California irrigation districts to license detection algorithms separately from satellite subscriptions. |
| SAR Constellation Deployment | Delivers all-weather flood extent mapping for Gulf Coast agricultural insurers. |
| Canadian Regulatory Filing Hub Establishment | Positions Vancouver and Toronto operators for accelerated ISED radiocommunication review. |
Research Methodology
Bottom-up agricultural and energy sector modeling reconciled against top-down satellite operator capacity tracking forms the analytical core. Primary interviews with satellite mission directors, FAA certification officers, irrigation district procurement managers, and oil and gas environmental compliance leads combined with secondary validation from NOAA licensing databases, FCC spectrum allocation filings, SEC 10-K disclosures from public operators, and Natural Resources Canada contract award records. Triangulation across stakeholder inputs and documentary sources ensures coverage of both demand-side procurement patterns and supply-side constellation deployment timelines.
Input-output matrices map spectral capability tiers against buyer procurement sophistication across the projection horizon. Segmentation dimensions include service type, technological method, application domain, and customer segment with additional modeling of regulatory framework variations between FAA Part 107 and ISED radiocommunication jurisdictions. CAGRs derive from fitted growth curves calibrated to historical constellation launch cadence and waiver approval velocity. Industry-specific forecast inputs encompass SpaceX launch manifest density and EPA methane monitoring rule implementation pace.
Caveats apply where FCC spectrum allocation backlogs or NOAA licensing delays could materially shift the outlook for new entrant market access. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
GEO Satellite Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
Canada Satellite Connectivity Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Israel Satellite Communications Market
Satellite
China Satellite Connectivity Market
Satellite
UAE Satellite Communication Market
Satellite
Electric Propulsion Satellite Market
Satellite
Commercial Satellite Launch Service Market
Satellite
Sudan Satellite Transponder Market
Satellite
Satellite Bus Market
Satellite
High-Throughput Satellite Market
Satellite
Global Satellite Propulsion System Market