
 Italy Satellite Communication Market | 2026-2036
Italy Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Satellite Communication Market Insights
GaN-on-SiC power amplifiers are recalibrating payload economics for Italian satellite manufacturers. Thales Alenia Space leverages its Cannes-Rome engineering pipeline to sustain dual-use geostationary programs. Sitael SpA anchors domestic small-satellite production through its Mola di Bari facility. Viasat Group SpA competes in ground-terminal integration for maritime and aero markets.
Italy satellite communication denotes the transmission, reception, and relay of signals via artificial Earth-orbiting platforms operating across C, Ku, Ka, and emerging Q/V bands, with transponder architectures enabling broadcast, broadband, and secure military links. Low Earth Orbit technology is attracting the fastest investment as constellation operators seek reduced latency for IoT and defense applications. Geostationary service types still command the largest revenue pool due to established broadcast and government backhaul contracts. Data Transmission applications are deepening margin pools in maritime and remote sensing verticals where fiber alternatives remain impractical.
Italy's space activities fall under ASI oversight with EU Space Programme alignment through EUSPA, while military satellite procurement follows NATO standards and national defense guidelines. The country's national space strategy channels public funding toward sovereign constellation capabilities and ground infrastructure resilience. Stakeholders must monitor spectrum allocation decisions at ITU and EU levels, as Ka and Q/V band licensing directly shapes terminal manufacturing roadmaps and service profitability.
Market Dynamics
GaN-on-SiC power amplifiers are compressing payload mass-to-power ratios for Italian satellite manufacturers, forcing ground segment investments to keep pace with orbital capability gains.
Growth Catalysts
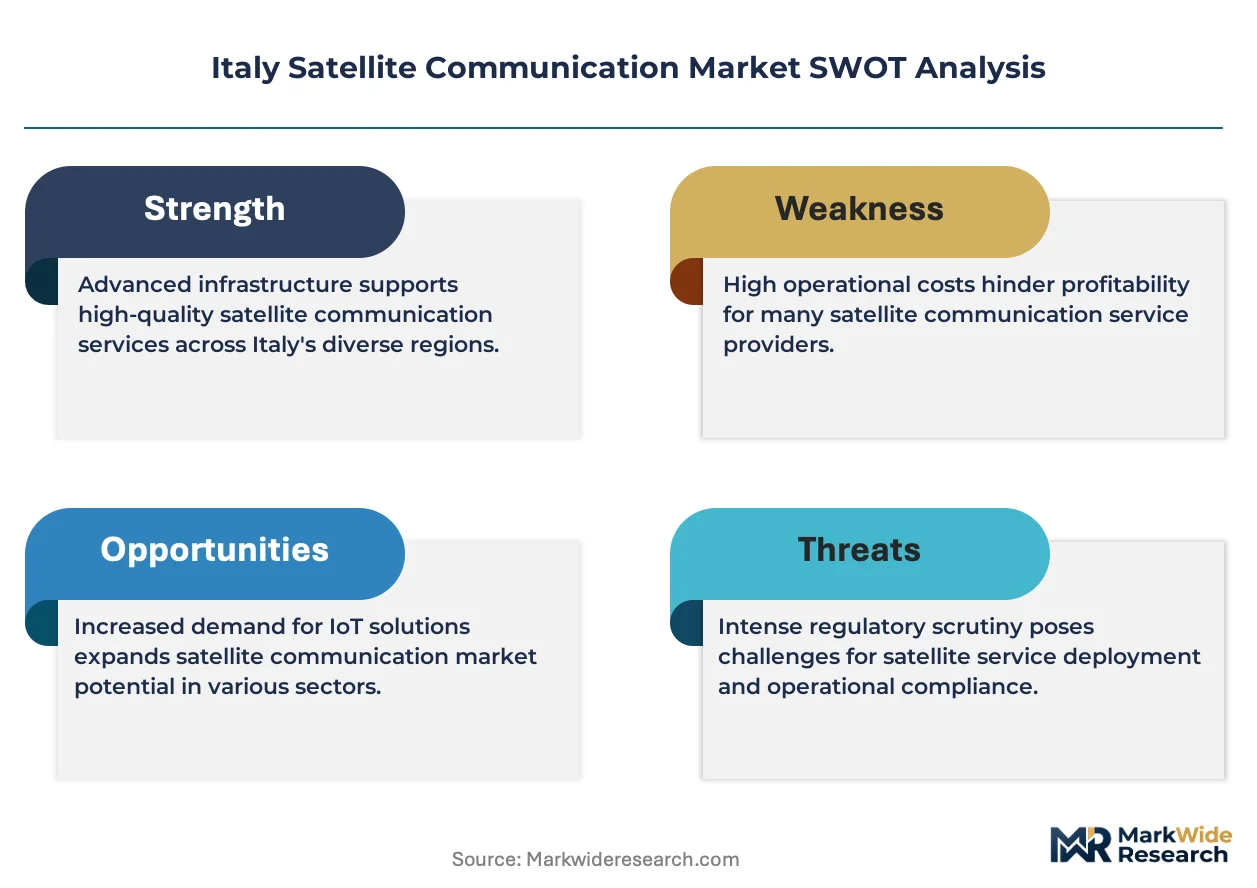
- EU Space Programme funding:EUSPA disbursements for sovereign constellation capabilities are accelerating ground infrastructure tenders across Italy's aerospace corridor.
- Naval bandwidth expansion:Italian defense procurement for maritime platforms is pulling dedicated military transponder capacity into geostationary slots.
- Q/V band licensing momentum:ITU spectrum allocations for higher-frequency operations are enabling terminal manufacturers to refresh product roadmaps for broadband verticals.
Market Restraints
- GaN substrate supply concentration:US and Japanese wafer suppliers control critical feedstock for high-performance amplifiers, exposing Italian payload builders to input bottlenecks.
- Launch cost rigidity:Arianespace and SpaceX pricing floors constrain small-satellite operators from achieving target unit economics for constellation deployment.
- Optical fiber substitution:Submarine cable expansions in the Mediterranean are eroding addressable market for maritime satellite backhaul on trunk routes.
Strategic Opportunities
- Southern Italy ground segment:Underdeveloped teleport infrastructure in Sicily and Calabria offers greenfield sites for satellite gateway consolidation.
- IoT constellation services:Low Earth Orbit platforms for agricultural and logistics monitoring remain underpenetrated in Italian SME verticals.
- Dual-use technology convergence:Civilian broadband payloads with software-defined frequency agility can pivot to defense applications under NATO interoperability standards.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave design capabilities for Ka and Q/V band systems concentrate in Rome and Turin, creating recruitment bottlenecks for expanding facilities.
- ASI certification timelines:National space agency qualification protocols for flight hardware extend development cycles beyond commercial satellite operator procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Satellite Communication Market |
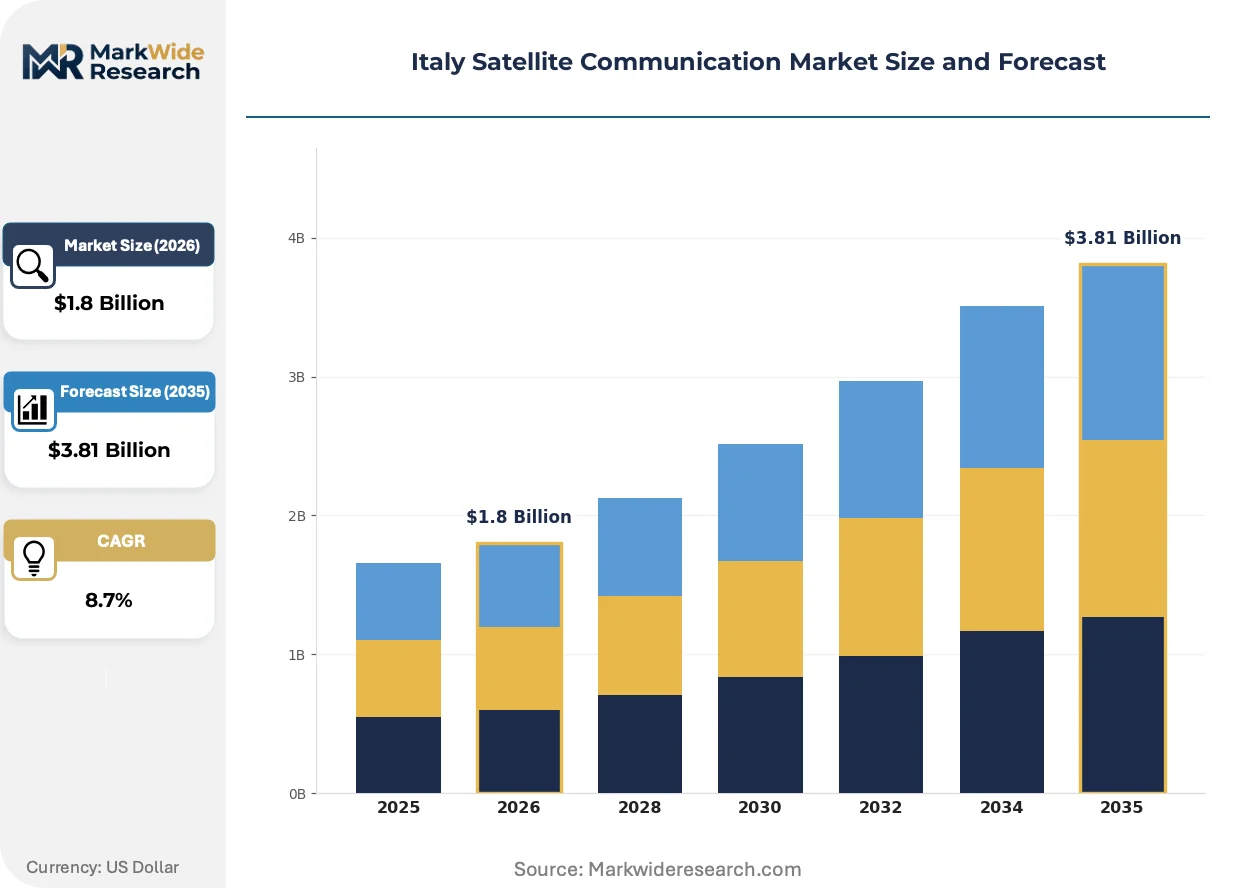
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadcast, Internet, Data Transmission, Telemetry Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, HTS End User: Government, Defense, Telecommunications, Broadcasting Application: Aerospace, Maritime, Remote Sensing, Emergency Services |
| Companies Covered | Sitael SpA, Gomedia Satcom, Thales Alenia Space, Airbus Italia SpA, Leaf Space, Viasat Group SpA, Antech Space, Temix Communications, Telecom Italia (TIM), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Satellite Communication Market Trends and Innovations
Software-defined payload architectures are decoupling hardware refresh cycles from service contracts, enabling Italian operators to reconfigure orbital assets without replacement launches.
GaN-on-SiC power amplifiers are overtaking traditional traveling-wave tube amplifiers in geostationary broadcast payloads. Italian prime contractors are adopting solid-state designs for 500W-class transponders. This transition is compressing thermal management subsystem mass and extending operational lifespans.
EU Space Programme alignment through EUSPA is mandating ground segment interoperability standards for member state constellations. Italian teleport operators must retrofit legacy C-band infrastructure for multi-orbit gateway functionality. The Rome aerospace corridor is responding with consolidated certification labs to accelerate terminal type approvals.
Defense procurement patterns are compressing vendor qualification cycles for dual-use satellite components. Italian military buyers now require civilian manufacturers to pre-certify hardware against NATO STANAG protocols before tender participation. This behavioral shift is most visible in Turin's satellite manufacturing cluster, where primes are restructuring engineering teams to parallel-track civil and military qualification streams.
Italy Satellite Communication Market Segmentation
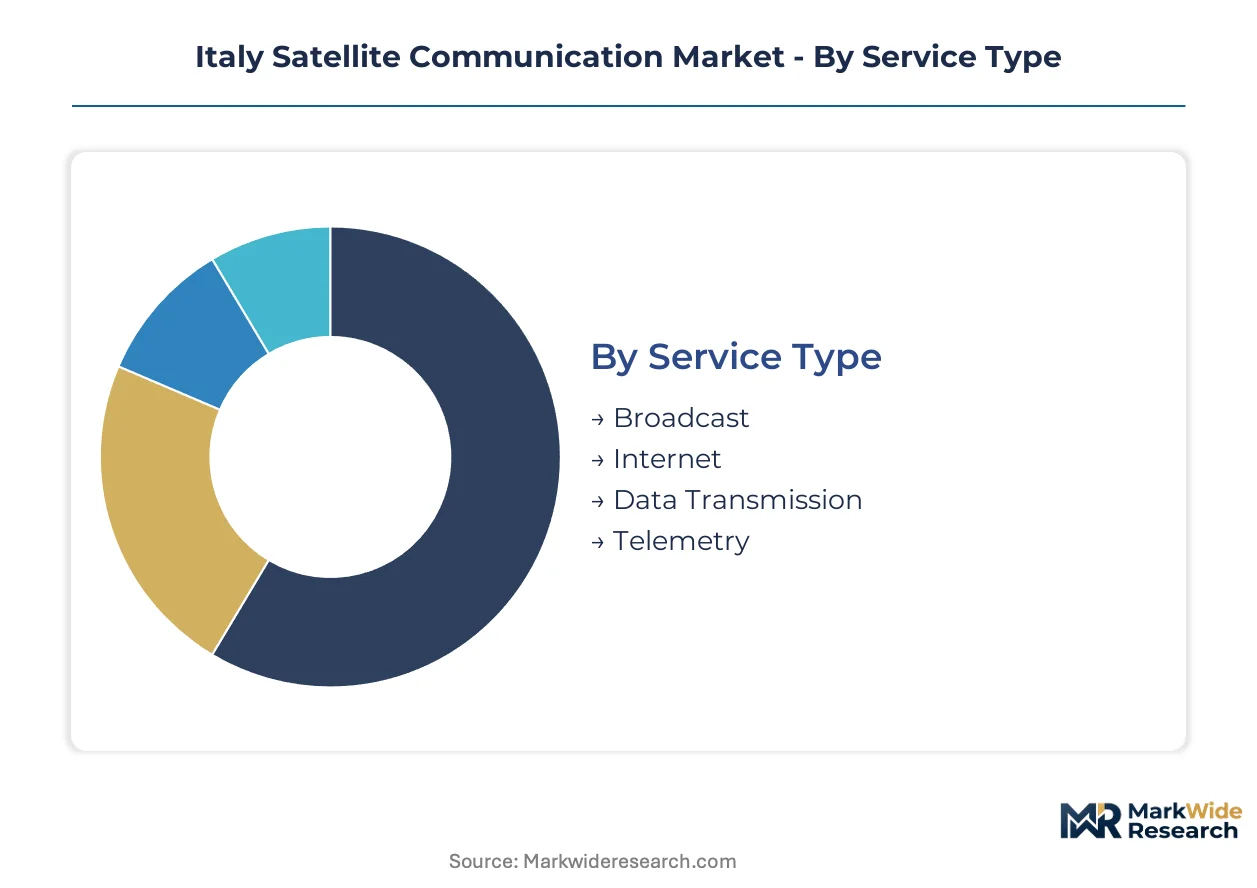
Segmentation in Italy's satellite communication market reflects divergent procurement priorities across defense, civil government, and commercial verticals. Each dimension captures distinct buyer requirements that shape payload specifications, ground segment investments, and service pricing architectures.
Service Type:
Government and commercial buyers differentiate primarily by latency tolerance, bandwidth guarantees, and security classification requirements.
- Broadcast:Geostationary transponders deliver television and radio distribution to Italian terrestrial headends. Rome's aerospace corridor concentrates demand from RAI and Mediaset for DTH platform capacity.
- Internet:Broadband satellite services address connectivity gaps in Sicily, Calabria, and Alpine regions where fiber deployment remains uneconomical. HTS spot-beam architectures are displacing legacy Ku-band widebeam offerings.
- Data Transmission:Maritime and aero backhaul contracts dominate procurement from Viasat Group SpA and ground segment integrators. Mediterranean shipping lanes and Italian naval platforms drive transponder leasing volumes.
- Telemetry:Command and control links for ASI missions and commercial constellations require ultra-reliable low-data-rate channels. Sitael SpA's Mola di Bari facility specializes in compact telemetry terminals for small-satellite operators.
Broadcast leads volumes today; Internet is gaining share fastest.
Technology:
Orbital altitude selection determines capital intensity, coverage patterns, and terminal economics for Italian operators.
- Geostationary:Fixed orbital slots at 36,000km altitude enable persistent coverage of Italian territory with single-satellite architectures. Thales Alenia Space leverages its Cannes-Rome pipeline for dual-use geostationary programs serving both ASI and defense clients.
- Low Earth Orbit:Constellations below 2,000km altitude deliver sub-50ms latency for IoT and defense applications. Italian investment concentrates in agricultural monitoring and logistics tracking for SME verticals previously underserved by satellite.
- Medium Earth Orbit:Intermediate altitudes balance coverage footprint with latency performance. Limited Italian procurement to date reflects constellation operator focus on polar or geostationary alternatives.
- HTS:High-throughput satellite architectures multiply capacity per orbital slot through frequency reuse. Ground segment modernization across Turin's satellite manufacturing cluster supports HTS terminal production for European export markets.
Geostationary retains the largest revenue pool; Low Earth Orbit shows steepest expansion trajectory.
End User:
Procurement authority and certification requirements fragment the buyer landscape across civilian and military hierarchies.
- Government:ASI and civil ministries fund sovereign constellation capabilities and scientific missions. EU Space Programme disbursements through EUSPA accelerate ground infrastructure tenders.
- Defense:NATO-aligned procurement follows national defense guidelines and STANAG interoperability standards. Naval bandwidth expansion for maritime platforms pulls dedicated military transponder capacity into geostationary slots.
- Telecommunications:Mobile network operators lease satellite backhaul for rural 5G base stations. Telecom Italia and Wind Tre represent anchor tenants for HTS capacity over Italian territory.
- Broadcasting:Content distributors require guaranteed availability for live event transmission. Premium sports and news contracts command highest transponder pricing tiers.
Defense procurement is climbing the fastest; Telecommunications maintains the largest contract value.
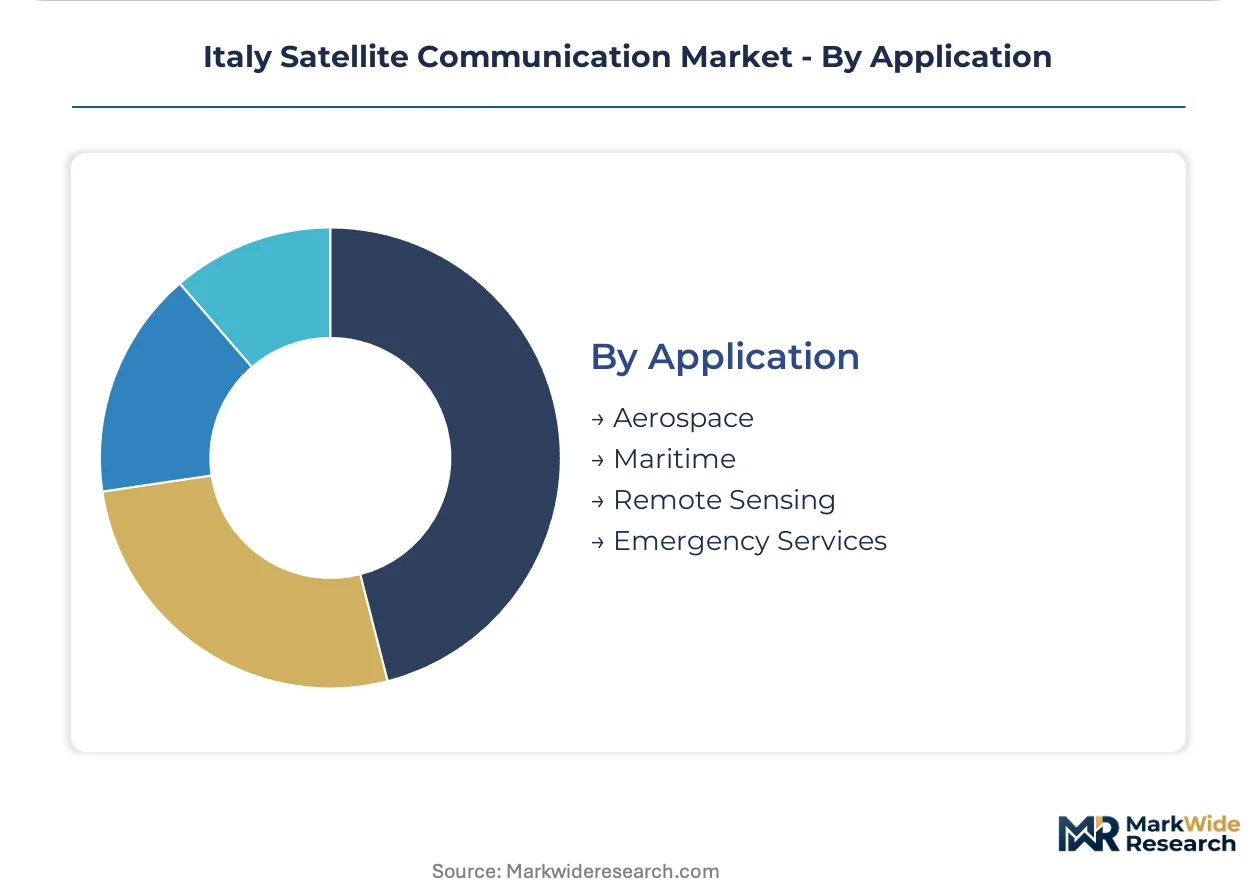
Application:
Environmental conditions and mobility requirements dictate terminal specifications and service level agreements.
- Aerospace:In-flight connectivity for Alitalia and business aviation operators demands low-profile antenna solutions. Italian aero terminal manufacturers compete on weight and drag reduction.
- Maritime:Merchant vessels and naval platforms require stabilized antennas for continuous connectivity at sea. Mediterranean trunk routes face erosion from submarine cable expansions.
- Remote Sensing:Earth observation data downlink drives Ka-band ground segment investment. ASI's COSMO-SkyMed constellation generates sustained demand for high-rate telemetry.
- Emergency Services:Disaster response and civil protection require rapidly deployable satellite terminals. Sicily and Calabria underdeveloped teleport infrastructure offers greenfield gateway consolidation opportunities.
Maritime leads current revenue; Emergency Services is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rome's aerospace corridor concentrates Italy's satellite communication demand through ASI headquarters, defense procurement offices, and broadcast media clusters. Turin's satellite manufacturing ecosystem anchors payload production for European export markets. Southern Italy's underdeveloped teleport infrastructure presents greenfield investment opportunities.
Lombardy
Telecom Italia's Milan operations drive HTS capacity leasing for rural 5G backhaul across Alpine valleys. The region's financial services sector generates demand for low-latency satellite links to trading infrastructure. Milan-based integrators coordinate ground segment deployments for maritime customers operating in Mediterranean shipping lanes.
Piedmont
Turin's satellite manufacturing cluster specializes in geostationary payload production and RF component fabrication. Thales Alenia Space leverages its Cannes-Rome engineering pipeline from facilities in the metropolitan area. Local technical universities feed specialized microwave engineering talent into Ka and Q/V band system development.
Lazio
Rome hosts ASI headquarters and coordinates national space strategy implementation through EUSPA-aligned programs. Defense procurement offices in the capital region pull dedicated military transponder capacity for naval bandwidth expansion. Broadcast distributors RAI and Mediaset anchor DTH platform demand from geostationary slots.
Apulia
Sitael SpA's Mola di Bari facility anchors domestic small-satellite production for commercial constellation operators. The region's underdeveloped ground segment infrastructure offers teleport consolidation opportunities for southern Mediterranean coverage. Agricultural IoT monitoring applications remain underpenetrated among Apulian SME verticals.
Sicily
Strategic geographic positioning enables satellite gateway operations covering North African and Middle Eastern orbital footprints. Palermo and Catania ports generate maritime connectivity demand for merchant vessel fleets. Civil protection agencies require rapidly deployable emergency satellite terminals for disaster response coordination.
Italy Satellite Communication Market Competitive Landscape
Global majors compete with regional champions across payload manufacturing and ground segment integration, creating a tiered structure where scale-driven primes coexist with specialized subsystem providers. The vendor base clusters around three strategic archetypes: geostationary platform integrators with dual-use capabilities, small-satellite specialists serving constellation operators, and ground terminal manufacturers competing on maritime and aero applications. Dominant competitive moves include strategic partnerships for spectrum access and portfolio diversification into software-defined payload architectures.
Within the prime contractor tier, Thales Alenia Space and Airbus Italia SpA exemplify geostationary platform integration with defense-civilian crossover capabilities. Sitael SpA occupies a position among small-satellite specialists focused on compact platform production for emerging constellation operators.
| Leading Market Players |
|---|
| Sitael SpA |
| Gomedia Satcom |
| Thales Alenia Space |
| Airbus Italia SpA |
| Leaf Space |
| Viasat Group SpA |
| Antech Space |
| Temix Communications |
| Telecom Italia (TIM) |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride substrate pricing indices cascade through Italian payload manufacturing, compressing margins for GaN-on-SiC amplifier suppliers while elevating terminal costs for ground segment integrators serving defense and maritime verticals.
Pricing Analysis
Input-cost pass-through from US and Japanese wafer suppliers shapes three-tier pricing structure across premium, standard, and economy levels for satellite transponder capacity. Price differentiation hinges on NATO STANAG certification grade and volume scale of constellation commitments. Pricing pressure stems from launch cost rigidity constraining small-satellite operator procurement budgets. Commercial broadcasting clients exhibit highest price sensitivity, while defense buyers prioritize security classification over unit cost.
Supply Chain Analysis
Freight costs for oversized satellite bus components from Cannes to Rome engineering facilities add margin pressure to geostationary platform integration. Supply concentrates in the United States, Japan, and France for critical RF components and payload subsystems. Raw material dependencies center on GaN wafers, high-purity aluminum for thermal management, and specialized composite materials for antenna reflectors. Single-source vulnerability from concentrated GaN substrate suppliers creates procurement risk. Distribution runs through prime contractor-led integration channels with ASI certification gates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's satellite communication market represents a late-cycle quality story as defense procurement shifts toward software-defined frequency agility and sovereign constellation capabilities demand premium payload specifications.
For Market Incumbents: Deepen backward integration into GaN-on-SiC amplifier design to offset substrate supply concentration from US and Japanese suppliers. Secure captive capacity through long-term offtake agreements with wafer foundries. Expand Turin manufacturing cluster capacity to parallel-track civil and military qualification streams against compressed NATO STANAG vendor cycles. For New Entrants and Emerging Players: Launch via ground-terminal integration partnerships targeting underpenetrated agricultural IoT monitoring in Apulian SME verticals. White-space opportunities concentrate in southern Italy teleport infrastructure and compact telemetry terminals for commercial constellation operators. Prioritize rapid ASI certification pathways to compress development cycles against incumbent qualification advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with small-satellite specialists possessing sovereign constellation relationships and software-defined payload architectures. Long-term viability favors dual-use technology convergence enabling civilian broadband pivots to defense applications. Monitor ITU Q/V band licensing momentum as inflection indicator for terminal manufacturer refresh cycles and service profitability expansion.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Amplifier Development | Thales Alenia Space and Sitael SpA compete on solid-state payload mass reduction for geostationary programs. |
| Southern Italy Teleport Consolidation | Greenfield gateway investments in Sicily and Calabria capture Mediterranean and North African orbital coverage. |
| Dual-Use Certification Parallel-Tracking | Turin manufacturers restructure engineering teams to accelerate NATO STANAG and ASI qualification timelines. |
| IoT Constellation Service Launch | Low Earth Orbit platforms target agricultural monitoring gaps in Alpine and southern Italian regions. |
| EU Space Programme Alignment | EUSPA disbursements mandate ground segment interoperability standards across member state infrastructure tenders. |
Research Methodology
Bottom-up defense and commercial bandwidth demand modeling reconciled against top-down payload manufacturing capacity tracking forms the analytical core. Primary interviews with ASI program directors, Thales Alenia Space engineering leads, naval procurement officers, and teleport operators combined with secondary validation from EUSPA disbursement records, ITU spectrum allocation filings, and NATO STANAG protocol documentation. Triangulation against customs data for GaN substrate imports and Arianespace launch manifests anchored supply-side estimates.
Input-output matrices mapped transponder capacity deployment against ground segment modernization spend across the projection horizon. Segmentation dimensions modeled include orbital altitude, service type, end-user procurement authority, and regional infrastructure development stage. CAGRs derived from capacity expansion trajectories and pricing elasticity assumptions for defense versus commercial verticals. Forecast inputs incorporated EU Space Programme funding schedules and Italian national space strategy implementation timelines.
Several conditions sit outside the modeled scope, including unannounced constellation operator bankruptcies, ITU spectrum reallocation decisions, and breakthrough optical inter-satellite link technologies. Forecasts reflect assumptions about sustained defense procurement growth and EUSPA funding continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Bus Market
Satellite
North America Remote Sensing Satellites Market
Satellite
Europe Satellite Connectivity Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Reconnaissance Satellite Market
Satellite
LEO Satellite Constellation Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Global Dish Antennas Market
Satellite
Optical Satellite Communication Market
Satellite
High-Throughput Satellite Market
Satellite
4K Satellite Broadcasting Market
Satellite
France Satellite Imagery Services Market
Satellite
Satellite Manufacturing Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Satellite Broadband Market