
 Germany Satellite Connectivity Market | 2026-2036
Germany Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Satellite Connectivity Market Insights
Government procurement channels is tilting toward sovereign satellite networks as Berlin prioritizes strategic autonomy in space infrastructure. Airbus Defence and Space GmbH anchors German manufacturing capabilities through its Friedrichshafen and Bremen facilities. Spaceopal GmbH operates the Galileo ground control segment, leveraging its unique position within European navigation programs. Thales Group competes across military-grade encryption and waveform technologies for Bundeswehr satellite terminals.
Germany satellite connectivity encompasses orbital and ground-based systems that relay data, voice, and video across LEO, MEO, and GEO constellations using Ku-, Ka-, and X-band frequencies for commercial and defense applications. Broadband services command the largest revenue pool among service types due to enterprise and consumer backhaul demand, while IoT connectivity represents the fastest-expanding segment driven by agricultural and utility sensor networks. GEO technology maintains mature, high-margin broadcast and government contracts, though hybrid systems integrating LEO constellations are capturing new defense and maritime accounts requiring low-latency performance.
The Bundesnetzagentur governs spectrum allocation and orbital slot coordination under EU regulatory frameworks, while the EU Space Programme and IRIS² initiative mandate interoperable encryption and frequency standards that reshape vendor qualification requirements. Germany's national space strategy and alignment with ESA procurement rules further condition market access for non-European equipment suppliers. Stakeholders must track IRIS² deployment timelines and Bundeswehr satellite service tenders to align capability roadmaps with sovereign demand cycles.
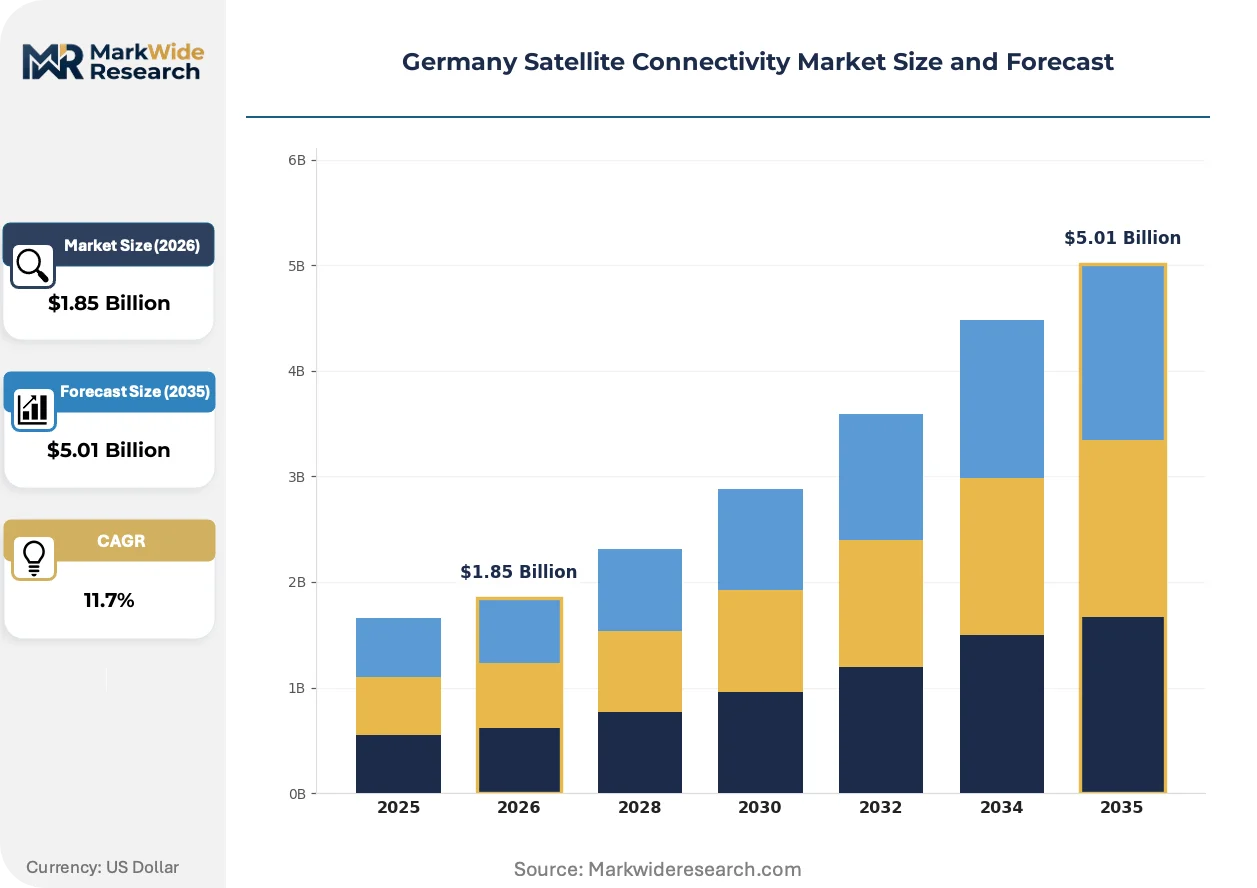
Market Dynamics
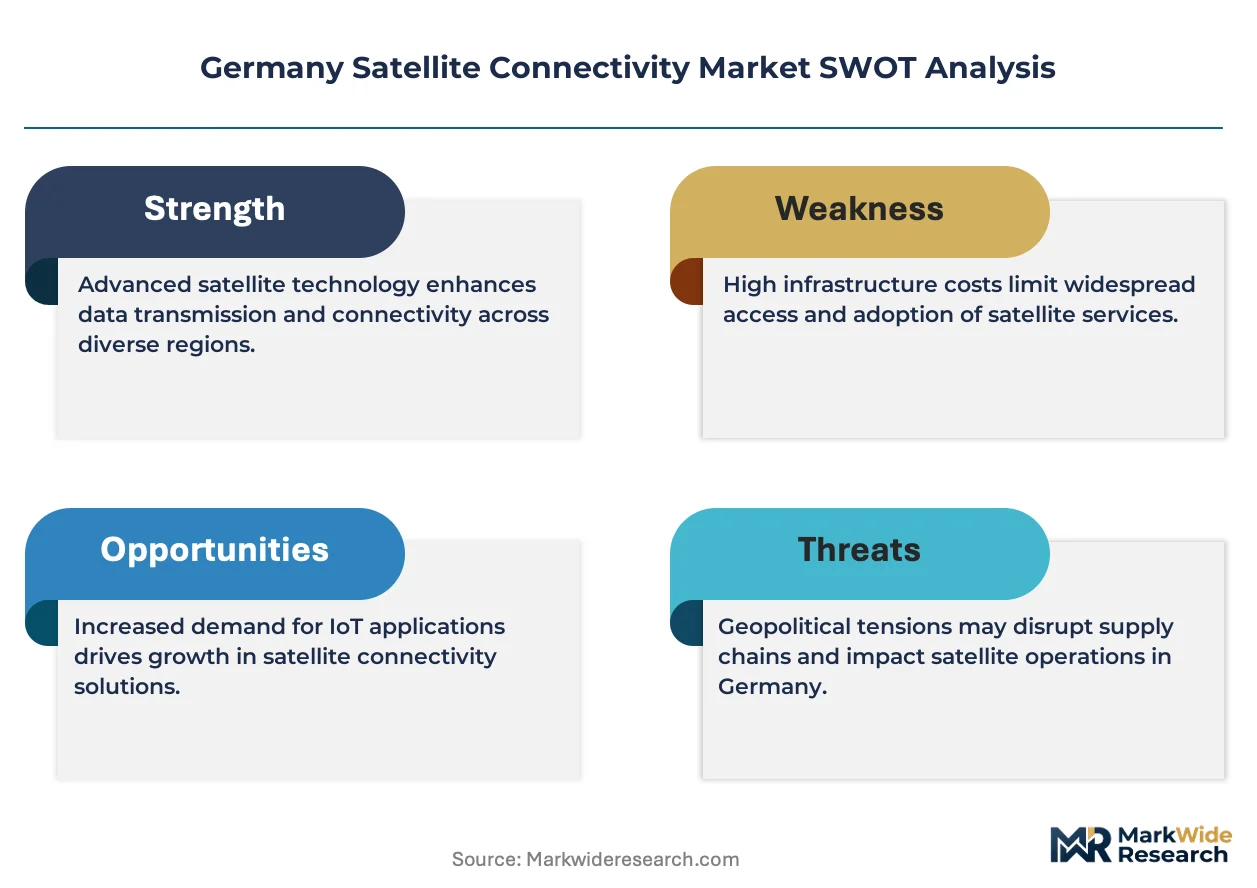
Bundeswehr procurement cycles and IRIS² sovereign infrastructure mandates are compressing vendor qualification timelines while fragmenting demand across defense, enterprise, and agricultural verticals.
Growth Catalysts
- EU Space Programme mandates:IRIS² constellation deployment accelerates sovereign ground segment procurement across German federal agencies. The framework prioritizes European vendor participation in navigation and broadband services.
- Bavaria aerospace cluster concentration:Munich-Ottobrunn engineering density enables rapid prototyping of Ka-band terminals for maritime and aeronautical applications. Proximity to ESA establishments reduces integration cycle times.
- Precision agriculture sensor networks:IoT backhaul demand from Rhineland-Palatinate vineyard monitoring and Brandenburg grain operations expands narrowband satellite subscriptions. Utility operators deploy satellite-linked smart grid infrastructure.
Market Restraints
- Launch capacity bottlenecks:European small-lift vehicle availability constrains LEO constellation refresh rates for German operators. Dependence on French Guiana and emerging German launch sites creates deployment uncertainty.
- Spectrum coordination complexity:Bundesnetzagentur orbital slot allocation procedures extend licensing timelines for Ku-band broadcast services. EU-wide harmonization delays compound national approval backlogs.
- Terrestrial fiber substitution:Deutsche Telekom rural broadband expansion threatens satellite consumer backhaul economics in Saxony and Lower Saxony regions. Fixed wireless access erodes price premiums.
Strategic Opportunities
- Defense encryption standards convergence:Bundeswehr quantum-resistant waveform specifications create first-mover advantage for domestic terminal manufacturers. NATO interoperability requirements extend addressable market.
- North Sea offshore energy:Unmanned platform connectivity and crew transfer vessel tracking demand hybrid GEO-LEO service bundles. Wind farm operators seek guaranteed latency for turbine control systems.
- ESA technology transfer programs:Copernicus data downstream commercialization incentives support Earth observation analytics startups in Bremen and Darmstadt. Public-private partnerships reduce ground infrastructure capex burdens.
Industry Challenges
- RF engineering talent scarcity:Microwave and antenna design expertise concentrates among aging specialists in Friedrichshafen and Munich. University pipeline output lags constellation deployment schedules.
- ITAR-free component sourcing:Export-controlled semiconductor procurement complicates dual-use terminal production for Middle East and Asia-Pacific defense customers. Supply chain reconfiguration absorbs engineering resources.
- Legacy GEO integration:Bundeswehr existing X-band infrastructure requires gateway interoperability with emerging LEO constellations. Multi-orbit service orchestration demands software-defined radio investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Satellite Connectivity Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadband, IoT Connectivity, Government Services, Maritime Communication End User: Aerospace, Telecom Operators, Defense, Energy Sector Technology: LEO, MEO, GEO, Hybrid Systems Application: Emergency Services, Remote Monitoring, Satellite TV, Military Operations |
| Companies Covered | Spaceopal GmbH, Airbus Defence and Space GmbH, SES S.A., Inmarsat Global Limited, Deutsche Telekom, Viasat Inc., Eutelsat Communications SA, Thales Group, Intelsat, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Satellite Connectivity Market Trends and Innovations
Software-defined payload architectures and quantum-secure communication protocols are reconfiguring how German operators provision bandwidth across civilian and military applications.
Digital transparent processors aboard next-generation GEO satellites enable dynamic beam-forming and frequency reuse across coverage footprints. German maritime operators and government fleets are adopting these payloads for flexible capacity allocation. This capability is virtualizing traditional fixed-transponder lease structures into on-demand service models.
The EU AI Act and Cybersecurity Act impose conformity assessment requirements on satellite ground systems processing sensitive data. German terminal manufacturers must embed certified encryption modules and audit logging capabilities. Defense procurement specifications now mandate compliance with these frameworks, elevating vendor qualification costs.
Enterprise buyers are unbundling managed services from hardware procurement, favoring satellite-as-a-service subscriptions with guaranteed SLA tiers. Systems integrators in Baden-Württemberg and North Rhine-Westphalia are displacing direct operator relationships. This pattern concentrates in automotive and logistics verticals seeking operational expenditure predictability.
Germany Satellite Connectivity Market Segmentation
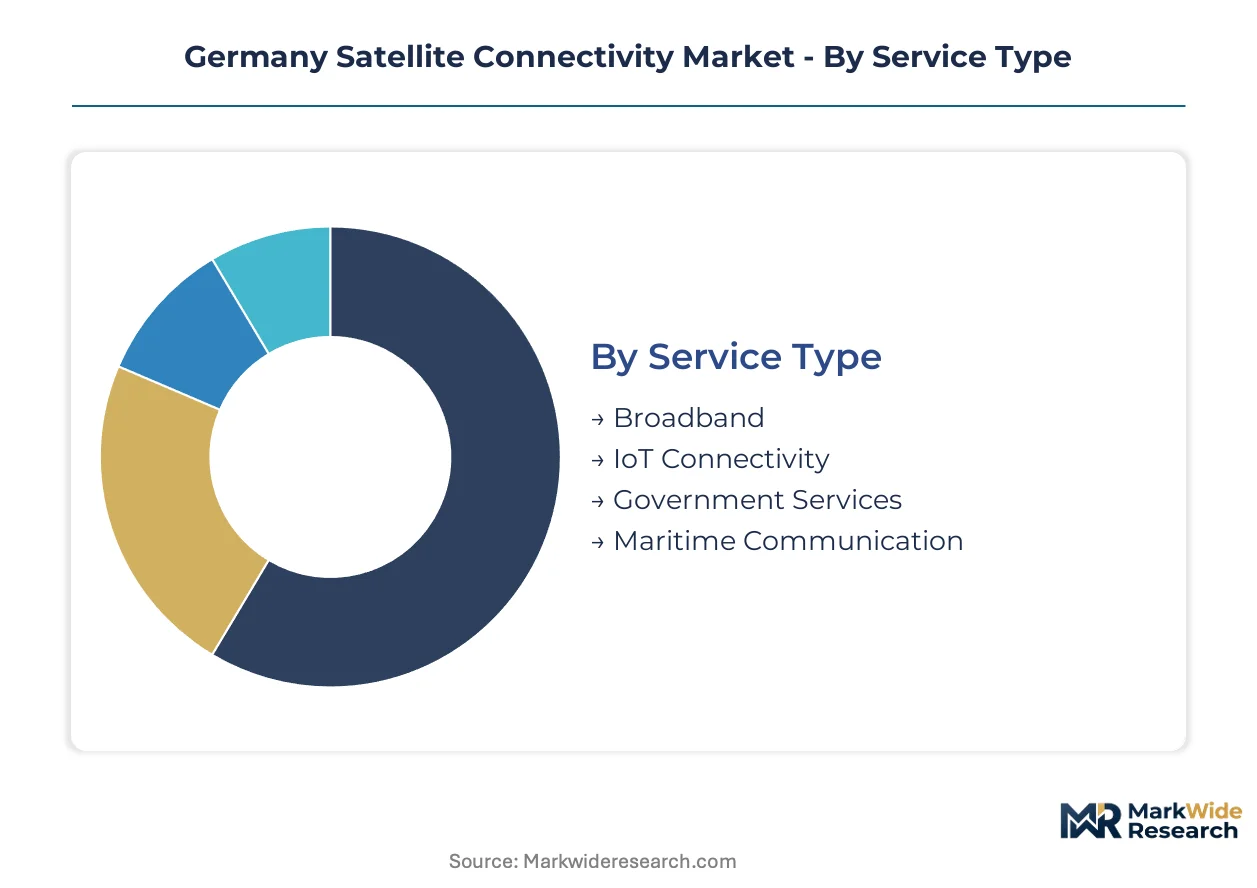
German satellite connectivity procurement fragments across sovereign defense mandates, commercial broadband economics, and precision agriculture sensor networks. Understanding segment turnover rates reveals where vendor qualification investments yield fastest returns versus long-cycle infrastructure commitments.
Service Type:
Broadband services refresh on 3-5 year enterprise contract cycles, while IoT connectivity turns over annually as agricultural operators trial narrowband subscriptions. Government services extend across decade-long framework agreements tied to EU Space Programme milestones.
- Broadband:High-throughput Ku- and Ka-band capacity serves enterprise backhaul and maritime vessel connectivity. Demand concentrates in Bavaria's automotive manufacturing corridors and North Sea offshore logistics corridors. Deutsche Telekom fiber gaps in rural Saxony sustain price premiums for satellite alternatives.
- IoT Connectivity:Narrowband protocols link agricultural sensors in Brandenburg grain belts and Rhineland-Palatinate vineyard telemetry. Utility smart grid deployments in Baden-Württemberg drive fastest subscription growth among service types.
- Government Services:Bundeswehr X-band and future IRIS² procurement channels require sovereign ground segment compliance.
- Maritime Communication:Crew welfare bandwidth and vessel tracking dominate commercial shipping accounts from Hamburg and Bremen ports.
Broadband dominates installed base. IoT connectivity is where expansion concentrates.
End User:
Defense procurement absorbs highest per-site equipment values, while telecom operators achieve scale through wholesale capacity aggregation. Energy sector demand is accelerating fastest as offshore wind buildouts multiply.
- Defense:Bundeswehr satellite terminal specifications mandate quantum-resistant encryption and NATO interoperability. Friedrichshafen suppliers anchor domestic manufacturing for classified waveform requirements.
- Energy Sector:Unmanned North Sea platforms and crew transfer vessel fleets require guaranteed latency for turbine control. Hybrid GEO-LEO bundles capture premium positioning against pure-play alternatives.
- Aerospace:In-flight connectivity and ground segment integration support Munich-Ottobrunn engineering clusters.
- Telecom Operators:Wholesale capacity resale and rural backhaul extension shape procurement patterns.
Defense commands highest unit economics. Energy sector is climbing the fastest.
Technology:
GEO assets depreciate over 15-year orbital lifespans, while LEO constellation refresh cycles compress to 5-7 years. Hybrid system adoption is expanding most quickly as multi-orbit orchestration matures.
- GEO:Mature broadcast and government contracts sustain high-margin transponder leases. Digital transparent processors enable dynamic beam-forming for German maritime operators.
- Hybrid Systems:Software-defined radios integrate legacy X-band infrastructure with emerging LEO constellations. Bundeswehr gateway interoperability requirements drive defense procurement concentration.
- LEO:Low-latency performance targets financial trading and autonomous vehicle telemetry applications.
- MEO:Intermediate altitude constellations balance coverage footprint with propagation delay.
GEO maintains revenue concentration. Hybrid systems are gaining share fastest.
Application:
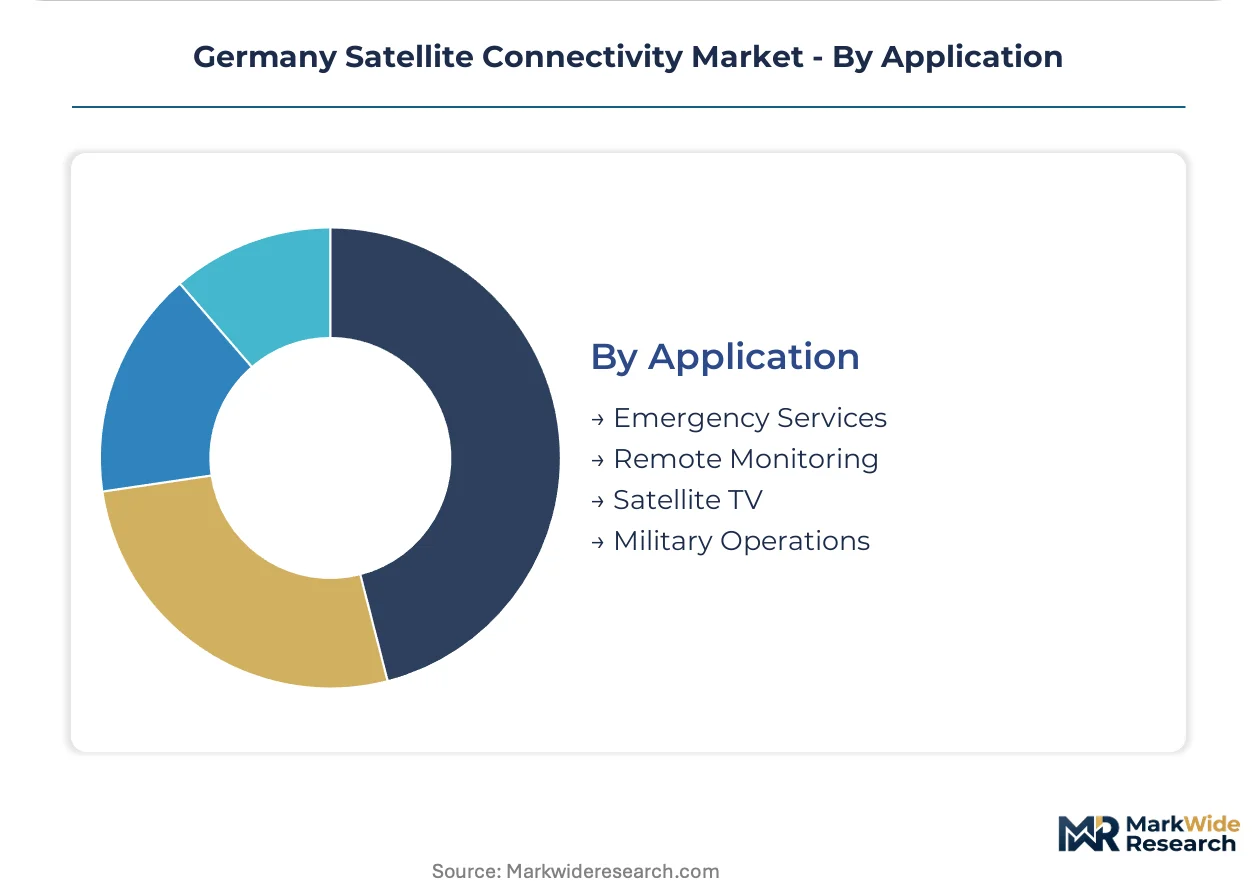
Military operations demand longest development timelines for certified terminals, while remote monitoring scales through standardized sensor platforms. Emergency services procurement is accelerating with civil defense modernization.
- Military Operations:Secure waveform specifications and NATO interoperability testing extend vendor qualification cycles. Thales Group and domestic manufacturers compete for Bundeswehr satellite terminal awards.
- Remote Monitoring:Agricultural and utility sensor networks deploy through standardized narrowband subscriptions. Copernicus data downstream commercialization supports Earth observation analytics startups.
- Emergency Services:Civil defense satellite communication modernization prioritizes resilient backup for terrestrial network failures.
- Satellite TV:Direct-to-home broadcast maintains stable subscriber bases in rural German regions.
Military operations anchor premium pricing tiers. Remote monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria commands premium pricing for sovereign ground segment manufacturing, while North Rhine-Westphalia competes on wholesale capacity aggregation scale. This asymmetry shapes procurement patterns across German federal states.
Bavaria
Bundeswehr satellite terminal demand and IRIS² ground control procurement concentrate procurement power in Munich-Ottobrunn. The Bundesnetzagentur coordinates spectrum allocation with ESA establishments in Oberpfaffenhofen. Friedrichshafen suppliers anchor quantum-resistant waveform manufacturing for classified defense applications.
North Rhine-Westphalia
Telecom operator wholesale backhaul and enterprise managed services drive volume-based competition. Deutsche Telekom rural broadband gaps sustain satellite price premiums in Eifel and Sauerland regions. Cologne-Düsseldorf logistics corridors generate maritime connectivity demand through Ruhr industrial ports.
Baden-Württemberg
Automotive telemetry and precision agriculture sensor networks expand IoT connectivity subscriptions. The EU AI Act conformity requirements reshape ground system procurement for Stuttgart manufacturing clusters. Darmstadt-Griesheim Earth observation analytics startups commercialize Copernicus downstream data.
Lower Saxony
North Sea offshore wind farm connectivity and unmanned platform operations demand hybrid GEO-LEO service bundles. Cuxhaven and Bremerhaven ports anchor maritime crew welfare bandwidth procurement. Bundeswehr naval base requirements at Wilhelmshaven extend defense-grade terminal demand.
Hamburg
Commercial shipping fleet management and vessel tracking concentrate maritime communication service demand. The port authority's smart logistics infrastructure integrates satellite-linked container monitoring. Airbus Defence and Space GmbH maintains engineering presence for aeronautical terminal development.
Germany Satellite Connectivity Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying RF modules and encryption chipsets. The vendor base concentrates among European defense conglomerates and specialized ground segment operators. Two archetypes dominate: sovereign infrastructure champions serving IRIS² and Bundeswehr mandates, and commercial service aggregators targeting enterprise backhaul. Competitive moves center on ESA technology transfer access and ITAR-free supply chain certification.
Within the sovereign infrastructure tier, Airbus Defence and Space GmbH and Spaceopal GmbH occupy anchor positions. Airbus Defence and Space GmbH represents vertically integrated manufacturing capabilities spanning Friedrichshafen and Bremen facilities. Spaceopal GmbH exemplifies specialized ground segment operation through its Galileo control segment mandate. Thales Group sits within the defense electronics archetype, competing across encryption and waveform technologies without claiming specific market share positions.
| Leading Market Players |
|---|
| Spaceopal GmbH |
| Airbus Defence and Space GmbH |
| SES S.A. |
| Inmarsat Global Limited |
| Deutsche Telekom |
| Viasat Inc. |
| Eutelsat Communications SA |
| Thales Group |
| Intelsat |
| Others |
Pricing and Supply Chain Analysis
ITAR-free semiconductor sourcing constraints determine both the premium commanded by sovereign-certified terminals and the geographic reconfiguration of German manufacturing networks. Single-source dependency on export-controlled RF components compresses margins for dual-use equipment while elevating pricing power for domestic suppliers with Bundesnetzagentur qualification.
Pricing Analysis
Configured-to-order pricing for quantum-resistant Bundeswehr terminals spreads 40-60% above standard Ku-band maritime units, with differentiation anchored in NATO interoperability certification and embedded encryption module grade. Three-tier pricing structure across premium sovereign-grade, standard enterprise, and economy consumer backhaul segments governs the market. Cost compression in consumer broadband tiers intensifies as Deutsche Telekom fiber expansion erodes satellite price premiums in Saxony and Lower Saxony. Telecom operators exhibit highest price sensitivity through wholesale capacity aggregation, while defense procurement absorbs premium positioning with decade-long framework agreements.
Supply Chain Analysis
Contract manufacturing for satellite terminals concentrates with Thales Alenia Space facilities in France and Italy, alongside specialized German EMS providers in Friedrichshafen and Munich engineering clusters. Geographic supply concentration spans Taiwan for RF semiconductor foundry capacity, the United States for ITAR-controlled encryption chipsets, and Germany for antenna subsystem integration. Raw material dependencies include gallium nitride substrates for high-power amplifiers, specialized aluminum alloys for reflector dishes, and radiation-hardened semiconductors for space-grade applications. Single-source vulnerability on export-controlled components threatens production continuity for Middle East defense contracts. Distribution runs through ESA-qualified systems integrators and direct Bundeswehr procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany satellite connectivity is approaching a platform-economics inflection as IRIS² sovereign infrastructure mandates force interoperability standardization across previously siloed defense and commercial ground segments.
For Market Incumbents: Insulate terminal manufacturing margins through captive supply of ITAR-free encryption modules and backward integration into antenna subsystem production. Prioritize Bundesnetzagentur qualification maintenance against emerging Polish and Italian competitors seeking IRIS² ground segment share. Capacity addition in Bavaria aerospace clusters preserves proximity advantage for rapid prototyping cycles. For New Entrants and Emerging Players: Brandenburg precision agriculture sensor networks represent the most penetrable white-space target, with narrowband IoT subscriptions turning annually and low incumbent loyalty. Target utility smart grid deployments in Baden-Württemberg through satellite-as-a-service subscription models that displace direct operator relationships. Partner with Stuttgart automotive clusters for telemetry integration to secure anchor demand. For Investors and Strategic Acquirers: The market sits at a sovereign infrastructure deployment phase that favors specialized ground segment operators with ESA technology transfer access over pure-play satellite operators. Long-term viability over the next decade hinges on IRIS² execution timelines and Bundeswehr quantum-resistant waveform adoption curves. Acquisition targets should demonstrate ITAR-free supply chain certification and Galileo ground control segment operational experience. Watch IRIS² procurement tender announcements as the critical inflection signal for vendor qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR-Free Supply Chain Certification | Eliminates export control barriers for Middle East and Asia-Pacific defense contracts under Bundesnetzagentur oversight. |
| Quantum-Resistant Waveform Development | Captures first-mover advantage in Bundeswehr satellite terminal specifications mandating NATO interoperability. |
| Hybrid GEO-LEO Service Bundling | Addresses North Sea offshore wind farm latency requirements through software-defined radio orchestration. |
| ESA Technology Transfer Partnership | Reduces ground infrastructure capex burdens for Copernicus downstream commercialization in Bremen and Darmstadt. |
| RF Engineering Talent Pipeline Investment | Mitigates microwave and antenna design scarcity in Friedrichshafen and Munich through university collaboration. |
Research Methodology
A spread of perspectives from satellite terminal procurement officers at Bundeswehr, ground segment engineering directors at Airbus Defence and Space GmbH, spectrum allocation specialists at Bundesnetzagentur, and maritime fleet managers at Hamburg port authorities converged on the working assumptions. Primary interview insights combined with secondary validation from ESA procurement databases, EU Space Programme implementation reports, and customs records of RF component imports. Bottom-up capacity assessments across Bavaria and North Rhine-Westphalia manufacturing clusters triangulated against top-down demand modeling from IRIS² deployment schedules.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, end user vertical, orbital technology tier, and regional federal state cluster. CAGRs derived from equipment replacement cycles, subscription renewal rates, and sovereign procurement milestone timing. Industry-specific forecast inputs included LEO constellation refresh schedules and Bundeswehr satellite service tender pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by French and Italian ground segment specialists would shift outcomes beyond modeled ranges. Quarterly review of IRIS² procurement tender releases and Bundesnetzagentur spectrum allocation decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Small Satellite Market
Satellite
North America Satellite Launch Vehicle Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Russia Satellite Imagery Services Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
ASEAN Satellite Communications Market
Satellite
Commercial LEO Satellite Market
Satellite
All-Electric Satellites Market
Satellite
Satellite Connectivity Market
Satellite
South Korea Satellite Communication Market
Satellite
Germany Satellite Communications Market
Satellite
M2M Satellite Communication Market
Satellite
Satellite Link Emulator Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Satellite Transponder Market
Satellite
Satellite Payload Market