

4K Satellite Broadcasting Market Size, Share, and Industry Trends Forecast 2026-2036
4K Satellite Broadcasting Market Insights
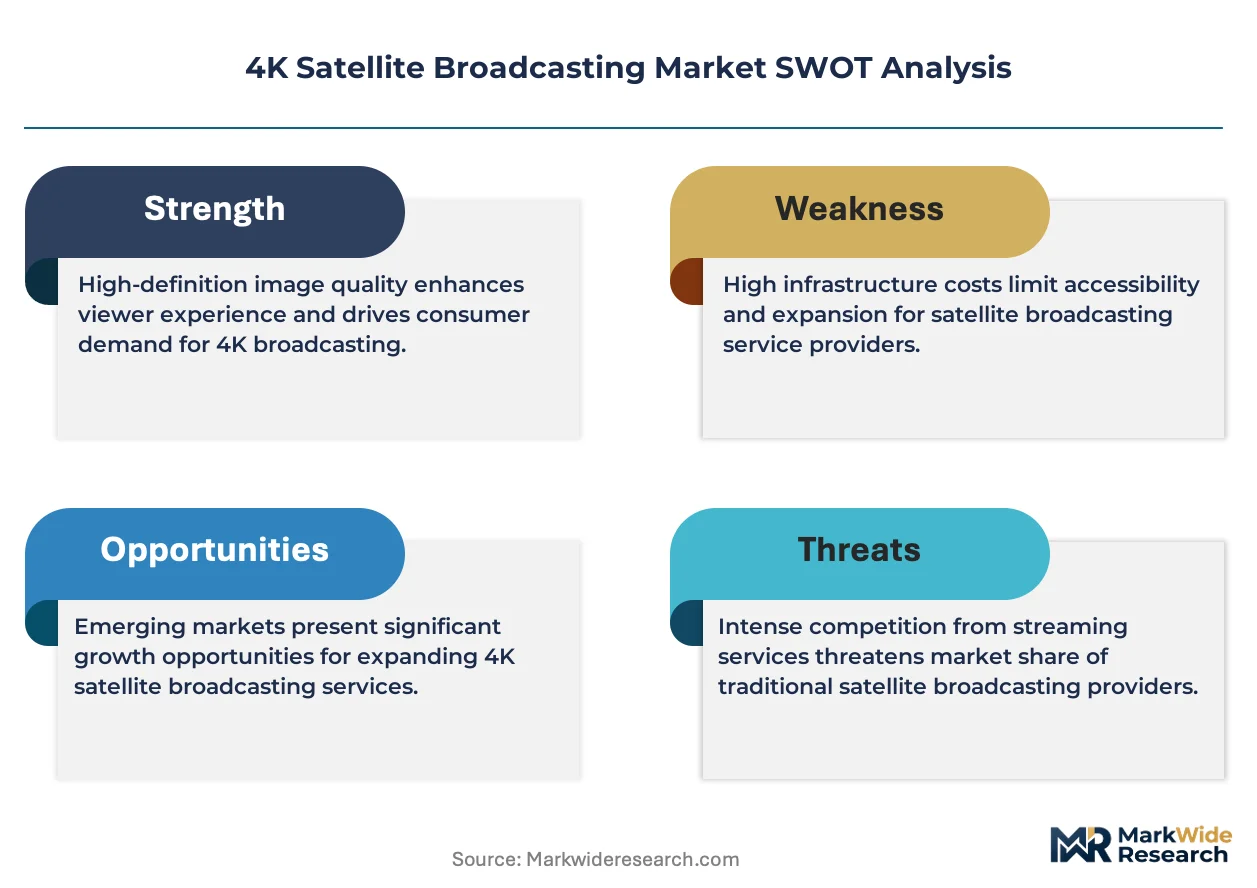
The capital-intensity divergence between fleet-owning satellite operators and terrestrial aggregators is rotating competitive advantage toward orbital infrastructure holders. SES leverages its MEO-GEO hybrid architecture to sustain capacity leadership across video neighborhoods. Eutelsat anchors European 4K distribution through prime orbital slots at 13°E and 19.2°E. Intelsat competes on global reach, dominating transatlantic and Latin American video trunking routes.
4K satellite broadcasting transmits ultra-high-definition video content via geostationary and medium-earth orbit satellites using Ku-band and Ka-band frequencies, employing HEVC encoding to compress 3840×2160 resolution signals within standard transponder bandwidth allocations. Its primary commercial purpose is delivering cinema-grade live and on-demand content to direct-to-home subscribers beyond fiber reach. The application dimension shows direct-to-home services commanding the largest revenue pool while IPTV services represent the fastest expansion vector as hybrid satellite-IP bundles gain traction. Among service types, subscription-based viewing occupies the mature profit core whereas live streaming of sports and cultural events captures emerging margin concentration.
The Federal Communications Commission shapes US market access through orbital slot coordination and spectrum auction frameworks, while the European Commission's F-Gas Regulation and REACH directives constrain ground station cooling system chemistries. Japan's Ministry of Internal Affairs and Communications enforces 4K broadcast readiness mandates through ISDB-S3 standards, compelling receiver ecosystem upgrades. Stakeholders must monitor convergence between satellite 4K delivery and 5G broadcast multicast architectures to preserve spectrum economics against terrestrial challengers.
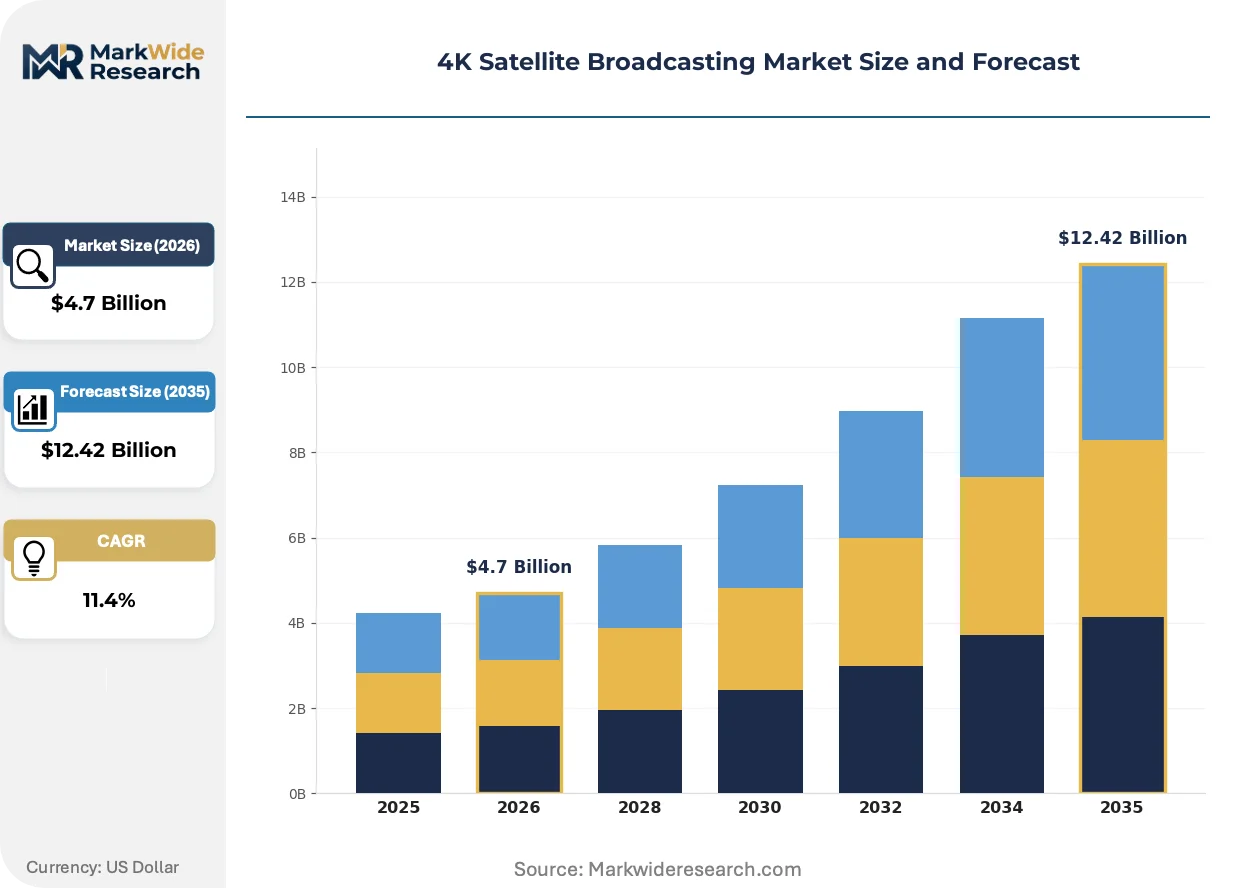
Market Dynamics
The transition from DVB-S2 to DVB-S2X modulation standards is compressing transponder costs per 4K channel by nearly thirty percent, forcing fleet operators to accelerate refresh cycles or surrender orbital capacity to more efficient competitors.
Growth Catalysts
- HEVC Compression Maturation:Advanced encoding protocols now squeeze 4K signals into legacy Ku-band transponders without bandwidth expansion. Broadcasters in India leverage this to avoid costly Ka-band migration.
- ISDB-S3 Mandates:Japan's Ministry of Internal Affairs and Communications compels receiver ecosystem upgrades through 4K broadcast readiness requirements, creating forced replacement demand across 50 million households.
- Sports Rights Inflation:Premium live content—particularly cricket in South Asia and football in Europe—drives subscriber willingness to pay for 4K tiers, justifying headend infrastructure investments.
Market Restraints
- Transponder Lease Volatility:Geostationary slot scarcity concentrates pricing power among three dominant fleet operators, exposing broadcasters to step-function cost increases upon contract renewal.
- F-Gas Regulatory Burden:The European Commission's F-Gas Regulation constrains ground station cooling system chemistries, forcing retrofit capital expenditure across legacy uplink facilities.
- Fiber-to-the-Home Substitution:Gigabit passive optical networks in urban South Korea and Japan erode satellite's historical advantage in ultra-high-definition delivery density.
Strategic Opportunities
- Rural Indian Penetration:Direct-to-home 4K adoption remains below fifteen percent in India's Hindi-speaking belt, presenting subscriber acquisition runway as set-top box subsidies expand.
- Hybrid Satellite-IP Bundles:Convergence between geostationary delivery and 5G multicast architectures enables seamless handoff between fixed and mobile screens, opening new service tiers.
- PLI Scheme Alignment:India's Production Linked Incentive scheme for electronics manufacturing reduces indigenous set-top box production costs, accelerating hardware ecosystem localization.
Industry Challenges
- HEVC Patent Licensing Complexity:Fragmented intellectual property pools across MPEG LA, HEVC Advance, and Velos Media create royalty stacking risk for decoder manufacturers.
- Legacy MPEG-2 Integration:Backward compatibility requirements with standard-definition headend infrastructure extend deployment timelines and inflate testing protocols.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4K Satellite Broadcasting Market Trends and Innovations
Broadcast infrastructure is bifurcating between fiber-rich urban zones where satellite competes on content exclusivity versus rural and maritime environments where orbital delivery retains structural cost advantage.
DVB-S2X modulation with 256APSK constellations is displacing legacy DVB-S2 across premium transponder leases. Pay-TV operators in Germany and the United Kingdom are migrating sports multiplexes to the new standard within eighteen-month windows. The efficiency gain is compressing effective cost per 4K channel below fiber equivalent rates in low-density geographies.
The European Commission's F-Gas Regulation tightens hydrofluorocarbon phase-down schedules for ground station cooling systems through 2030. Uplink facility operators face refrigerant retrofit mandates or equipment replacement. Facilities in Spain and Italy are responding with closed-loop liquid cooling architectures that eliminate fluorinated gas dependency entirely.
Subscription unbundling is fragmenting traditional package structures across Southeast Asian markets. Consumers in Indonesia and Vietnam increasingly purchase event-specific 4K access rather than monthly commitments. This compresses customer lifetime value metrics while expanding addressable audience for single-match or single-concert broadcasts.
4K Satellite Broadcasting Market Segmentation
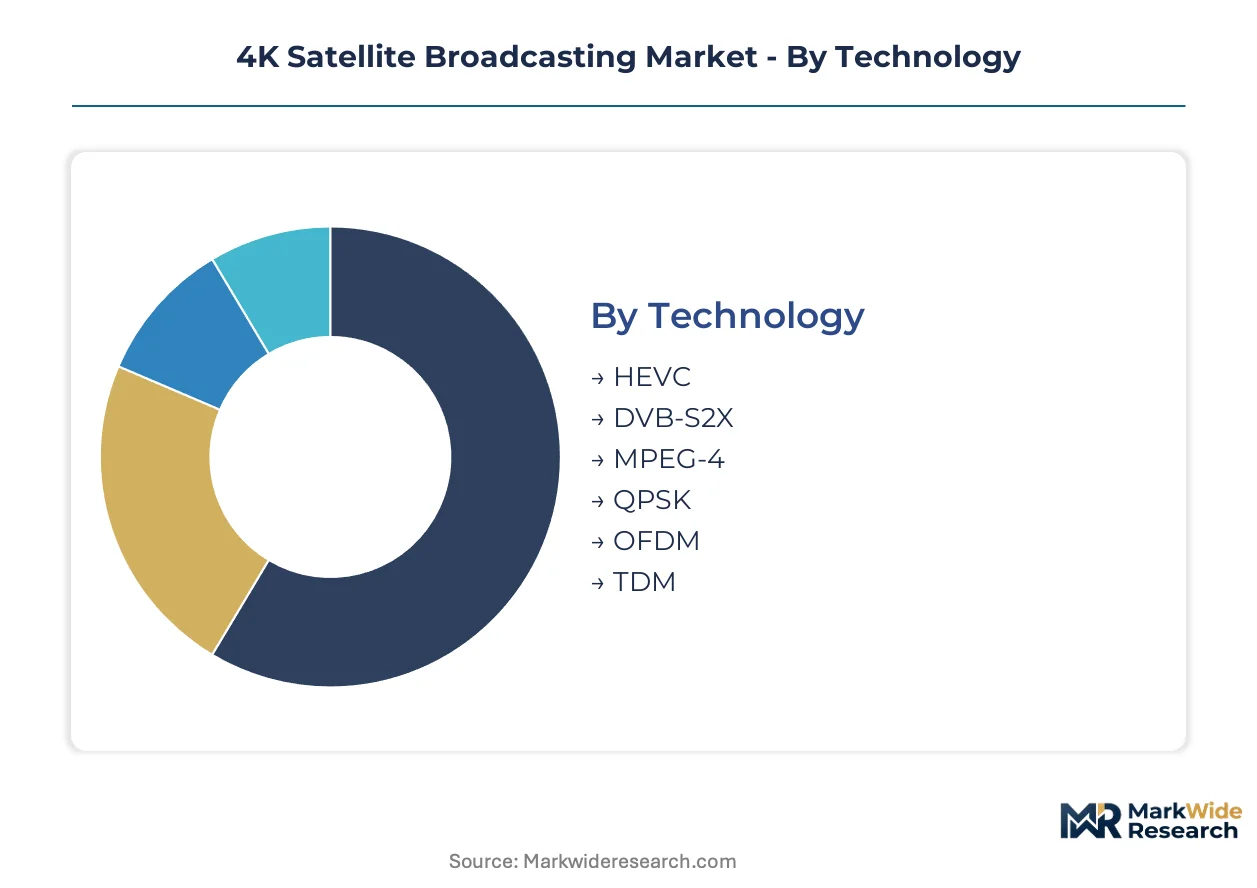
4K satellite broadcasting segments reveal distinct channel economics. Compression standards and modulation protocols determine transponder efficiency. Service delivery models dictate subscriber acquisition costs and lifetime value calculations across orbital infrastructure investments.
Technology:
HEVC and DVB-S2X flow through premium transponder leases to direct-to-home operators, while legacy MPEG-4 and QPSK serve cable headend aggregation and mobile TV multicast.
- HEVC:Advanced video coding compresses 4K streams at 15-25 Mbps, enabling Ku-band carriage without Ka-band migration. Indian direct-to-home operators leverage HEVC to avoid costly infrastructure overhauls while expanding 4K channel counts.
- DVB-S2X:Next-generation modulation with 256APSK constellations improves spectral efficiency by 30% over DVB-S2. European pay-TV providers deploy this across sports multiplexes to reduce per-channel transponder costs.
- MPEG-4:Legacy compression standard retains backward compatibility with installed set-top box bases across Southeast Asian markets.
- QPSK:Robust modulation scheme persists in mobile TV and maritime applications where signal stability trumps bandwidth efficiency.
- OFDM:Multi-carrier transmission technology enables hybrid satellite-terrestrial convergence for 5G multicast integration.
- TDM:Time-division multiplexing architectures support statistical multiplexing of variable-bitrate 4K content across shared transponder resources.
HEVC dominates installed base. DVB-S2X is where expansion concentrates.
Application:
Cost tier stratification separates premium direct-to-home deployments from mid-market cable network upgrades and emerging mobile TV propositions.
- Direct-to-Home:Satellite-to-consumer delivery commands the largest revenue pool, with Reliance Jio and Tata Play subsidizing 4K set-top boxes across India's Hindi-speaking belt to capture subscriber tiers beyond fiber reach.
- Cable Network Broadcasting:Headend reception and redistribution of 4K satellite feeds serves hybrid fiber-coaxial networks in Germany and the United Kingdom where DVB-S2X migration is accelerating.
- IPTV Services:Hybrid satellite-IP bundles represent the steepest expansion trajectory as telecom operators converge geostationary delivery with fixed-line broadband infrastructure.
- Mobile TV:Handheld and vehicular reception of 4K content targets maritime, aviation, and rural mobility use cases where terrestrial networks fail.
- Public Broadcasting:State-funded 4K distribution prioritizes universal service obligations over commercial return, particularly in Japan under ISDB-S3 mandates.
Direct-to-Home captures the mature profit core. IPTV Services is climbing the fastest.
End User:
Volume concentration varies by customer type, with pay-TV providers driving hardware refresh cycles while content distributors negotiate long-term transponder commitments.
- Content Distributors:Sports rights holders and studio aggregators lease orbital capacity for exclusive 4K event delivery, particularly cricket in South Asia where single-match broadcasts justify premium transponder spend.
- Telecom Operators:Integrated carriers bundle satellite 4K with fixed and mobile services, requiring seamless handoff between geostationary delivery and 5G multicast architectures.
- Broadcasters:National public service networks in Japan face ISDB-S3 readiness mandates compelling receiver ecosystem upgrades across 50 million households.
- Pay-TV Providers:Subscription platforms in Indonesia and Vietnam respond to unbundling pressures with event-specific 4K access rather than monthly commitments.
Pay-TV Providers dominate installed base. Telecom Operators is where expansion concentrates.
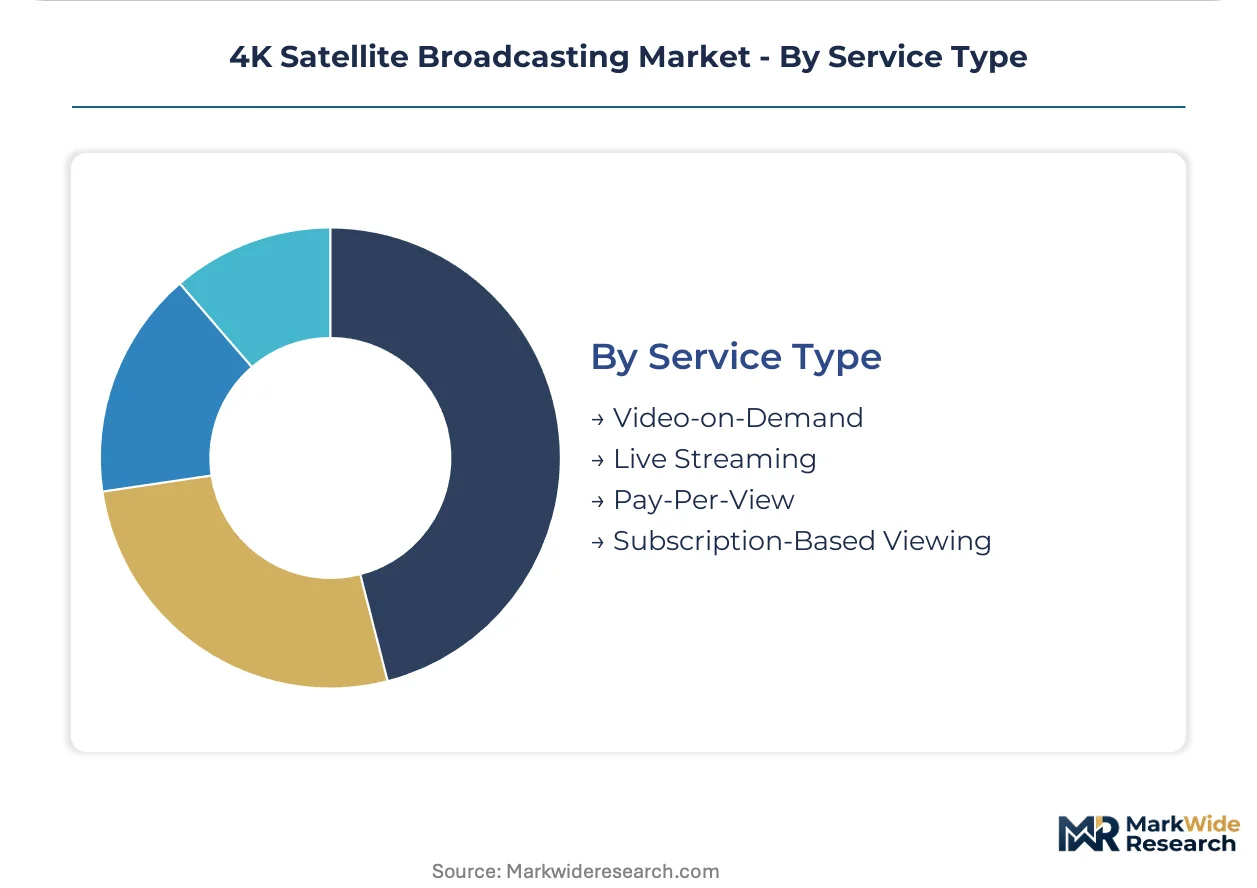
Service Type:
Margin structure differentiates recurring subscription revenue from transactional and on-demand models, with live sports commanding premium pricing elasticity.
- Video-on-Demand:Library 4K content delivered via satellite multicast to edge caches enables time-shifted viewing without repeated transponder utilization.
- Live Streaming:Real-time 4K sports and cultural events capture emerging margin concentration, with football in Europe and cricket in India driving subscriber willingness to pay for tier upgrades.
- Pay-Per-View:Event-specific access models expand addressable audience beyond committed subscribers, compressing customer lifetime value while reducing churn exposure.
- Subscription-Based Viewing:Monthly 4K tier commitments occupy the mature profit core across established direct-to-home markets.
Subscription-Based Viewing dominates installed base. Live Streaming is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orbital slot scarcity in Europe compresses transponder lease rates below those prevailing in South Asian markets where fiber penetration remains patchy. This pricing-power asymmetry redirects fleet operator investment toward capacity expansion over the Indian Ocean and Southeast Asian arcs.
United States
The FCC coordinates orbital slot assignments and spectrum auctions that shape market access for direct-to-home operators. DirecTV and DISH Network compete for subscriber tiers through exclusive sports rights acquisitions in 4K resolution. Los Angeles and New York metro areas concentrate headend infrastructure investment despite fiber encroachment.
India
Reliance Jio and Tata Play subsidize 4K set-top boxes to capture subscribers beyond fiber reach across the Hindi-speaking belt. TRAI regulates tariff structures and interoperability mandates for direct-to-home services. Mumbai and Delhi-NCR anchor headend operations serving the country's largest metropolitan subscriber bases.
Japan
Sky Perfect JSAT leverages ISDB-S3 broadcast readiness mandates to drive receiver ecosystem upgrades across 50 million households. METI enforces technical standards through the Ministry of Internal Affairs and Communications. Tokyo and Osaka metropolitan clusters concentrate uplink facilities and broadcast operations.
Germany
Sky Deutschland migrates sports multiplexes to DVB-S2X modulation within accelerated eighteen-month windows to reduce per-channel transponder costs. The European Commission's F-Gas Regulation constrains ground station cooling system retrofits. Munich and Cologne host major broadcast headend and uplink infrastructure serving Central European distribution.
Brazil
Hispasat and regional operators target premium sports content delivery to direct-to-home subscribers in urban peripheries where fiber deployment lags. ANATEL regulates orbital slot coordination and broadcast licensing frameworks. São Paulo and Rio de Janeiro concentrate subscriber density and headend investment for Latin American trunking routes.
4K Satellite Broadcasting Market Competitive Landscape
Concentration sits with fleet-owning satellite operators possessing prime geostationary slots and hybrid MEO-GEO architectures. Three orbital infrastructure holders control pricing power over transponder leases, while terrestrial aggregators compete on content bundling and subscriber acquisition. Strategic archetypes include integrated fleet operators, pay-TV platform owners, and hybrid satellite-IP service providers. Competitive moves center on capacity expansion through satellite replenishment programs and strategic partnerships for ground segment integration.
Within the integrated fleet operator tier, SES exemplifies MEO-GEO hybrid architecture deployment, Eutelsat anchors European distribution through prime orbital positions, and Intelsat occupies a position emphasizing transatlantic and Latin American video trunking reach. These Luxembourg-based, Paris-based, and McLean-based operators respectively represent capacity leadership, regional slot dominance, and global route concentration archetypes that define competitive positioning across premium video neighborhoods.
| Leading Market Players |
|---|
| SES |
| Eutelsat |
| Intelsat |
| Sky |
| DirecTV |
| DISH Network |
| Hispasat |
| Telesat |
| Sky Perfect JSAT |
| Others |
Pricing and Supply Chain Analysis
Long-term transponder lease contracts lock in capacity access and price visibility for broadcasters navigating orbital slot scarcity. These multi-year agreements with fleet operators like SES and Eutelsat insulate pay-TV providers from step-function cost spikes while committing capital upfront.
Pricing Analysis
The customization-premium spread separates configured-to-order transponder leases from standard capacity blocks. Three-tier pricing structure across premium orbital positions, standard transponder leases, and economy backup capacity dominates, with slot scarcity at prime longitudes driving differentiation. Pricing pressure stems from DVB-S2X efficiency gains compressing per-channel economics. Small broadcasters exhibit highest price sensitivity, while sports rights holders absorb premiums for exclusive 4K event windows.
Supply Chain Analysis
France and Luxembourg anchor satellite manufacturing and fleet operations, with Thales Alenia Space and Airbus Defence and Space producing orbital platforms. Ground segment hardware draws from US solid-state amplifier suppliers and Japanese receiver component fabricators. Single-source vulnerability concentrates in geostationary launch services, where Arianespace and SpaceX dominate. Distribution runs through direct-to-home operators, cable headend aggregators, and hybrid satellite-IP bundlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pay-TV platforms capable of negotiating multi-year transponder blocks, fragmenting smaller broadcaster leverage.
For Market Incumbents: Consolidate orbital capacity holdings through accelerated refresh cycles or strategic slot acquisitions before DVB-S2X adoption widens. Defend against fiber-to-the-home substitution by locking exclusive sports rights into long-term distribution deals. Prioritize backward integration into ground station infrastructure to control uplink costs. For New Entrants and Emerging Players: Anchor in India's Hindi-speaking belt where direct-to-home 4K penetration remains below fifteen percent and set-top box subsidies expand. Target hybrid satellite-IP service bundles as telecom operators converge delivery architectures. Pursue pay-per-view event access models to bypass entrenched subscription platforms. For Investors and Strategic Acquirers: Capital is best deployed toward fleet operators with prime geostationary slots and demonstrated replenishment program execution. Long-term viability hinges on capacity leadership across video neighborhoods. Watch DVB-S2X migration velocity as inflection indicator for transponder efficiency gains and pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Orbital Slot Acquisition | Prime longitude positions at 13°E and 19.2°E anchor European 4K distribution economics. |
| Ground Station Modernization | Closed-loop liquid cooling eliminates F-Gas regulatory exposure across Spanish and Italian uplink facilities. |
| HEVC Patent Pool Navigation | Structured royalty agreements with MPEG LA and Velos Media reduce decoder manufacturing risk. |
| Hybrid Service Bundle Launch | Convergence with 5G multicast architectures enables seamless handoff between fixed and mobile screens. |
| Set-Top Box Ecosystem Localization | India's PLI scheme alignment reduces indigenous hardware production costs for direct-to-home operators. |
Research Methodology
A standing panel of satellite fleet executives, broadcast technology directors, pay-TV platform strategists, and regulatory affairs specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against FCC orbital filings, Eutelsat and SES capacity disclosures, TRAI tariff orders, and METI technical standards. Bottom-up subscriber and transponder modeling triangulated against top-down fleet operator revenue segmentation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled technology adoption curves, application delivery modes, service type margin structures, and regional regulatory clusters. CAGRs derived from transponder lease rate trajectories, set-top box shipment forecasts, and sports rights expenditure patterns.
Material uncertainties — launch delays, spectrum reallocation proceedings, and compression standard patent disputes — sit outside the modeled envelope. Forecasts reflect assumptions about orbital slot continuity and receiver ecosystem upgrade cycles. Recalibration cycles align with material shifts in modulation efficiency gains and fiber penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.