
 China Satellite Imagery Services Market | 2026-2036
China Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
China Satellite Imagery Services Market Insights
China's domestic satellite constellation builders is shifting toward higher revisit frequencies for commercial clients. Chang Guang Satellite Technology Co., Ltd leverages its Jilin-1 constellation to dominate optical imaging subscriptions for provincial land bureaus. Beijing Space View Technology Co., Ltd anchors government contracts through specialized radar imaging capabilities for all-weather disaster response. HEAD Aerospace Group competes across dual-use segments by sustaining long-term service agreements with defense-adjacent research institutes.
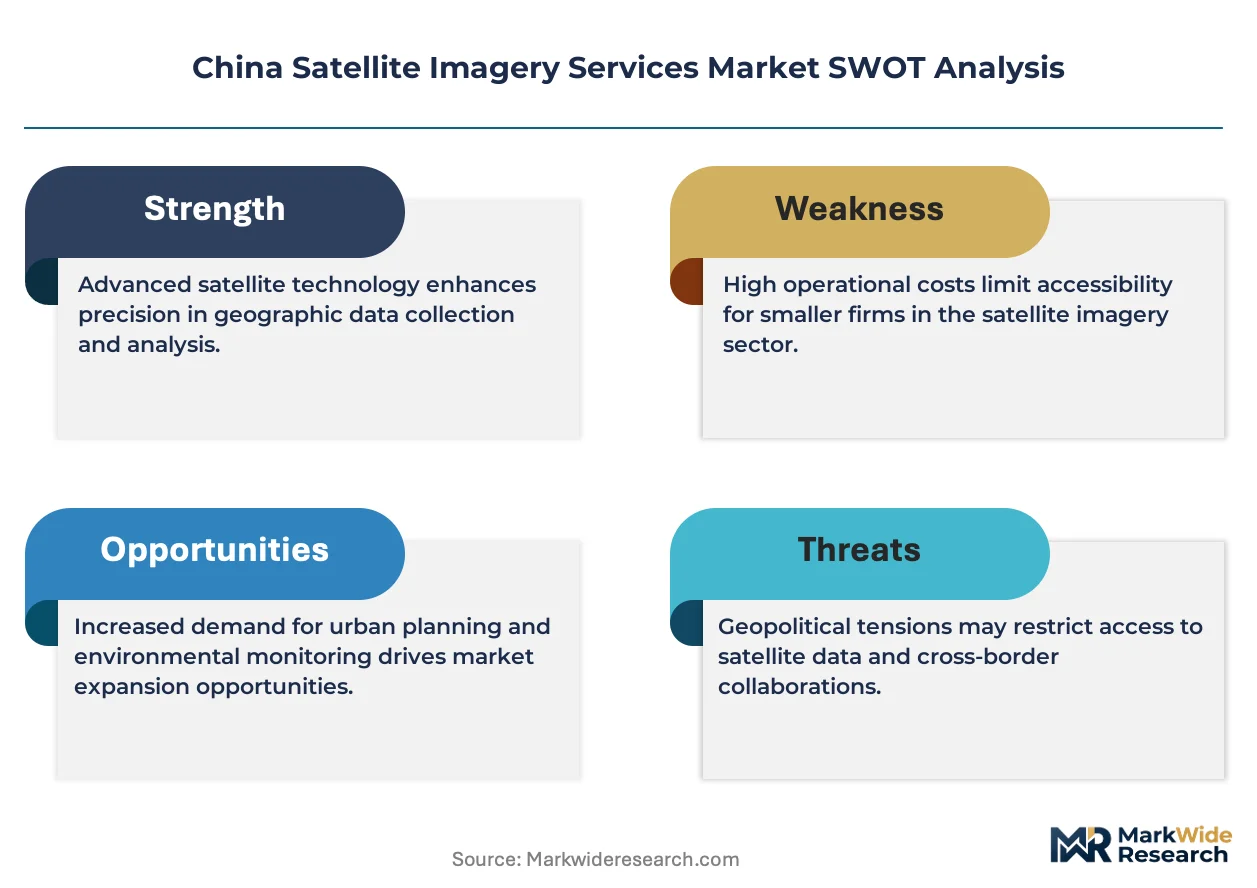
China satellite imagery services encompass the acquisition, processing, and distribution of geospatial data captured by Earth-observation platforms operating in low, medium, and geostationary orbits, with spatial resolutions ranging from sub-meter panchromatic to 30-meter multispectral products. These services convert raw sensor data into actionable intelligence for infrastructure planning, resource extraction, and climate attribution studies. Environmental monitoring applications lead service-type revenue due to recurring government mandates for pollution tracking and ecological red-line zone enforcement. Radar imaging technology represents the fastest-expanding technology segment as cloud-penetrating synthetic aperture radar supports maritime surveillance and subsidence monitoring in coastal manufacturing zones. Urban development applications within the application dimension command premium pricing through high-frequency change-detection contracts tied to property tax assessment and illegal construction identification.
MIIT spectrum allocation rules and GB standards for remote sensing data security shape product specifications and cross-border transfer restrictions for foreign operators like Airbus. NMPA licensing requirements for commercial satellite operators dictate minimum resolution thresholds and customer screening protocols that filter market access. Stakeholders must monitor evolving SAMR data-localization enforcement and provincial procurement preferences that increasingly favor domestic constellation operators over foreign imagery providers.
Market Dynamics
China's dual carbon goals under MEE oversight are compressing procurement cycles for environmental monitoring services, forcing constellation operators to prioritize higher revisit frequencies over raw resolution specifications. This structural pivot favors domestic operators with rapid-tasking capabilities and penalizes foreign providers facing SAMR data-localization enforcement.
Growth Catalysts
- MEE ecological red-line mandates:Provincial governments must maintain continuous coverage of protected zones, generating recurring subscription revenue for satellite operators.
- Heilongjiang precision agriculture expansion:Large-scale farming cooperatives are contracting satellite-derived crop health analytics to optimize fertilizer application and irrigation scheduling.
- Yangtze River Delta smart city infrastructure:Municipal planning bureaus procure high-frequency change-detection imagery for property tax assessment and illegal construction identification.
Market Restraints
- MIIT spectrum allocation scarcity:Limited S-band and X-band frequencies constrain constellation expansion plans and increase coordination costs for new entrants.
- GB standards compliance burden:Data security classification requirements impose processing delays and restrict cross-border transfer options for multinational clients.
- Domestic operator concentration:Chang Guang Satellite Technology and Beijing Space View Technology control critical orbital slots and ground station networks, raising barriers for challengers.
Strategic Opportunities
- Maritime surveillance integration:Coastal manufacturing zones require subsidence monitoring and vessel tracking combining SAR with AIS data fusion.
- Carbon credit verification services:MEE's emissions accounting rules create demand for satellite-based forest carbon stock measurement and industrial plume quantification.
- Cloud-penetrating radar subscriptions:All-weather imaging capabilities unlock year-round agricultural monitoring in southern provinces with heavy monsoon coverage.
Industry Challenges
- Geospatial data scientist scarcity:Shortage of professionals trained in synthetic aperture radar processing and multi-temporal analysis limits service scaling.
- NMPA licensing timeline compression:Commercial operators face extended review periods for resolution threshold adjustments and customer screening protocol updates.
- Legacy GIS system integration:Provincial land bureaus operate fragmented software architectures that complicate API-based data delivery standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Satellite Imagery Services Market |
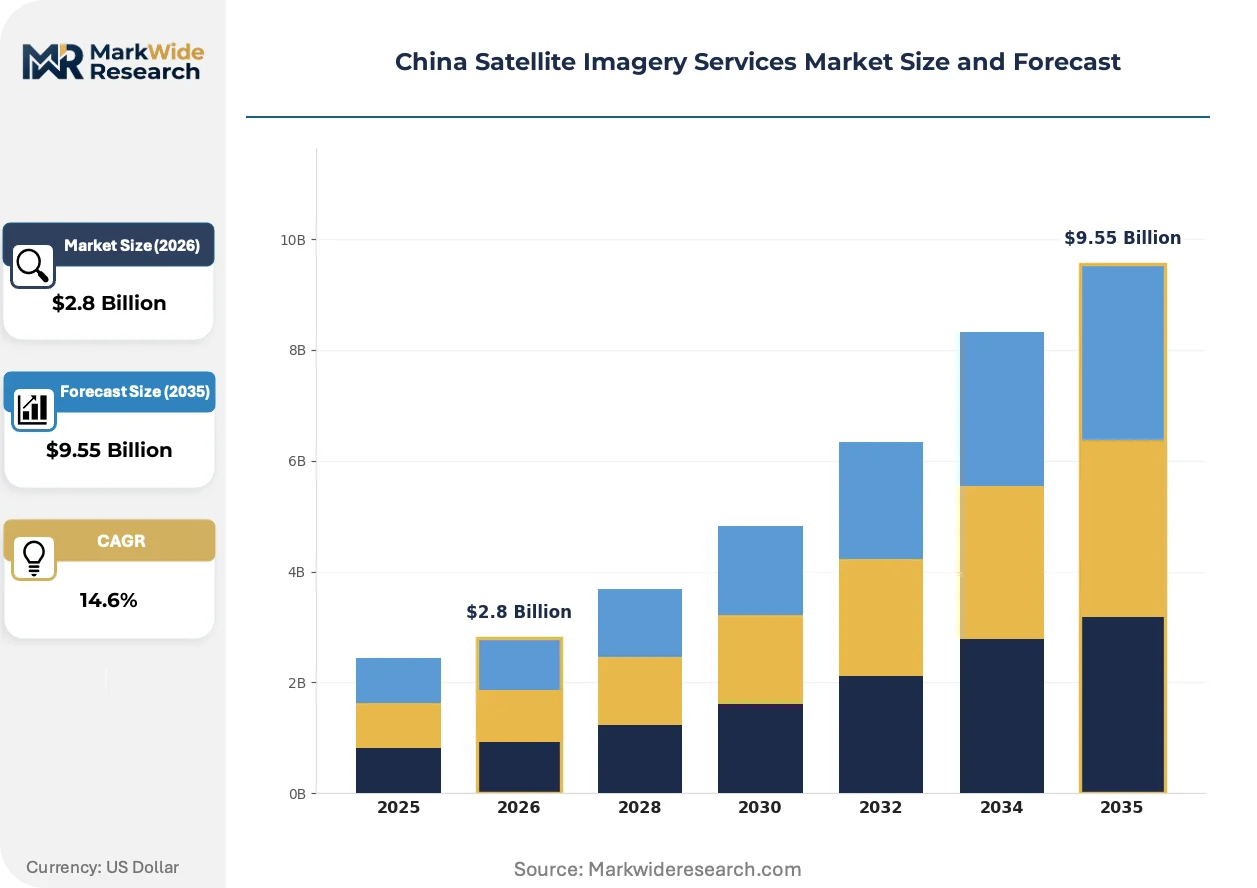
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Aerial Imaging, Land Use Mapping, Environmental Monitoring, Disaster Management End User: Aerospace, Agriculture, Urban Planning, Defense Application: Natural Resource Management, Urban Development, Transportation Planning, Climate Studies Technology: Optical Imaging, Radar Imaging, Multispectral Imaging, Hyperspectral Imaging |
| Companies Covered | 21st Century Space Technology Application Co., Ltd, Beijing Zero Map Information Technology Co., Ltd, China Siwei Surveying and Mapping Technology Co., Ltd, National Satellite Meteorological Center, China National Space Administration, Chang Guang Satellite Technology Co., Ltd, Beijing Space View Technology Co., Ltd, Airbus, HEAD Aerospace Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Satellite Imagery Services Market Trends and Innovations
Synthetic aperture radar is rewriting competitive positioning in China's satellite imagery market. Cloud-penetrating capabilities are displacing optical dominance in coastal and agricultural zones where weather interference previously degraded service reliability.
AI-driven on-board processing is rewriting how raw sensor data converts to actionable intelligence. Jilin-1 constellation operators embed edge-computing chips that perform automated feature extraction before downlink, compressing delivery latency from hours to minutes. Municipal governments in the Yangtze River Delta now expect near-real-time change-detection alerts for urban planning violations.
MIIT's updated remote sensing data security GB standards are mandating stricter customer screening and localization requirements. Foreign operators including Airbus face operational friction as SAMR enforcement intensifies cross-border transfer restrictions. Domestic constellation builders capture provincial procurement contracts previously contested by international providers.
Subscription-based tasking models are displacing traditional per-image transactions across government and commercial segments. Agricultural cooperatives in Heilongjiang now contract seasonal monitoring packages rather than ad-hoc acquisitions, locking in revenue predictability for operators. This shift concentrates buyer power among large-scale farming entities while squeezing smaller imagery resellers unable to offer integrated analytics layers.
China Satellite Imagery Services Market Segmentation
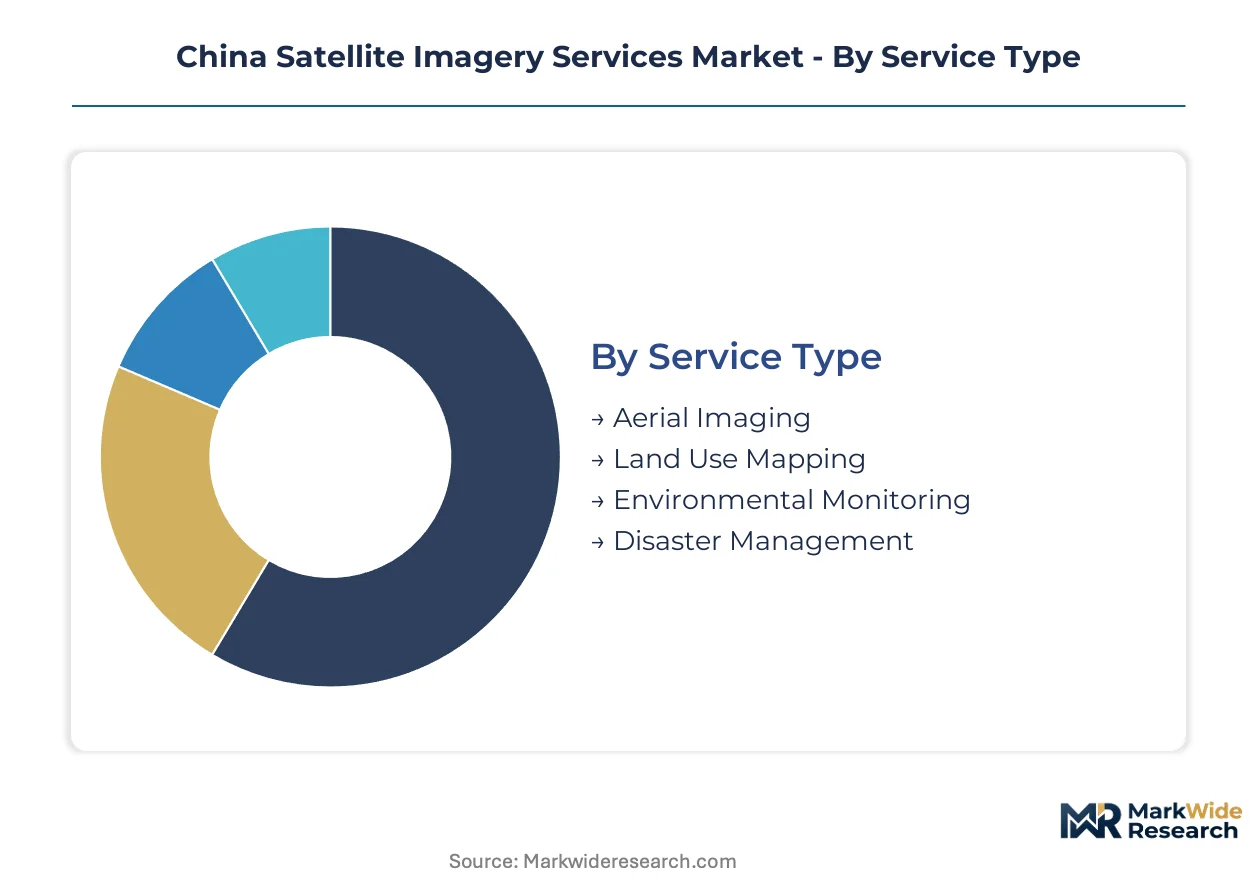
China's satellite imagery market fragments across four critical dimensions that determine pricing power and contract duration. Service type and technology choices dictate whether operators capture recurring subscription revenue or one-time tasking fees. End-user concentration in state-directed sectors and application specificity around environmental compliance create divergent margin profiles across segments.
Service Type:
Customization intensity spans from standardized subscription products to fully bespoke analytics pipelines, with government mandates pushing toward the latter.
- Environmental Monitoring:Continuous coverage of pollution sources, ecological red-line zones, and industrial emissions under MEE oversight generates recurring multi-year contracts. Provincial environmental protection bureaus in the Yangtze River Delta and Pearl River Delta dominate procurement, driven by dual carbon goal enforcement and air quality attribution requirements.
- Disaster Management:Rapid-tasking protocols for flood, earthquake, and landslide response command premium pricing during activation windows. All-weather radar capabilities are displacing optical subscriptions in Sichuan and Yunnan provinces where monsoon seasons previously degraded service reliability.
- Aerial Imaging:High-resolution panchromatic capture supports construction progress tracking and property boundary disputes.
- Land Use Mapping:Cadastral updates and illegal construction identification flow through municipal planning bureaus.
Leading the category by volume: Environmental Monitoring. Growing fastest: Disaster Management.
End User:
Budget scale and procurement flexibility separate state-mandated programs from discretionary commercial spending.
- Urban Planning:Municipal governments in tier-one cities deploy change-detection analytics for property tax assessment and zoning enforcement. Shanghai and Shenzhen planning bureaus now require sub-meter resolution with sub-24-hour revisit frequencies, compressing delivery windows for constellation operators.
- Agriculture:Large-scale cooperatives in Heilongjiang Province contract seasonal crop health monitoring to optimize input application. Satellite-derived NDVI analytics integrate directly with precision spraying equipment, creating stickier vendor relationships than raw imagery resale.
- Defense:Research institutes under State Administration of Science, Technology and Industry for National Defense fund dual-use capability development.
- Aerospace:Constellation operators and launch service providers consume imagery for site selection and range safety.
Dominating procurement value: Urban Planning. Expanding most quickly: Agriculture.
Application:
Regulatory urgency around climate accountability is elevating certain applications above infrastructure planning in budget priority.
- Urban Development:High-frequency change detection identifies illegal construction and supports property tax base mapping. Guangdong and Jiangsu provincial governments mandate quarterly coverage of all prefecture-level cities, locking in predictable revenue streams for domestic operators with sufficient revisit capacity.
- Climate Studies:Forest carbon stock measurement and industrial plume quantification are emerging under MEE emissions accounting rules. Verification services for carbon credit markets remain nascent but attract venture funding for specialized analytics layers.
- Natural Resource Management:Mining concession monitoring and water rights enforcement flow through provincial land and resources departments.
- Transportation Planning:Corridor selection and construction progress tracking support national highway and rail expansion programs.
Highest contract value concentration: Urban Development. Steepest expansion trajectory: Climate Studies.
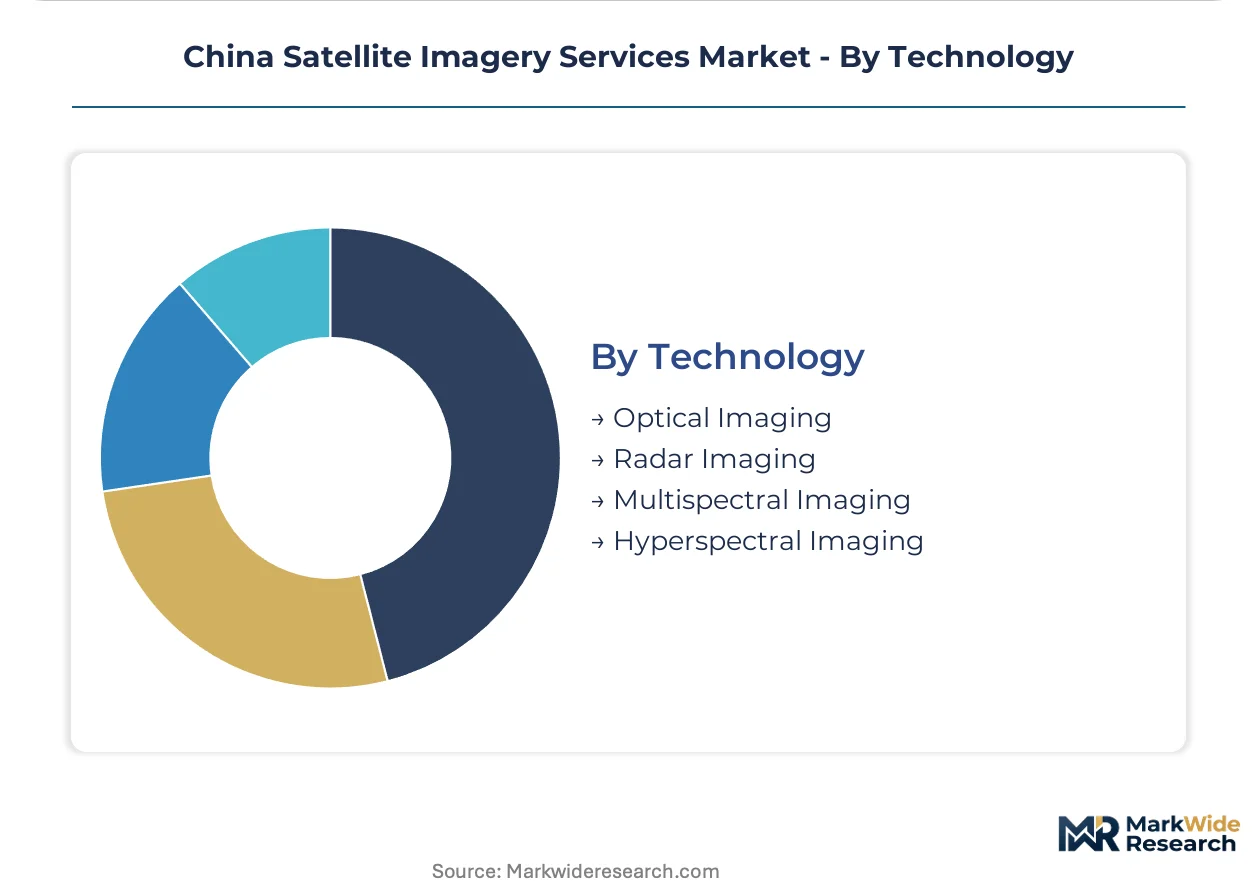
Technology:
Performance trade-offs between resolution, revisit, and weather independence segment the vendor competitive landscape.
- Radar Imaging:Synthetic aperture radar penetrates cloud cover and operates day-night, enabling year-round agricultural monitoring in southern provinces and subsidence tracking in coastal manufacturing zones. MIIT spectrum allocation for S-band and X-band frequencies constrains new entrants but protects incumbent margins.
- Optical Imaging:Sub-meter panchromatic resolution remains essential for urban planning and cadastral applications where visual interpretation dominates. Chang Guang Satellite Technology's Jilin-1 constellation leverages high revisit rates to compensate for weather dependency in northern provinces.
- Multispectral Imaging:Red-edge and near-infrared bands support vegetation health analytics for agricultural cooperatives.
- Hyperspectral Imaging:Mineral identification and precision agriculture applications remain limited by data processing bottlenecks and analyst scarcity.
Commanding premium pricing: Radar Imaging. Gaining share fastest: Optical Imaging through constellation densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orbital slot allocations and ground station networks cluster in eastern coastal provinces where MIIT spectrum licenses concentrate. Provincial environmental bureaus drive procurement cycles through MEE-mandated monitoring programs.
Yangtze River Delta
Shanghai and Jiangsu municipal governments contract high-frequency change-detection for property tax assessment and illegal construction identification. MEE dual carbon enforcement mandates quarterly coverage of industrial emissions across the corridor. Nanjing and Hangzhou planning bureaus now require sub-24-hour revisit frequencies, compressing delivery windows for constellation operators.
Beijing-Tianjin-Hebei
State-administered research institutes under the State Administration of Science, Technology and Industry for National Defense fund dual-use capability development. SAMR data-localization rules filter foreign operator access to sensitive government contracts. Tianjin coastal manufacturing zones demand SAR-based subsidence monitoring for port infrastructure integrity.
Heilongjiang Province
Large-scale farming cooperatives contract satellite-derived NDVI analytics to optimize fertilizer application and irrigation scheduling. NMPA licensing requirements for commercial operators dictate minimum resolution thresholds for agricultural monitoring services. Harbin-based agritech clusters integrate imagery feeds directly with precision spraying equipment.
Sichuan-Chongqing
Monsoon-season cloud cover drives substitution toward all-weather radar capabilities for disaster response. MIIT spectrum allocation for X-band frequencies supports rapid-tasking protocols for flood and landslide activation. Chengdu municipal emergency management bureaus procure premium-priced SAR subscriptions during high-risk weather windows.
Pearl River Delta
Guangdong provincial governments mandate quarterly coverage of all prefecture-level cities for urban development compliance. GB standards for remote sensing data security impose processing delays on cross-border transfer requests. Shenzhen smart city infrastructure programs anchor demand for near-real-time change-detection alerts.
China Satellite Imagery Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized analytics layers and vertical application integration. The vendor base stratifies across constellation operators with orbital assets, ground segment service providers, and value-added analytics platforms. Three archetypes dominate: state-affiliated constellation builders with captive government demand, commercial radar specialists capturing premium all-weather contracts, and foreign operators navigating SAMR localization requirements. Competitive intensity centers on rapid-tasking capabilities and AI-driven on-board processing rather than raw resolution specifications.
Within the state-affiliated tier, Chang Guang Satellite Technology Co., Ltd exemplifies the constellation-builder archetype through its Jilin-1 platform dominance in optical imaging subscriptions. Beijing Space View Technology Co., Ltd occupies a parallel position in radar imaging capabilities for government disaster response contracts. Among foreign participants, Airbus represents the constrained-operator archetype facing operational friction from MIIT spectrum rules and GB standards compliance burdens.
| Leading Market Players |
|---|
| 21st Century Space Technology Application Co., Ltd |
| Beijing Zero Map Information Technology Co., Ltd |
| China Siwei Surveying and Mapping Technology Co., Ltd |
| National Satellite Meteorological Center |
| China National Space Administration |
| Chang Guang Satellite Technology Co., Ltd |
| Beijing Space View Technology Co., Ltd |
| Airbus |
| HEAD Aerospace Group |
| Others |
Pricing and Supply Chain Analysis
AI-driven on-board processing is compressing delivery latency from hours to minutes while simultaneously concentrating value capture among constellation operators with orbital assets and edge-computing capabilities. This technological pivot rewards domestic players with rapid-tasking infrastructure and penalizes foreign providers facing SAMR data-localization enforcement and extended NMPA licensing timelines.
Pricing Analysis
Service-level bundling separates premium subscriptions with guaranteed revisit windows from standard tiers with longer tasking queues and economy offerings limited to archived imagery resale. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by revisit frequency, resolution thresholds, and analytics integration depth. Pricing pressure stems from domestic operator concentration as Chang Guang Satellite Technology and Beijing Space View Technology lock in multi-year government contracts with below-market introductory rates. Agricultural cooperatives in Heilongjiang Province exhibit highest price sensitivity due to seasonal budget constraints, while Yangtze River Delta municipal governments demonstrate lowest sensitivity given MEE-mandated procurement ceilings.
Supply Chain Analysis
Ground station networks and regional distribution centers cluster along China's eastern coastal corridor where MIIT spectrum licenses concentrate, creating hub-and-spoke patterns radiating from Beijing, Shanghai, and Shenzhen. Manufacturing of optical sensors draws from Japan and South Korea, while radar component fabrication rests on German and Israeli specialist suppliers. Single-source vulnerability runs through X-band frequency allocation controlled by MIIT, constraining constellation expansion for new entrants. Distribution runs through provincial land bureaus and municipal planning departments operating fragmented procurement systems with divergent API standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic aperture radar is displacing optical dominance in coastal and agricultural zones, creating a technology-transition phase where all-weather capability commands premium positioning. Legacy optical providers without radar diversification face margin compression as MEE mandates accelerate radar procurement cycles.
For Market Incumbents: Cement rapid-tasking superiority through additional orbital slot acquisition under MIIT allocation rules, prioritizing S-band and X-band spectrum reserves that block challenger expansion. Invest in backward integration into edge-computing chip design to maintain on-board processing latency advantages over foreign competitors facing SAMR data-localization barriers. Defensive positioning requires locking in multi-year service agreements with provincial environmental bureaus before NMPA licensing reforms lower resolution thresholds for new entrants.
For New Entrants and Emerging Players: Begin with carbon credit verification analytics as the most penetrable white-space segment, where MEE emissions accounting rules create demand without requiring owned orbital assets. Target Heilongjiang agricultural cooperatives with seasonal subscription packages integrating NDVI analytics directly with precision spraying equipment, bypassing incumbent dominance in government contracts. Go-to-market positioning should emphasize API-based delivery standardization that resolves legacy GIS fragmentation frustrating provincial land bureaus.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by state-affiliated constellation builders seeking specialized radar or analytics capabilities, with venture-backed SAR processing specialists commanding premium multiples. Long-term viability favors operators with dual-use revenue streams bridging commercial environmental monitoring and defense-adjacent research institute contracts. Watch MIIT spectrum auction timing as the critical inflection signal—new frequency releases would unlock challenger constellation expansion and compress incumbent pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| SAR Constellation Expansion | Cloud-penetrating capabilities unlock year-round agricultural monitoring in monsoon-affected southern provinces. |
| AI On-Board Processing Investment | Edge-computing compression of delivery latency from hours to minutes meets Yangtze River Delta municipal expectations. |
| Carbon Credit Verification Service Launch | MEE emissions accounting rules create satellite-based forest carbon stock measurement demand from industrial emitters. |
| Provincial Procurement Contract Lock-In | Multi-year agreements with environmental bureaus secure recurring revenue before NMPA licensing reforms lower barriers. |
| API Standardization Partnership | Unified data delivery protocols resolve legacy GIS fragmentation blocking municipal planning bureau adoption. |
Research Methodology
Multi-period observation of constellation launch schedules, MIIT spectrum allocation decisions, and provincial procurement award patterns anchored the trend analysis, supplemented by interviews with satellite operators, ground segment engineers, and municipal planning bureau procurement officers. Secondary validation drew from NMPA licensing disclosures, MEE environmental monitoring mandates, GB standards documentation, and customs records of sensor component imports. Bottom-up triangulation across operator revenue segments and top-down reconciliation against provincial budget allocations ensured cross-verification of market sizing.
Input-output matrices modeled capacity expansion, tasking demand, and pricing elasticity across service type, technology, and application dimensions over the projection horizon. Segmentation variables included environmental monitoring against disaster management service types, radar against optical imaging technologies, and urban development against climate studies applications. CAGRs derived from installed base growth curves, replacement cycle analysis, and MEE mandate enforcement timelines. Industry-specific forecast inputs incorporated MIIT spectrum release schedules and dual carbon goal implementation pacing.
Underlying measurement precision varies by segment; environmental monitoring and urban planning applications carry tighter precision than emerging carbon credit verification services. Forecasts reflect documented assumptions around NMPA licensing timeline stability, MIIT spectrum allocation continuity, and MEE enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Latin America Satellite Connectivity Market
Satellite
Satellite Amplifier Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Satellite Communication Equipment Market
Satellite
Canada Satellite Connectivity Market
Satellite
Satellite Communication System Market
Satellite
Italy Satellite Imagery Services Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Satellite Payload Market
Satellite
LEO and GEO Satellite Market
Satellite
Global Dish Antennas Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Satellite Bus Market
Satellite
Commercial Satellite Launch Service Market
Satellite
China Satellite Connectivity Market