
 Reconnaissance Satellite Market | 2026-2036
Reconnaissance Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Reconnaissance Satellite Market Analysis
Government procurement channels is rewriting how reconnaissance satellite contracts flow from defense agencies to prime contractors. Lockheed Martin leverages its classified manufacturing campuses in Colorado and California to sustain long-term NRO relationships. Airbus Defence and Space competes across European government tenders while anchoring dual-use production lines in France and Germany. Thales Alenia Space differentiates through Italian-led radar satellite programs that extend its footprint in Mediterranean defense cooperation frameworks.
Reconnaissance satellites are uncrewed orbital platforms carrying electro-optical, synthetic aperture radar, or hyperspectral sensors that capture imagery and signals intelligence at altitudes ranging from low Earth orbit to geostationary positions, serving military surveillance, border monitoring, and disaster response missions. Electro-optical systems still dominate current government fleet renewals, though synthetic aperture radar represents the fastest-expanding technology segment as operators demand all-weather, day-night imaging capability in denied areas. Military end users command the largest budget allocation, while private sector demand from energy infrastructure operators and agricultural analytics firms is building a secondary margin pool outside classified channels.
The U.S. Space Force and National Reconnaissance Office shape contractor requirements through classified mission specifications, while ESA and national European space agencies coordinate dual-use satellite development under EU Space Programme frameworks. Japan's METI and Cabinet Satellite Intelligence Center impose domestic content rules that restrict foreign subsystem access for sensitive orbital platforms. Stakeholders must monitor how export control regimes evolve around synthetic aperture radar components and whether new space traffic management rules constrain constellation deployment densities.
Market Dynamics
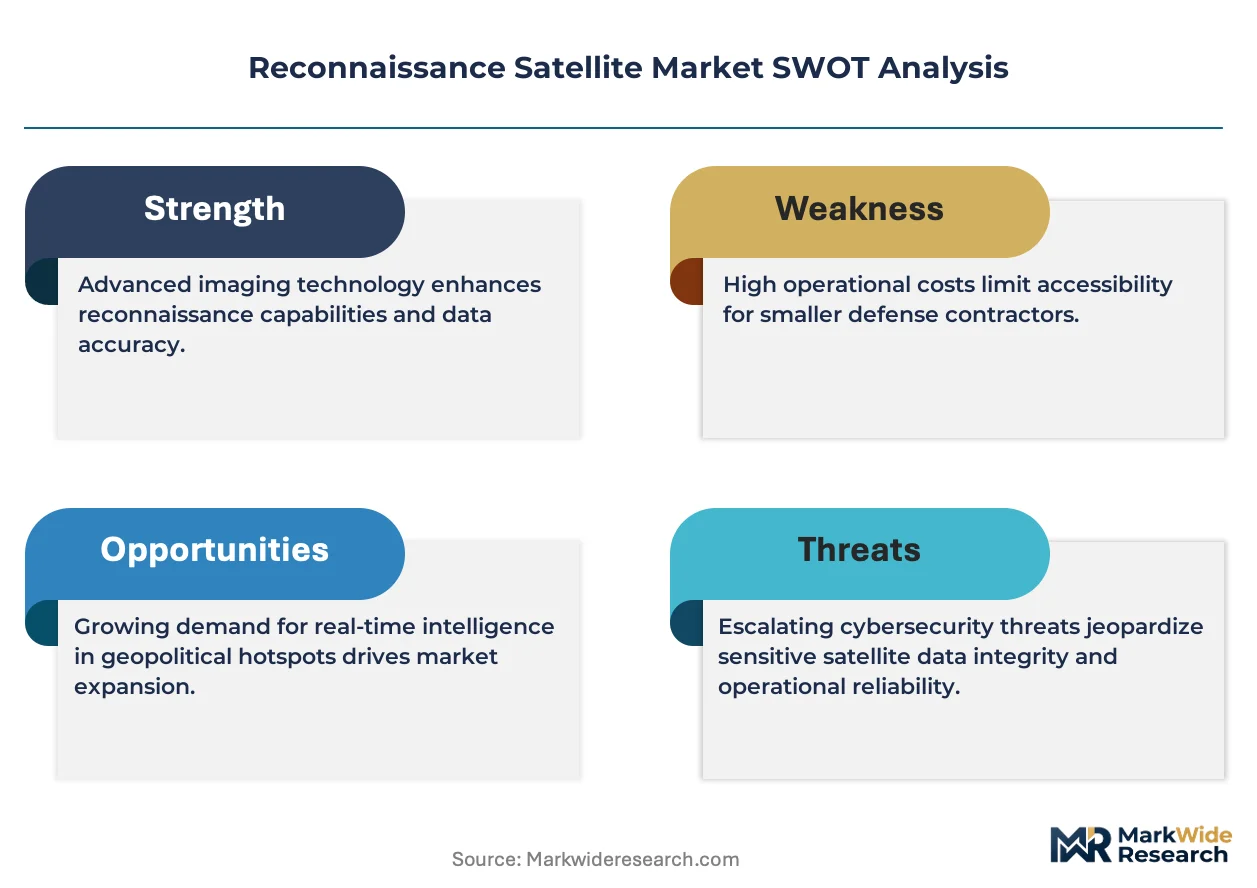
Synthetic aperture radar technology is compressing the competitive window for electro-optical satellite providers as defense agencies demand persistent imaging through cloud cover and electronic warfare conditions.
Growth Catalysts
- EU Space Programme frameworks:Dual-use satellite development receives coordinated funding across European member states, accelerating procurement timelines for Mediterranean defense cooperation missions.
- Energy infrastructure operators:Pipeline monitoring and offshore platform surveillance create commercial demand outside classified government channels, diversifying revenue pools for radar satellite services.
- Hyperspectral sensing:Agricultural analytics firms deploy orbital crop health monitoring, opening precision agriculture as a secondary end-use vertical with recurring subscription economics.
Market Restraints
- Gallium nitride component shortages:Radar satellite phased arrays depend on specialized semiconductor foundries concentrated in East Asian supply chains, creating input cost volatility and delivery uncertainty.
- US International Traffic in Arms Regulations:Export control classifications on synthetic aperture radar subsystems restrict technology transfer to allied nations, fragmenting supplier access for European and Asian integrators.
- Radio frequency interference:Crowded orbital spectrum allocations limit constellation deployment densities, constraining revisit rates for commercial imaging services in high-demand latitudes.
Strategic Opportunities
- Japan's Cabinet Satellite Intelligence Center:Domestic content rules for sensitive orbital platforms create captive demand for indigenous subsystem suppliers, rewarding local manufacturing partnerships.
- AI-driven autonomous tasking:Machine learning algorithms converging with edge computing onboard satellites enable real-time target detection without ground station relay, compressing intelligence delivery timelines.
- Disaster response agencies:Unmet demand for rapid post-event damage assessment creates white space for commercial satellite operators to sell surge capacity under emergency procurement frameworks.
Industry Challenges
- Cryptographic key management:Secure satellite-to-ground communications require specialized cybersecurity talent pools that defense contractors and commercial operators compete to staff.
- Space traffic coordination:Mega-constellation deployments by communications operators force reconnaissance mission planners to negotiate orbital slots and collision avoidance maneuvers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconnaissance Satellite Market |
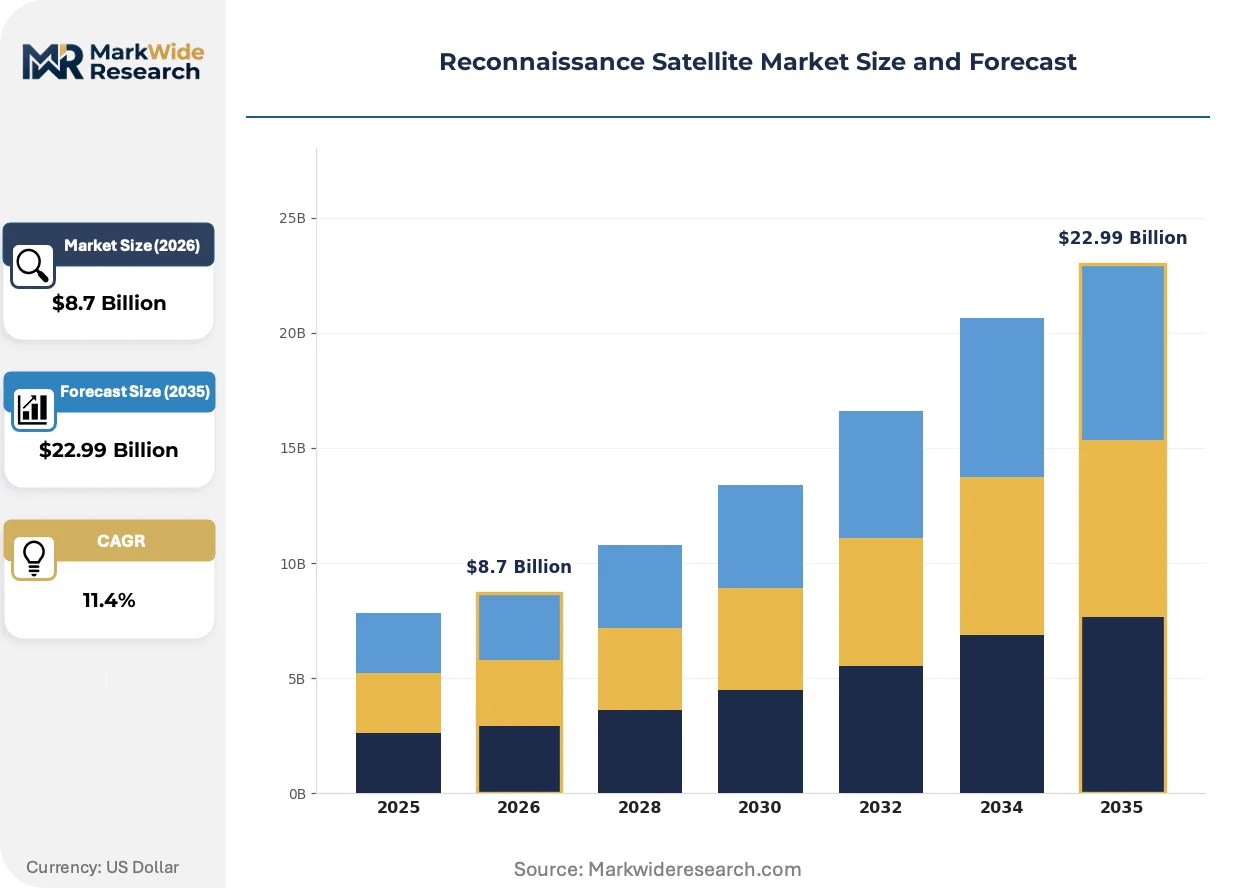
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electro-Optical, Synthetic Aperture Radar, Hyperspectral, Multispectral End User: Government, Military, Private Sector, Research Organizations Application: Surveillance, Reconnaissance, Mapping, Disaster Management Deployment: Low Earth Orbit, Geostationary Orbit, Medium Earth Orbit, Others |
| Companies Covered | Maxar Technologies, Airbus Defence and Space, Lockheed Martin, Northrop Grumman, L3Harris Technologies, Raytheon Technologies, Thales Alenia Space, Planet Labs, BlackSky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconnaissance Satellite Market Emerging Trajectories
Defense procurement offices are rewriting satellite specifications to prioritize resilience over raw resolution, forcing hardware and software architectures toward distributed, proliferated constellations.
Synthetic aperture radar payloads is migrating from specialized military platforms to commercial dual-use satellites as component miniaturization reduces mass and power requirements. Agricultural analytics firms and energy infrastructure operators now procure SAR imagery directly, bypassing traditional defense agency distribution channels. This migration from government-exclusive to commercial-accessible capability compresses pricing premiums and accelerates refresh cycles for legacy electro-optical fleets.
REACH chemical restrictions in Europe are forcing satellite manufacturers to eliminate hexavalent chromium coatings and specific composite resins from thermal control systems. Industrial consequence includes accelerated qualification of alternative materials for multi-year orbital durability. Prime contractors with European final assembly lines face compressed redesign timelines to maintain EU Space Programme eligibility.
Defense agencies are unbundling satellite construction from launch services from ground segment operations, creating disaggregated procurement models that favor specialized mid-tier suppliers. This pattern fragments historical prime contractor lock-in across the United States and United Kingdom. Commercial launch providers and ground station-as-a-service operators capture margin previously retained by integrated satellite builders.
Reconnaissance Satellite Market Segmentation
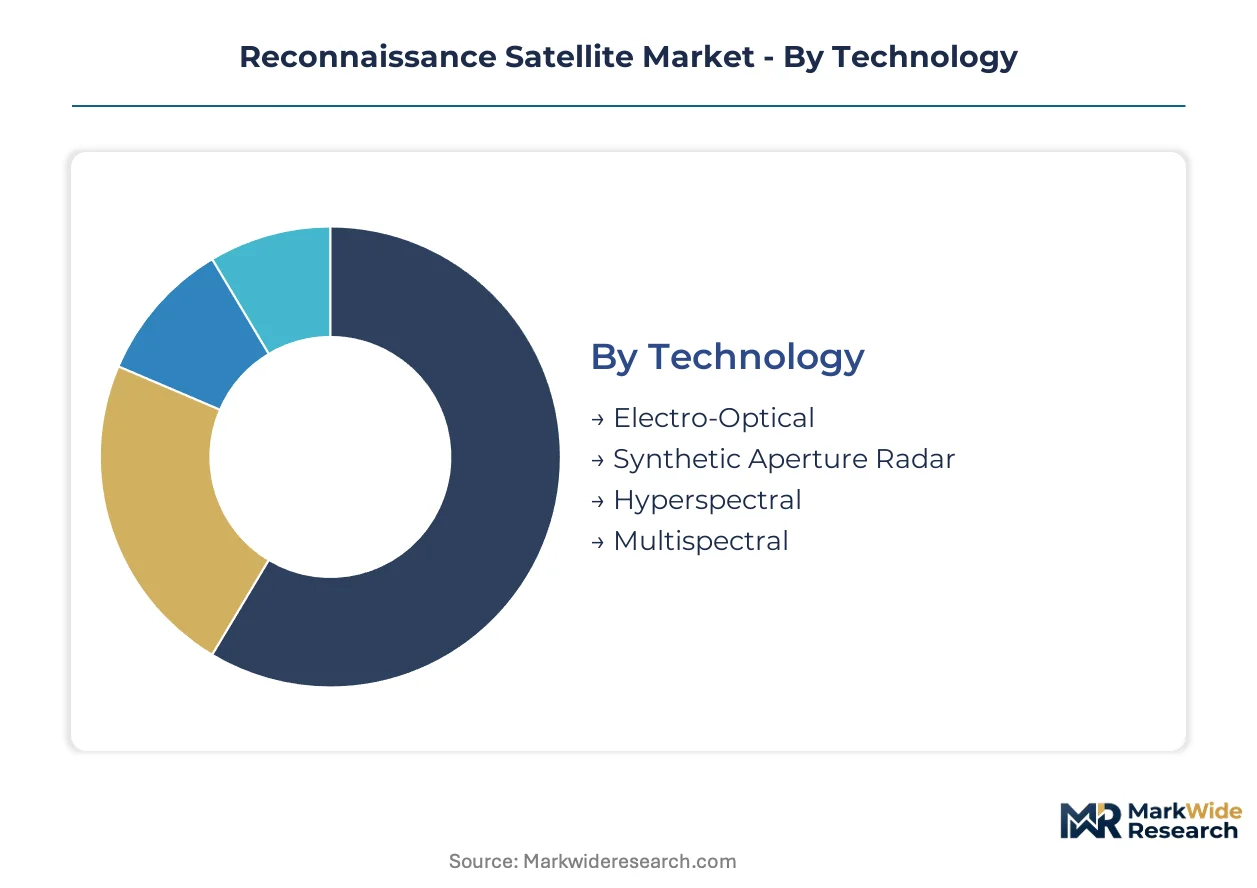
Reconnaissance satellite procurement flows through distinct technical and operational channels that reshape contractor bidding strategies. Defense agencies segment requirements by orbital altitude, sensor modality, and mission classification, creating tiered supplier ecosystems with divergent qualification barriers and contract tenors.
Technology:
Sensor modality determines platform mass, power budgets, and weather independence, creating four distinct procurement categories with diverging semiconductor supply chain dependencies.
- Synthetic Aperture Radar:Active microwave systems transmit and receive radar signals to generate imagery through cloud cover and darkness. Military end users in the United States and European NATO members drive procurement as electronic warfare resilience becomes mandatory. Gallium nitride component shortages constrain phased array production timelines.
- Electro-Optical:Passive visible and infrared sensors capture high-resolution imagery under clear-sky conditions. Legacy fleet renewals in Japan and France sustain demand despite vulnerability to weather denial. Cost advantages persist for non-contested surveillance missions.
- Hyperspectral:Hundreds of narrow spectral bands enable material identification for agricultural analytics and mineral exploration. Research organizations and commercial operators in Australia and Canada expand adoption outside classified channels.
- Multispectral:Limited discrete bands balance spectral information against data throughput constraints. Mapping agencies and environmental monitoring programs in Brazil and India deploy these platforms for land-use classification.
Electro-Optical holds installed capacity. Synthetic Aperture Radar is rotating up the share rankings.
End User:
Customer type dictates security clearance requirements, domestic content rules, and payment structures across the procurement lifecycle.
- Military:Classified mission specifications from the U.S. National Reconnaissance Office and Space Force demand hardened encryption, anti-jam capabilities, and nuclear event survivability. Budget allocation concentrates here with multi-decade program horizons.
- Government:Civilian agencies including border control and environmental ministries procure dual-use platforms under reduced security classifications. European Space Agency coordination streamlines multi-national tender processes.
- Private Sector:Energy infrastructure operators and insurance underwriters purchase imagery subscriptions without platform ownership. Commercial ground segment operators aggregate demand across fragmented buyers.
- Research Organizations:Universities and climate science institutes access subsidized launch slots through national space agencies. Data sharing agreements reduce per-mission costs for non-commercial Earth observation.
Military commands budget concentration. Private Sector is climbing the fastest as subscription models democratize access.
Application:
Mission purpose shapes revisit frequency requirements, resolution thresholds, and ground station network investments.
- Surveillance:Persistent monitoring of fixed installations and mobile assets demands high revisit rates from low Earth orbit constellations. Intelligence agencies in the United Kingdom and Germany prioritize this application for border and maritime domain awareness.
- Reconnaissance:Time-sensitive targeting of adversary forces requires rapid tasking responsiveness and low latency downlink. Synthetic aperture radar penetration through camouflage and concealment accelerates technology refresh.
- Mapping:Cartographic accuracy standards drive demand for stereo imaging and ground control point integration. National geospatial agencies in Japan and South Korea maintain dedicated satellite procurement lines.
- Disaster Management:Rapid post-event damage assessment creates surge demand for commercial operator capacity. Emergency procurement frameworks in Australia and the Philippines establish pre-negotiated access agreements.
Surveillance holds installed capacity. Disaster Management is gaining share fastest as climate-related event frequency rises.
Deployment:
Orbital altitude trades spatial resolution against areal coverage and atmospheric drag, segmenting platform design and launch cost structures.
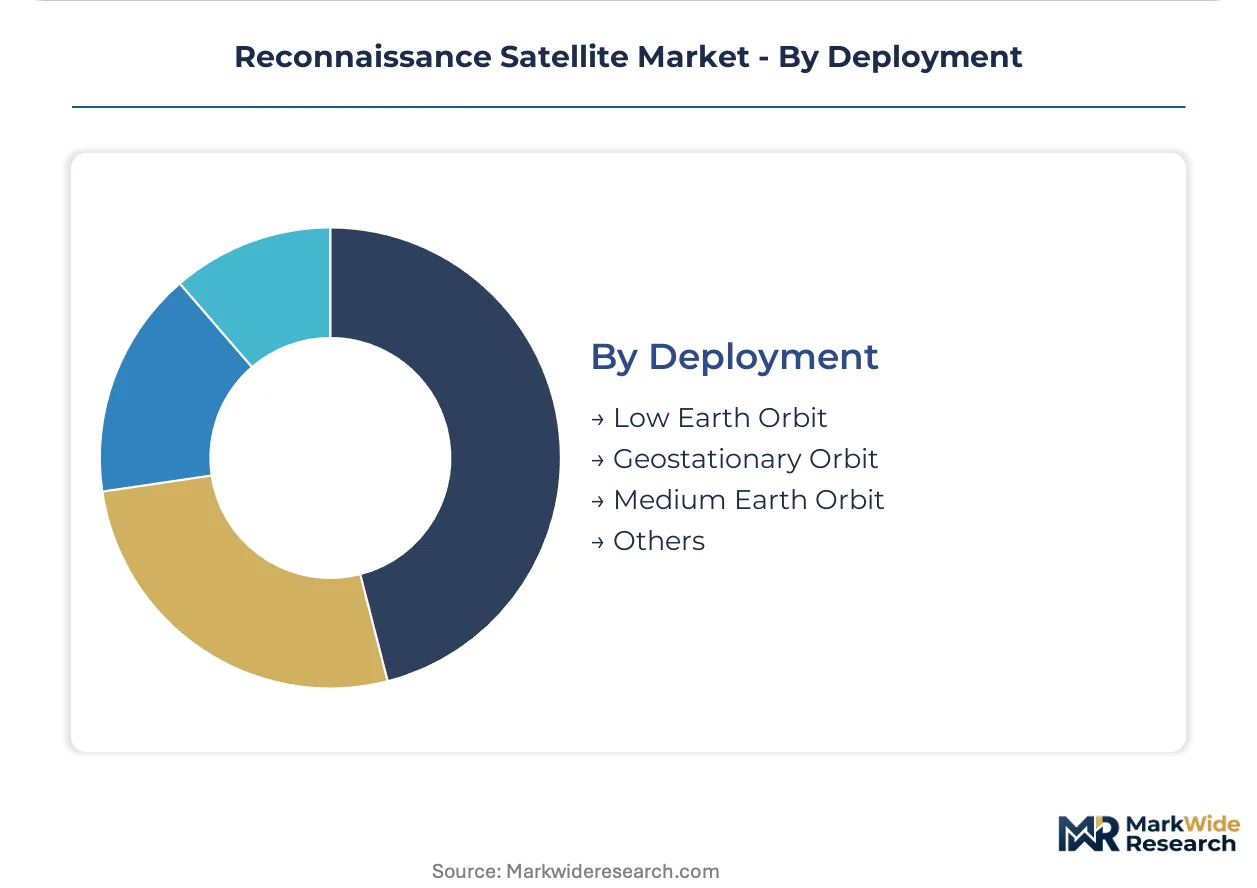
- Low Earth Orbit:Altitudes below 2,000 kilometers enable sub-meter resolution with minimal atmospheric interference. Proliferated constellations at 500-800 kilometer altitudes dominate new military procurement for resilience through redundancy.
- Geostationary Orbit:Fixed position at 35,786 kilometers supports continuous hemispheric coverage for missile warning and communications relay. Limited slot availability drives international coordination through the International Telecommunication Union.
- Medium Earth Orbit:Intermediate altitudes balance revisit frequency against launch energy requirements. Navigation augmentation and specialized signals intelligence missions occupy this less contested orbital band.
- Others:Highly elliptical and sun-synchronous orbits serve polar coverage and consistent illumination geometry requirements. Scientific and climate monitoring missions favor these specialized trajectories.
Low Earth Orbit holds installed capacity. Medium Earth Orbit is rotating up the share rankings as navigation-security convergence creates new mission profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement reforms across NATO member states are accelerating satellite constellation deployments. National security agencies in multiple jurisdictions now mandate domestic manufacturing content and technology transfer safeguards for sensitive orbital platforms.
United States
The National Reconnaissance Office and U.S. Space Force drive classified procurement through multi-decade program horizons. ITAR restrictions on synthetic aperture radar subsystems limit technology transfer to allied nations. Colorado and California host concentrated manufacturing campuses where prime contractors sustain long-term agency relationships.
France
Airbus Defence and Space anchors dual-use production lines serving both military and commercial imagery markets. EU Space Programme frameworks coordinate funding across member states for Mediterranean defense cooperation missions. Toulouse and Paris-Saclay clusters specialize in electro-optical payload integration and ground segment operations.
Germany
The Bundeswehr and federal intelligence services procure radar satellites for persistent surveillance of Eastern European borders. ESA coordination streamlines multi-national tender processes for dual-use platforms. Munich and Bremen industrial concentrations focus on synthetic aperture radar component manufacturing and satellite bus assembly.
Japan
METI and the Cabinet Satellite Intelligence Center impose strict domestic content rules for sensitive orbital platforms. National security legislation restricts foreign subsystem access for intelligence-gathering satellites. Tokyo and Tsukuba clusters develop indigenous phased array technologies and cryptographic communications systems.
United Kingdom
UK Space Agency and Ministry of Defence coordinate sovereign satellite capabilities post-Brexit outside EU procurement frameworks. Disaggregated procurement models unbundle construction from launch services and ground operations. Harwell and Glasgow space clusters specialize in small satellite manufacturing and downstream analytics services.
Reconnaissance Satellite Market Vendor Landscape
On the supply side, the industry is consolidating around defense primes with classified manufacturing clearances and long-term agency relationships. A tiered structure separates integrated platform builders from specialized payload providers and commercial imagery operators. Two strategic archetypes dominate: legacy aerospace conglomerates with security-cleared production facilities, and commercial remote sensing ventures selling subscription-based analytics. Competitive moves center on M&A to acquire synthetic aperture radar capabilities and strategic partnerships to secure gallium nitride component supply.
Among U.S.-based defense primes, Lockheed Martin and Northrop Grumman occupy positions within the classified satellite manufacturing tier, exemplifying the integrated platform builder archetype through their sustained National Reconnaissance Office relationships. Thales Alenia Space represents the European defense prime model, anchoring radar satellite programs within Mediterranean defense cooperation frameworks while maintaining dual-use production flexibility.
| Leading Market Players |
|---|
| Maxar Technologies |
| Airbus Defence and Space |
| Lockheed Martin |
| Northrop Grumman |
| L3Harris Technologies |
| Raytheon Technologies |
| Thales Alenia Space |
| Planet Labs |
| BlackSky |
| Others |
Supply Flow & Price Mechanics
Gallium nitride foundry concentration in Taiwan and South Korea generates dual pricing pressure—elevating input costs for radar satellite phased arrays while compressing margins for electro-optical providers facing SAR substitution. This single-source semiconductor dependency forces tiered spreads between ITAR-restricted U.S. platforms and commercially accessible European alternatives.
Pricing Analysis
Security clearance tier creates the primary spread between classified NRO contracts and commercial dual-use subscriptions. Three-tier pricing structure across classified, restricted, and open-access levels dominates procurement, with certification level determining access to synthetic aperture radar tasking priority. Pricing pressure stems from commercial imagery commoditization as Planet Labs and BlackSky flood agricultural analytics markets. Government end users exhibit lowest price sensitivity due to mission-critical specifications, while energy infrastructure operators negotiate volume discounts on annual subscriptions.
Supply Chain Analysis
ITAR restrictions on synthetic aperture radar subsystems fragment supplier access for European and Asian integrators seeking U.S. phased array components. Manufacturing concentrates in the United States, France, and Japan, with gallium nitride semiconductors drawing from Taiwan and South Korean foundries. Single-source vulnerability runs through East Asian semiconductor supply chains subject to export control volatility. Distribution runs through defense procurement offices for classified missions and commercial ground station aggregators for private sector access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ground segment-as-a-service and AI-driven analytics layers expand faster than satellite hardware manufacturing, creating attach-rate opportunities for recurring revenue capture. Subscription-based imagery intelligence now outpaces platform sale margins across commercial verticals.
For Market Incumbents: Pre-empt commercial SAR commoditization by deepening classified manufacturing relationships with NRO and Space Force through multi-decade program structures. Lockheed Martin and Northrop Grumman must accelerate gallium nitride supply partnerships to offset Taiwan foundry concentration risk. Vertical integration into edge-computing payloads preserves pricing power against software-defined satellite entrants.
For New Entrants and Emerging Players: Disaster response surge capacity in Australia and Southeast Asia represents the most penetrable entry point outside classified procurement channels. Agricultural analytics subscriptions in Brazil and India offer second-mover advantages through hyperspectral crop monitoring differentiation. Target emergency procurement frameworks with pre-negotiated access agreements bypassing traditional defense agency distribution.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors synthetic aperture radar capability acquisitions over electro-optical legacy assets. Long-term viability hinges on export-control compliance infrastructure and domestic content manufacturing partnerships. Watch for ITAR relaxation signals or allied-nation technology-sharing agreements as inflection indicators for cross-border M&A feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Aperture Radar Capability Acquisition | Captures fastest-growing sensor segment as defense agencies mandate all-weather imaging resilience. |
| Gallium Nitride Supply Partnership | Secures phased array semiconductor access against Taiwan and South Korean foundry concentration risk. |
| Ground Segment-as-a-Service Launch | Captures recurring revenue from commercial imagery operators bypassing platform ownership. |
| Domestic Content Manufacturing Partnership | Unlocks Japan and European procurement restricted by METI and EU Space Programme rules. |
| AI-Driven Analytics Platform Integration | Compresses intelligence delivery timelines through autonomous satellite tasking algorithms. |
Methodological Framework
Operator-level perspectives from satellite program directors at national reconnaissance offices, procurement officers at defense ministries, and executives at commercial imagery operators anchored the qualitative base. Primary interviews combined with secondary validation against NRO budget justifications, ESA procurement databases, Japan Cabinet Satellite Intelligence Center reports, and U.S. Space Force capability roadmaps. Bottom-up segment sizing triangulated against top-down defense spending analysis across NATO member states.
Scenario-bracketing around ITAR relaxation timelines and gallium nitride supply disruption probabilities shaped the projection framework. Segmentation modeling spanned sensor modality, orbital altitude, end-user classification, and security clearance tier throughout the forecast period. CAGRs derived from procurement pipeline visibility and constellation deployment schedules. Synthetic aperture radar adoption curves and commercial subscription conversion rates served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in defense budget trajectories or semiconductor trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding classified program continuity and allied-nation technology-sharing frameworks. Material shifts in U.S. export control classifications or East Asian foundry capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Global Small Satellite Service Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
North America Remote Sensing Services Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
China Satellite Imagery Services Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Small Satellite Market
Satellite
Satellite Gateway Market
Satellite
Global Commercial Satellite Imaging Market
Satellite
Satellite Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Germany Satellite Connectivity Market