
 Flying Taxi Market | 2026-2036
Flying Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Flying Taxi Market Analysis
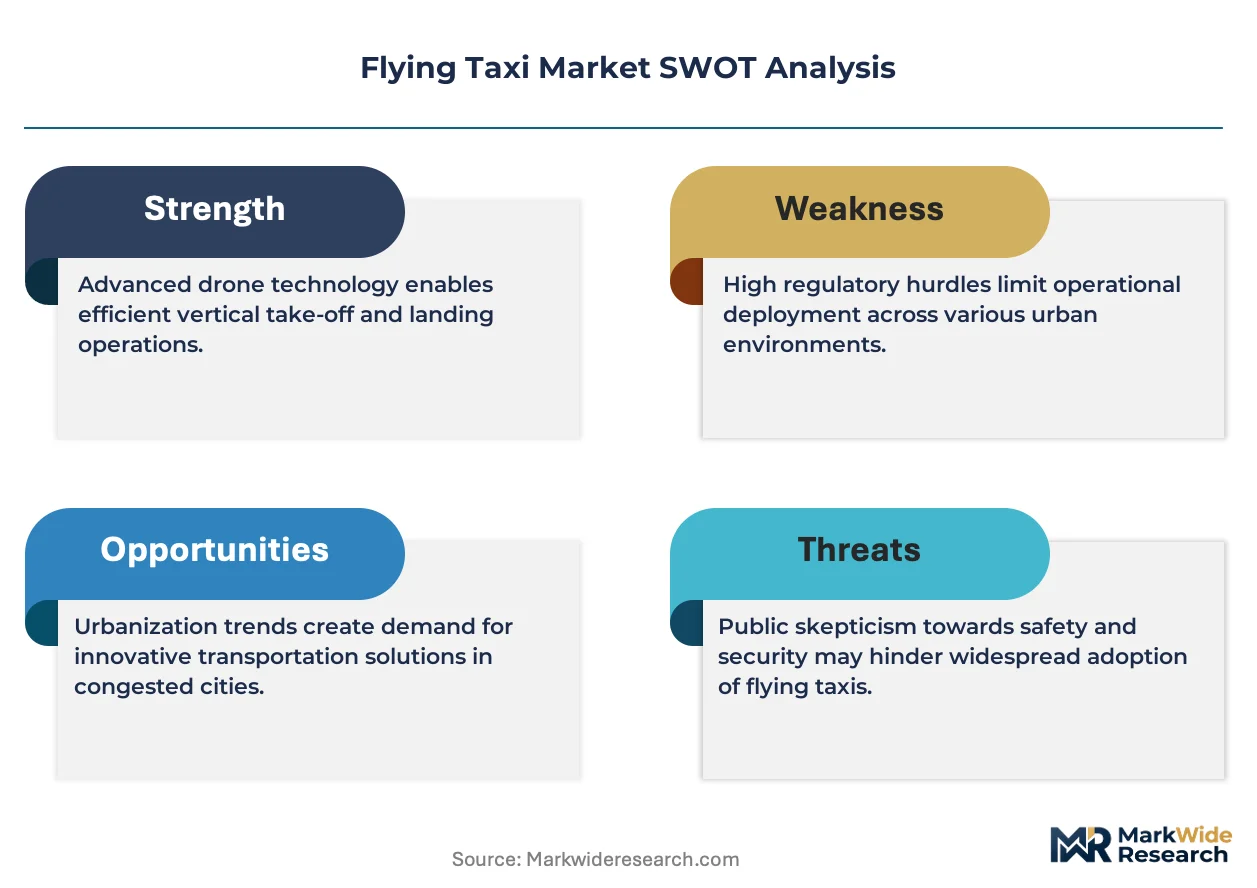
The capital-intensity divergence between well-funded aerospace conglomerates and venture-backed startups is unwinding competitive dynamics across the sector. Hyundai Motor Company leverages its automotive manufacturing scale to drive down per-unit airframe costs. Joby Aviation sustains an early-mover advantage through extensive flight-test hours and FAA certification progress. EHang Holdings dominates the Asian pilotless segment with operational permits in multiple Chinese municipalities.
Flying taxis are electrically powered vertical-takeoff-and-landing aircraft designed for short-haul urban transit, typically operating at cruise speeds between 100 and 200 knots with ranges of 25 to 150 nautical miles depending on battery configuration and aerodynamic design. Their primary commercial purpose is to bypass ground congestion through point-to-point aerial corridors in metropolitan regions. The eVTOL vehicle type captures the dominant engineering investment pool due to its simplified mechanical complexity and reduced maintenance burden versus hybrid architectures. On-demand operational models attract the largest share of venture funding, though scheduled commuter services between airports and central business districts present more predictable unit economics. Charter configurations currently occupy a premium niche serving high-net-worth individuals and time-sensitive corporate travelers.
The FAA's Part 135 framework and EASA's SC-VTOL special condition govern commercial entry requirements in North America and Europe, while China's CAAC issues type certificates under GB standards adapted for low-altitude urban operations. These regulatory pathways directly determine which vehicle architectures achieve operational approval first and where fleet deployments commence. Stakeholders must monitor certification timeline accelerations or delays as the primary signal for capital allocation timing across manufacturing and infrastructure buildout.
Market Dynamics
The FAA's Part 135 certification pathway is compressing operator readiness timelines and forcing capital reallocation toward flight-test validation ahead of manufacturing scale-up.
Growth Catalysts
- Airspace Integration Frameworks:The FAA's Part 135 pathway and EASA's SC-VTOL special condition are creating predictable regulatory on-ramps for commercial operators in the United States and Germany.
- Battery Energy Density Gains:Solid-state lithium-metal cells are extending eVTOL range envelopes from 25 toward 150 nautical miles without hybrid architecture complexity.
- Urban Congestion Pricing:London, Singapore, and New York congestion charges are elevating the value proposition of point-to-point aerial corridors for time-sensitive commuters.
Market Restraints
- Lithium Supply Concentration:Cathode precursor refining concentrates in China, exposing airframe manufacturers to input cost volatility and geopolitical supply risk.
- Vertiport Infrastructure Gap:Real estate scarcity in central business districts limits landing zone availability and drives site acquisition costs upward.
- Hybrid Architecture Persistence:Turboelectric range extenders retain operational flexibility advantages in markets with immature charging networks, slowing pure-electric adoption.
Strategic Opportunities
- Inter-City Airport Shuttles:Scheduled services connecting John F. Kennedy International Airport to Manhattan present more predictable unit economics than on-demand models.
- Autonomous Operations:CAAC pilotless permits in Chinese municipalities are creating a regulatory sandbox for remote-supervision business models ahead of Western certification.
- Vertiport-Real Estate Convergence:Mixed-use developments in Dubai and Los Angeles are integrating rooftop landing infrastructure with hospitality and commercial tenants.
Industry Challenges
- Flight-Test Engineer Scarcity:The pool of professionals with rotary-wing and fixed-wing certification experience simultaneously is insufficient for parallel vehicle programs.
- Certification Timeline Uncertainty:FAA mean-time-between-failure requirements for tilt-rotor actuation systems remain unresolved, delaying type certificate issuance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flying Taxi Market |
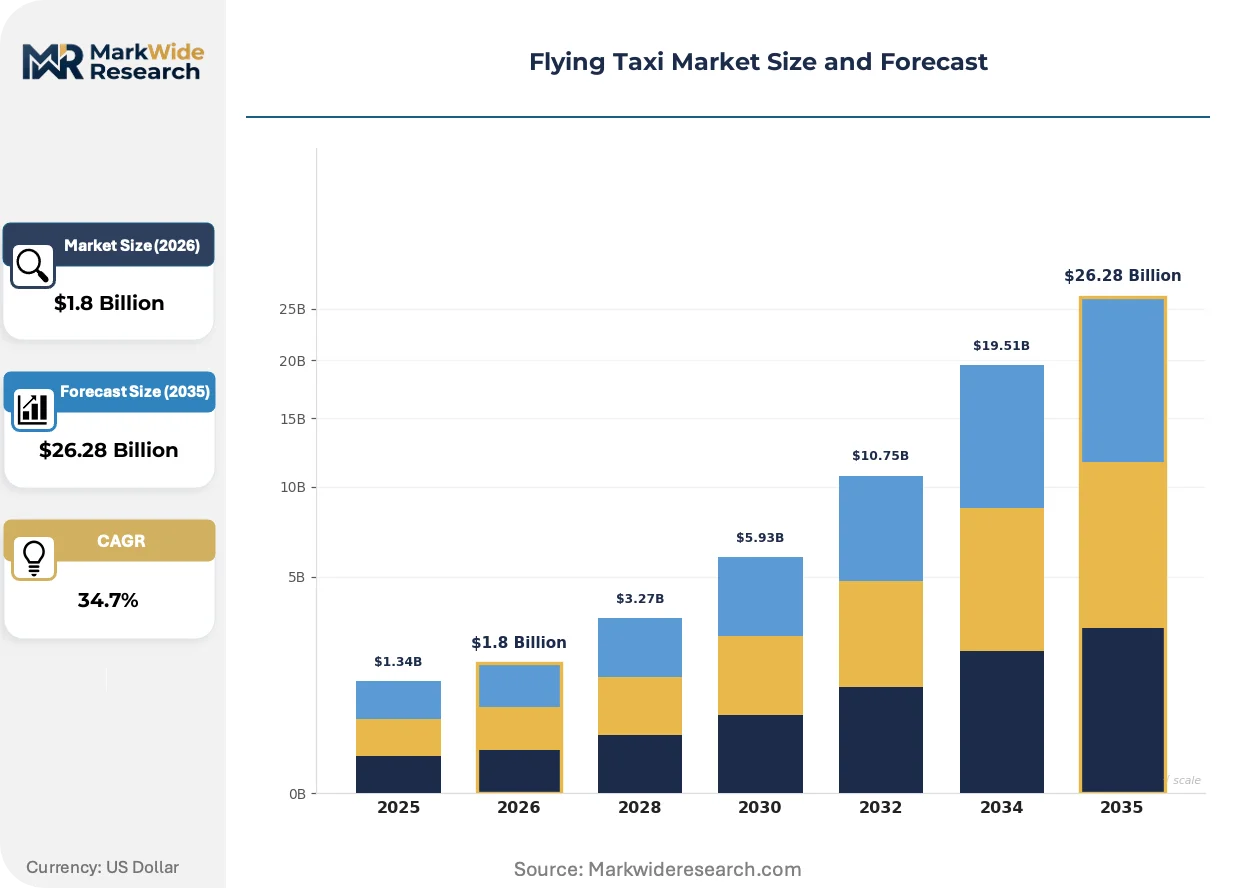
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Operational Model: On-Demand, Scheduled, Charter, Shared Vehicle Type: eVTOL, Multicopter, Fixed-Wing, Hybrid Regulatory Framework: Part 135, Part 91, Urban Air Mobility, Cargo End User: Commuters, Tourists, Businesses, Government |
| Companies Covered | Hyundai Motor Company, The Boeing Company, Joby Aviation, Volocopter, Lilium, Archer Aviation, Airbus SE, Beta Technologies, EHang Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flying Taxi Market Emerging Trajectories
Distributed electric propulsion architectures are rewriting airframe design constraints, while regulatory bodies race to certify autonomous flight systems ahead of operational demand.
Silicon-carbide power electronics are displacing silicon IGBT modules in motor controllers. Tier-one aerospace suppliers are adopting these wide-bandgap semiconductors for their thermal efficiency and switching-speed advantages. This transition is displacing legacy thermal management hardware and enabling higher power density in compact nacelle packages.
EASA's SC-VTOL special condition is mandating fault-tolerant flight-control architectures for commercial passenger operations. The regulation requires redundant flight-computer channels and independent power distribution buses. European operators are responding by restructuring supplier qualification programs to prioritize aviation-grade component traceability over automotive heritage.
Corporate travel managers are consolidating ground and aerial mobility procurement under single-vendor enterprise contracts. Airlines and eVTOL operators are forming interline agreements to bundle airport transfers with long-haul tickets. This bundling is most visible in the United States, where Delta Air Lines has integrated Joby Aviation reservations into its loyalty platform.
Flying Taxi Market Segmentation
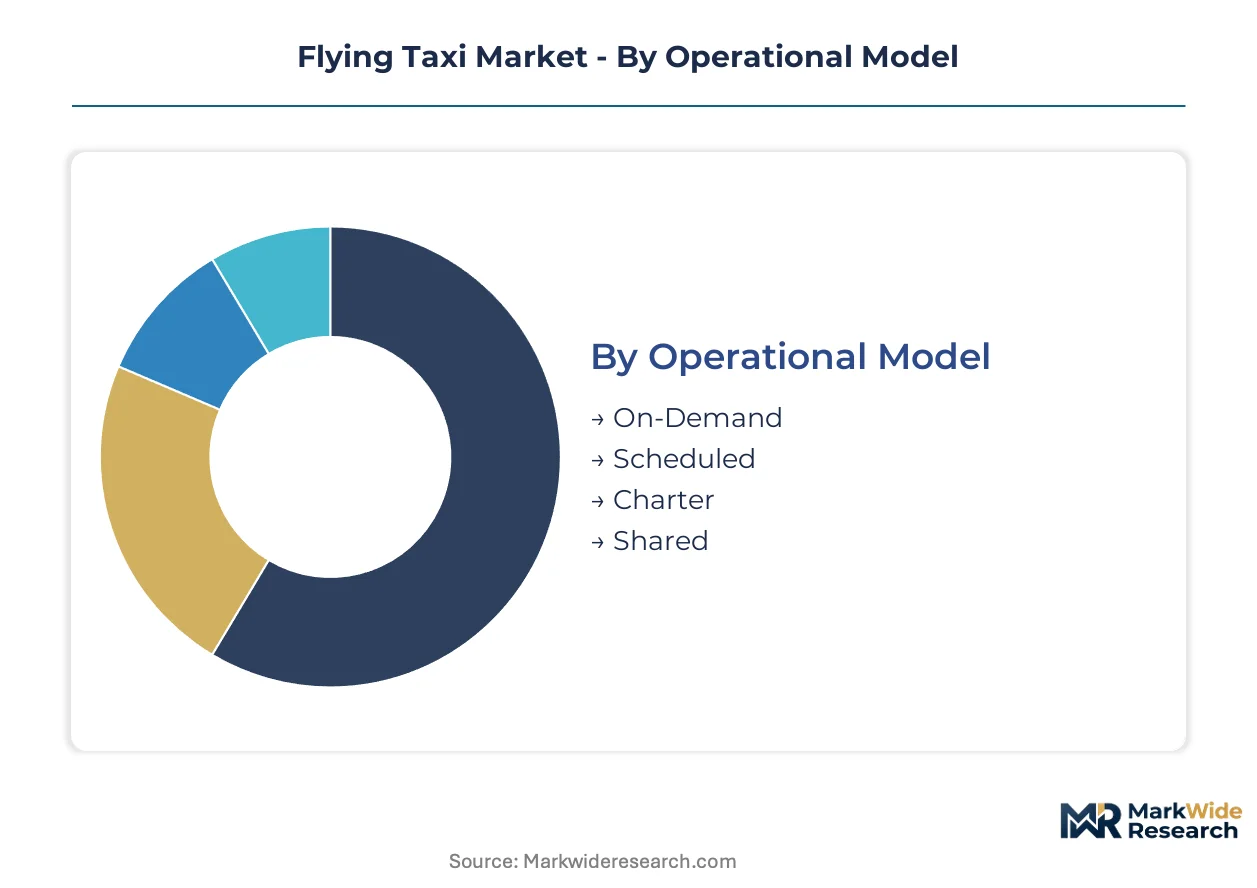
Segmentation in the flying taxi market determines which vehicle architectures and operational models align with specific regulatory pathways and infrastructure readiness levels. Regulatory frameworks vary sharply by jurisdiction, forcing operators to match certification timelines with capital deployment strategies.
Operational Model:
FAA Part 135 certification requirements create divergent compliance burdens across service configurations, directly shaping unit economics and fleet utilization rates.
- On-Demand:Point-to-point bookings triggered through mobile applications dominate venture capital flows. Manhattan-to-JFK corridors attract the highest trip frequency, though per-seat economics remain challenging below four-passenger load factors.
- Scheduled:Fixed-route services between airports and central business districts offer predictable demand curves. Dubai's vertiport network demonstrates how scheduled shuttles achieve utilization rates above on-demand alternatives.
- Charter:Exclusive-occupancy configurations serve time-sensitive corporate travelers. Premium pricing absorbs higher per-mile operating costs.
- Shared:Multi-party pooling models reduce per-passenger fares. CAAC pilotless permits in Shenzhen enable remote-supervision cost structures unavailable in Western markets.
Established volume favors Scheduled; emerging adoption favors Shared.
Vehicle Type:
Powertrain architecture selection hinges on battery energy density thresholds and charging infrastructure maturity across target operating regions.
- eVTOL:Distributed electric propulsion with tilt-rotor or lift-plus-cruise configurations captures the dominant engineering investment pool. EASA SC-VTOL fault-tolerance mandates favor redundant flight-control architectures in European certification pathways.
- Multicopter:Simplified mechanical design with eight or more rotors enables pilotless operation. Chinese municipalities issue operational permits for multicopter cargo services ahead of passenger certification.
- Fixed-Wing:Conventional aerodynamic efficiency suits longer inter-city corridors. Runway dependency limits vertiport flexibility.
- Hybrid:Turboelectric range extenders retain operational advantages in markets with immature charging networks. German operators evaluate hybrid architectures for rural air ambulance applications.
Engineering investment concentrates on eVTOL; hybrid architectures gain traction where grid infrastructure lags.
Regulatory Framework:
Certification pathway selection locks operators into specific operational constraints and geographic markets for multi-year horizons.
- Part 135:FAA commercial air carrier certification mandates operational control standards and pilot qualification requirements. US operators prioritize Part 135 readiness for revenue service entry.
- Part 91:Private operation rules enable experimental flight-test programs and owner-pilot configurations. Lower regulatory burden limits commercial scalability.
- Urban Air Mobility:Emerging regulatory category under development by EASA and FAA harmonization working groups. Framework uncertainty delays fleet deployment commitments.
- Cargo:Unmanned aerial system regulations permit remote-supervised freight operations. China's CAAC leads operational permit issuance for autonomous cargo corridors.
Commercial revenue flows through Part 135; experimental validation advances under Part 91.
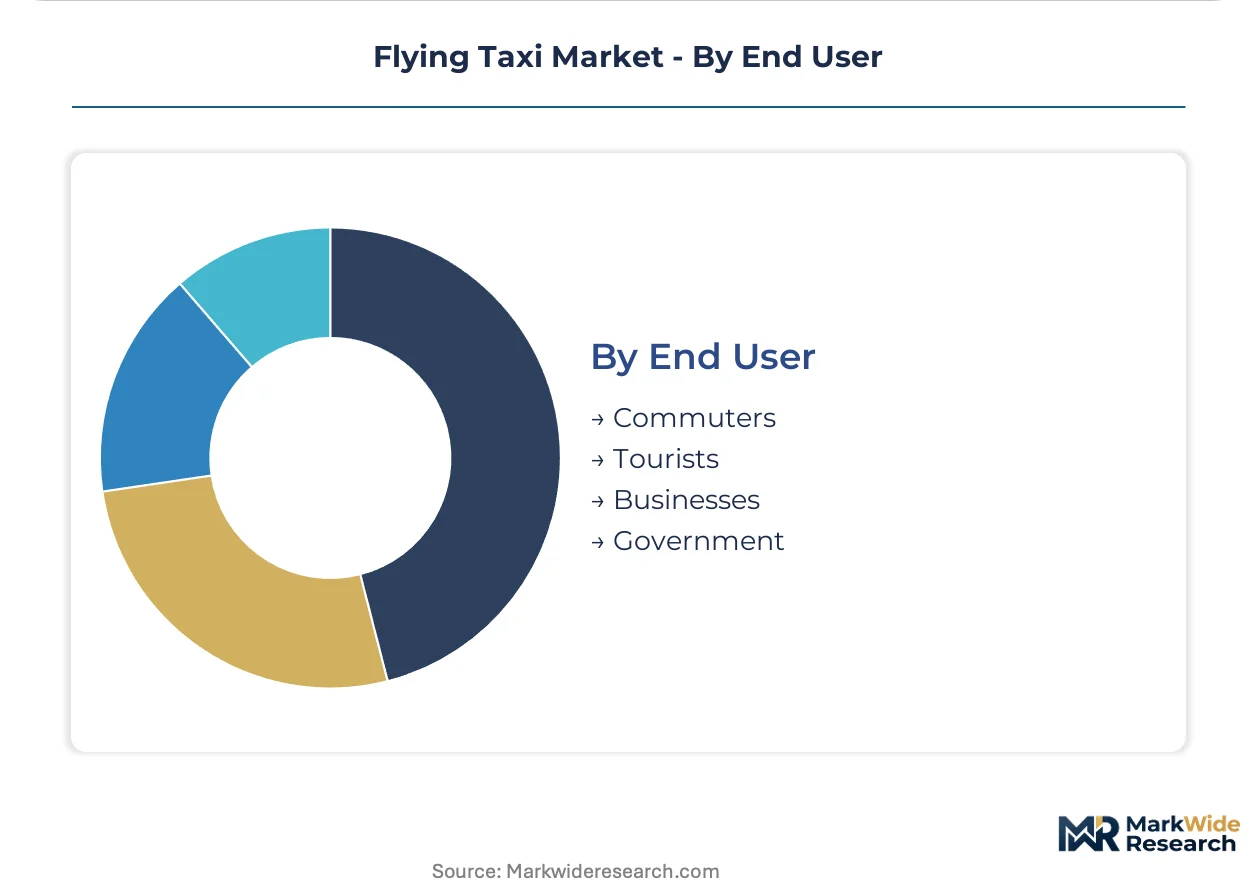
End User:
Customer segmentation reflects divergent price sensitivity, trip purpose, and regulatory risk tolerance across passenger and non-passenger applications.
- Commuters:Daily work-trip travelers in congested megacities form the core addressable market. Singapore congestion pricing elevates willingness-to-pay for aerial alternatives.
- Tourists:Sightseeing and experience-driven demand concentrates in Dubai, Los Angeles, and coastal Chinese cities. Seasonal demand curves challenge fleet utilization.
- Businesses:Corporate travel managers bundle ground and aerial mobility under single-vendor contracts. Delta Air Lines integrates eVTOL reservations into loyalty platforms for business travelers.
- Government:Public-sector demand spans air ambulance, law enforcement, and infrastructure inspection applications. German federal procurement prioritizes domestic airframe suppliers.
Corporate procurement drives near-term contract value; government tenders extend program timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate travelers in the United States show the highest price inelasticity for premium aerial transit, while Asian commuter markets demand fare structures competitive with ground-based ride-hailing. European buyers occupy a middle tier, prioritizing regulatory assurance over cost minimization.
United States
Manhattan-to-JFK corridors generate the highest trip frequency globally, with corporate travel managers bundling aerial transfers into enterprise mobility contracts. The FAA's Part 135 certification pathway mandates operational control standards that compress operator readiness timelines. Los Angeles hosts the most advanced vertiport-real estate convergence, with rooftop landing infrastructure integrated into mixed-use hospitality developments.
China
Shenzhen and Guangzhou municipalities issue operational permits for pilotless multicopter services ahead of Western certification timelines. The CAAC adapts GB standards for low-altitude urban operations, creating regulatory sandboxes for remote-supervision business models. The Yangtze River Delta cluster concentrates domestic airframe manufacturing and battery supply chain integration.
Germany
Munich and Hamburg corporate travelers drive scheduled shuttle demand between airports and central business districts. EASA's SC-VTOL special condition mandates fault-tolerant flight-control architectures with redundant computer channels. Bavaria anchors the domestic supplier qualification ecosystem, prioritizing aviation-grade component traceability over automotive heritage.
United Arab Emirates
Dubai's tourism-driven sightseeing demand creates seasonal utilization challenges for fleet operators. The General Civil Aviation Authority accelerates vertiport licensing for rooftop and waterfront landing zones. The emirate's mixed-use developments integrate hospitality and commercial tenants with dedicated aerial mobility infrastructure.
Japan
Tokyo's congestion pricing mechanisms elevate willingness-to-pay for point-to-point aerial alternatives among daily commuters. METI coordinates urban air mobility demonstration projects linking Narita Airport to the capital's financial districts. The Kanto region hosts flight-test validation partnerships between domestic aerospace suppliers and international eVTOL developers.
Flying Taxi Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the flying taxi sector. Aerospace conglomerates with legacy certification experience compete against venture-backed startups prioritizing flight-test velocity. Three archetypes dominate: automotive-scale manufacturers leveraging production expertise, pure-play eVTOL developers accumulating regulatory milestones, and established airframers extending rotorcraft portfolios. Competitive moves concentrate on strategic partnerships with airlines for interline agreements and vertiport infrastructure joint ventures with real estate developers.
Among automotive-origin entrants, Hyundai Motor Company exemplifies the manufacturing-scale archetype applying production cost discipline to airframe fabrication. Within the pure-play certification-focused tier, Joby Aviation and Archer Aviation occupy positions defined by FAA Part 135 progress and flight-test hour accumulation. EHang Holdings anchors the pilotless-operations segment, representing the regulatory-sandbox approach enabled by Chinese municipal permits. These three companies illustrate the strategic divergence between manufacturing heritage, certification velocity, and autonomous-flight regulatory positioning.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| The Boeing Company |
| Joby Aviation |
| Volocopter |
| Lilium |
| Archer Aviation |
| Airbus SE |
| Beta Technologies |
| EHang Holdings |
| Others |
Supply Flow & Price Mechanics
Solid-state lithium-metal cell adoption is displacing conventional lithium-ion architectures, simultaneously shifting cathode precursor sourcing toward Chinese refiners and compressing per-kilowatt-hour cost curves for airframe manufacturers. This substitution dynamic concentrates pricing power among integrated battery suppliers while exposing operators to geopolitical input volatility.
Pricing Analysis
After-sales service contracts and flight-hour maintenance agreements drive lifetime value beyond initial airframe sales. Three-tier pricing structure across premium charter, scheduled shuttle, and shared-pool economy levels segments buyers by time sensitivity and load-factor tolerance. Pricing pressure stems from battery raw material concentration in Chinese processing facilities. Corporate travel managers show lowest price sensitivity; leisure commuters in Asian megacities demand fare parity with ground ride-hailing.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for European airframe assemblers. Cathode precursor refining concentrates in China; silicon-carbide wafer fabrication centers on Taiwan and Germany; composite airframe structures source from Japan and the United States. Lithium supply concentration creates single-source vulnerability for tier-one battery suppliers. Distribution runs through vertiport infrastructure joint ventures with real estate developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including flight-hour maintenance, pilot training subscriptions, and vertiport access fees are expanding faster than hardware sales, creating recurring-income opportunities for platform operators.
For Market Incumbents: Shield certification timelines from flight-test engineer scarcity by acquiring rotary-fixed-wing dual-qualified talent pools. Prioritize backward integration into battery pack assembly to offset Chinese cathode cost volatility. Lock in long-term vertiport site leases before real estate scarcity intensifies in Manhattan and Los Angeles central business districts. For New Entrants and Emerging Players: Anchor in autonomous cargo corridors where CAAC permits enable remote-supervision cost structures unavailable under FAA Part 135. Target Chinese municipalities piloting pilotless multicopter services ahead of Western passenger certification. Pursue interline agreements with legacy airlines as the primary go-to-market channel for airport shuttle demand. For Investors and Strategic Acquirers: The market sits at a pre-revenue commercialization phase that favors certification-velocity archetypes over manufacturing-scale players. Five-to-ten year viability hinges on FAA type certificate issuance timelines. Acquisition targets should demonstrate fault-tolerant flight-control architectures meeting EASA SC-VTOL standards. Monitor Part 135 certification accelerations as the primary capital deployment signal.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 135 Certification Pursuit | Unlocks commercial revenue service in United States urban corridors ahead of operational competitors. |
| Vertiport-Real Estate Joint Venture | Secures scarce rooftop landing zones in Los Angeles and Dubai mixed-use developments. |
| Airline Interline Agreement | Bundles eVTOL airport transfers with Delta Air Lines loyalty platform for corporate travelers. |
| Silicon-Carbide Power Electronics Transition | Enables higher power density in compact nacelle packages through wide-bandgap semiconductor adoption. |
| Autonomous Flight Certification Investment | Positions operators for CAAC pilotless permits in Shenzhen and Guangzhou regulatory sandboxes. |
Methodological Framework
Initial hypotheses were tested against primary input from eVTOL program directors, FAA certification leads, vertiport infrastructure developers, and airline partnership executives and refined through secondary validation across FAA type certificate filings, EASA SC-VTOL special condition documentation, CAAC operational permit registries, and vertiport real estate development announcements. Bottom-up fleet deployment models triangulated against top-down urban congestion pricing elasticity estimates.
Variance decomposition across operational model, vehicle architecture, and regulatory framework dimensions structured the analytical framework over the projection horizon. CAGRs derived from battery energy density improvement curves and airspace integration timeline assumptions. Segmentation modeling incorporated piloted versus autonomous certification pathways, tilt-rotor versus multicopter propulsion configurations, and Part 135 versus Part 91 operational categories.
Underlying assumptions cover lithium-metal cell commercialization schedules and municipal vertiport zoning approvals, with deviation risk concentrated in FAA mean-time-between-failure requirement resolutions for tilt-rotor actuation systems. Recalibration cycles align with material shifts in certification timeline announcements and battery supply contract disclosures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
South America Offshore Helicopter Services Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Airborne Pods Market
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
Hang Glider Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Global Flying Cars Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
Global Aerodynamics Market