
 Global Aerial Imaging Market | 2026-2036
Global Aerial Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerial Imaging Market Foresight
Sub-centimeter ground sample distance is bifurcating the competitive landscape between premium geospatial service providers and volume drone operators. DJI Technology Co., Ltd. leverages its manufacturing scale to dominate consumer and prosumer hardware tiers. EagleView Technologies, Inc. differentiates through proprietary image libraries and insurance industry channel control. Nearmap Ltd anchors its position with high-frequency aerial capture programs across metropolitan areas.
Aerial imaging encompasses the acquisition of georeferenced photographic, multispectral, LiDAR, or thermal data from elevated platforms operating at altitudes from fifty meters to orbital heights, with spatial resolutions ranging from sub-meter to thirty-meter ground sample distances depending on sensor payload and platform altitude. The primary commercial purpose centers on creating actionable geospatial intelligence for asset monitoring, land use planning, and environmental assessment. Rotary-wing UAV platforms lead in deployment frequency for infrastructure inspection due to vertical takeoff flexibility and hovering precision, while fixed-wing systems capture margin pools in large-area terrain mapping through extended endurance and reduced per-acre flight costs. Thermal imaging segments show structural momentum in energy operator use cases, particularly pipeline leak detection and solar farm performance auditing.
The FAA governs commercial drone operations through Part 107 certification and emerging beyond-visual-line-of-sight rulemakings that reshape market access for automated inspection services. EASA's specific category framework under EU Regulation 2019/947 and the EU AI Act's risk classification for autonomous aerial systems create compliance thresholds for European deployment. China's CAAC coordinates with MIIT on low-altitude economy policies that accelerate domestic unmanned aerial system commercialization. Stakeholders must monitor regulatory divergence between permissive experimental frameworks and restrictive certification requirements when allocating platform development resources across jurisdictions.
Market Dynamics
The FAA's Part 107 expansion for beyond-visual-line-of-sight operations is compressing deployment timelines for automated inspection services while fragmenting competitive advantage between hardware manufacturers and geospatial analytics platforms.
Growth Catalysts
- Precision agriculture adoption:Farmers deploy drone-mounted multispectral sensors to optimize crop yields and reduce input waste.
- FAA Part 107 expansion:Beyond-visual-line-of-sight rulemakings accelerate commercial deployment for infrastructure inspection.
- Utility operator scaling:US power and pipeline operators expand aerial monitoring programs for predictive maintenance.
Market Restraints
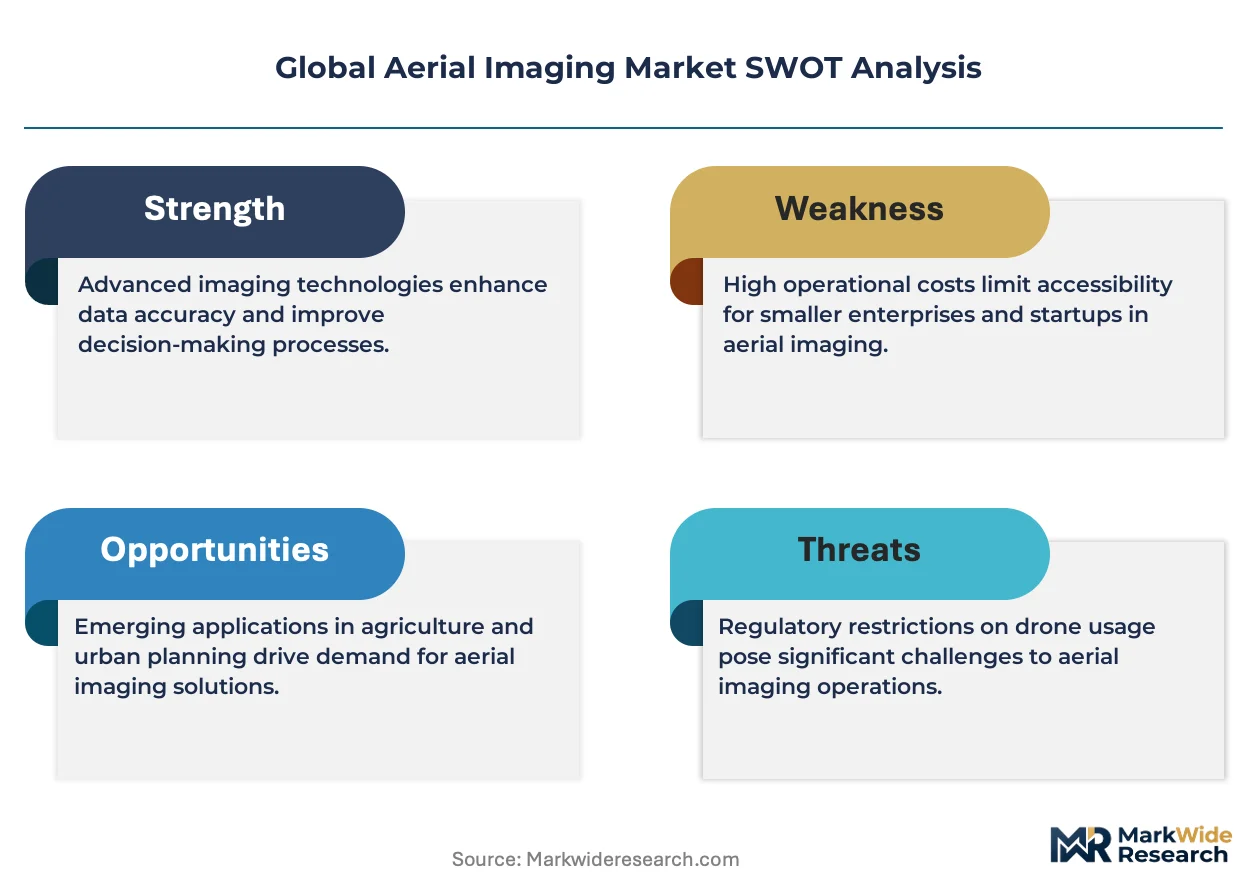
- Sensor payload costs:LiDAR and thermal imaging modules command premium pricing that limits mid-tier operator participation.
- Regulatory fragmentation:Divergent certification requirements between FAA, EASA, and CAAC complicate cross-border platform deployment.
- Satellite imagery substitution:Commercial Earth observation constellations erode addressable market for wide-area terrain mapping.
Strategic Opportunities
- India low-altitude economy:DGFT and CEA coordination on unmanned aerial system commercialization creates first-mover positioning.
- Insurance channel integration:Property and casualty carriers adopt aerial imagery for claims verification and risk underwriting.
- AI-photogrammetry convergence:Machine learning pipelines automate feature extraction from orthomosaic datasets.
Industry Challenges
- Remote pilot certification timelines:FAA Part 107 practical testing bottlenecks constrain operator supply for commercial fleets.
- Legacy GIS integration:Municipal planning departments require custom API development to ingest drone-derived data layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerial Imaging Market |
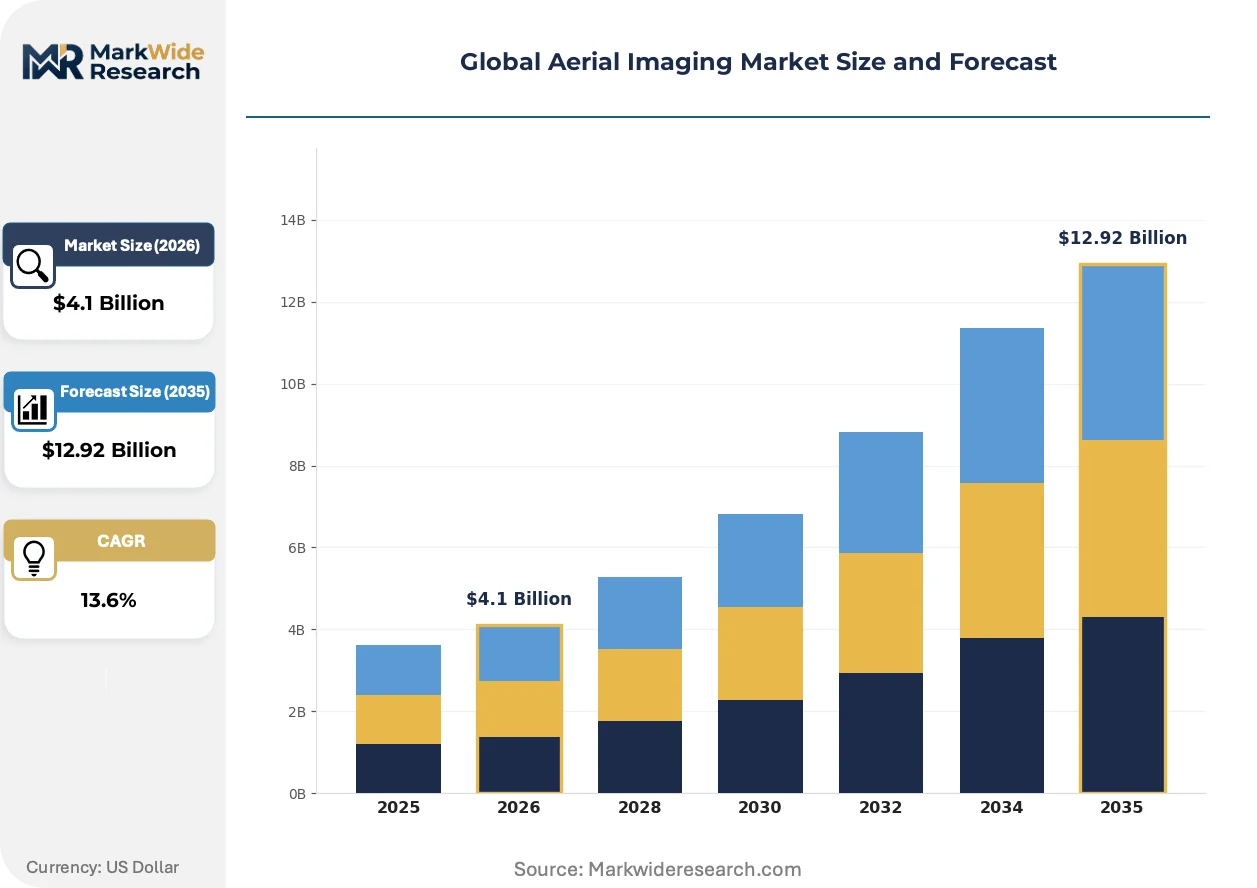
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $12.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
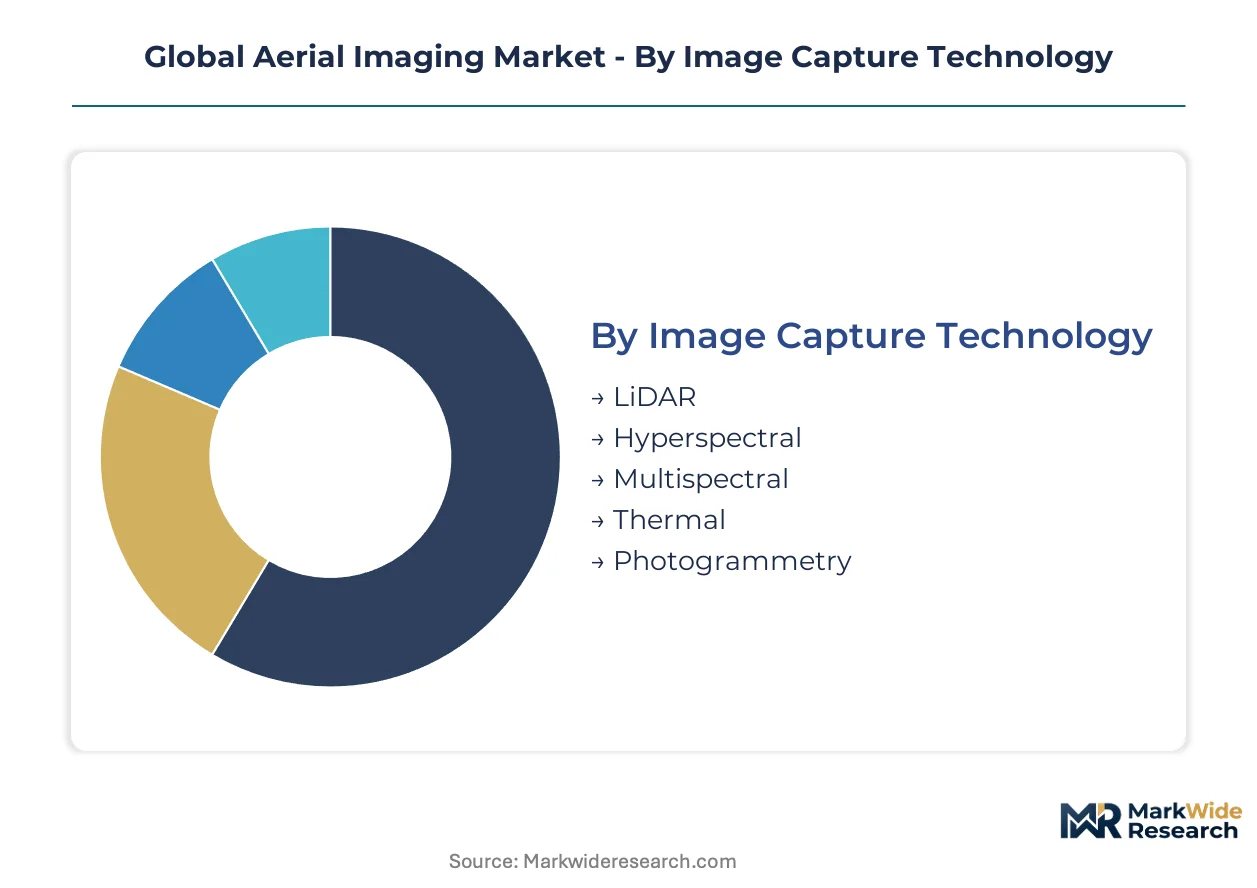
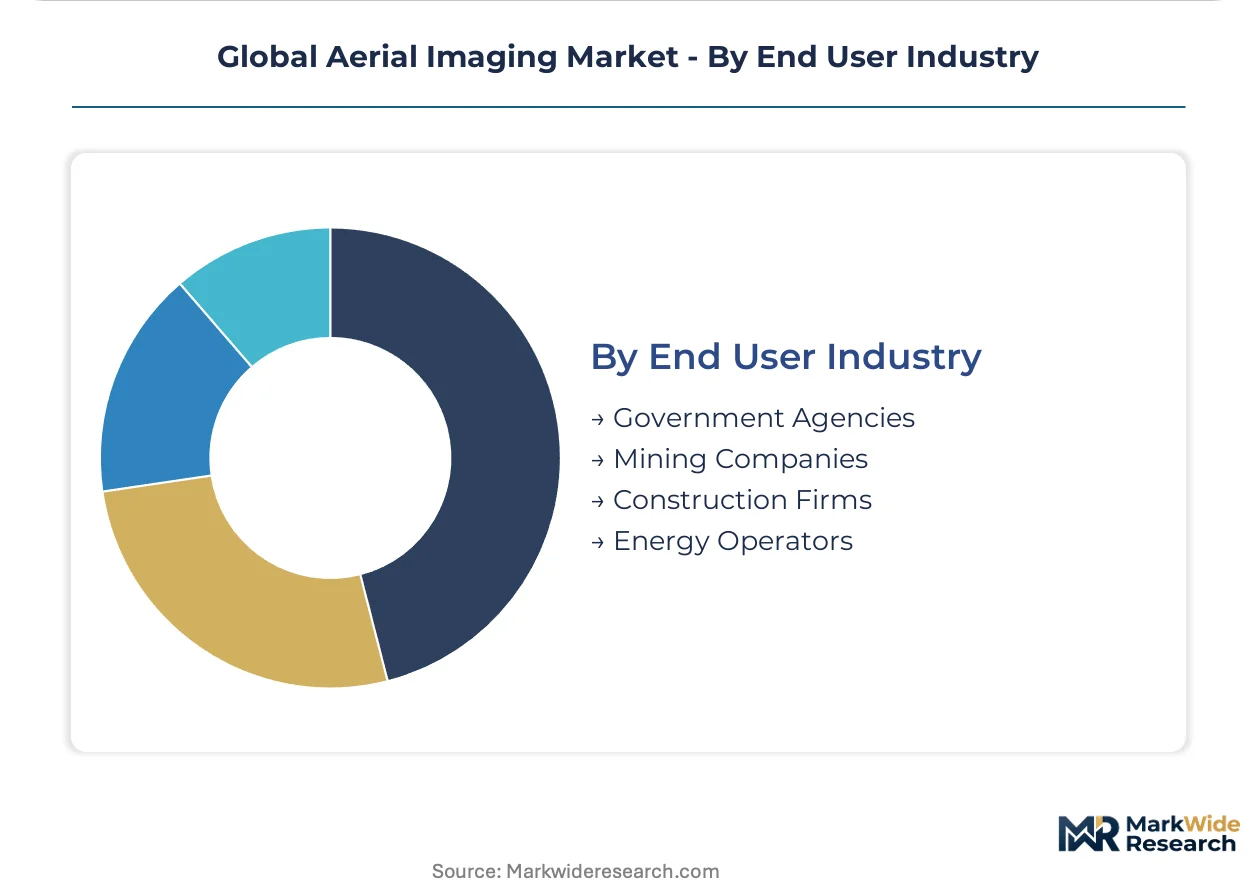
| Segmentation | Image Capture Technology: LiDAR, Hyperspectral, Multispectral, Thermal, Photogrammetry Platform Type: Fixed-Wing UAV, Rotary-Wing UAV, Satellites, Manned Aircraft Application: Precision Agriculture, Terrain Mapping, Infrastructure Inspection, Disaster Management, Environmental Monitoring End User Industry: Government Agencies, Mining Companies, Construction Firms, Energy Operators |
| Companies Covered | DJI Technology Co., Ltd., EagleView Technologies, Inc., Nearmap Ltd, Fugro N.V., Hexagon AB, Trimble Inc., Vexcel Imaging GmbH, Parrot Drones SAS, Skydio, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerial Imaging Market Shifts & Advancements
Sensor miniaturization and edge computing architectures are redistributing value capture from airborne platforms toward real-time analytics engines.
Hyperspectral imaging payloads are supplanting standard RGB and multispectral sensors for vegetation stress detection. Viticulture and specialty crop operators in California and France adopt these systems for irrigation timing and disease early warning. The technology is supplanting manual scouting labor and compressing subscription pricing for crop monitoring services.
EASA's specific category framework under EU Regulation 2019/947 and the EU AI Act's risk classification for autonomous aerial systems impose compliance thresholds on European deployment. Operators must demonstrate operational safety cases for flights over populated areas. Insurance and infrastructure inspection segments are responding by segregating fleet operations between certified and experimental airframes.
Subscription-based imagery licensing is displacing per-project photogrammetry contracts among municipal governments and construction firms. Channel intermediaries including equipment distributors and surveying consultancies are losing margin to direct platform relationships. This pattern concentrates in Australia and the United Kingdom where Nearmap and EagleView have established metropolitan capture programs.
Global Aerial Imaging Market Segmentation
Platform altitude and sensor payload combinations determine regulatory jurisdiction and operational economics across deployment scenarios. Procurement patterns diverge between government agencies requiring certified workflows and commercial operators optimizing per-acre capture costs.
Image Capture Technology:
FAA Part 107 altitude waivers and EASA's specific category framework create divergent compliance burdens for sensor-heavy payloads versus lightweight alternatives.
- LiDAR:Active laser scanning generates dense point clouds for topographic modeling and corridor mapping. Energy operators in Texas and Alberta deploy these systems for pipeline elevation profiling where vegetation penetration matters.
- Hyperspectral:Narrow-band spectral sampling detects vegetation stress and mineral signatures invisible to standard sensors. Viticulture operations in California's Central Valley and France's Bordeaux region adopt these for irrigation timing and disease early warning.
- Multispectral:Discrete band imaging supports normalized difference vegetation index calculations for crop health monitoring.
- Thermal:Infrared radiometry identifies heat anomalies in electrical infrastructure and building envelopes.
- Photogrammetry:Stereoscopic image processing reconstructs three-dimensional surfaces from overlapping aerial photographs.
Established volume favors photogrammetry; emerging adoption favors hyperspectral.
Platform Type:
Endurance requirements and takeoff constraints segment procurement between vertical-lift flexibility and long-range efficiency.
- Rotary-Wing UAV:Multirotor systems enable hovering precision and vertical takeoff from confined sites. Utility operators across Germany and Japan scale these for substation and transmission tower inspection where maneuverability dominates.
- Fixed-Wing UAV:Aerodynamic efficiency extends flight duration for large-area terrain mapping. Surveying contractors in Australia and Brazil deploy these for mining lease boundary verification and agricultural parcel delineation.
- Satellites:Orbital platforms provide systematic revisit coverage for change detection at continental scale.
- Manned Aircraft:Piloted systems carry heavy sensor payloads for metropolitan-scale capture programs.
Procurement concentrates in rotary-wing for infrastructure; fixed-wing climbs the fastest for agriculture.
Application:
Return-on-measurement timelines vary from immediate operational decisions to long-cycle planning horizons.
- Precision Agriculture:Sub-field variable-rate prescriptions reduce fertilizer and irrigation inputs. Large-scale farming cooperatives in Iowa and São Paulo state integrate drone-derived NDVI layers with tractor-mounted application equipment.
- Infrastructure Inspection:Predictive maintenance programs replace calendar-based asset surveys. Power grid operators in the United Kingdom and South Korea deploy automated flight paths for transmission corridor monitoring.
- Terrain Mapping:Digital elevation models support engineering design and flood risk assessment.
- Disaster Management:Rapid deployment capabilities enable post-event damage inventory and search coordination.
- Environmental Monitoring:Repeatable capture protocols track ecosystem change and regulatory compliance.
Commercial margin pools deepest in precision agriculture; regulatory tailwinds strengthen environmental monitoring.
End User Industry:
Budget cycles and risk tolerance separate public procurement from private capital deployment.
- Government Agencies:Municipal planning departments and environmental regulators require auditable data provenance. India's Ministry of Rural Development and Indonesia's national mapping agency specify certified georeferencing for cadastral programs.
- Energy Operators:Oil, gas, and renewable asset managers prioritize predictive maintenance to minimize unplanned outages. Offshore wind farm developers in the North Sea and Gulf of Mexico use aerial thermal surveys for blade defect detection.
- Construction Firms:Earthwork volume calculations and progress documentation support project controls.
- Mining Companies:Pit wall stability monitoring and stockpile inventory management integrate with enterprise resource planning systems.
Contracting velocity favors energy operators; procurement scale favors government agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply by jurisdiction: United States utility operators absorb premium sensor costs for predictive maintenance, while Indian agricultural cooperatives prioritize per-acre flight economics over spectral sophistication.
United States
Utility operators across Texas and California scale automated transmission corridor monitoring using beyond-visual-line-of-sight waivers. FAA Part 107 expansion compresses deployment timelines for infrastructure inspection services. Houston and Denver anchor metropolitan capture programs where insurance carriers integrate aerial imagery into property underwriting workflows.
Germany
Grid operators deploy rotary-wing systems for substation thermography under EASA's specific category framework. The EU AI Act's risk classification for autonomous aerial systems imposes operational safety cases for flights over populated areas. Munich and Stuttgart concentrate precision viticulture adoption where hyperspectral sensors detect vineyard stress patterns.
China
CAAC coordination with MIIT on low-altitude economy policies accelerates unmanned aerial system commercialization for agricultural parcel delineation. Domestic manufacturing scale drives hardware cost compression for multispectral payloads. Shenzhen and Beijing anchor metropolitan drone logistics pilots that expand regulatory tolerance for automated flight operations.
Australia
Mining lease boundary verification and agricultural water stress monitoring dominate fixed-wing deployment across Queensland and Western Australia. Subscription-based imagery licensing displaces per-project contracts among municipal governments. Sydney and Melbourne anchor high-frequency aerial capture programs that compress channel intermediary margins.
Brazil
São Paulo state farming cooperatives integrate drone-derived NDVI layers with tractor-mounted application equipment for variable-rate prescriptions. Regulatory frameworks lag FAA and EASA maturity, creating first-mover positioning for experimental flight operations. The Central-West agricultural belt concentrates adoption where soy and sugarcane operators optimize input deployment across sub-field zones.
Global Aerial Imaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across hardware manufacturing and geospatial analytics. The market structures around three tiers: integrated platform manufacturers, specialized sensor developers, and subscription-based imagery aggregators. Consolidation pressures concentrate among analytics platforms seeking proprietary capture libraries, while hardware fabrication fragments across contract manufacturers. Dominant competitive moves include strategic partnerships between drone operators and insurance carriers, plus portfolio diversification into AI-powered feature extraction.
Within the integrated manufacturing tier, DJI Technology Co., Ltd. and Skydio, Inc. represent divergent scale positions. Among geospatial service providers, EagleView Technologies, Inc. and Nearmap Ltd exemplify contrasting channel strategies for imagery licensing. Vexcel Imaging GmbH occupies a position bridging sensor fabrication and metropolitan capture program execution.
| Leading Market Players |
|---|
| DJI Technology Co., Ltd. |
| EagleView Technologies, Inc. |
| Nearmap Ltd |
| Fugro N.V. |
| Hexagon AB |
| Trimble Inc. |
| Vexcel Imaging GmbH |
| Parrot Drones SAS |
| Skydio, Inc. |
| Others |
Supply & Pricing Matrix
Manufacturing scale economies in Shenzhen and Dongguan compress sensor payload costs while anchoring price floors for rotary-wing platforms. CAAC-MIIT coordination on low-altitude economy policies accelerates domestic production capacity, concentrating bargaining power among integrated hardware manufacturers and squeezing margin pools for mid-tier operators dependent on imported subsystems.
Pricing Analysis
FAA Part 107 certification tiers dictate the pricing structure across commercial drone operations. Three-tier pricing stratifies across certified BVLOS waivers, standard visual-line-of-sight operations, and experimental permits, with differentiation driven by insurance bonding requirements and pilot training depth. Pricing pressure stems from DJI's manufacturing scale compressing hardware margins, while subscription-based imagery licensing in Australia and the United Kingdom captures recurring revenue. Municipal governments show highest price sensitivity due to budget cycle constraints; energy operators absorb premium sensor costs for predictive maintenance ROI.
Supply Chain Analysis
Inventory strategy favors just-in-time component flows for multispectral sensors and compact LiDAR modules, with strategic stockpiling reserved for semiconductor-dependent flight controllers. Supply concentrates in China for airframe fabrication, the United States for geospatial analytics software, and Germany for precision optics. Raw material dependencies span rare-earth magnets for brushless motors, gallium arsenide for thermal sensors, and high-purity silicon for CMOS imagers. Single-source vulnerability runs through Taiwanese semiconductor foundries serving flight control systems. Distribution runs through equipment distributors losing margin to direct platform relationships in metropolitan capture markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from AI-powered feature extraction and subscription imagery licensing expands faster than hardware sales, repositioning competitive advantage toward analytics platforms with proprietary capture libraries.
For Market Incumbents: Consolidate proprietary image libraries through metropolitan capture program expansion to defend against satellite imagery substitution. Deepen backward integration into sensor calibration facilities to reduce payload cost exposure. Lock in insurance carrier channel control before new entrants replicate EagleView's underwriting integration model. For New Entrants and Emerging Players: Differentiate on hyperspectral analytics for viticulture and specialty crop segments where manual scouting labor costs create willingness-to-pay. Target India's DGFT-CEA coordination window for unmanned aerial system commercialization before regulatory maturity raises compliance barriers. Lead with AI-photogrammetry convergence as the go-to-market wedge against legacy GIS integration friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors subscription-based imagery aggregators with established metropolitan capture programs over hardware manufacturers facing margin compression. Long-term viability hinges on recurring revenue attachment rates and data network effects. Acquisition targets should demonstrate direct platform relationships displacing channel intermediaries. The signal to watch is FAA BVLOS rulemaking finalization accelerating automated inspection service deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Capture Library Expansion | Nearmap's metropolitan programs demonstrate recurring revenue defensibility against per-project competitors. |
| AI-Photogrammetry Platform Integration | Machine learning pipelines automate feature extraction, compressing subscription pricing for crop monitoring services. |
| BVLOS Certification Investment | FAA Part 107 waivers unlock automated inspection contracts with Texas and California utility operators. |
| Insurance Channel Partnership | Property carriers in Houston and Denver adopt aerial imagery for claims verification, anchoring enterprise demand. |
| Hyperspectral Sensor Development | Viticulture operations in California's Central Valley and France's Bordeaux region pay premium for disease early warning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA regulatory filings, EASA safety case databases, utility procurement records, and agricultural cooperative technology adoption surveys. Primary interviews engaged fleet operations managers at energy operators, precision agriculture directors at farming cooperatives, geospatial analytics product leads, and municipal planning department GIS administrators. Secondary validation drew from CAAC low-altitude economy policy circulars, EU AI Act risk classification guidance, and customs data on unmanned aerial system component trade flows. Bottom-up triangulation across operator deployment counts and top-down reconciliation against sensor shipment volumes anchor forecast integrity.
Segmentation dimensions modeled span platform type, image capture technology, application vertical, and end-user industry across the projection horizon. The analytical framework incorporates altitude waivers, sensor payload weight classes, and regulatory certification tiers as cross-cutting variables. CAGRs derive from deployment velocity curves calibrated against BVLOS rulemaking timelines and agricultural input cost cycles. Forecast inputs include utility capital expenditure patterns for predictive maintenance and satellite imagery resolution improvements eroding wide-area terrain mapping addressable market.
The analysis sits within stated boundaries; outcomes outside sustained FAA regulatory permissiveness, EASA specific category framework stability, or CAAC-MIIT policy coordination would require recalibration. Forecasts reflect assumptions on pilot certification pipeline throughput and municipal GIS integration willingness. Revision becomes warranted when satellite constellation revisit frequency crosses sub-daily thresholds or when hyperspectral sensor cost curves inflect downward.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Payload Market
UAV
Drone Inspection Service Market
UAV
Global Drone Services Market
UAV
FPV Drone Goggles Market
UAV
Global Inspection Drones Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Drone Leasing Market
UAV
Drone Camera Market
UAV
Home Security Drone Market
UAV
Tethered Drones Market
UAV
North America Drone Software Market
UAV
Passenger Drones Market
UAV
Global Drone Software Market
UAV
GCC Drones Market
UAV
Miniature Drone Market
UAV
Small UAV Market